
 United States Upholstered Furniture Market | 2026-2036
United States Upholstered Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United States Upholstered Furniture Market Analytics
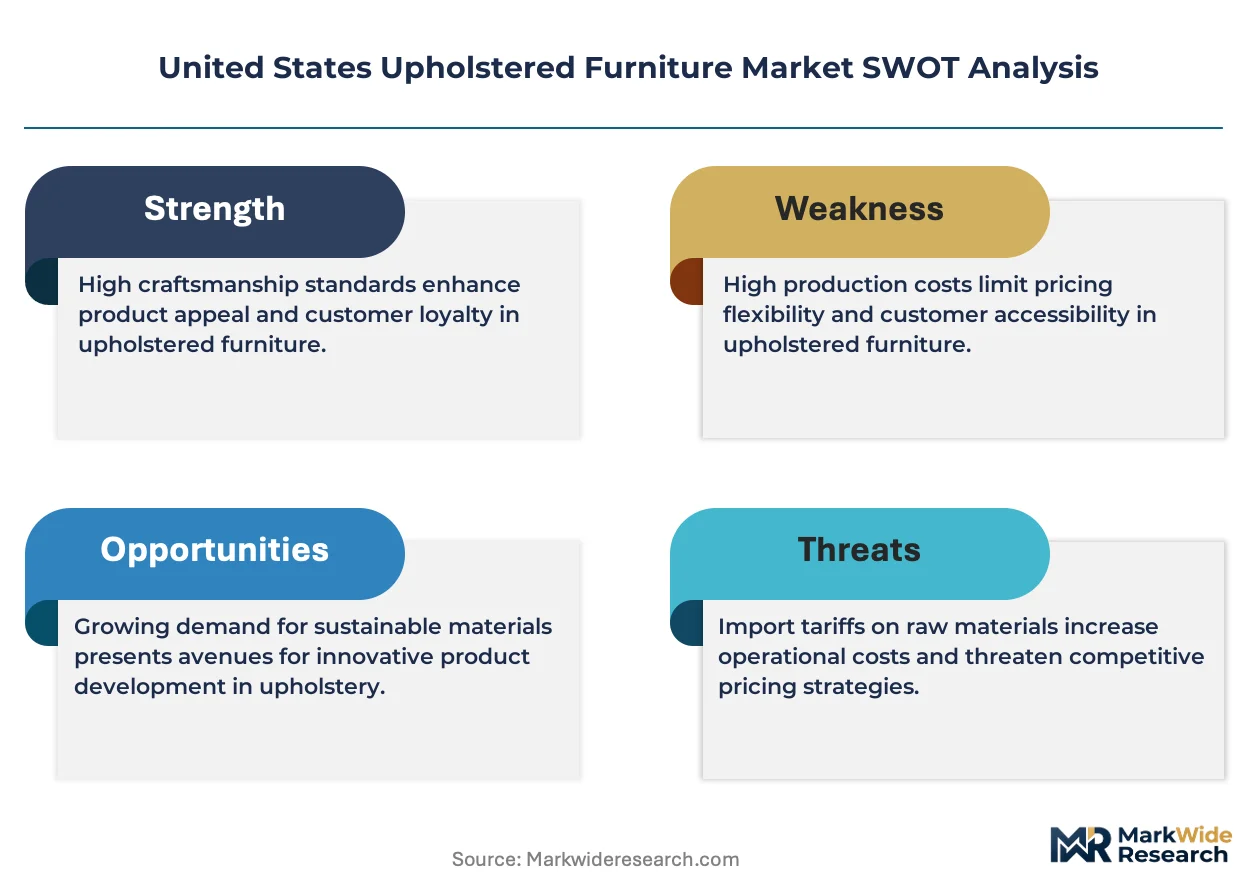
California TB 117-2013 is hardening compliance requirements for flame-retardant-free upholstered products across the United States. La-Z-Boy Incorporated navigates these standards through dedicated compliance laboratories and supply chain auditing. Ashley Furniture Industries controls raw material sourcing through extensive domestic manufacturing infrastructure. Flexsteel Industries differentiates with specialized motion upholstery engineering that meets evolving safety protocols.
United States upholstered furniture comprises padded seating and reclining products constructed with webbed or sprung suspension systems, foam cushioning, and textile or leather coverings, primarily serving residential living spaces, hospitality venues, and corporate interiors. Fabric upholstery leads volume shipments due to cost accessibility and pattern versatility, while leather commands concentrated margin pools in premium residential and commercial specification channels. The hospitality end user segment demonstrates accelerated replacement cycles as hotel renovation activity strengthens post-pandemic.
The Consumer Product Safety Commission enforces flammability standards while EPA oversight governs chemical emissions from foam and adhesive components, collectively elevating product testing costs and supplier qualification barriers. State-level extended producer responsibility proposals in California and New York signal additional compliance layers for furniture take-back and recycling. Stakeholders must monitor regulatory preemption battles between federal and state authorities while calibrating material substitution strategies.
Market Dynamics
The United States upholstered furniture market is experiencing structural compression as California's TB 117-2013 flammability standard cascades through national supply chains, forcing foam reformulation and textile chemistry changes that reshape manufacturing economics and supplier qualification protocols.
Growth Catalysts
- Performance Fabric Adoption:Residential buyers are expanding purchases of stain-resistant, durable upholstery textiles that withstand heavy use and simplify maintenance, particularly in households with children or pets.
- Hospitality Renovation Cycles:Hotel renovation activity has strengthened post-pandemic, accelerating replacement timelines for guest room seating and lobby furnishings across major metropolitan markets.
- Southeast Manufacturing Corridor:Demand concentrates in the production belt spanning North Carolina and Mississippi, where established supplier networks and skilled upholstery labor pools reduce logistics costs and lead times.
Market Restraints
- Polyurethane Foam Cost Volatility:Petrochemical feedstock price swings directly compress cushioning margins, forcing manufacturers to absorb costs or renegotiate annual contracts with hospitality specifiers.
- Extended Producer Responsibility Proposals:California and New York state legislatures are advancing furniture take-back mandates that would impose reverse logistics costs and recycling infrastructure investments on manufacturers.
- Regulatory Preemption Uncertainty:Conflicting federal and state authority over chemical emissions creates compliance duplication, as EPA oversight overlaps with state-level flammability enforcement.
Strategic Opportunities
- Extended-Stay Hospitality Segment:Underpenetrated serviced apartment and corporate housing channels offer volume potential as remote work policies lengthen average guest stays and increase seating wear rates.
- Modular Upholstery Systems:Component-based sofas with replaceable covers and cushions align with circular economy principles while reducing total cost of ownership for commercial buyers.
- Infrastructure Investment:Federal broadband and transportation spending is revitalizing rural commercial districts, creating demand for restaurant and hotel furnishings in secondary markets previously bypassed by national chains.
Industry Challenges
- Certification Timeline Compression:TB 117-2013 compliance testing now requires 12-16 weeks for new foam formulations, delaying product launches and locking working capital in unapproved inventory.
- Technical Talent Scarcity:Motion upholstery engineering expertise concentrates at a handful of specialized facilities, constrating Flexsteel Industries and similar competitors from scaling specialized recliner production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Upholstered Furniture Market |
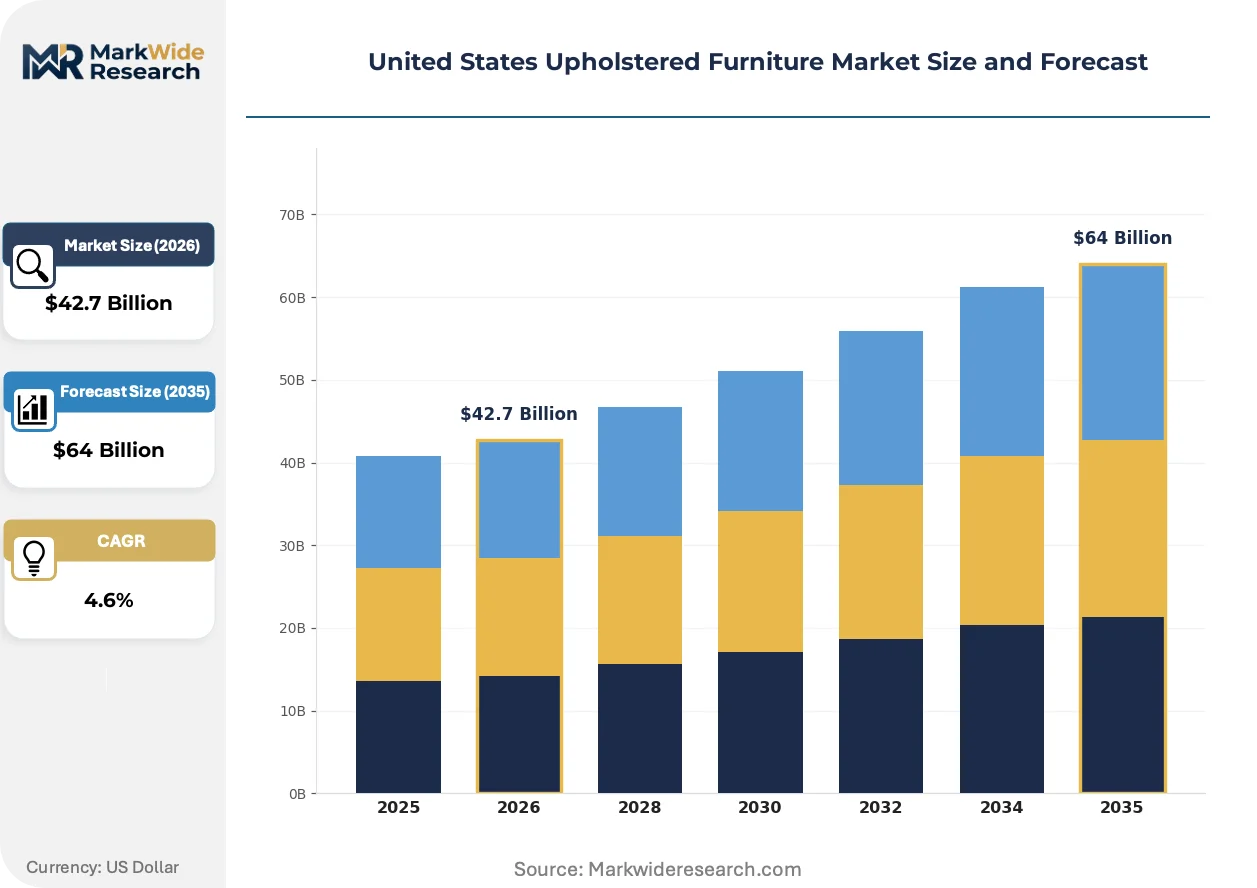
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $64 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Ottomans, Loveseats Material: Leather, Fabric, Microfiber, Velvet Style: Modern, Traditional, Contemporary, Rustic End User: Residential, Commercial, Hospitality, Office |
| Companies Covered | Flexsteel Industries, American Leather, Ashley Furniture Industries, Stickley, Hickory White, La-Z-Boy Incorporated, Hooker Furnishings Corporation, Rowe Furniture, Bassett Furniture Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Upholstered Furniture Market Evolving Landscape
Active innovation across the United States upholstered furniture sector centers on material science breakthroughs, regulatory compliance automation, and direct-to-commercial procurement platforms that compress specification cycles and disintermediate traditional dealer networks.
Smart suspension systems integrating sensor-enabled pressure mapping are electrifying how manufacturers design ergonomic seating for extended-use environments. Corporate furniture specifiers are piloting these technologies in call centers and healthcare waiting areas where occupant comfort directly impacts productivity metrics. The technology is electrifying competitive positioning by enabling outcome-based durability warranties that shift risk from buyers to manufacturers.
The Consumer Product Safety Commission's enforcement posture on composite foam smolder resistance has hardened following updated guidance documents issued in 2023. Manufacturers now face mandatory third-party testing for all imported cushioning components, elevating supplier qualification barriers and disqualifying several Southeast Asian foam sources. Residential brands with captive domestic foam production have absorbed certification costs faster than import-dependent competitors, compressing the viable supplier base.
Commercial buyers are consolidating specification authority through centralized procurement platforms that aggregate furniture purchases across multi-property hospitality portfolios. Marriott and Hilton procurement teams now mandate digital product configurators that eliminate physical sample cycles, forcing manufacturers to invest in 3D visualization infrastructure. This concentration is most visible in the Sun Belt hotel construction corridor, where standardized room packages dominate new build specifications.
United States Upholstered Furniture Market Segmentation
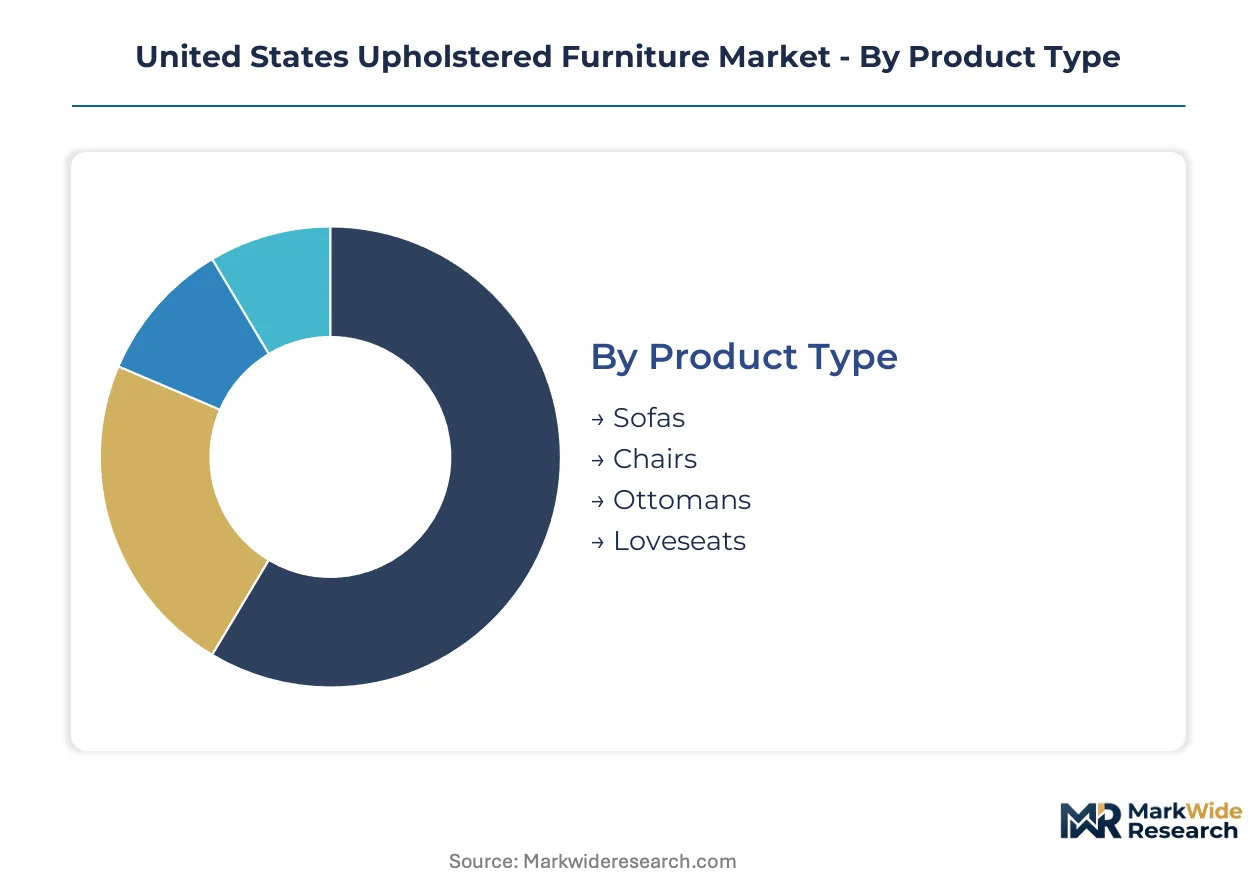
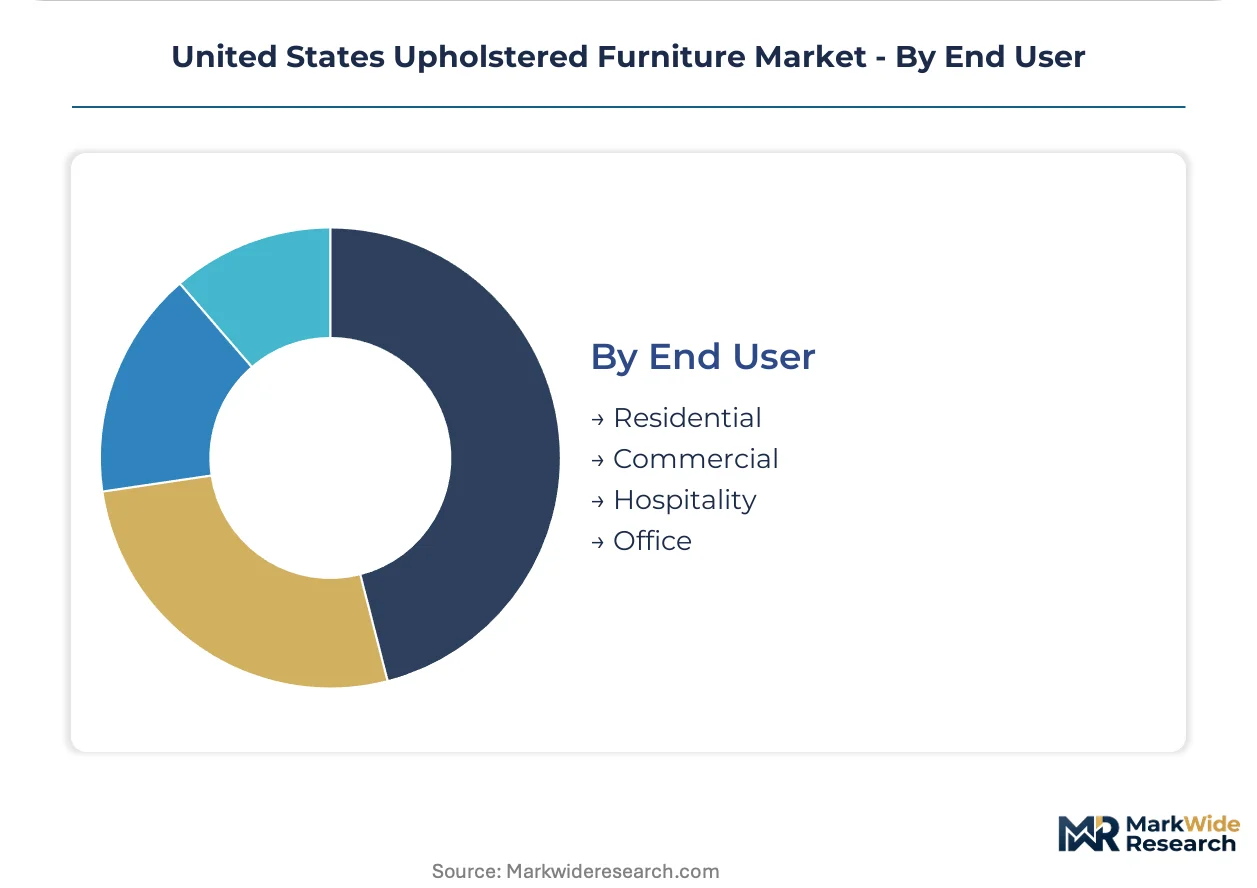
Segmentation reveals how replacement cycles and material specifications diverge across buyer types in the United States upholstered furniture market. California TB 117-2013 compliance costs hit segments differently, with foam-dependent categories facing steeper reformulation investments than textile-light alternatives.
Product Type:
Upgrade cycles vary dramatically by seating capacity and primary use environment, with multi-seat products demanding earlier replacement due to structural stress concentration.
- Sofas:Three-cushion and sectional configurations dominate residential living rooms with webbed suspension systems and high-density polyurethane cores. Demand concentrates in Southeast manufacturing corridors where North Carolina and Mississippi facilities reduce freight costs to Atlanta and Dallas distribution hubs, though TB 117-2013 foam certification delays now stretch lead times.
- Chairs:Accent and recliner units serve concentrated wear environments—home offices, hotel lobbies, senior living common areas—with motion mechanisms adding engineering complexity. Upholstery labor scarcity at specialized facilities constrains scaling of powered recliner production.
- Ottomans:Footrest and storage variants attach to sofa collections or standalone placement, requiring less foam volume per unit and escaping the harshest certification cost impacts.
- Loveseats:Two-seat configurations fill apartment-scale living spaces and boutique hotel guest rooms, with compact dimensions suiting urban density constraints.
Sofas sit at the top of the volume ranking, with chairs climbing the fastest.
Material:
Cost tiers separate segments by raw material sourcing geography and chemical compliance burden, with petroleum-derived inputs exposing margins to feedstock volatility.
- Leather:Full-grain and corrected hides command specification in premium residential and corporate reception settings, with Italian and Brazilian tanneries supplying domestic cut-and-sew operations. Hospitality buyers in the Sun Belt hotel corridor specify leather for lobby durability despite higher per-seat acquisition costs.
- Fabric:Woven synthetics and natural fibers lead unit shipments through cost accessibility and pattern versatility, with performance-treated polyester gaining share in pet-owning households. North Carolina textile mills supply rapid-turn custom runs for regional furniture manufacturers.
- Microfiber:Ultra-fine synthetic suede offers stain resistance at mid-tier price points, suiting extended-stay hospitality and multi-family residential common areas.
- Velvet:Pile-weave luxury textile targets design-forward residential and boutique hospitality segments, with fiber content variations spanning cotton, silk, and synthetic blends.
Fabric holds the volume lead, while performance-grade leather gains share fastest in commercial specification channels.
Style:
Customer type and application maturity shape style preferences, with generational turnover driving aesthetic displacement in residential replacement cycles.
- Modern:Clean lines and exposed leg structures dominate urban condominium markets and tech-sector corporate interiors, with lower profiles reducing foam volume requirements per unit.
- Traditional:Rolled arms, skirted bases, and decorative wood trim persist in suburban residential markets and heritage hospitality properties, though longer replacement cycles dampen volume relative to trend-responsive alternatives.
- Contemporary:Transitional aesthetics bridging modern and traditional elements capture the largest residential addressable market, with modular configurations suiting renovation-driven replacement timing.
- Rustic:Distressed leather and reclaimed wood accents target vacation rental and lodge hospitality segments, with durability specifications matching high-turnover commercial use.
Contemporary styling commands the highest shipment volumes, with modern designs expanding most quickly in metropolitan residential markets.
End User:
Margin structure and procurement concentration diverge sharply across buyer categories, with commercial accounts consolidating specification authority through centralized platforms.
- Residential:Individual households drive replacement through life events—relocation, household formation, renovation—with e-commerce configurators compressing decision timelines. Performance fabric adoption accelerates in pet-owning and child-present households.
- Commercial:Corporate buyers specify seating for reception, conference, and private office environments, with ergonomic warranties increasingly tied to sensor-enabled usage data.
- Hospitality:Hotel renovation cycles have strengthened post-pandemic, with Marriott and Hilton procurement teams mandating digital configurators that eliminate physical sample shipments. Extended-stay segments show underpenetrated potential as remote work lengthens average guest stays.
- Office:Workplace transformation projects concentrate demand in call centers and healthcare waiting areas where occupant comfort ties directly to productivity metrics.
Residential end users generate the highest absolute volume, with hospitality procurement climbing fastest on renovation cycle acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled upholstery labor pools in North Carolina and Mississippi anchor domestic production capacity, with craft apprenticeships and technical training programs sustaining the Southeast manufacturing corridor's competitive position against import alternatives.
Southeast Manufacturing Belt
North Carolina and Mississippi facilities process the majority of domestic foam cushioning and fabric cutting operations. EPA oversight of chemical emissions from adhesive components shapes plant permitting requirements. High Point, North Carolina hosts concentrated showroom and specification activity, with regional manufacturers reducing freight costs to Atlanta and Dallas distribution hubs.
Southwest Production Zone
Texas and Oklahoma operations serve Sun Belt hospitality construction with rapid-turn custom upholstery runs. OSHA workplace safety standards govern cutting floor ventilation and chemical handling protocols. Dallas-Fort Worth distribution clusters expedite delivery timelines to Phoenix and Los Angeles metropolitan markets.
Midwest Industrial Corridor
Michigan and Ohio retain legacy motion mechanism engineering expertise for powered recliner systems. Consumer Product Safety Commission flammability testing requirements extend lead times for new product introductions. Grand Rapids, Michigan maintains specialized technical talent pools for ergonomic seating development.
West Coast Specification Hub
California buyers drive performance fabric adoption through TB 117-2013 compliance mandates that cascade through national supply chains. State-level extended producer responsibility proposals signal additional take-back infrastructure investments. Los Angeles and San Francisco metropolitan areas concentrate boutique hospitality renovation demand.
Northeast Design Centers
New York and Boston corridors channel corporate and luxury residential specification authority through architect and interior designer networks. State legislatures advance furniture recycling mandates parallel to California frameworks. Manhattan showrooms function as gatekeepers for premium leather and custom textile sourcing decisions.
United States Upholstered Furniture Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a structurally tiered vendor base. Domestic manufacturers with captive foam production absorb certification costs faster than import-dependent competitors, compressing the viable supplier base. Three archetypes dominate: integrated manufacturers controlling raw material sourcing, specialized motion upholstery engineers, and regional craft producers serving custom specification channels. Competitive moves center on compliance laboratory investments and supply chain auditing capabilities.
Within the integrated manufacturing tier, Ashley Furniture Industries and La-Z-Boy Incorporated exemplify scale-driven operators with extensive domestic infrastructure. Flexsteel Industries occupies a specialized position in motion upholstery engineering. These three anchors represent contrasting strategic postures: captive supply control, dedicated compliance capabilities, and technical differentiation through powered seating mechanisms.
| Leading Market Players |
|---|
| Flexsteel Industries |
| American Leather |
| Ashley Furniture Industries |
| Stickley |
| Hickory White |
| La-Z-Boy Incorporated |
| Hooker Furnishings Corporation |
| Rowe Furniture |
| Bassett Furniture Industries |
| Others |
Value Network & Pricing Analysis
Hospitality procurement teams at Marriott and Hilton concentrate specification authority through centralized digital platforms, enforcing three-tier pricing structure across premium, standard, and economy levels that compresses margin pools for manufacturers lacking scale or compliance certification speed.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Italian leather specification from domestic fabric upholstery from import-dependent microfiber alternatives. Price differentiation hinges on TB 117-2013 certification tier and captive foam production versus import-dependent sourcing. Pricing pressure stems from polyurethane foam feedstock volatility forcing contract renegotiations with hospitality specifiers. Economy-tier import-dependent manufacturers face acute price sensitivity, while premium leather specification channels demonstrate inelastic demand from boutique hospitality renovators.
Supply Chain Analysis
Skilled upholstery labor scarcity in North Carolina and Mississippi constrains production scaling despite established supplier networks and craft apprenticeship pipelines. Domestic manufacturing draws from Southeast Asian textile mills, Brazilian and Italian tanneries, and regional petrochemical feedstocks for polyurethane foam. Single-source vulnerability concentrates in motion mechanism engineering expertise at Michigan and Ohio facilities. Distribution runs through Atlanta and Dallas hubs serving Sun Belt hospitality construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States upholstered furniture market represents a late-cycle quality story as residential buyers pivot toward performance fabric specifications that command durability premiums and simplify maintenance in pet-owning households.
For Market Incumbents: Cement compliance laboratory investments and supply chain auditing capabilities to absorb TB 117-2013 certification costs faster than import-dependent competitors. Lock in extended-stay hospitality procurement contracts before digital platform consolidation hardens switching barriers. Threat: EPA oversight of chemical emissions elevates testing costs and disqualifies uncertified foam sources. For New Entrants and Emerging Players: Extended-stay hospitality operators in secondary Sun Belt markets offer the most penetrable white-space target as remote work policies lengthen guest stays and accelerate seating wear rates. Target corporate housing channels with modular upholstery systems featuring replaceable covers. Go-to-market angle: circular economy total-cost-of-ownership positioning against traditional full-replacement cycles. For Investors and Strategic Acquirers: Private equity firms with manufacturing rollup experience are the most active acquirer in this space, targeting regional craft producers with captive Southeast corridor production capacity. Five-to-ten-year viability hinges on regulatory preemption clarity and extended producer responsibility implementation timing. Signal to watch: California and New York furniture take-back mandate passage as inflection indicator for reverse logistics infrastructure requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Laboratory Investment | TB 117-2013 certification speed separates viable suppliers from disqualified import-dependent competitors. |
| Backward Integration into Foam Production | Ashley Furniture Industries and La-Z-Boy absorb certification costs faster through captive domestic manufacturing. |
| Digital Configurator Deployment | Marriott and Hilton procurement mandates eliminate physical sample cycles and compress specification timelines. |
| Modular Upholstery System Development | Component-based designs align with circular economy principles and reduce total cost of ownership. |
| Southeast Manufacturing Corridor Expansion | North Carolina and Mississippi facilities reduce freight costs to Atlanta and Dallas distribution hubs. |
Research Methodology
Direct dialogue with upholstery plant managers, hospitality procurement directors, foam formulation chemists, and furniture dealer network heads grounded qualitative insights in operational reality. Secondary validation drew from CPSC enforcement guidance documents, EPA chemical emissions oversight records, California TB 117-2013 compliance databases, and customs trade data on textile and leather imports. Bottom-up facility capacity assessments triangulated against top-down end-use demand modeling across residential, hospitality, and commercial segments.
Segment-level value and volume trajectories across the analysis window reflect product-type, material-grade, style-category, and end-user stratification with regional production cluster overlays. CAGRs were derived from replacement cycle analysis, renovation pipeline tracking, and hospitality construction permit flows. Forecast inputs incorporated polyurethane foam feedstock price elasticity, TB 117-2013 certification timeline compression, and skilled labor availability indices for North Carolina and Mississippi corridors.
Inputs from CPSC enforcement records and state legislative tracking databases were available through the study window; gaps in real-time hospitality procurement contract terms introduce uncertainty bands around commercial segment projections. Forecasts reflect documented assumptions regarding regulatory preemption outcomes and extended producer responsibility implementation sequencing. Practitioners should monitor California and New York furniture take-back mandate progression and EPA chemical emissions guidance updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Piano Stools Market
Furniture
Armchairs with Footrest Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Wooden Furniture Market
Furniture
North America Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Entryway Furniture Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
US Sustainable Furniture Market
Furniture
Bar Stools Market
Furniture
Salon Chairs Market
Furniture
GCC Luxury Furniture Market
Furniture
Netherlands Home Furniture Market
Furniture
Europe Smart Furniture Market
Furniture
Canada Secondary Wood Products Market