
 Fireplace Mantels Market | 2026-2036
Fireplace Mantels Market Size, Share, and Industry Trends Forecast 2026-2036
Fireplace Mantels Market Analysis
Capital-intensity divergence between automated CNC carving operations and hand-finish craft workshops is redrawing competitive boundaries in fireplace mantel manufacturing. Heat & Glo leverages integrated metal fabrication to control hearth-to-mantel system compatibility. Chesneys anchors its position through proprietary stone sourcing relationships that sustain premium positioning. Pearl Mantels Corporation competes on rapid-turn custom dimensions via lean manufacturing cells.
Fireplace mantels are load-bearing or decorative surrounds installed above firebox openings, typically fabricated from wood, stone, marble, or synthetic composites with fire-resistant backing materials and depth specifications calibrated to local building codes. Their primary commercial purpose spans aesthetic room anchoring, heat deflection, and display surface provision in residential and commercial interiors. Wood mantels retain the largest installed base across traditional and rustic style categories, though marble and engineered stone segments command premium margin pools in modern and contemporary installations. Wall-mounted configurations dominate volume due to retrofit accessibility, while built-in systems capture higher per-unit value through architectural integration requirements.
EPA emissions standards constrain wood-burning hearth designs and indirectly shape mantel depth and clearance specifications to accommodate catalytic combustion systems. OSHA workplace safety rules and regional building codes govern installation contractor licensing and structural anchoring requirements. The EU Green Deal's embodied carbon tracking provisions are beginning to influence stone sourcing disclosures for European-bound exports. Stakeholders must monitor evolving combustion efficiency mandates and material transparency requirements to align product development with compliance trajectories.
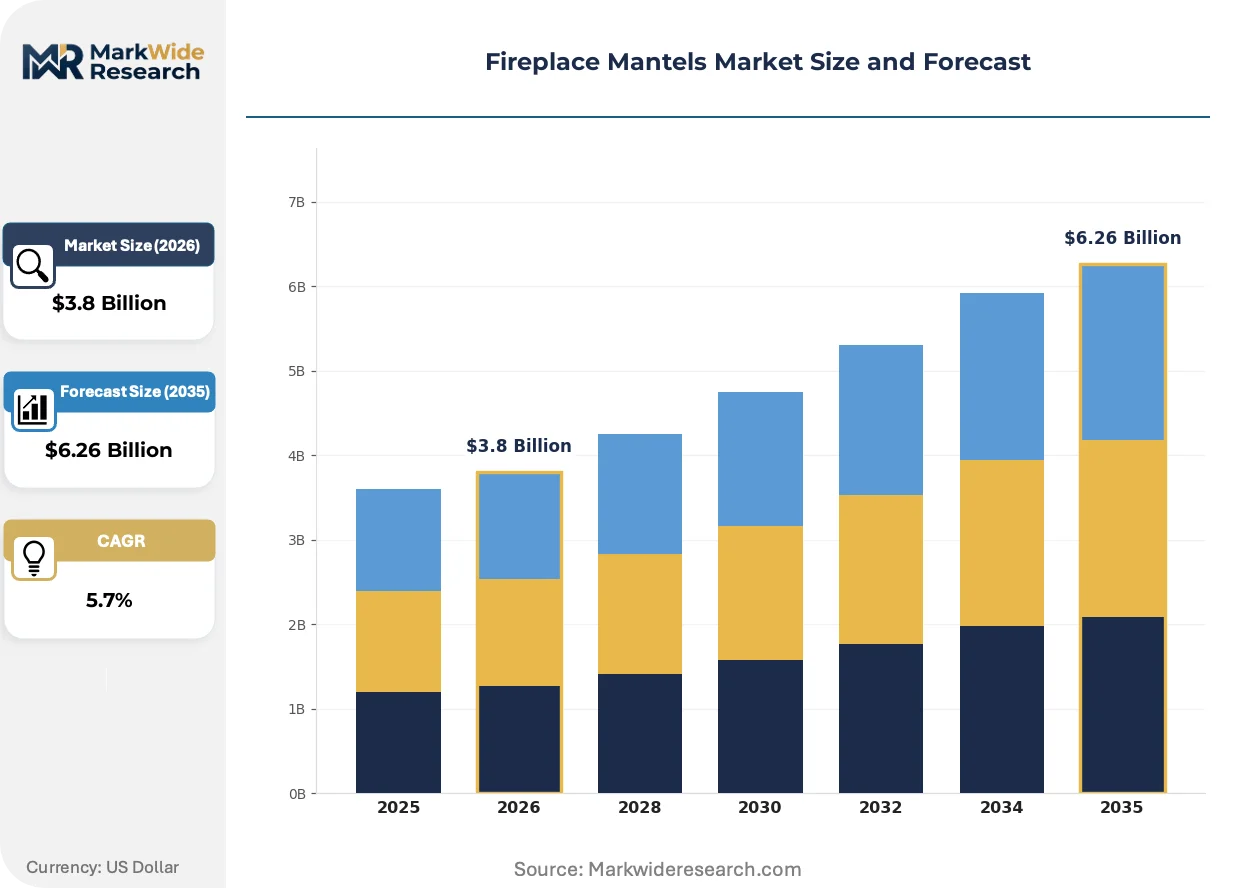
Market Dynamics
Residential renovation spending is concentrating demand around aesthetic upgrades that reposition fireplace mantels as room-anchoring focal points, while EPA emissions standards for wood-burning appliances simultaneously reshape material specifications and clearance requirements across the supply base.
Growth Catalysts
- Sun Belt Construction Surge:New residential development across Florida, Texas, and Arizona integrates fireplace features at elevated rates, creating sustained pull for mantel systems in single-family and multi-family housing.
- EPA 2020 Certified Wood Heater Standards:These emissions regulations accelerate replacement cycles for non-compliant hearth systems, generating retrofit demand for mantels configured to catalytic combustion clearances.
- Engineered Stone Adoption:Fabricators are pivoting production lines toward quartz-composite materials that offer marble aesthetics at reduced weight and installation labor.
Market Restraints
- Natural Stone Supply Concentration:Premium marble and limestone sourcing clusters in Carrara, Italy and select quarries in Portugal, exposing finished goods pricing to extraction quota volatility and shipping lane disruptions.
- Solid Wood Input Cost Pressure:Oak and walnut lumber prices fluctuate with North American sawmill capacity constraints and tariff exposure on Canadian softwood imports.
- Building Code Fragmentation:Municipality-level hearth clearance and combustible material restrictions create SKU proliferation burdens for national distribution networks.
Strategic Opportunities
- EU Green Deal Embodied Carbon Tracking:Stone exporters to European markets can capture premium positioning through certified low-carbon quarrying disclosures and supply chain transparency documentation.
- Direct-to-Contractor Digital Platforms:E-commerce channels bypass traditional distributor markups for renovation contractors seeking rapid-turn custom dimension orders.
- Heat Pump Hearth Convergence:Electric and hybrid heating system manufacturers require mantel designs adapted to zero-clearance firebox architectures without traditional chimney infrastructure.
Industry Challenges
- CNC Programming Talent Scarcity:Automated carving operations require operators skilled in CAD-to-CAM translation for complex custom profiles, creating recruitment bottlenecks in traditional woodworking regions.
- UL 127 Certification Timelines:Factory-built fireplace and mantel system testing protocols extend product launch cycles by six to nine months for novel material combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fireplace Mantels Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Stone, Marble, Synthetic Style: Traditional, Modern, Rustic, Contemporary Installation Type: Wall-Mounted, Freestanding, Corner, Built-in End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Heat & Glo, Chesneys, Piazzetta, Acrila, Prestige, Kratki, Quadra-Fire, Pearl Mantels Corporation, Dimplex Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fireplace Mantels Market Emerging Trajectories
Material science advances and regulatory pressure on combustion efficiency are compressing traditional manufacturing methods while opening pathways for lighter, code-adaptable mantel systems. These shifts favor producers with integrated design-to-installation capabilities.
Ultralight glass-fiber reinforced concrete (GFRC) is supplanting quarried stone in contemporary and transitional design segments. Custom home builders in California and Colorado specify GFRC mantels for seismic zone installations where structural load limits constrain natural stone options. This substitution is compressing per-unit freight costs and enabling single-person installation crews that natural stone fabrication cannot match.
REACH regulation SVHC disclosure requirements are compelling European-bound exporters to document flame-retardant chemical content in composite backing materials. Manufacturers serving German and French markets now embed material passport data directly into product QR codes for contractor compliance verification. Stone veneer suppliers with incomplete chemical inventories face delayed customs clearance and project specification exclusion.
Homeowners increasingly initiate mantel selection through interior design software integrations rather than showroom visits. Platforms like Houzz and proprietary builder configurators now render mantel options in photorealistic room visualizations, compressing the traditional three-visit purchase cycle. This channel shift is most pronounced in Texas and Florida metropolitan markets where new construction volume supports digital-first procurement workflows.
Fireplace Mantels Market Segmentation
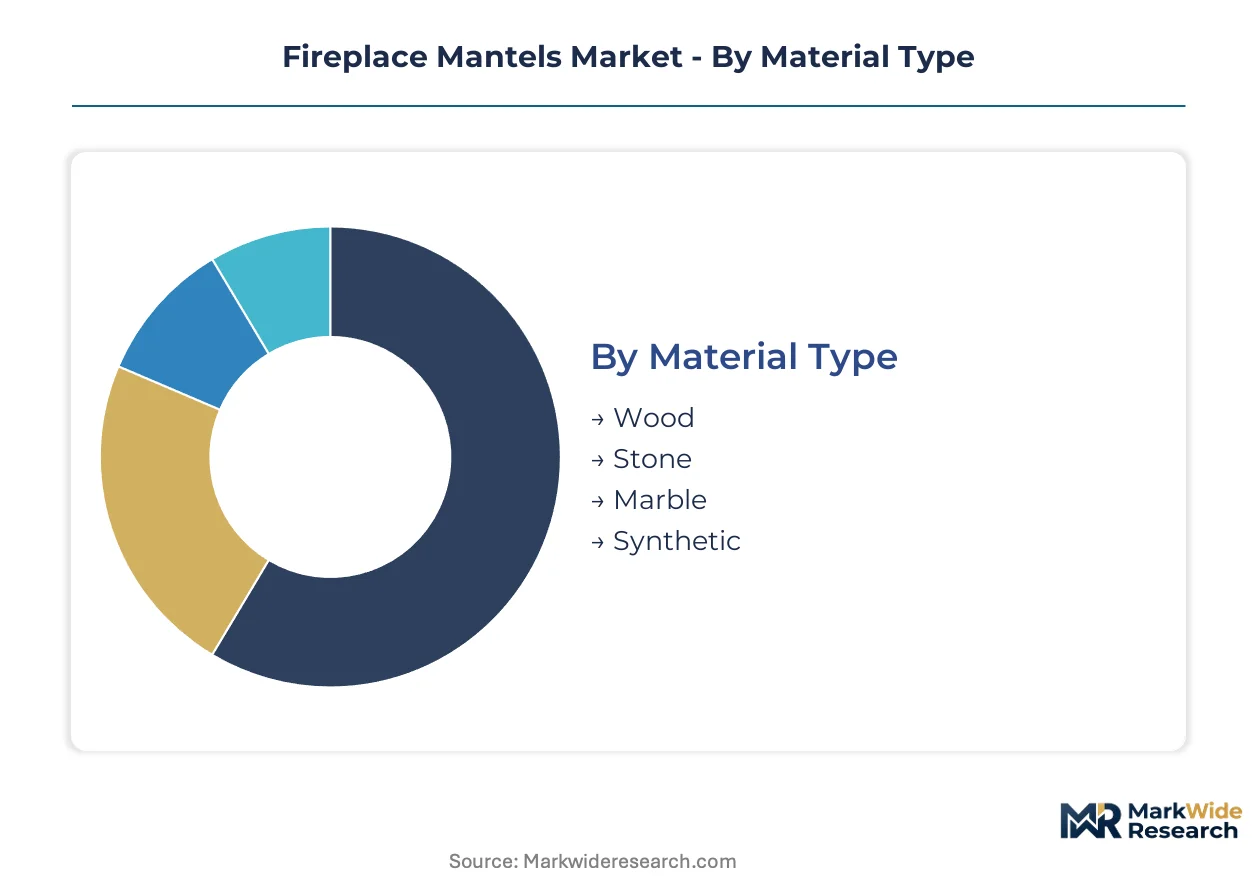
Material composition determines thermal performance, structural anchoring requirements, and compliance pathways for fireplace mantel specifications. Style and installation configurations segment procurement channels between new construction contractors and renovation specialists. End-use concentration shapes volume-to-margin tradeoffs across project types.
Material Type:
Domestic production dominates wood and synthetic categories, while stone and marble sourcing concentrates in Mediterranean quarries with established export infrastructure to North American distributors.
- Wood:Oak, walnut, and pine varieties constitute the installed base across traditional residential applications. EPA emissions standards for wood-burning hearths constrain clearance specifications, favoring mantel depths that accommodate catalytic combustion systems in Sun Belt renovation markets.
- Stone:Limestone and sandstone fabrication relies on regional quarry networks in Texas and Indiana for domestic supply, with Italian Carrara imports serving premium coastal markets. Seismic zone building codes in California and Colorado accelerate specification shifts toward lighter engineered alternatives.
- Marble:Veined calcite varieties command specification in luxury hospitality and high-end residential segments.
- Synthetic:Glass-fiber reinforced concrete and resin composites enable single-person installation crews and freight cost compression.
Wood holds the largest share; momentum sits with synthetic materials gaining specification in multi-family housing.
Style:
Cost tier stratification separates artisan hand-finish premiums from CNC-milled production efficiency, with distinct margin pools across architectural style categories.
- Traditional:Ornate crown molding and corbel-supported designs reference colonial and Victorian architectural vocabularies. Historic district renovation projects in Charleston and Savannah sustain demand for period-accurate reproductions with hand-carved detailing.
- Modern:Clean lines and floating shelf configurations align with open-concept interiors. Specifiers in Austin and Denver metropolitan markets prioritize minimal visual mass and concealed hardware systems for contemporary residential construction.
- Rustic:Reclaimed barn wood and live-edge profiles serve mountain resort and vacation home segments.
- Contemporary:Asymmetrical forms and mixed-material compositions bridge transitional design preferences.
Traditional styling retains volume leadership; contemporary applications are climbing the fastest among design-forward urban markets.
Installation Type:
Application context dictates structural integration depth, with retrofit accessibility driving volume concentration and architectural embedding capturing premium value.
- Wall-Mounted:Floating shelf and bracket-anchored systems enable same-day installation without masonry modification. Florida and Arizona renovation contractors specify these configurations for rapid project turnaround in aging residential stock.
- Built-in:Full-surround integration with firebox enclosures requires coordination with hearth system manufacturers. Custom home builders in Texas Hill Country and Colorado Front Range prioritize these specifications for architectural cohesion.
- Freestanding:Self-supporting pilaster designs accommodate non-standard wall constructions.
- Corner:Diagonal firebox orientations maximize spatial efficiency in compact residential footprints.
Wall-mounted configurations dominate unit volume; built-in systems command the steepest expansion trajectory in new construction.
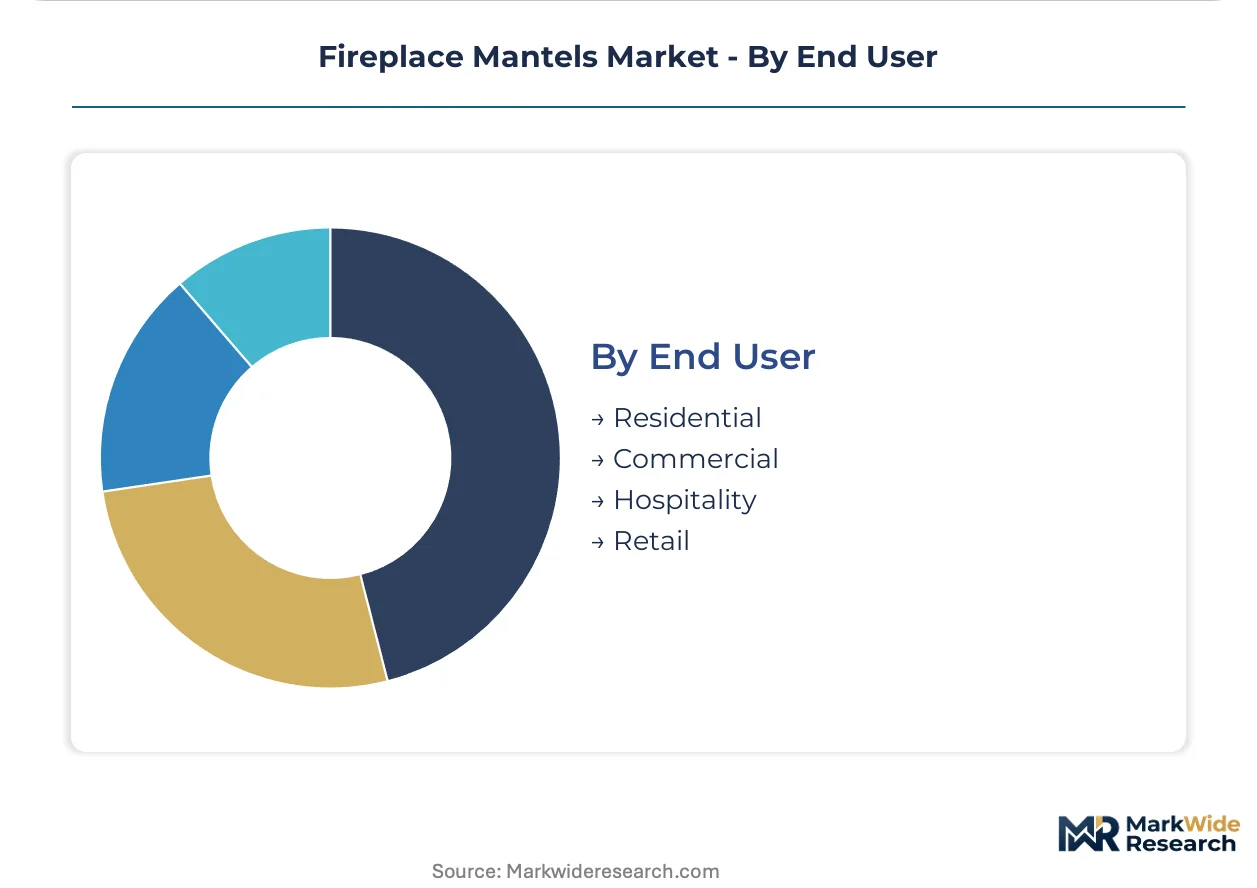
End User:
Customer type segments procurement behavior between price-sensitive volume contracting and specification-driven aesthetic commissioning.
- Residential:Single-family homeowners drive seasonal renovation cycles, with mantel replacement correlating to broader kitchen and living room upgrade projects. Sun Belt states exhibit elevated per-capita fireplace feature integration in new construction.
- Hospitality:Boutique hotel and resort developers specify statement mantels for lobby anchoring and guest experience differentiation. Aspen and Napa Valley hospitality projects sustain premium material sourcing relationships.
- Commercial:Office and mixed-use developments incorporate electric hearth simulations with mantel surrounds for amenity space activation.
- Retail:Restaurant and hospitality-facing retail environments use fireplace features for dwell time extension.
Residential end-use holds the largest share; hospitality applications are gaining share fastest among experience-economy investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Sun Belt homeowners in the United States treat fireplace mantels as standard new-construction features with limited price sensitivity, while European renovation buyers scrutinize embodied carbon disclosures and freight-cost premiums.
United States
Florida, Texas, and Arizona construction markets integrate fireplace features at elevated rates in single-family and multi-family housing. EPA 2020 Certified Wood Heater Standards accelerate replacement cycles for non-compliant hearth systems, generating retrofit demand. Dallas-Fort Worth and Houston metropolitan clusters concentrate fabrication capacity for engineered stone and synthetic composite mantels serving regional distribution networks.
Germany
Renovation contractors prioritize low-carbon material sourcing for residential upgrades in Berlin and Munich metropolitan zones. EU Green Deal embodied carbon tracking provisions compel stone exporters to document quarry-level emissions data. The North Rhine-Westphalia industrial corridor hosts precision fabrication operations supplying certified mantel systems to German and Benelux markets.
Italy
Carrara marble quarries anchor premium material sourcing for luxury hospitality and high-end residential segments worldwide. REACH regulation SVHC disclosure requirements mandate flame-retardant chemical documentation in composite backing materials. Tuscany-based fabricators maintain established export infrastructure to North American distributors despite extraction quota volatility.
United Kingdom
Historic district renovation projects in London and Edinburgh sustain demand for period-accurate reproductions with traditional detailing. Building regulations governing hearth clearance and combustible material restrictions vary by municipality, creating specification complexity. The Southeast England manufacturing cluster specializes in custom dimension production for rapid-turn contractor orders.
Canada
Tariff exposure on softwood lumber imports from the United States elevates input cost pressure for oak and walnut mantel producers. Provincial building codes in British Columbia and Alberta govern installation contractor licensing and structural anchoring requirements. Ontario-based fabricators leverage proximity to U.S. Great Lakes markets for cross-border distribution efficiency.
Fireplace Mantels Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in fireplace mantel manufacturing. Heat & Glo leverages integrated metal fabrication to control hearth-to-mantel system compatibility, while Chesneys anchors premium positioning through proprietary stone sourcing relationships. Pearl Mantels Corporation competes on rapid-turn custom dimensions via lean manufacturing cells. Strategic moves concentrate on backward integration into raw material supply and direct-to-contractor digital platform development.
Within the integrated-system tier, Heat & Glo and Dimplex Plc represent manufacturers controlling hearth-to-mantel compatibility through captive metal fabrication and electric heating technology integration. Chesneys occupies a position exemplifying premium stone specialists with quarry-direct sourcing relationships. Pearl Mantels Corporation sits within the lean-manufacturing archetype, serving renovation contractors with rapid-turn custom dimension capabilities. These three company types illustrate the competitive divergence between capital-intensive automated operations and craft-finish workshops.
| Leading Market Players |
|---|
| Heat & Glo |
| Chesneys |
| Piazzetta |
| Acrila |
| Prestige |
| Kratki |
| Quadra-Fire |
| Pearl Mantels Corporation |
| Dimplex Plc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Carrara quarry operators and North American distributors lock in both premium marble supply access and eighteen-month price visibility for luxury hospitality projects. These contracts insulate finished goods pricing from extraction quota volatility while exposing buyers to freight cost fluctuations on Mediterranean-to-East Coast shipping lanes.
Pricing Analysis
After-sales installation service and warranty extensions drive lifetime value for mantel manufacturers, with project-based pricing dominating commercial hospitality specifications. Three-tier pricing structure across premium, standard, and economy levels separates hand-carved Carrara marble from CNC-milled domestic stone and GFRC composites. Cost compression in the synthetic tier is intensifying because engineered stone fabricators are achieving single-person installation economics that natural stone cannot match. Renovation contractors in Florida and Arizona exhibit the highest price sensitivity due to rapid-turn project budgets, while boutique hotel developers in Aspen and Napa Valley show minimal sensitivity to material premiums.
Supply Chain Analysis
Port congestion on Mediterranean-to-Atlantic trade lanes and container availability constraints at Genoa and Livorno elevate inbound logistics costs for Italian stone imports. Raw material supply concentrates in Italy for premium marble, Texas and Indiana for domestic limestone, and China for GFRC resin components. Fabrication draws from oak and walnut lumber sourced through North American sawmill networks, with tariff exposure on Canadian softwood imports creating input cost volatility. Single-source vulnerability sits with Carrara quarry concentration for luxury tier materials. Distribution runs through regional distributor networks serving renovation contractors, with direct-to-contractor digital platforms emerging as an alternative channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of CNC programming talent capable of CAD-to-CAM translation for complex custom profiles is constraining automated production scaling. This capability gap favors incumbents with established training pipelines and recruitment relationships in traditional woodworking regions.
For Market Incumbents: Secure proprietary stone sourcing relationships in Carrara and Portuguese quarries to defend premium positioning against engineered stone substitution. Invest in captive CNC operator training programs at fabrication facilities in Texas and Colorado to overcome recruitment bottlenecks that constrain automated output scaling. For New Entrants and Emerging Players: Differentiate on rapid-turn custom dimension capabilities via lean manufacturing cells targeting renovation contractors in Sun Belt metropolitan markets. Target the wall-mounted retrofit segment in Florida and Arizona where installation accessibility creates procurement speed advantages over built-in system specialists. For Investors and Strategic Acquirers: Lean-manufacturing specialists with established direct-to-contractor digital platforms represent the most attractive acquisition archetype for exposure to renovation-driven demand cycles. Monitor UL 127 certification timeline compression as an inflection signal indicating regulatory adaptation capability among target fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Operations | Carrara quarry control secures premium material access against extraction quota restrictions. |
| Direct-to-Contractor Digital Platform Launch | Bypasses traditional distributor markups for rapid-turn custom dimension orders in Texas and Florida. |
| GFRC Production Line Expansion | Enables single-person installation crews that reduce project labor costs in seismic zones. |
| CNC Operator Training Academy Development | Addresses talent scarcity constraining automated carving operations in traditional woodworking regions. |
| EU Green Deal Compliance Certification | Embodied carbon documentation captures premium positioning in German and French renovation markets. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with fireplace mantel fabricators, hearth system manufacturers, and renovation contractors across Sun Belt states, combined with secondary validation through EPA emissions filings, UL certification databases, and regional building code repositories. Primary fieldwork captured installation specification practices and procurement channel preferences. Secondary sources included customs records tracking Mediterranean stone imports, SEC filings from publicly traded building products companies, and trade association production surveys. Bottom-up volume estimates triangulated against top-down construction spending allocations.
Across the analysis window, the forecasting framework modeled demand by material type, installation configuration, and end-use segment, with geographic granularity at state and metropolitan cluster levels. CAGRs were derived from regression analysis against residential renovation spending indices and new construction permit data. Industry-specific inputs incorporated EPA 2020 Certified Wood Heater Standards compliance timelines and EU Green Deal embodied carbon tracking implementation trajectories.
Forecasts assume regulatory continuity in EPA emissions standards and EU Green Deal provisions; material policy shifts would require re-modeling of replacement cycle assumptions and export market access conditions. Commodity price volatility in lumber and shipping costs represents a boundary condition. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Canada Home Furniture Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Global Folding Furniture Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
Europe Furniture Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
Taiwan Home Furniture Market
Furniture
North America School Furniture Market
Furniture
Vietnam Home Furniture Market
Furniture
Wooden Furniture Market
Furniture
United States Home Furniture Market
Furniture
Global Furniture Fittings Market
Furniture
Italy Furniture Retail Market
Furniture
Metal Furniture Market