
 Armchair on Casters Market | 2026-2036
Armchair on Casters Market Size, Share, and Industry Trends Forecast 2026-2036
Armchair on Casters Market Analytics
Aftermarket service revenue is fragmenting across reupholstery, caster replacement, and frame refurbishment as original manufacturers cede margin pools to independent repair networks. Herman Miller sustains premium positioning through captive supply of proprietary caster mechanisms and ergonomic certification programs. Ekornes ASA anchors Scandinavian design credibility while leveraging its Stressless recliner technology to command pricing power in residential channels. Ashley Furniture Industries competes on manufacturing scale, operating one of the largest upholstered furniture production footprints in North America to serve mass-market furniture outlets.
An armchair on casters is a wheeled seating unit combining an upholstered or hard-shell seat with a swivel or fixed base incorporating rolling casters, typically rated for load capacities between 250 and 400 pounds depending on frame construction. The primary commercial purpose spans residential living spaces, executive offices, and healthcare waiting areas where mobility, repositioning ease, and floor-surface protection drive specification. Ergonomic armchairs lead product type demand as employers and home office users prioritize lumbar support and adjustable tilt mechanisms over basic standard models. Fabric materials dominate volume shipments due to lower unit costs and broader pattern availability, though leather commands margin concentration in premium residential and hospitality segments.
The EPA regulates formaldehyde emissions from composite wood components under TSCA Title VI, directly affecting laminate and plywood substrates used in armchair frames sold in the United States. REACH compliance in Europe restricts phthalate-based plasticizers in caster wheels and polyurethane foam, compelling suppliers to reformulate soft components for market access. OSHA ergonomic guidelines for office seating influence institutional procurement specifications, particularly for healthcare facilities and educational institutions with large employee populations. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions, as these programs threaten to shift end-of-life collection costs upstream to manufacturers and reshape channel economics for online retail and wholesale distributors alike.
Market Dynamics
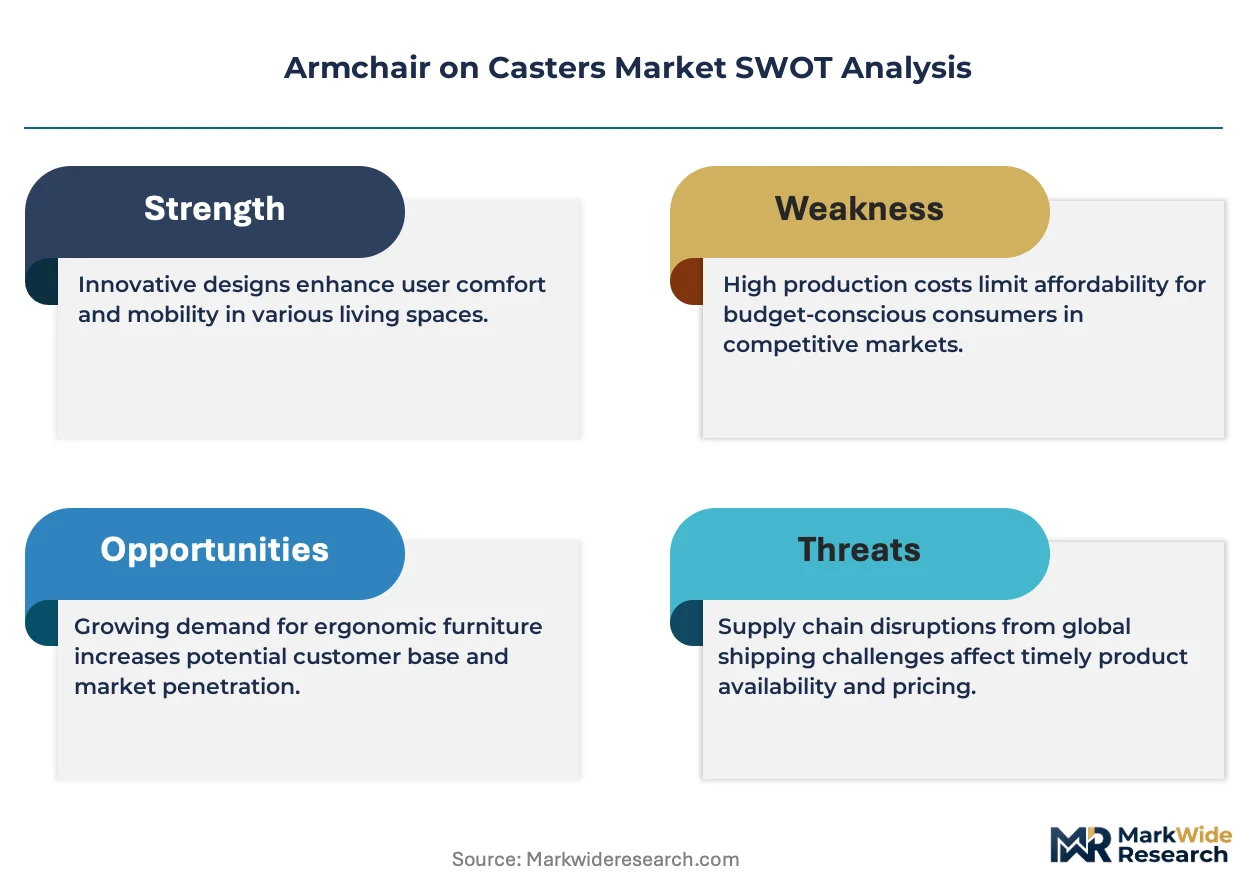
Home office permanence and aging residential demographics are restructuring demand flows away from commercial contract furniture toward mobility-enabled residential seating, forcing manufacturers to recalibrate distribution and service architectures.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Material disclosure mandates for upholstered furniture sold in Europe are accelerating transparency investments and favoring suppliers with certified supply chains.
- Remote-work permanence:Home office users now specify ergonomic casters and lumbar support as standard requirements, expanding the addressable market beyond traditional commercial buyers.
- German aging demographics:Replacement cycles for residential seating with mobility features sustain volume concentration in Europe's largest furniture market.
Market Restraints
- REACH phthalate restrictions:European chemical regulations force reformulation of caster wheel polyurethane and foam components, raising compliance costs for soft-component suppliers.
- Steel and aluminum input volatility:Frame and caster mechanism producers face margin compression from raw material price swings in metal commodities.
- Aftermarket fragmentation:Independent repair networks capture reupholstery and caster replacement revenue pools, eroding original manufacturer service attach rates.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging collection-cost mandates in multiple jurisdictions create first-mover advantage for manufacturers with reverse logistics infrastructure.
- Healthcare waiting-area specification:Mobility-enabled seating with infection-resistant upholstery opens institutional channels beyond traditional office and residential segments.
- Online direct-to-consumer channels:E-commerce platforms bypass wholesale furniture outlets, enabling margin recovery and customer data capture for mid-tier producers.
Industry Challenges
- Ergonomic certification timelines:OSHA guideline alignment and third-party testing protocols delay product launches for institutional procurement cycles.
- Legacy caster-floor compatibility:Heterogeneous residential flooring materials create specification complexity and return-rate risk for direct-ship retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armchair on Casters Market |
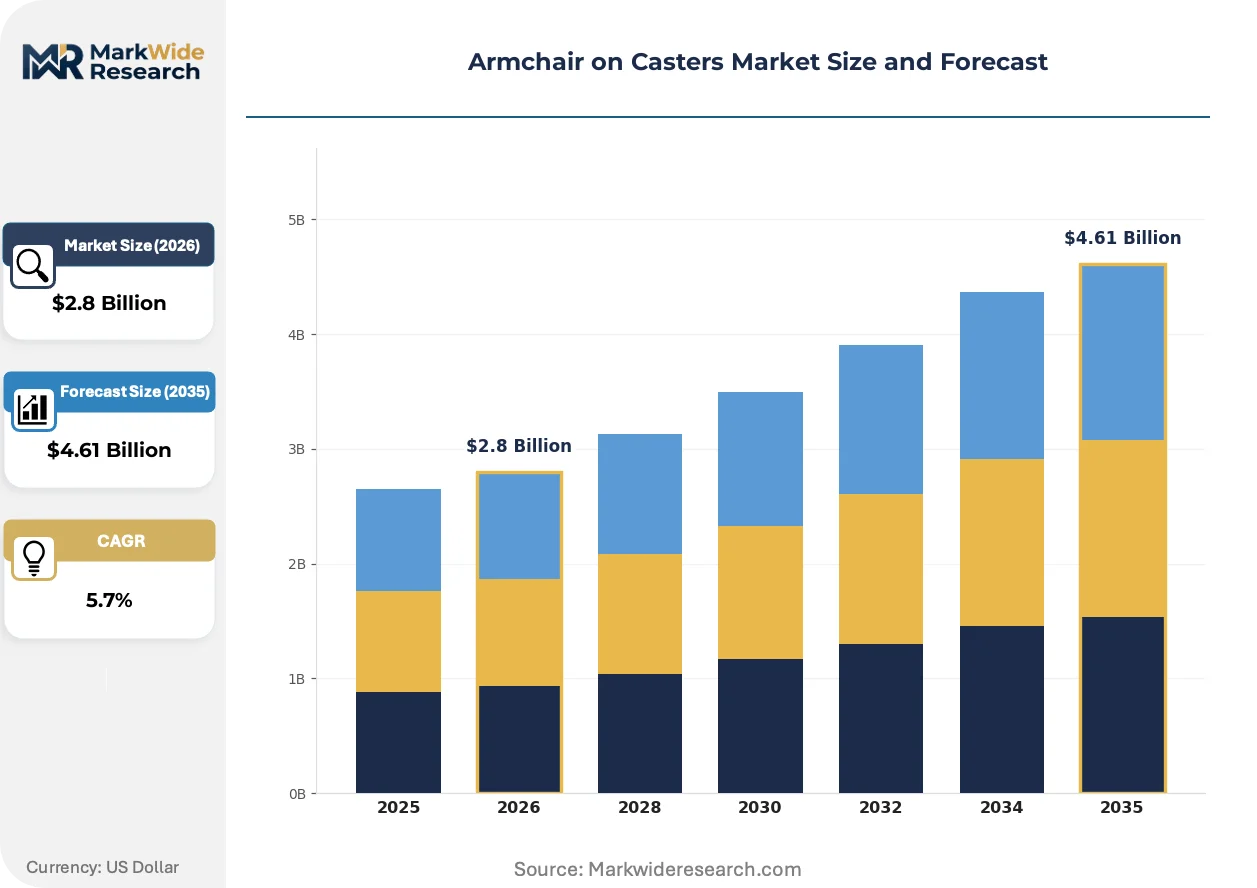
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Armchairs, Recliners, Ergonomic Armchairs, Office Chairs Material: Fabric, Leather, Plastic, Metal End User: Residential Users, Office Employees, Healthcare Facilities, Educational Institutions Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Furniture Outlets |
| Companies Covered | IKEA, La-Z-Boy, Herman Miller, Ashley Furniture Industries, Ekornes ASA, Natuzzi, Restoration Hardware, Poltrona Frau Group, Flexform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armchair on Casters Market Evolving Landscape
Sensor-enabled seating and predictive maintenance capabilities are converging with regulatory pressure on material provenance, reshaping how armchairs are specified, serviced, and valued across residential and institutional channels.
Smart caster systems with embedded load sensors and connectivity modules are digitizing fleet management for corporate and healthcare buyers. Facility managers in multi-location operations deploy these systems to track utilization patterns and schedule preemptive maintenance. This technology is digitizing the traditional break-fix service model into subscription-based uptime guarantees.
REACH substance restrictions and the EU Green Deal's carbon border adjustments are tightening compliance requirements for foam and plasticizer suppliers. Manufacturers must now document chemical composition through the full supply chain to maintain European market access. Upholstered furniture with recycled-content certification commands specification preference in German and French public procurement.
Buyers now unbundle after-sales service from initial purchase, selecting independent reupholstery networks and third-party caster suppliers based on cost and speed rather than brand loyalty. This pattern compresses manufacturer margin retention and forces channel partners to compete on service responsiveness rather than product exclusivity. The shift is most pronounced in North American residential e-commerce, where review-driven purchasing dominates.
Armchair on Casters Market Segmentation
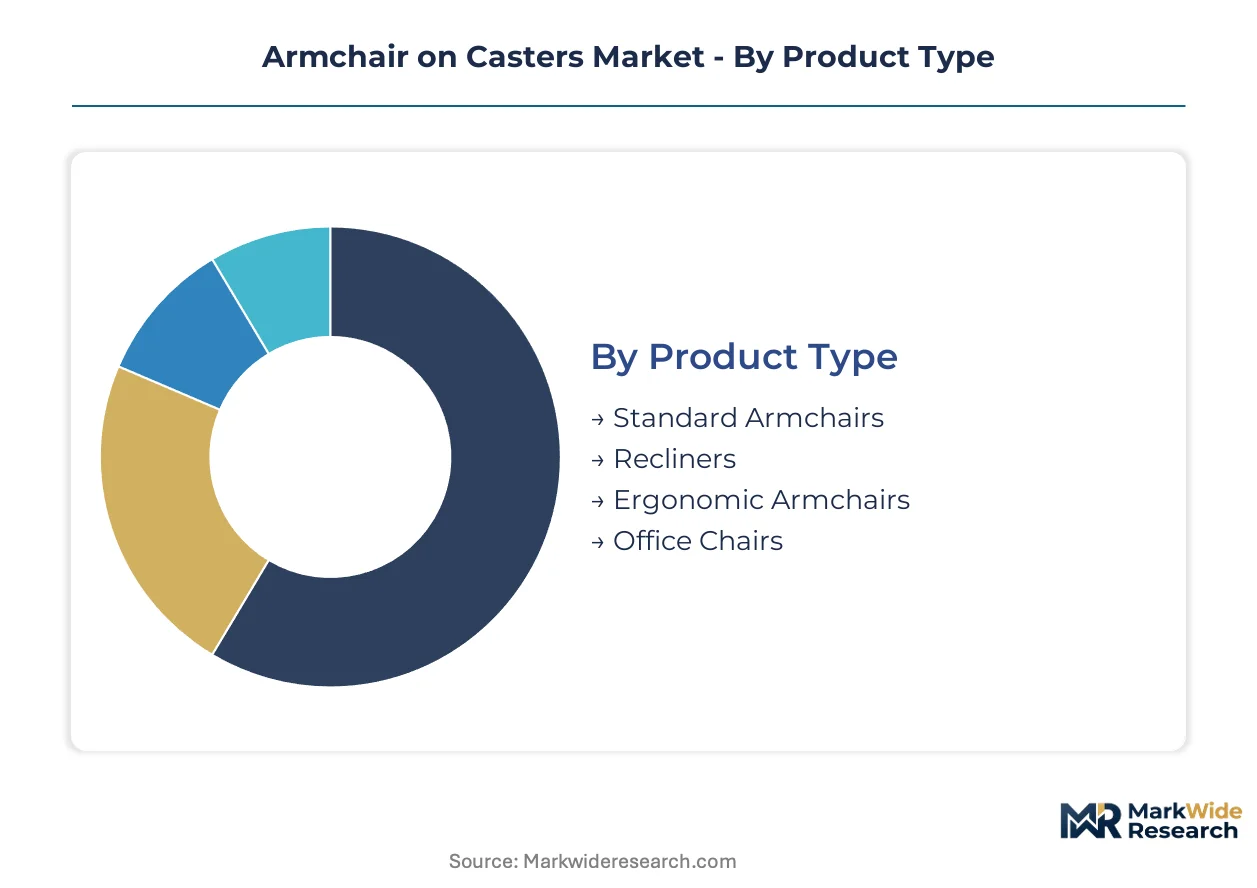
Segmentation in the armchair on casters market reveals how mobility-enabled seating serves divergent functional requirements across residential comfort, workplace ergonomics, and institutional durability. Manufacturers must align frame engineering, upholstery specifications, and caster ratings to distinct use-case demands rather than pursuing universal designs.
Product Type:
Mature categories dominate residential volume while emerging variants capture specification-driven commercial replacement cycles.
- Ergonomic Armchairs:Lumbar support mechanisms, adjustable tilt tension, and synchronized recline systems define this segment. Home office users in Germany and the United States now specify these as baseline requirements, displacing basic task seating in remote-work environments.
- Recliners:Stressless technology and integrated footrest mechanisms command premium positioning. Scandinavian design credibility sustains pricing power in residential channels where aging demographics prioritize comfort adjustability.
- Standard Armchairs:Fixed-back designs with basic swivel bases serve mass-market furniture outlets through lower unit costs and faster production cycles.
- Office Chairs:Task-oriented configurations with five-star bases and dual-wheel casters target institutional procurement cycles governed by OSHA ergonomic guidelines.
Ergonomic armchairs handle the majority of throughput; office chairs are expanding most quickly on share as healthcare and educational procurement accelerates.
Material:
Cost tiers separate premium specification from mass-market volume, with sustainability credentials increasingly influencing European procurement decisions.
- Fabric:Polyester blends and natural fiber weaves dominate shipment volumes through lower unit costs and pattern versatility. REACH-compliant dye processes and recycled-content certification now condition German and French public procurement preferences.
- Leather:Full-grain and corrected-grain hides command margin concentration in hospitality and executive residential segments. EPA formaldehyde regulations on composite substrates affect laminated frame compatibility with premium upholstery attachment methods.
- Plastic:Polypropylene and ABS shell constructions serve healthcare waiting areas requiring infection-resistant, wipe-clean surfaces.
- Metal:Powder-coated steel and aluminum frames provide structural ratings above 350 pounds for bariatric healthcare applications and heavy-use institutional environments.
Fabric handles the majority of throughput; leather is climbing the fastest on margin contribution as sustainability transparency reshapes premium positioning.
End User:
Customer type determines durability specifications, with institutional buyers enforcing stricter testing protocols than residential purchasers.
- Residential Users:Individual purchasers prioritize aesthetic coordination with interior design and caster-floor compatibility across hardwood, carpet, and tile surfaces.
- Office Employees:Corporate procurement departments specify ANSI/BIFMA compliance and warranty terms spanning 10-12 years for fleet deployments.
- Healthcare Facilities:Waiting-area and patient-room applications demand moisture-barrier upholstery, antimicrobial frame coatings, and 400-pound load ratings.
- Educational Institutions:K-12 and university procurement emphasizes vandal resistance, stackability, and rapid replacement part availability.
Residential users handle the majority of throughput; healthcare facilities are gaining share fastest as infection-control specifications expand addressable demand.
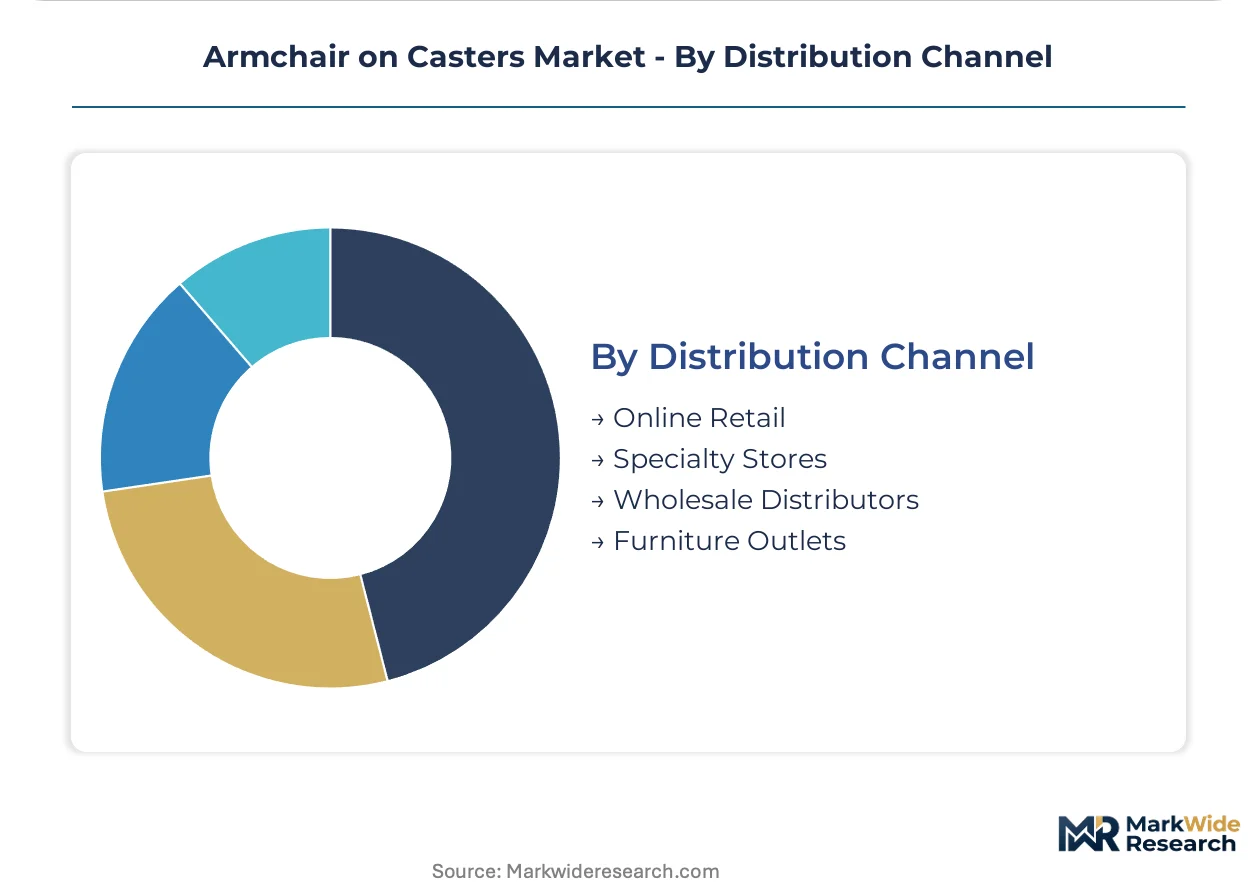
Distribution Channel:
Channel selection determines margin recovery and customer data access, with digital platforms disrupting traditional wholesale furniture economics.
- Online Retail:Direct-to-consumer platforms enable mid-tier manufacturers to bypass wholesale markups while capturing purchase behavior data for product development.
- Specialty Stores:Design-focused showrooms provide tactile evaluation and white-glove delivery services for premium ergonomic and recliner categories.
- Wholesale Distributors:Furniture logistics networks serve mass-market retailers with consolidated freight and inventory financing for standard armchair volumes.
- Furniture Outlets:Big-box and regional chains compete on price transparency and immediate availability, compressing manufacturer margins through volume purchasing power.
Wholesale distributors handle the majority of throughput; online retail is expanding most quickly on share as review-driven purchasing reshapes residential buying behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in Germany demonstrate the lowest price elasticity for ergonomic casters, while mass-market consumers in the United States and emerging Asian markets prioritize unit cost over certification premiums. This divergence shapes manufacturer channel strategies and margin recovery profiles.
Germany
Aging demographics and remote-work permanence sustain replacement cycles for mobility-enabled residential seating. The EU Ecodesign for Sustainable Products Regulation mandates material disclosure for upholstered furniture, accelerating transparency investments among suppliers. North Rhine-Westphalia hosts concentrated upholstery manufacturing clusters where REACH-compliant foam reformulation is reshaping component sourcing.
United States
Home office adoption pulls demand from traditional commercial contract channels toward residential ergonomic specification. EPA formaldehyde regulations under TSCA Title VI affect composite wood substrates in armchair frames. The Southeast furniture manufacturing belt, particularly North Carolina and Mississippi, anchors mass-market production capacity serving big-box retail channels.
China
Domestic consumption of mid-tier ergonomic seating expands alongside export manufacturing for global brands. GB standards and MIIT industrial policy guide quality certification for furniture components. The Pearl River Delta cluster around Dongguan and Foshan concentrates metal frame and caster mechanism production for international supply chains.
United Kingdom
Post-pandemic hybrid work patterns sustain demand for residential office seating with aesthetic coordination requirements. The UK Furniture and Furnishings (Fire Safety) Regulations enforce flammability standards for upholstery materials. The Midlands manufacturing region, centered on Nottinghamshire and Leicestershire, maintains specialized upholstery finishing capabilities for premium residential brands.
Italy
Design-driven residential demand prioritizes leather-upholstered recliners and executive seating with mobility features. CE marking requirements and EU Green Deal carbon border adjustments condition export competitiveness. The Brianza furniture district north of Milan concentrates high-end upholstered seating production with integrated supply chains for premium casters and mechanisms.
Armchair on Casters Market Competitive Landscape
Capability concentration sits with ergonomic specialists and design houses; scale advantage sits with mass-market fabricators with captive distribution. The market structures around three tiers: premium ergonomic brands with certification programs, mid-market residential specialists with Scandinavian or Italian design positioning, and high-volume producers serving wholesale furniture outlets. Consolidation pressure runs through M&A activity targeting regional upholstery capabilities and strategic partnerships for caster mechanism supply.
Among premium-tier ergonomic specialists, Herman Miller exemplifies certification-driven positioning through proprietary mechanism supply and workplace wellness programs. Ekornes ASA anchors Scandinavian design credibility with Stressless recliner technology commanding residential pricing power. Ashley Furniture Industries occupies the scale-driven end with North American manufacturing footprint serving mass-market furniture outlets through consolidated freight and inventory financing.
| Leading Market Players |
|---|
| IKEA |
| La-Z-Boy |
| Herman Miller |
| Ashley Furniture Industries |
| Ekornes ASA |
| Natuzzi |
| Restoration Hardware |
| Poltrona Frau Group |
| Flexform |
| Others |
Value Network & Pricing Analysis
Dongguan's metal frame and caster mechanism clusters concentrate export manufacturing capacity for global brands, creating asymmetric pricing power for suppliers with captive polyurethane foam reformulation capabilities under REACH compliance timelines. North Carolina's upholstered furniture belt anchors mass-market production for big-box retail channels, where consolidated freight economics compress unit costs but erode margin recovery for manufacturers lacking direct-to-consumer infrastructure.
Pricing Analysis
Aftermarket service revenue from reupholstery, caster replacement, and frame refurbishment now drives lifetime value capture more than initial hardware margins. Three-tier pricing structure across premium ergonomic certification, standard residential utility, and economy mass-market tiers segments buyer willingness-to-pay. Price differentiation rests on proprietary mechanism supply and ergonomic certification grade. Pricing pressure stems from independent repair networks capturing service attach revenue. Mass-market furniture outlet buyers exhibit highest price sensitivity; German aging residential purchasers show lowest elasticity for mobility-enabled ergonomic specification.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from wholesale distributors anchor working capital structures for mass-market fabricators in China and Vietnam. Raw material flows draw from steel and aluminum frame inputs in the Pearl River Delta, REACH-compliant foam components in Germany's North Rhine-Westphalia cluster, and leather finishing in Italy's Brianza district. Single-source vulnerability concentrates in proprietary caster mechanism supply. Distribution runs through wholesale furniture logistics networks, with direct-to-consumer platforms gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive maintenance subscriptions and sensor-enabled fleet management expands faster than hardware unit sales, reframing competitive advantage around uptime guarantees rather than transactional seating volume.
For Market Incumbents: Entrench proprietary caster mechanism supply through backward integration into polyurethane foam reformulation, defending margin pools against independent repair network encroachment. Capture customer data via direct-to-consumer platforms to preempt aftermarket fragmentation. Prioritize ergonomic certification investments that institutional procurement mandates. For New Entrants and Emerging Players: Establish a beachhead in healthcare waiting-area specification where infection-resistant upholstery and 400-pound load ratings create procurement barriers for undifferentiated competitors. Target mid-tier ergonomic residential segments in aging European demographics with Scandinavian design positioning. Deploy online direct-to-consumer channels with review-driven purchasing optimization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-enabled seating specialists with recurring revenue infrastructure over pure hardware fabricators. Long-term viability hinges on reverse logistics capabilities for extended producer responsibility frameworks. Watch smart caster adoption rates in multi-location healthcare and corporate fleet deployments as inflection indicator for subscription model traction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Reformulation | REACH-compliant polyurethane supply secures European market access against chemical regulation barriers. |
| Sensor-Enabled Fleet Management Launch | Predictive maintenance subscriptions digitize break-fix service models into recurring revenue streams. |
| Direct-to-Consumer Channel Expansion | Online platforms bypass wholesale markups while capturing purchase behavior data for product development. |
| Ergonomic Certification Investment | ANSI/BIFMA and OSHA-aligned testing protocols unlock institutional procurement cycles with 10-12 year warranties. |
| Reverse Logistics Infrastructure Buildout | Extended producer responsibility compliance creates first-mover advantage in emerging collection-cost jurisdictions. |
Research Methodology
Cross-validation between primary interviews with furniture manufacturing executives, ergonomic certification specialists, wholesale distribution channel heads, and institutional procurement officers anchors the qualitative findings against secondary validation from EPA TSCA Title VI filings, ECHA REACH substance registrations, customs trade data for upholstered furniture imports, and SEC 10-K disclosures from publicly traded manufacturers. Bottom-up shipment analysis triangulates against top-down demand modeling across residential, office, healthcare, and educational end-use segments.
Calibration against historical volume trajectories and replacement cycle patterns shapes the analytical framework across the analysis window. Segmentation dimensions include product type tier, material grade, end-user durability specification, and distribution channel format. CAGRs derive from fitted growth curves adjusted for regulatory compliance timelines and demographic demand drivers. Forecast inputs incorporate remote-work permanence assumptions and EU Ecodesign material disclosure implementation schedules.
Sensitivities concentrate around REACH substance restriction expansion, steel and aluminum commodity volatility, and smart caster technology adoption rates. Forecasts reflect documented assumptions on replacement cycle duration and channel shift velocity. Macroeconomic contraction, accelerated extended producer responsibility mandates, or breakthrough seating technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Italy Luxury Furniture Market
Furniture
United Arab Emirates Furniture Market
Furniture
Global Organic Furniture Market
Furniture
Spain Furniture Market
Furniture
UK Sustainable Home Furniture Market
Furniture
Portering Chair Market
Furniture
Russia Home Furniture Market
Furniture
Back Mount Frames Market
Furniture
Furniture Laminate Market
Furniture
Wooden Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Home Furnishings Market
Furniture
Germany Furniture Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
Luxury Furniture Market
Furniture
High Density Fiberboard (HDF) Market