
 Enterprise Asset Leasing Market | 2026-2036
Enterprise Asset Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Asset Leasing Market Intelligence
Buyer concentration among large logistics fleets and healthcare networks is shifting toward multi-year master lease agreements that consolidate vendor relationships. United Rentals dominates North American construction equipment leasing through branch density and fleet scale. Orix Corporation anchors Asian market presence with cross-border aviation and maritime asset platforms. Deutsche Leasing AG competes across European SME segments with localized underwriting and residual value expertise.
Enterprise asset leasing encompasses contractual arrangements where businesses obtain use rights to vehicles, machinery, IT equipment, or furniture without transferring ownership, governed by term structures, residual value assumptions, and return conditions. The primary purpose is to convert capital expenditures into predictable operating costs while preserving balance sheet flexibility and technology refresh options. Operating lease structures command the largest transaction volume among leasing types due to off-balance-sheet treatment and embedded maintenance services. SME customer segments represent the fastest-growing demand pool as digital onboarding and automated credit scoring reduce origination friction. Finance lease portfolios generate concentrated margin pools from residual value realization and end-of-term asset remarketing.
The SEC mandates lease capitalization under ASC 842, compelling corporations to reassess ownership versus lease structures for financial statement transparency. EBA guidelines and Basel III frameworks shape European bank-affiliated lessors' capital reserve requirements and risk-weighting methodologies. Stakeholders must monitor evolving accounting standards, central bank rate trajectories, and residual value volatility to optimize lease portfolio construction and funding mix decisions.
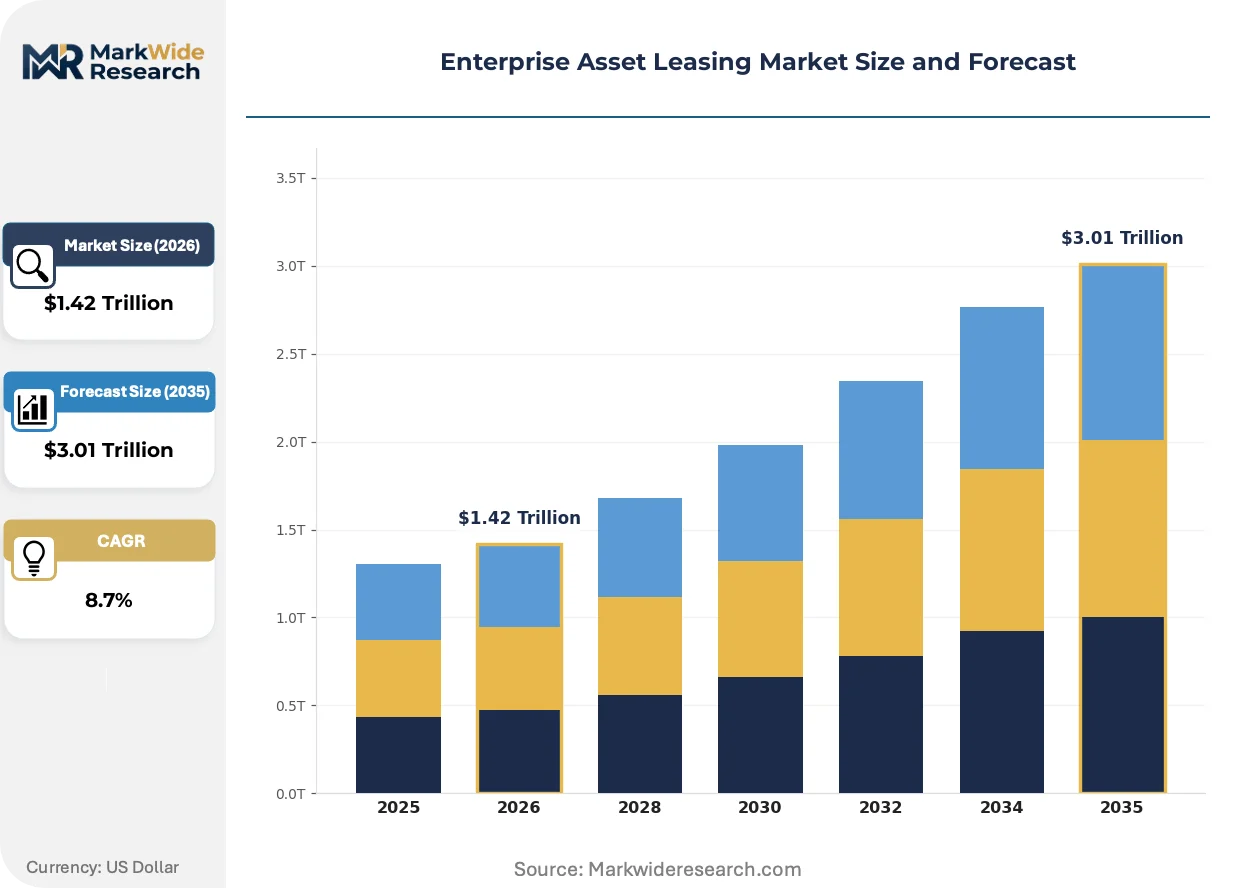
Market Dynamics
ASC 842 lease capitalization mandates are compressing operating lease advantages and forcing CFOs to restructure balance sheet strategies across capital-intensive industries.
Growth Catalysts
- Healthcare Equipment Modernization:Hospital networks facing reimbursement pressure are converting MRI, CT, and surgical robot acquisitions to multi-year operating leases. The SEC's climate disclosure rules simultaneously favor off-balance-sheet structures for sustainability reporting transparency.
- EBA Capital Relief Frameworks:European bank-affiliated lessors leverage Basel III risk-weighting advantages to price SME equipment leases below traditional commercial lending rates.
- Logistics Fleet Electrification:Battery-electric truck deployment timelines accelerate as fleet operators lease to avoid residual value risk on unproven powertrain technology.
Market Restraints
- Central Bank Rate Trajectories:Fed and ECB policy rate uncertainty compresses net interest margin spreads for fixed-rate lease portfolios.
- Residual Value Volatility:Semiconductor equipment and commercial aircraft lessors face concentrated exposure to technology obsolescence cycles and cyclical demand collapses.
- Input Cost Concentration:Steel and aluminum price volatility in Asian manufacturing hubs directly impacts construction equipment lease rate competitiveness.
Strategic Opportunities
- India SME Digital Onboarding:Automated credit scoring and Aadhaar-linked KYC protocols reduce origination friction for mid-market manufacturing equipment leases.
- CSRD-Aligned Green Leasing:EU corporate sustainability reporting mandates create demand for circular economy asset structures with embedded carbon accounting.
- Aviation Cross-Border Platforms:Asia-Pacific air cargo expansion drives wet lease and power-by-the-hour structures for freighter aircraft.
Industry Challenges
- Embedded Systems Integration:IoT-enabled usage-based billing requires legacy ERP reconciliation with telematics platforms across heterogeneous fleet portfolios.
- Certification Timeline Compression:FAA and EASA airworthiness directives on aging commercial aircraft compress remarketing windows and residual realization periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Asset Leasing Market |
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $3.01 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Asset Type: Vehicles, Machinery, IT Equipment, Furniture Customer Segment: Corporations, SMEs, Government, Non-Profits Leasing Type: Operating Lease, Finance Lease, Sale and Leaseback, Capital Lease Payment Structure: Monthly Payments, Upfront Payment, Deferred Payments, Balloon Payments |
| Companies Covered | Orix Corporation, Ashtead Group plc, General Electric Company, Deutsche Leasing AG, Herc Rentals Inc., United Rentals Inc., BNP Paribas SA, Air Lease Corporation, Caterpillar Financial Services Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Asset Leasing Market Strategic Shifts & Innovations
Telematics penetration and usage-based pricing models are displacing fixed-term structures in fleet and equipment leasing, compressing traditional risk assessment methodologies.
Blockchain-enabled smart contracts are expanding into lease administration functions, automating payment verification, condition assessment triggers, and end-of-term asset transfers. Logistics operators with dispersed equipment footprints adopt these platforms to reduce documentation friction across multi-jurisdictional portfolios. The structural consequence is expanding into disintermediation of traditional lease servicers and captive finance arms.
CSRD disclosure requirements in the European Union mandate granular asset-level carbon footprint reporting for leased equipment. This regulatory pressure forces lessors to embed lifecycle emissions tracking into contract structures and residual value models. Heavy machinery and commercial vehicle segments face the steepest compliance cost escalation.
Fleet operators now demand unbundled maintenance and insurance components from core lease payments, reversing decades of full-service bundling. Third-party maintenance aggregators and parametric insurance platforms capture value previously retained by captive lessors. This behavioral shift is most pronounced in United States long-haul trucking and last-mile delivery verticals.
Enterprise Asset Leasing Market Segmentation
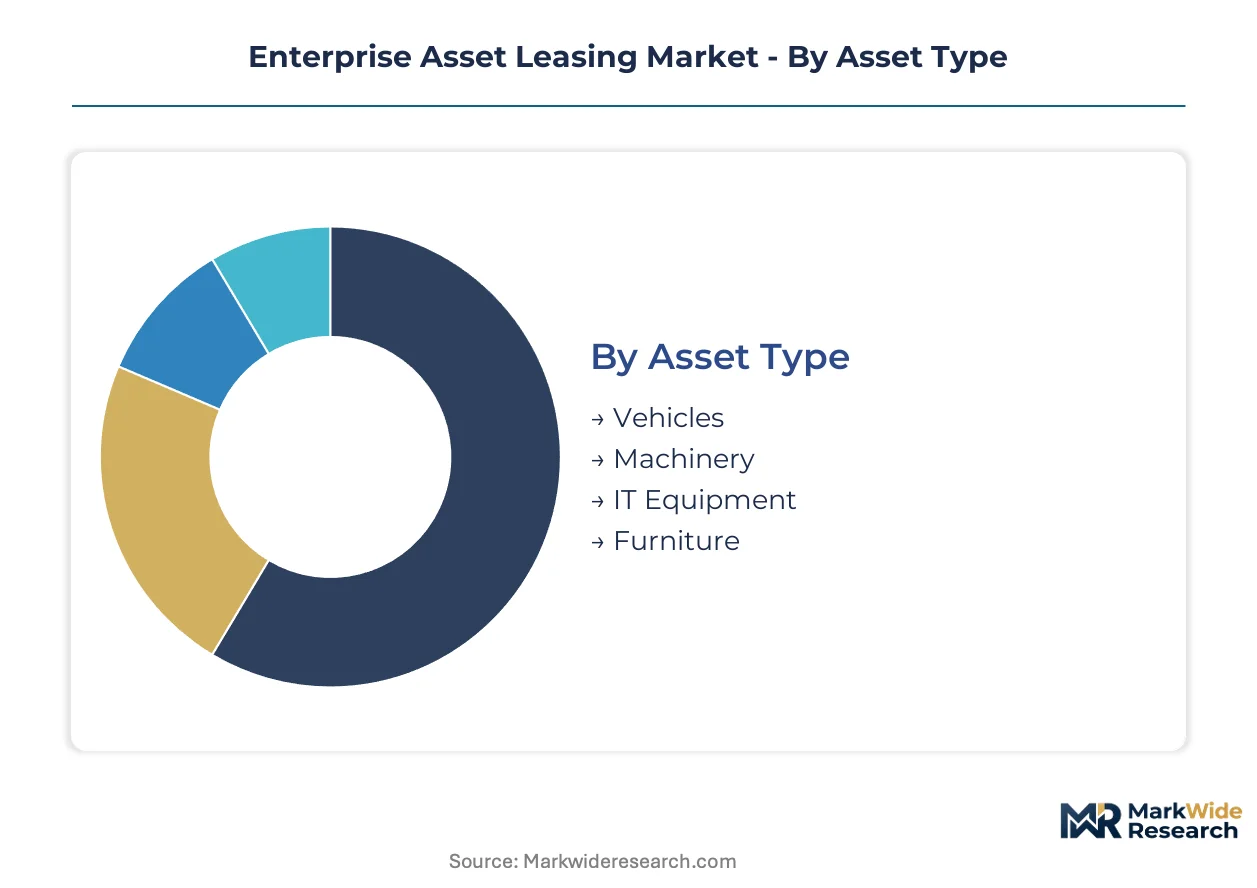
Enterprise asset leasing segmentation reveals distinct capital intensity profiles and regulatory treatment across asset classes. Leasing structures align with balance sheet strategies, tax optimization objectives, and technology refresh cycles that vary sharply by customer scale and industry vertical.
Asset Type:
FAA airworthiness certification governs aviation leasing, while FCC equipment authorization shapes IT hardware structures. Machinery and vehicle segments face divergent residual value risk frameworks.
- Vehicles:Fleet leasing spans commercial trucks, passenger cars, and specialty equipment with telematics-enabled usage tracking. Demand concentrates in United States logistics corridors where electrification timelines accelerate lease term compression.
- Machinery:Construction and manufacturing equipment carries residual value exposure to commodity price cycles and technology obsolescence. German industrial clusters and Texas energy basins drive concentrated deployment of CNC machines and drilling platforms.
- IT Equipment:Server, networking, and endpoint device leasing requires rapid refresh cycles to maintain cybersecurity compliance. Cloud migration pressures are shortening effective lease durations for on-premise infrastructure.
- Furniture:Office systems and modular workspace solutions carry lower residual volatility but higher transaction friction from customization requirements.
Vehicles sit at the top of the volume ranking, with IT equipment climbing the fastest.
Customer Segment:
Credit assessment protocols scale from automated scoring for SMEs to covenant-heavy structures for multinational corporations. Government and non-profit segments trigger specialized procurement regulations and tax-exempt financing mechanisms.
- Corporations:Large enterprises leverage master lease agreements and portfolio-level rate negotiations. ASC 842 compliance costs are driving operating lease restructuring among Fortune 500 treasury departments.
- SMEs:Digital onboarding platforms and alternative credit data are expanding addressable markets for mid-market manufacturing and service firms. India and Brazil show steepest origination volume expansion.
- Government:Federal, state, and municipal leases incorporate prevailing wage requirements and domestic content provisions that elevate transaction complexity.
- Non-Profits:Mission-driven organizations access tax-advantaged structures through 501(c)(3) qualified lease financing with specialized residual treatment.
Corporations command the largest outstanding lease volume, though SME origination velocity is gaining share fastest.
Leasing Type:
Accounting classification under ASC 842 and IFRS 16 determines balance sheet treatment and drives structural preference shifts. Tax ownership transfer rules and depreciation recapture exposure vary across lease categories.
- Operating Lease:Off-balance-sheet treatment preserves debt capacity and covenant headroom for capital-intensive industries. SEC climate disclosure rules are reinforcing demand for this structure among sustainability-focused corporates.
- Finance Lease:Capitalization requirements align lessee treatment with economic substance, concentrating in heavy machinery and aircraft where ownership transfer is probable. European bank-affiliated lessors price these structures aggressively under Basel III risk-weighting advantages.
- Sale and Leaseback:Liquidity extraction from owned assets enables balance sheet deleveraging for real estate and infrastructure-heavy enterprises.
- Capital Lease:Legacy terminology persists in certain jurisdictions with specific tax code elections governing depreciation benefits.
Operating leases dominate transaction count, while finance leases capture the steepest expansion trajectory in aviation and maritime.
Payment Structure:
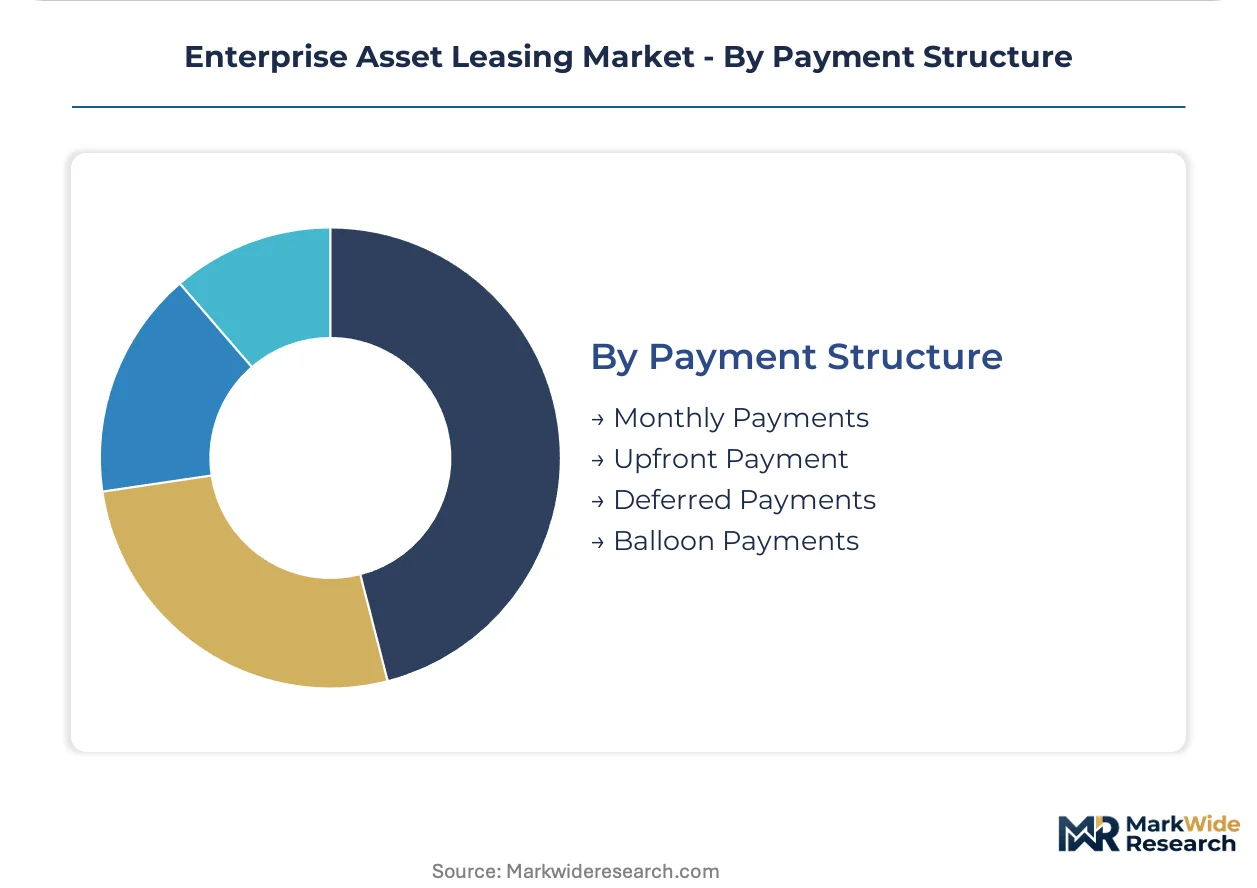
Cash flow matching drives structure selection, with seasonal businesses favoring deferred patterns and credit-constrained borrowers accepting balloon exposure for lower periodic obligations.
- Monthly Payments:Level amortization structures dominate fleet and equipment leasing for predictable budgeting. United States trucking operators and German Mittelstand manufacturers show strongest preference concentration.
- Upfront Payment:Advance rental structures reduce effective interest rates and satisfy lessor security requirements for high-risk credits or specialized assets.
- Deferred Payments:Seasonal businesses in agriculture and construction align obligations with revenue recognition timing.
- Balloon Payments:Residual value exposure shifts to lessee, common in commercial vehicle leasing where end-of-term purchase options are routinely exercised.
Monthly payment structures anchor the market by volume, with balloon structures expanding most quickly in used vehicle remarketing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Mittelstand manufacturing base generates denser equipment lease penetration than India's emerging SME sector, though Indian origination velocity is accelerating faster under digital onboarding protocols.
United States
Logistics fleet electrification and healthcare network consolidation drive multi-year master lease demand. SEC climate disclosure rules pressure Fortune 500 treasury departments toward off-balance-sheet operating structures. Dallas-Fort Worth and Chicago logistics corridors concentrate battery-electric truck leasing activity.
Germany
Industrial machinery leasing anchors demand from automotive component suppliers and precision engineering clusters. EBA capital relief frameworks under Basel III enable bank-affiliated lessors to price SME equipment leases below commercial lending rates. Baden-Württemberg and Bavaria host concentrated CNC machine and robotics leasing deployment.
India
Mid-market manufacturing expansion and agricultural mechanization create origination volume surges. Aadhaar-linked KYC protocols and automated credit scoring reduce friction for equipment lease onboarding. Gujarat and Maharashtra industrial corridors show steepest growth in construction and textile machinery leasing.
Japan
Aging capital stock replacement and semiconductor equipment refresh cycles sustain corporate lease demand. METI industrial policy incentives favor operating lease structures for technology-intensive assets. Kyushu and Chubu manufacturing belts concentrate precision equipment leasing transactions.
United Kingdom
Corporate realignment post-Brexit drives sale-and-leaseback liquidity extraction from owned infrastructure. CSRD-aligned sustainability reporting mandates favor circular economy asset structures with embedded carbon accounting. London and Southeast England financial centers anchor cross-border aviation and maritime leasing platforms.
Enterprise Asset Leasing Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across fragmented tiering. Bank-affiliated lessors leverage regulatory capital advantages to undercut independent competitors on rate. Three archetypes dominate: integrated equipment manufacturers with captive finance arms, independent fleet-scale rental operators, and bank-backed multi-asset platforms. Geographic expansion through branch density and residual value expertise through specialized underwriting represent the primary competitive vectors.
Among Asia-Pacific headquartered conglomerates, Orix Corporation anchors cross-border aviation and maritime asset platforms. United Rentals exemplifies the fleet-scale independent operator model dominating North American construction equipment through branch density. Deutsche Leasing AG occupies the bank-affiliated specialist position across European SME segments with localized underwriting capabilities.
| Leading Market Players |
|---|
| Orix Corporation |
| Ashtead Group plc |
| General Electric Company |
| Deutsche Leasing AG |
| Herc Rentals Inc. |
| United Rentals Inc. |
| BNP Paribas SA |
| Air Lease Corporation |
| Caterpillar Financial Services Corporation |
| Others |
Cost & Logistics Intelligence
Bank-affiliated lessors with captive funding pools anchor supply-side discipline, compressing rate spreads for independent competitors while concentrating pricing power in residual value underwriting expertise. This ownership pattern feeds directly into lease rate construction, where Basel III capital relief advantages translate into structurally lower cost of funds for European bank platforms versus private-equity-backed specialists.
Pricing Analysis
Capacity additions in India's digital onboarding infrastructure are reshaping price floors for SME equipment leases, forcing incumbent lessors to match automated credit-scoring efficiency. The dominant pricing structure stratifies across premium full-service bundles, standard maintenance-inclusive contracts, and economy bare-lease arrangements. Price differentiation hinges on residual value guarantee depth and embedded telematics coverage. Cost compression in the economy tier is intensifying because fintech entrants are disintermediating traditional origination networks. Fleet operators with electrification mandates show least price sensitivity, while cash-constrained agricultural equipment lessees exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for commercial vehicle and aviation assets, while distributor networks serve fragmented SME manufacturing equipment procurement. Supply concentration centers on Germany for precision machinery, Japan for semiconductor equipment, and China for construction equipment components. Raw material dependencies include steel and aluminum from Asian manufacturing hubs, lithium-ion cells from South Korean producers, and specialized avionics from US suppliers. Single-source vulnerability in FAA-certified component supply creates remarketing timeline risk for aging aircraft portfolios. Distribution runs through lessor-owned branch networks for construction equipment and third-party broker platforms for IT hardware refresh cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
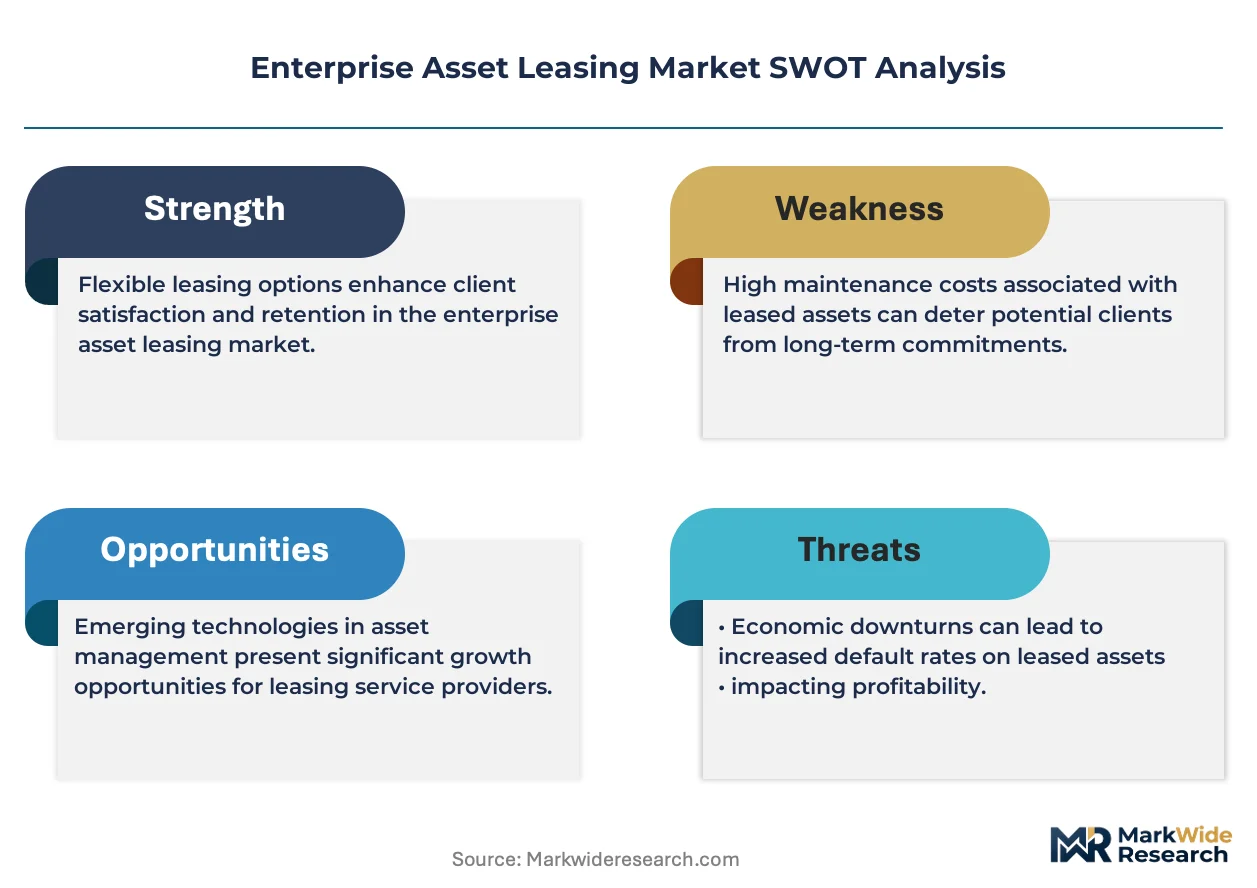
Enterprise asset leasing functions as a regulatory compounder where ASC 842 capitalization mandates and SEC climate disclosure rules simultaneously expand demand for operating lease structures while elevating compliance costs for market participants.
For Market Incumbents: Acquire residual value underwriting platforms specializing in battery-electric vehicle depreciation modeling to counter technology obsolescence risk from unproven powertrain lifecycles. Consolidate branch density in Dallas-Fort Worth and Chicago logistics corridors to defend against fleet-scale independent operators. Vertical integration into IoT telematics deployment preserves margin pools from third-party usage-based billing platforms.
For New Entrants and Emerging Players: Enter via India's Aadhaar-linked digital onboarding protocols for mid-market manufacturing equipment leases, where origination friction reduction creates addressable market expansion. Target Gujarat and Maharashtra industrial corridors with automated credit-scoring platforms that undercut bank-affiliated lessors on approval velocity. White-label residual value insurance products to construction equipment distributors lacking captive finance arms.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent fleet-scale rental operators with underoptimized telematics penetration and legacy ERP systems. Long-term viability over the projection horizon rests on embedded carbon accounting capabilities for CSRD-aligned corporate clients. Monitor FAA airworthiness directive issuance frequency as inflection indicator for commercial aircraft remarketing window compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Residual Value Platform Acquisition | Battery-electric truck depreciation expertise addresses unproven powertrain lifecycle risk for fleet lessors. |
| Telematics Infrastructure Deployment | IoT-enabled usage tracking displaces fixed-term billing and captures value from third-party aggregators. |
| Digital Onboarding Scale-Up | Aadhaar-linked KYC protocols in India reduce origination friction for SME manufacturing equipment leases. |
| Green Leasing Certification Program | CSRD-aligned carbon accounting embeds circular economy structures into contract documentation. |
| Cross-Border Aviation Platform Expansion | Asia-Pacific air cargo growth drives wet lease and power-by-the-hour structures for freighter aircraft. |
Research Approach
Multiple input streams — structured interviews with fleet procurement directors and treasury officers, automated credit-scoring platform data, and residual value realization databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged lessor underwriting heads, captive finance executives, OEM distribution managers, and logistics fleet operators across North America, Europe, and Asia-Pacific. Secondary validation drew from SEC lease disclosure filings, EBA capital framework documentation, FAA airworthiness directives, and customs equipment trade statistics.
Data-stream reconciliation across supply-side capacity indicators and demand-side origination velocity produced segment-level volume and value estimates throughout the forecast period. The analytical framework modeled asset type, customer segment scale, leasing structure classification, and payment configuration dimensions. CAGRs were derived from regression analysis against central bank rate trajectories and fleet modernization cycle timing. Industry-specific forecast inputs included semiconductor equipment depreciation curves and commercial aircraft remarketing timeline compression from regulatory certification mandates.
Inputs from structured executive interviews and disclosed regulatory filings were available through the study window; gaps in private lessor portfolio composition introduce uncertainty bands around residual value realization assumptions. Forecasts reflect documented assumptions regarding technology obsolescence cycles and central bank policy normalization paths. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
India Car Loan Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Invoice Factoring Market
Loans and Leasing
Asia-Pacific Motorcycle Loan Market
Loans and Leasing
Factoring Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
NPL Servicing Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
Japan Mortgage/Loan Brokers Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
US Home Equity Lending Market