
 Hotel and Hospitality Management Software Market | 2026-2036
Hotel and Hospitality Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Hotel and Hospitality Management Software Market Outlook
Mid-sized independent hotels is redrawing competitive priorities for platform vendors. Cloudbeds leverages direct channel connectivity to sustain pricing autonomy for property owners across fragmented markets. Oracle Opera Cloud anchors enterprise-grade deployments through deep PMS functionality and multi-property orchestration. SiteMinder competes aggressively on distribution breadth, controlling connections to hundreds of online travel agencies and metasearch engines.
Hotel and hospitality management software comprises integrated digital platforms that automate front-desk operations, reservation workflows, revenue optimization, and guest communication through API-connected modules operating on cloud or on-premises infrastructure. These systems process real-time inventory, rate parity, and guest preference data to synchronize operations across properties, channels, and service departments. Property Management System deployments generate the deepest margin pools due to their central role in daily operations and high switching costs, while Revenue Management Software represents the fastest-expanding segment as dynamic pricing algorithms displace static rate calendars. Cloud-Based delivery dominates new implementations, though Hybrid architectures persist among large resort operators requiring localized failover capabilities.
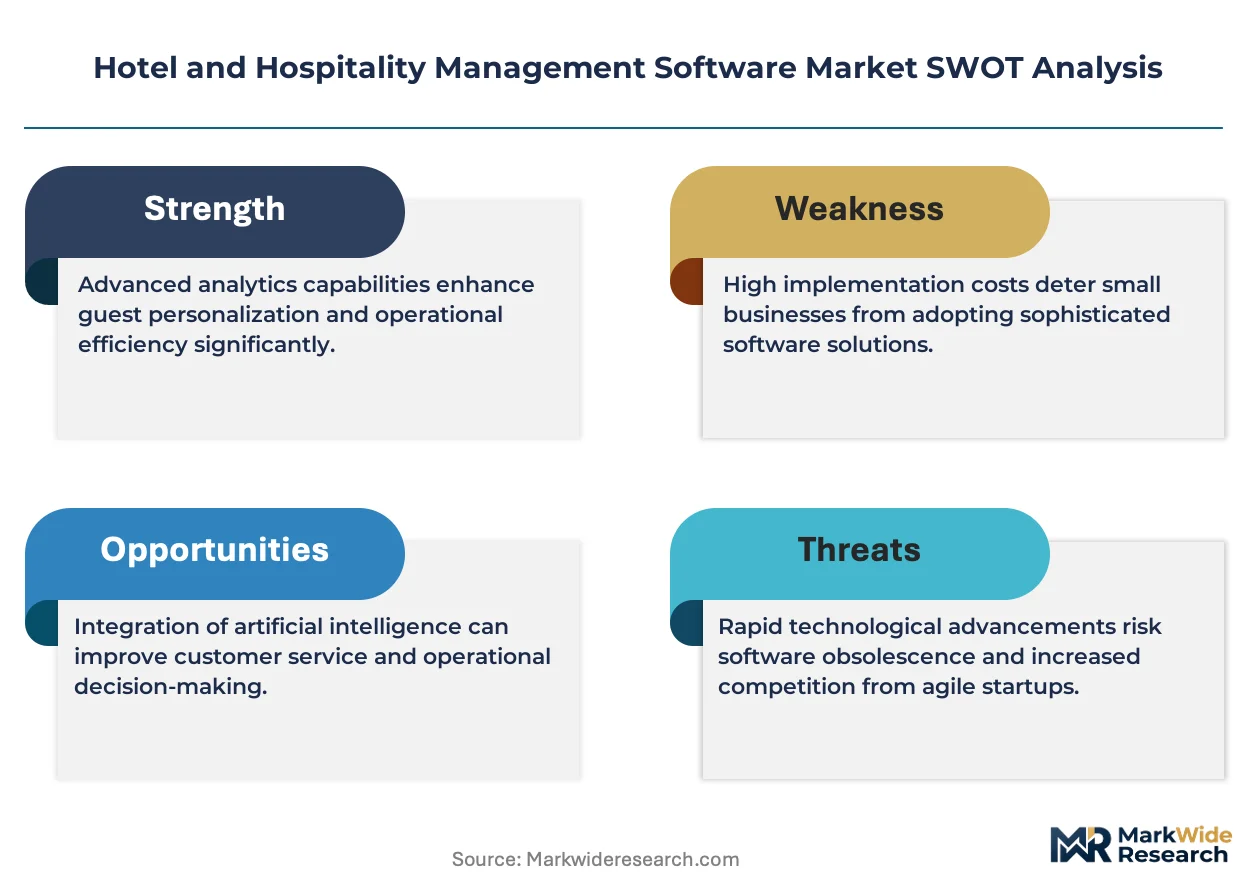
FDA guidelines on cybersecurity for connected hospitality devices, GDPR data sovereignty rules enforced by European regulators, and PCI-DSS payment security standards collectively elevate compliance costs for cross-border platform deployments. Vendors must architect systems for jurisdictional data residency while maintaining unified guest profiles across properties. Stakeholders should monitor how emerging AI disclosure requirements in the European Union reshape automated guest interaction features and algorithmic pricing transparency obligations.
Market Dynamics
Cloud migration pressure is compressing vendor margins while elevating switching costs for property operators locked into legacy on-premises Property Management Systems. The EU AI Act and GDPR enforcement are forcing architectural rewrites for guest-facing automation modules.
Growth Catalysts
- PCI-DSS compliance mandates:Payment security standards in the United States are accelerating replacement cycles for outdated point-of-sale integrations.
- Boutique hotel consolidation:Independent properties in fragmented markets are pooling procurement to negotiate enterprise-tier SaaS pricing.
- Dynamic pricing algorithms:Revenue Management Software adoption is displacing static rate calendars across mid-sized properties.
Market Restraints
- GDPR data residency requirements:European regulators are imposing jurisdictional storage obligations that fragment unified guest profile architectures.
- Cloud infrastructure concentration:Hyperscaler dependency in Ireland and Frankfurt creates single-point-of-failure exposure for multi-property operators.
- API integration complexity:Legacy property systems lack standardized middleware, forcing expensive custom connector development.
Strategic Opportunities
- Japan's aging property infrastructure:Legacy system replacement cycles are opening greenfield cloud deployments in Tokyo and Osaka hotel clusters.
- EU AI Act transparency requirements:Automated guest interaction disclosure rules are creating first-mover advantage for vendors with explainable algorithmic pricing.
- Voice-activated room controls:Natural language processing convergence with IoT sensors is enabling new upsell categories for premium room tiers.
Industry Challenges
- Cybersecurity talent scarcity:Hospitality IT departments lack personnel to manage FDA-connected device guidelines for smart room infrastructure.
- Hybrid architecture complexity:Large resort operators maintaining localized failover capabilities face dual-stack maintenance burdens.
- Certification timeline compression:Multi-jurisdictional compliance (GDPR, PCI-DSS, EU AI Act) is stretching product release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hotel and Hospitality Management Software Market |
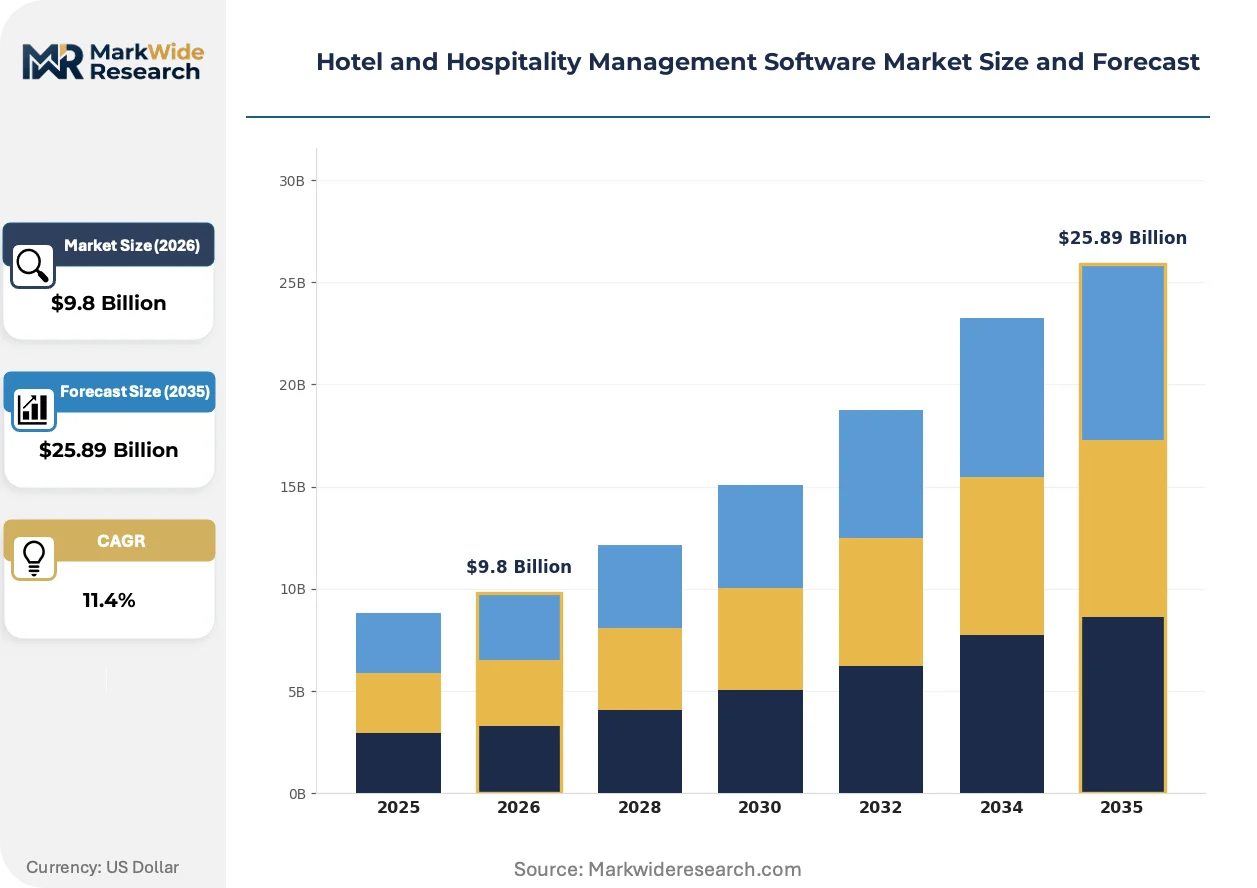
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Property Management System, Central Reservation System, Channel Management Software, Revenue Management Software Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Hotels, Restaurants, Event Venues, Travel Agencies Service Type: Support Services, Training Services, Consulting Services, Integration Services |
| Companies Covered | Amenitiz, Hotelogix, Cloudbeds, Hostaway, SiteMinder, Mews, Oracle Opera Cloud, SkyTouch Technology, eviivo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hotel and Hospitality Management Software Market Strategic Shifts
Artificial intelligence capabilities are splitting vendor roadmaps between predictive operational tools and generative guest-facing interfaces. Regulatory pressure on algorithmic transparency is accelerating investment in explainable automation.
Machine learning revenue optimization is bifurcating competitive positioning between established Property Management System incumbents and specialized Revenue Management Software attackers. Mid-sized independent hotels are adopting these tools fastest, compressing the pricing advantage previously held by enterprise chains with in-house data science teams. The technology is bifurcating vendor margins: platforms embedding native dynamic pricing capture premium subscriptions, while pure-play PMS providers face commoditization.
The EU AI Act disclosure requirements are mandating algorithmic transparency for automated guest interactions including chatbots and dynamic pricing engines. Vendors must now document decision logic for European deployments, elevating compliance engineering headcount. Boutique hotel chains in Germany and France are responding by demanding vendor-provided audit trails before contract renewal.
Buyer procurement patterns are consolidating around integrated platform suites rather than best-of-breed point solutions. Independent hotel operators are abandoning fragmented tool stacks for unified front-desk, revenue, and channel management systems. This consolidation is most visible in the United States, where property management companies are centralizing technology decisions across dispersed regional portfolios.
Hotel and Hospitality Management Software Market Segmentation
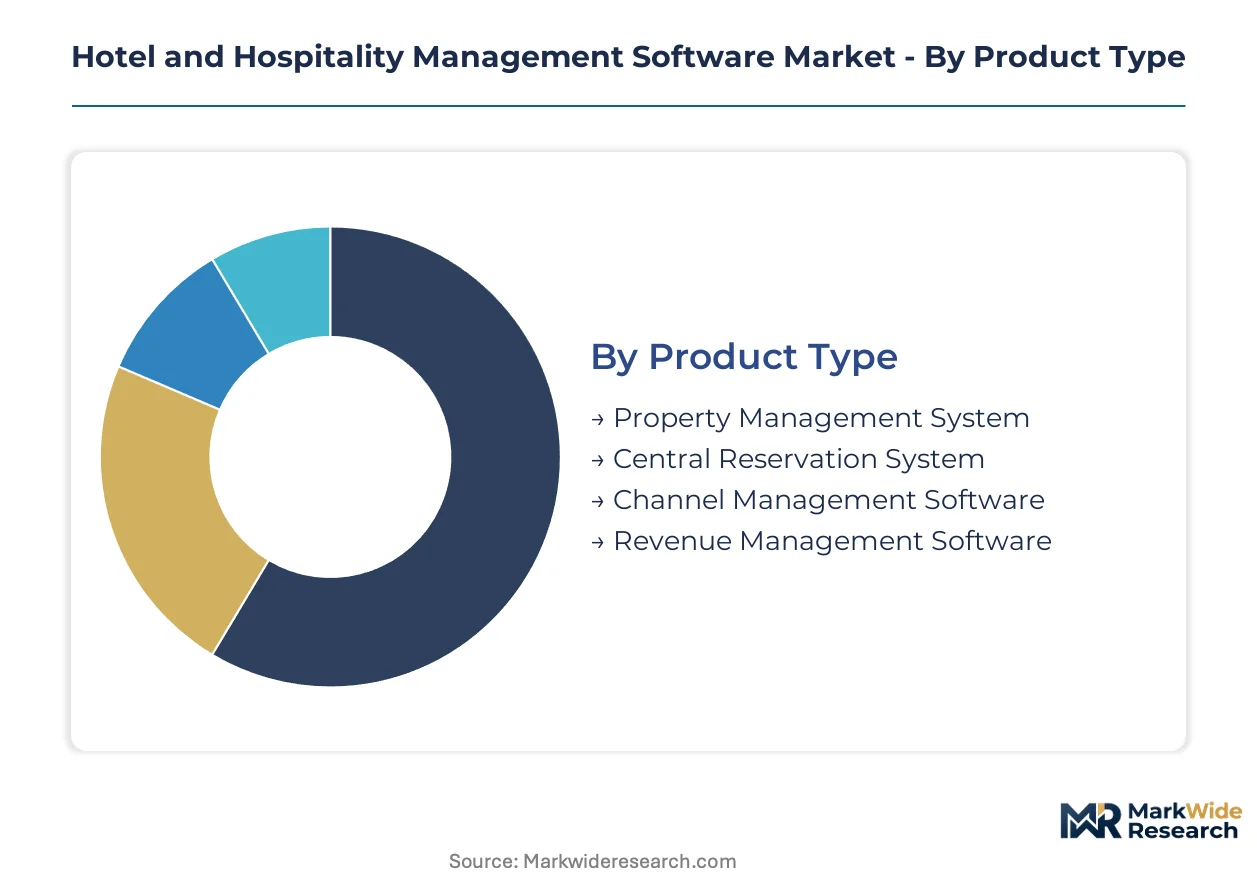
Segmentation in hospitality software reveals where procurement power concentrates and which architectures face displacement pressure from adjacent technologies. Vendors calibrate R&D allocation across these dimensions to defend margin pools against modular substitutes.
Product Type:
Property Management Systems face substitution pressure from vertically integrated hospitality platforms that embed front-desk functionality into broader operational suites.
- Property Management System:Core operational layer managing check-in, housekeeping coordination, and guest folio administration through centralized database architecture. Demand concentrates among mid-sized independent hotels in Germany and Japan where legacy on-premises replacements accelerate. PCI-DSS compliance mandates in the United States are forcing upgrade cycles for properties with outdated payment integrations.
- Revenue Management Software:Dynamic pricing engines processing demand signals, competitive rate intelligence, and booking pace data to optimize yield. Boutique hotel chains in France and independent operators in the United States are displacing static rate calendars fastest. The EU AI Act transparency requirements are elevating vendor engineering costs for algorithmic explanation features.
- Central Reservation System:Inventory aggregation hub synchronizing availability across property portfolios and distribution channels.
- Channel Management Software:Rate parity enforcement and inventory push mechanisms connecting property systems to online travel agencies.
Property Management System retains volume leadership; Revenue Management Software holds the steepest expansion curve.
Deployment:
Cost tier stratification separates premium cloud-native architectures from maintenance-heavy legacy installations that drain operational budgets.
- Cloud-Based:Multi-tenant SaaS architecture with automatic updates, elastic scaling, and centralized security patching delivered through hyperscaler infrastructure. Greenfield deployments in Tokyo and Osaka hotel clusters favor this model. GDPR data residency requirements are forcing European vendors to architect region-specific instances in Ireland and Frankfurt.
- SaaS:Subscription-licensed application delivery with API-first integration frameworks and pre-built connector libraries. Mid-sized property portfolios in the United States are consolidating procurement around unified SaaS suites rather than fragmented point solutions.
- Hybrid:Split architecture maintaining localized failover capabilities at property level with cloud-based analytics and reporting layers.
- On-Premises:Single-tenant installation requiring dedicated server infrastructure and in-house IT maintenance staff.
Cloud-Based deployment captures the majority of new implementations; SaaS is climbing fastest among procurement consolidators.
End User:
Customer type divergence shapes feature prioritization, with hotels demanding operational depth while restaurants prioritize table-turn optimization.
- Hotels:Full-service properties requiring integrated front-desk, revenue, channel, and guest communication modules operating on unified data models. Demand concentrates in the United States, Germany, and Japan as these markets modernize aging property infrastructure. Boutique hotel chains are pooling procurement to negotiate enterprise-tier pricing.
- Restaurants:Table management, kitchen display systems, and reservation platforms with POS integration requirements.
- Event Venues:Banquet and conference management with catering coordination and space utilization optimization.
- Travel Agencies:Multi-property booking interfaces and commission tracking systems for third-party distribution.
Hotels dominate absolute spend; Restaurants are expanding most quickly as dining operators digitize legacy reservation workflows.
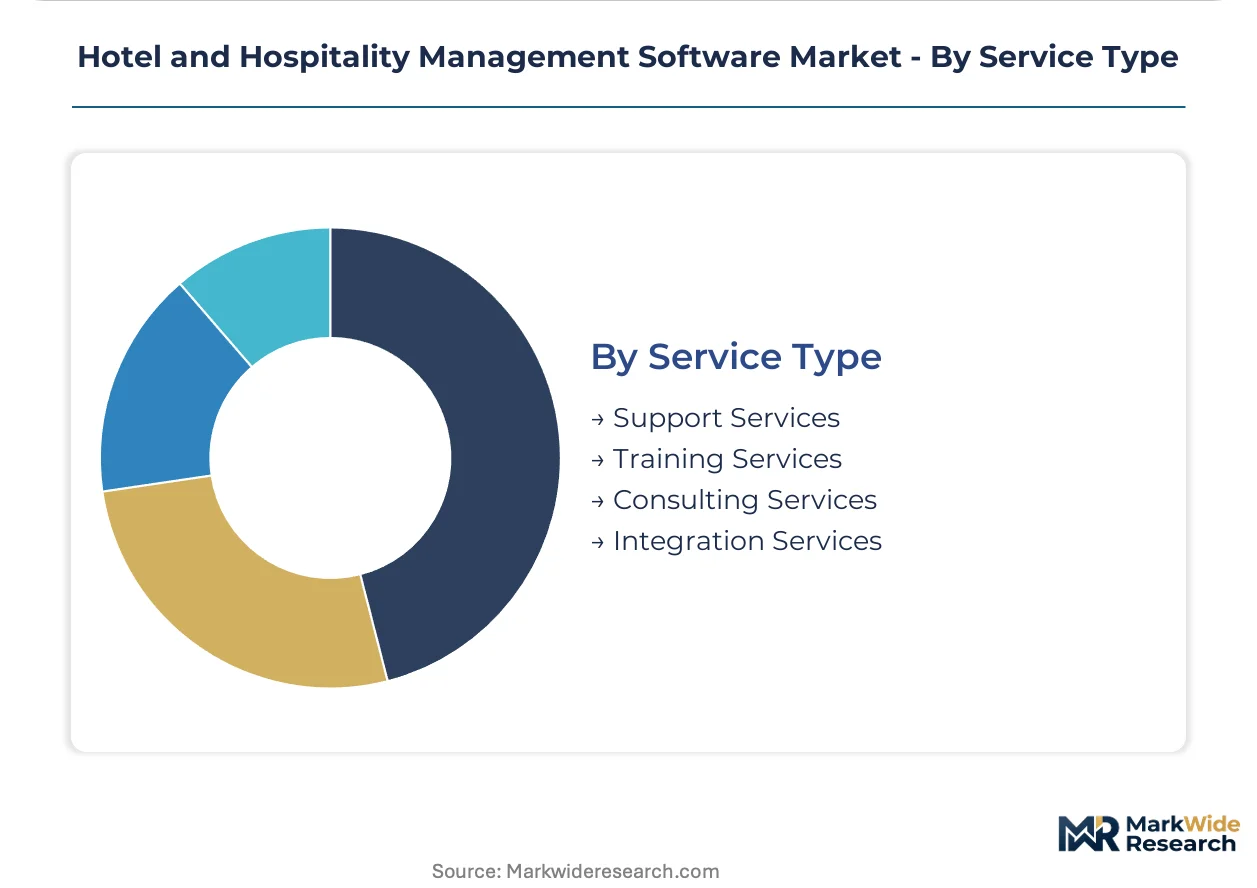
Service Type:
Margin concentration flows toward integration and consulting engagements where specialized expertise commands premium pricing against commoditized support tiers.
- Integration Services:Custom API development and middleware deployment connecting disparate property systems into unified operational workflows. Large resort operators maintaining hybrid architectures require these services most intensively. API integration complexity with legacy property systems stretches implementation timelines and inflates project budgets.
- Consulting Services:Operational workflow redesign, change management, and technology roadmap advisory for multi-property portfolios.
- Training Services:End-user onboarding, certification programs, and ongoing education for front-desk and revenue management staff.
- Support Services:Break-fix troubleshooting, version maintenance, and helpdesk operations delivered through tiered SLA structures.
Integration Services command the highest project values; Consulting Services are gaining share fastest as operators seek operational transformation guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes cluster around mid-sized independent hotels in mature markets and boutique chains pooling procurement power. Property management companies centralize technology decisions across dispersed portfolios. Modernization cycles for aging infrastructure concentrate demand in specific metropolitan clusters.
United States
Property management companies dominate procurement, centralizing SaaS decisions across regional hotel portfolios. PCI-DSS compliance mandates force upgrade cycles for outdated payment integrations. Los Angeles and Miami hotel clusters drive greenfield cloud deployments as independent operators abandon fragmented tool stacks.
Germany
Boutique hotel chains pool procurement to negotiate enterprise-tier pricing for integrated platforms. GDPR data residency requirements fragment unified guest profile architectures. Berlin and Munich property clusters accelerate replacement of legacy on-premises systems with region-specific cloud instances.
Japan
Legacy system replacement cycles open greenfield cloud deployments in aging property infrastructure. METI guidelines shape digital transformation priorities for hospitality operators. Tokyo and Osaka hotel clusters modernize operational workflows through multi-tenant SaaS adoption.
France
Boutique hotel chains demand vendor-provided audit trails before contract renewal under algorithmic transparency pressure. EU AI Act disclosure requirements elevate compliance engineering costs for automated guest interaction modules. Paris and Lyon property markets displace static rate calendars with dynamic pricing engines.
United Kingdom
Independent hotel operators consolidate procurement around unified front-desk and revenue management systems. GDPR enforcement reshapes vendor certification requirements for guest data handling. London and Edinburgh hospitality clusters drive adoption of API-connected operational platforms.
Hotel and Hospitality Management Software Market Competitive Environment
Player mix skews toward cloud-native SaaS specialists competing against legacy enterprise platform incumbents. Market structure exhibits tiered fragmentation with distinct layers serving boutique independents, mid-sized portfolios, and large multi-property chains. Three strategic archetypes dominate: integrated platform suites, pure-play property management systems, and specialized revenue optimization tools. Competitive moves center on distribution breadth expansion and direct channel connectivity investments that sustain pricing autonomy for property owners.
Within the cloud-native specialist tier, Cloudbeds and SiteMinder exemplify platform archetypes competing on channel connectivity depth. Oracle Opera Cloud occupies the enterprise-grade deployment segment through multi-property orchestration capabilities. Mews represents the European challenger model with API-first architecture positioning.
| Leading Market Players |
|---|
| Amenitiz |
| Hotelogix |
| Cloudbeds |
| Hostaway |
| SiteMinder |
| Mews |
| Oracle Opera Cloud |
| SkyTouch Technology |
| eviivo |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation agreements with hyperscalers in Ireland and Frankfurt lock in multi-year cloud infrastructure access while fixing subscription pricing visibility for SaaS vendors serving European hotel operators. These contracts tie data residency compliance costs directly to platform pricing tiers, compressing margins for vendors architecting GDPR-compliant guest profile systems.
Pricing Analysis
Cost-plus contracts indexed to hyperscaler compute rates dominate vendor procurement, with PCI-DSS certification tier and API integration depth driving price differentiation. Three-tier pricing structure across premium, standard, and economy levels separates enterprise multi-property orchestration from independent boutique deployments. Pricing pressure stems from boutique hotel chains pooling procurement to negotiate enterprise-tier SaaS rates. Mid-sized independent hotels exhibit highest price sensitivity; large resort operators with hybrid architectures show lowest sensitivity due to switching cost lock-in.
Supply Chain Analysis
Hyperscaler concentration in Ireland and Frankfurt creates a chokepoint for European cloud deployments, forcing redundant capacity reservation strategies. Software development draws from engineering talent pools in the United States, Germany, and India, with API middleware components sourced from specialized integration firms. Single-source vulnerability runs through hyperscaler dependency for multi-tenant SaaS architectures. Distribution runs through direct vendor sales teams and channel partners serving property management companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in hospitality software hinge on API interoperability consolidation, where unified guest profile architectures displace fragmented point-solution stacks across mid-sized independent hotels.
For Market Incumbents: Secure multi-property orchestration capabilities through native revenue management embedding before specialized attackers capture boutique chain procurement. Consolidate channel connectivity depth as SiteMinder and Cloudbeds expand distribution breadth. Invest in explainable algorithmic pricing engineering to satisfy EU AI Act transparency mandates ahead of contract renewal cycles in Germany and France. For New Entrants and Emerging Players: Lead with API-first architecture targeting Japan's aging property infrastructure in Tokyo and Osaka clusters, where legacy system replacement creates greenfield cloud deployment opportunities. Capture voice-activated room control integration as premium tier upsell categories emerge. Position through METI-aligned digital transformation advisory to differentiate from incumbent sales approaches. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native SaaS specialists with embedded revenue management capabilities, suggesting superior long-term viability through the analysis window. Target acquisition candidates demonstrating explainable AI pricing transparency compliance and GDPR data residency architecture. Monitor EU AI Act enforcement intensity in France and Germany as inflection indicator for vendor compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies front-desk, revenue, and channel modules for boutique hotel chains in Germany and France. |
| Acquisition of Specialist Firm | Captures dynamic pricing algorithm expertise as Revenue Management Software displaces static rate calendars. |
| Geographic Expansion | Opens greenfield cloud deployments in Tokyo and Osaka hotel clusters modernizing legacy infrastructure. |
| Strategic Partnership | Secures hyperscaler capacity reservation in Ireland and Frankfurt for GDPR-compliant data residency. |
| Product Launch | Introduces explainable algorithmic pricing transparency features satisfying EU AI Act disclosure requirements. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vendor financial disclosures, hyperscaler infrastructure reports, and regulatory filings from EMA and national data protection authorities. Primary interviews engaged hospitality technology executives, property management company procurement directors, hotel operations managers, and API integration specialists. Secondary validation drew from SEC 10-K filings, GDPR enforcement decisions, EU AI Act implementation guidance, and PCI-DSS compliance documentation. Bottom-up property-level deployment estimates triangulated against top-down vendor revenue aggregation.
Segmentation dimensions modeled span deployment architecture, property portfolio scale, integration complexity tier, and regional regulatory cluster across the projection horizon. CAGRs derived from property inventory growth, cloud migration velocity, and substitution rates for legacy on-premises systems. Forecast inputs incorporated boutique hotel consolidation patterns and EU AI Act compliance timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained cloud migration acceleration or relaxed GDPR enforcement would require recalibration. Forecasts reflect documented assumptions regarding hyperscaler capacity expansion and PCI-DSS mandate adherence. Practitioners should keep alternative scenarios live as EU AI Act transparency rule implementation and Japan METI digital transformation subsidy evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Hospitality Furniture Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
North America Restaurant Furniture Market