
 Hospitality Furniture Market | 2026-2036
Hospitality Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Hospitality Furniture Market Outlook
Engineered wood and thermally modified timber is realigning cost structures across mid-scale hospitality furniture programs. Kimball Hospitality leverages captive veneer-sourcing operations in North Carolina to sustain margin stability on large hotel rollouts. Bernhardt Hospitality anchors its competitive stance through dedicated upholstery workshops that control fabric-to-frame integration. Janus et Cie specializes in weather-resistant aluminum and synthetic weave systems for outdoor lounge collections.
Hospitality furniture encompasses contract-grade fixtures designed for commercial lodging, foodservice, and leisure environments, typically rated for cycles exceeding 100,000 uses and fabricated with fire-retardant foams, moisture-resistant substrates, and abrasion-tested textiles. Seating commands the largest share of replacement spending as restaurants refresh dining rooms on compressed schedules, while upholstered beds and headboards capture premium margin pools in boutique hotel renovations. Metal framing grows fastest in outdoor and poolside applications where powder-coated aluminum resists corrosion in humid climates.
The US Consumer Product Safety Commission enforces flammability protocols through 16 CFR Part 1633 for mattresses and TB 117-2013 for upholstered furniture, forcing importers to certify foam suppliers before customs release. The EU REACH regulation restricts formaldehyde emissions and certain flame retardants in wood-based panels, compelling Asian manufacturers to reformulate adhesives or risk market exclusion. Stakeholders must monitor evolving state-level chemical disclosure laws and building code amendments that specify recycled content thresholds for public-sector hospitality projects.
Market Dynamics
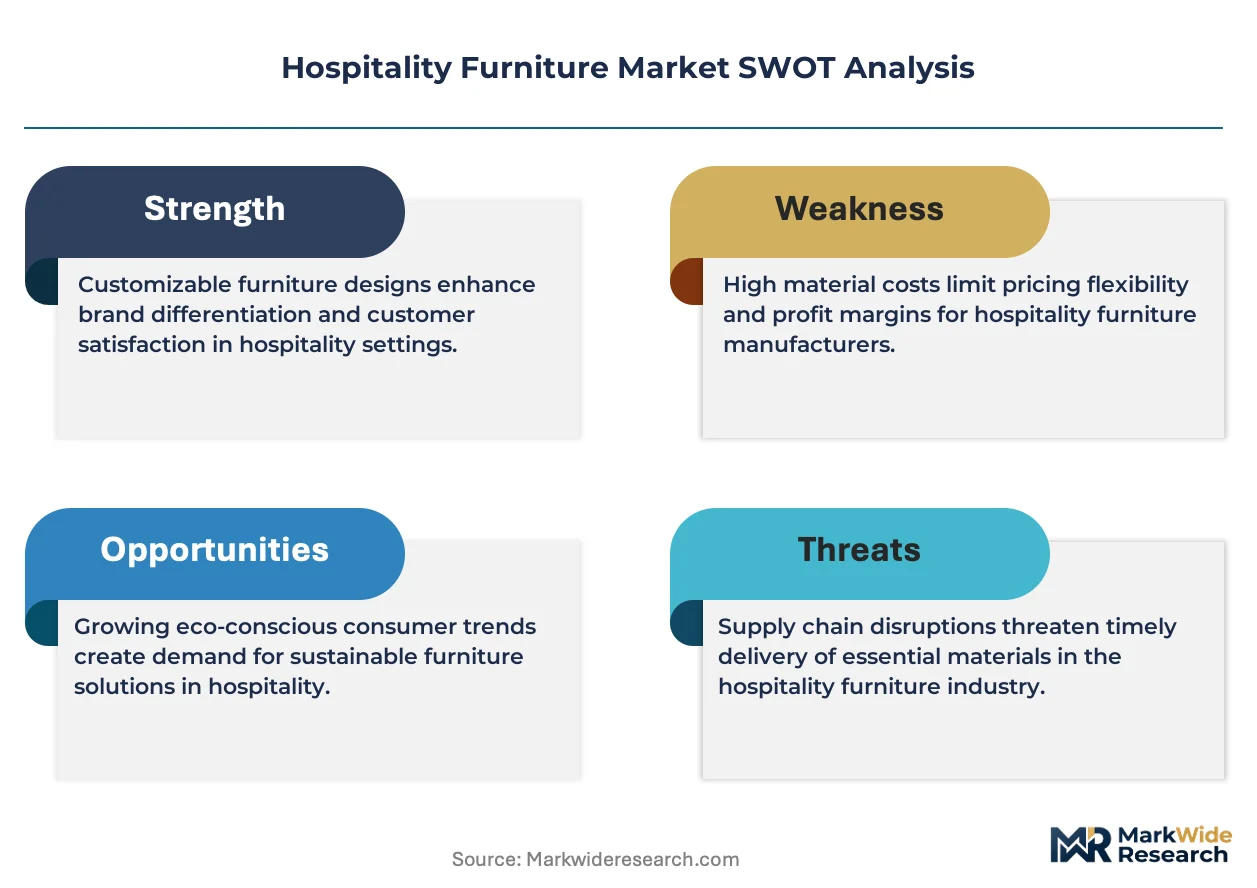
Engineered wood and thermally modified timber are compressing raw material costs for mid-scale hospitality programs while California's TB 117-2013 flammability standard forces foam reformulation across Asian export factories.
Growth Catalysts
- Boutique hotel expansion:Southeast Asian boutique chains are accelerating custom seating and casegoods procurement to differentiate guest experiences.
- REACH compliance adaptation:Vietnamese manufacturers reformulating adhesives to meet EU formaldehyde emission limits are securing preferential access to European contract buyers.
- Metal framing technology:Powder-coated aluminum systems are displacing steel in humid-climate outdoor installations due to superior corrosion resistance.
Market Restraints
- Foam certification costs:US-bound producers face elevated testing expenses to satisfy 16 CFR Part 1633 mattress flammability protocols before customs release.
- Binh Duong concentration risk:Factory clustering in this Vietnamese province creates vulnerability to regional logistics disruptions and labor pool competition.
- Adhesive substitution delays:Alternative chemistries replacing formaldehyde-based resins require extended cure times, constraining compressed lead-time programs.
Strategic Opportunities
- Weather-resistant outdoor systems:Synthetic weave and aluminum lounge collections for poolside environments remain underpenetrated in coastal Mediterranean markets.
- Recycled content mandates:Building code amendments specifying minimum recycled thresholds for public-sector hospitality projects create specification advantages for certified suppliers.
- Direct-to-hotelier digital platforms:Online specification tools are compressing traditional dealer networks in North American boutique renovation segments.
Industry Challenges
- Upholstery craft scarcity:Fabric-to-frame integration expertise is concentrating at dedicated workshops, limiting scalable quality replication.
- Multi-jurisdiction compliance timelines:Simultaneous certification for US CPSC, EU REACH, and emerging state-level chemical disclosure laws extends product development cycles.
- Moisture-resistant substrate integration:Specifying fire-retardant foams with humidity-stable cores requires complex supplier coordination across dispersed manufacturing nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospitality Furniture Market |
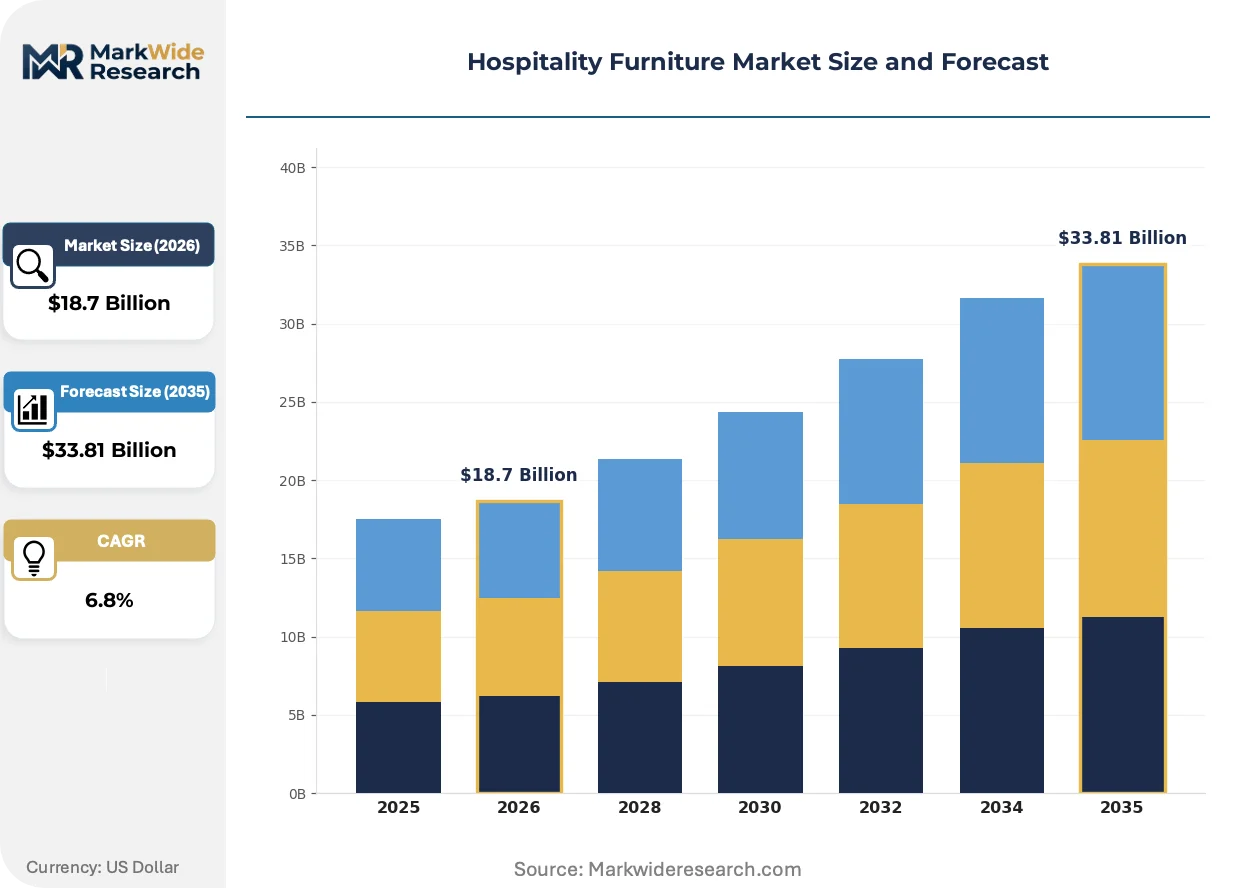
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Tables, Beds, Cabinets Material: Wood, Metal, Upholstery, Glass Usage: Restaurants, Hotels, Cafes, Lounges Design Style: Modern, Rustic, Vintage, Industrial |
| Companies Covered | Sara Hospitality USA, CenSO Home, Kimball Hospitality, Charter Furniture, PAKEN Hotel Furniture, Bernhardt Hospitality, Baker Furniture, Janus et Cie, MINGSUN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospitality Furniture Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape specification priorities across contract hospitality manufacturing, with sustainability credentials and compressed delivery windows now competing as primary order-winning criteria.
Thermally modified timber is expanding into mid-scale hotel casegoods and millwork applications as a cost-stabilizing alternative to tropical hardwoods. Boutique operators in Scandinavia and Pacific Northwest markets are specifying these materials for lobby and guestroom fixtures on 12-16 week procurement cycles. The technology is expanding into previously solid-wood-dominated segments by offering comparable dimensional stability at 30-40 percent lower landed cost.
EU REACH restrictions on halogenated flame retardants are compelling Asian panel manufacturers to migrate toward phosphorus-based and intumescent coating systems. Wood-based substrate suppliers in Vietnam and Malaysia are reformulating production lines to maintain CE marking eligibility for European contract buyers. Upholstered furniture bound for EU hospitality projects faces the most acute compliance pressure, with testing documentation now required at the component level rather than finished-goods certification.
Hotel asset managers are compressing dining room refresh cycles from 7-10 years to 3-5 years, treating seating as a consumable operational expense rather than capital investment. This behavioral shift favors domestic or near-shore fabricators capable of 8-12 week turnaround on custom dining chair programs. The pattern is most visible in US urban markets where restaurant concepts rotate aesthetics to maintain social media relevance and repeat visitation rates.
Hospitality Furniture Market Segmentation
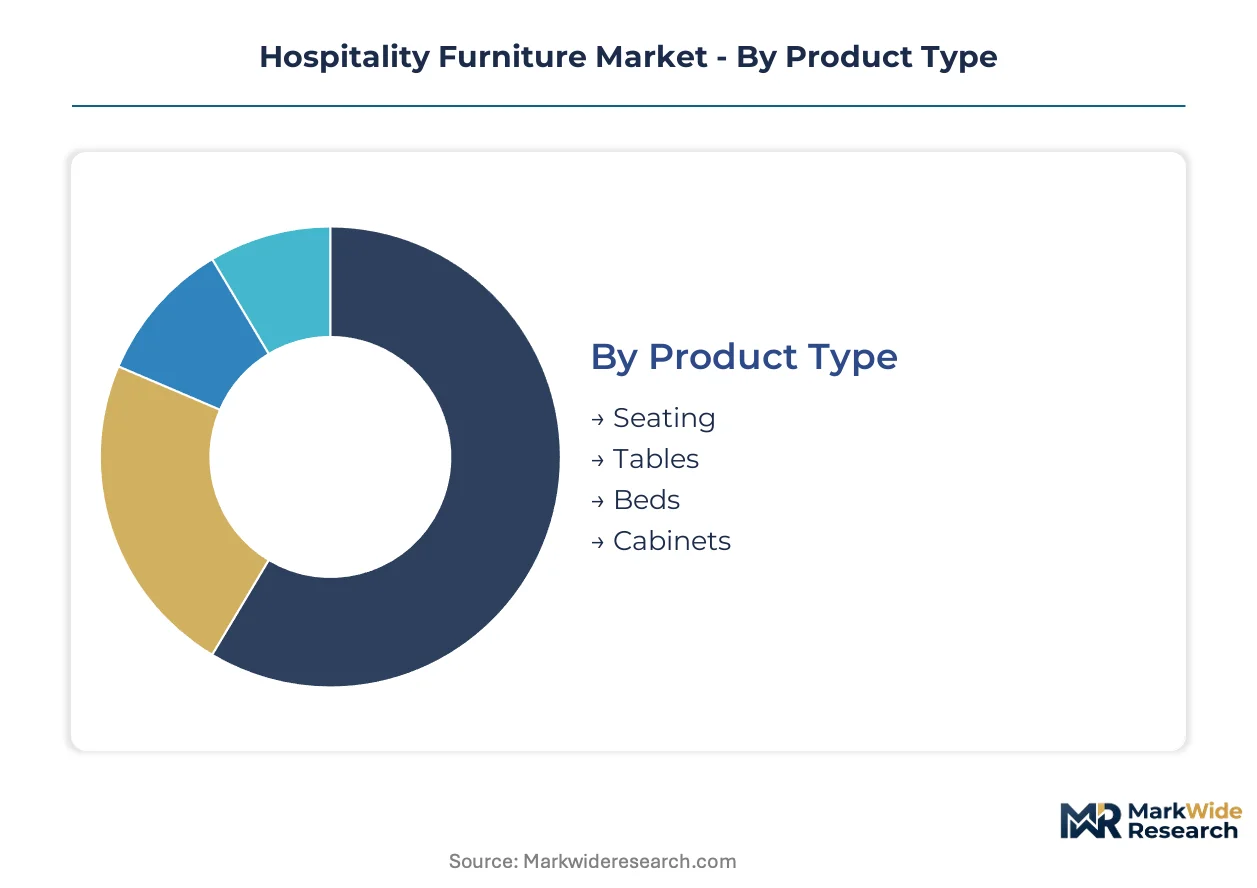
Hospitality furniture procurement splits sharply between high-volume replacement programs and premium renovation contracts, with specification requirements diverging on durability cycles, fire certification, and lead-time flexibility. Understanding these segment boundaries enables suppliers to align production capacity with margin profiles rather than chasing undifferentiated volume.
Product Type:
Seating commands disproportionate replacement frequency while beds and casegoods anchor capital-intensive renovation cycles.
- Seating:Dining chairs and lounge seating undergo the most frequent refresh cycles, with US urban restaurants now replacing seating every 3-5 years to maintain social media relevance. Compressed turnaround requirements favor domestic or near-shore fabricators capable of 8-12 week custom programs.
- Tables:Engineered wood and thermally modified timber substrates are compressing raw material costs for mid-scale hotel dining programs. Scandinavian and Pacific Northwest boutique operators specify these materials on 12-16 week procurement cycles for lobby and guestroom applications.
- Beds:Upholstered headboards and platform frames capture premium margin pools in boutique hotel renovations, with fabric-to-frame integration expertise concentrating at dedicated workshops.
- Cabinets:Casegoods and millwork applications face EU REACH formaldehyde emission restrictions, compelling Vietnamese and Malaysian panel manufacturers to reformulate adhesives for CE marking eligibility.
Mature deployment sits with seating. Newer deployment is concentrated in upholstered beds and integrated headboard systems.
Material:
Material selection determines regulatory compliance pathways and climate suitability more than aesthetic preference alone.
- Wood:Thermally modified timber offers dimensional stability comparable to tropical hardwoods at 30-40 percent lower landed cost, expanding into previously solid-wood-dominated segments across mid-scale hotel programs.
- Metal:Powder-coated aluminum systems are displacing steel in humid-climate outdoor installations, with Janus et Cie specializing in weather-resistant aluminum and synthetic weave collections for poolside environments.
- Upholstery:Fabric-to-frame integration requires complex supplier coordination across dispersed manufacturing nodes, particularly when specifying fire-retardant foams with humidity-stable cores.
- Glass:Tempered and laminated glass surfaces appear primarily in tabletop and decorative applications where scratch resistance and cleanability outweigh weight considerations.
Specification density clusters in wood and upholstery for indoor applications, while metal framing is expanding most quickly in outdoor and coastal Mediterranean markets.
Usage:
End-use environment dictates durability ratings, with foodservice applications demanding higher abrasion resistance than lodging.
- Restaurants:Dining room refresh cycles have compressed from 7-10 years to 3-5 years, with operators treating seating as consumable operational expense rather than capital investment.
- Hotels:Boutique chains across Southeast Asia are accelerating custom seating and casegoods procurement to differentiate guest experiences, sourcing from Vietnam's Binh Duong province factory clusters.
- Cafes:Quick-service and specialty coffee concepts prioritize rapid aesthetic rotation, favoring standardized designs with interchangeable upholstery for seasonal refreshes.
- Lounges:Airport and hotel lobby lounge applications require contract-grade durability exceeding 100,000 use cycles with fire-retardant foam and moisture-resistant substrate specifications.
Volume concentration remains with restaurant and hotel segments, while cafes represent the steepest expansion trajectory for standardized, quick-turn programs.
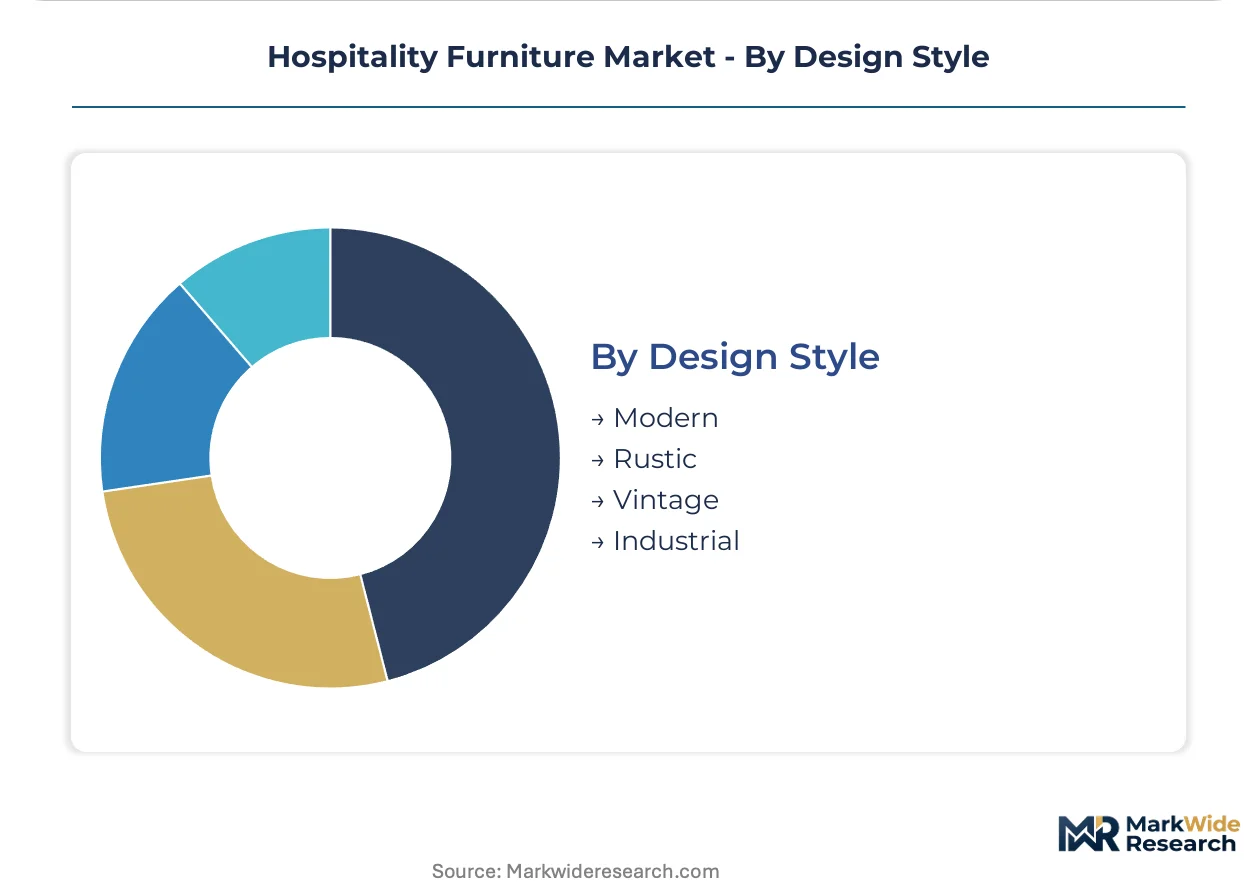
Design Style:
Aesthetic positioning correlates with geographic market maturity and renovation cycle length.
- Modern:Clean lines and minimal ornamentation dominate North American and Northern European contract specifications, aligning with compressed refresh timelines.
- Rustic:Reclaimed and distressed wood finishes concentrate in mountain resort and agritourism hospitality concepts, with thermally modified timber substituting for scarce reclaimed supply.
- Vintage:Curated antique reproductions and retro styling appear in boutique urban hotels seeking Instagram differentiation, though fabrication requires skilled craft labor that limits scalable replication.
- Industrial:Exposed metal framing and raw material honesty characterizes converted warehouse and adaptive reuse hospitality projects, with metal-wood hybrid construction dominating.
Modern styling holds established position across corporate and upscale select-service chains. Vintage and industrial aesthetics represent newer deployment concentrated in independent boutique and lifestyle hotel conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitality procurement concentrates on California's TB 117-2013 compliance requirements, while European REACH formaldehyde limits reshape Vietnamese export formulations. Factory clustering in Binh Duong province serves both regulatory regimes with compressed lead times.
United States
Boutique hotel renovations in New York and Los Angeles drive custom seating demand on 8-12 week cycles. The US Consumer Product Safety Commission enforces 16 CFR Part 1633 mattress flammability protocols, forcing foam supplier certification before customs release. North Carolina hosts captive veneer-sourcing operations that sustain margin stability on large hotel rollouts.
Germany
Scandinavian and Pacific Northwest boutique operators specify thermally modified timber for lobby fixtures on compressed procurement timelines. ECHA REACH restrictions on halogenated flame retardants compel Asian panel manufacturers to migrate toward phosphorus-based coating systems. Hamburg-based contract buyers prioritize CE marking eligibility and component-level testing documentation.
Vietnam
Binh Duong province factory clusters serve European and North American contract buyers with engineered wood and thermally modified timber programs. Manufacturers reformulating adhesives to meet EU formaldehyde emission limits secure preferential access to German and Dutch contract buyers. The province's concentration creates vulnerability to regional logistics disruptions and labor pool competition.
China
Guangdong and Zhejiang manufacturing bases supply standardized quick-turn cafe seating for seasonal refresh programs. MIIT industrial standards and GB certification requirements shape export-oriented production configurations. Yangtze River Delta fabricators specialize in metal framing systems for humid-climate outdoor installations.
United Arab Emirates
Dubai hospitality developments drive demand for weather-resistant aluminum and synthetic weave poolside collections. MOHAP product safety requirements intersect with European REACH-equivalent substance restrictions on imported furnishings. Jebel Ali industrial zones host finishing and assembly operations for Gulf Cooperation Council distribution.
Hospitality Furniture Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with upholstery craft expertise concentrating at dedicated workshops while scale-driven players dominate standardized programs. The vendor base organizes around three archetypes: captive-veneer specialists controlling raw material costs, integrated upholstery workshops managing fabric-to-frame coordination, and aluminum-system fabricators serving humid-climate outdoor applications. Competitive moves center on backward integration into veneer sourcing and geographic expansion of dedicated workshop networks.
Among US-based hospitality specialists, Kimball Hospitality and Bernhardt Hospitality occupy positions reflecting divergent strategic anchors. Kimball Hospitality exemplifies the captive-supply archetype through North Carolina veneer-sourcing operations that compress raw material cost volatility. Bernhardt Hospitality sits within the integrated-workshop tier, with dedicated upholstery facilities controlling fabric-to-frame integration. Janus et Cie represents the weather-resistant-systems specialization, anchoring competitive positioning in powder-coated aluminum and synthetic weave technologies for poolside environments.
| Leading Market Players |
|---|
| Sara Hospitality USA |
| CenSO Home |
| Kimball Hospitality |
| Charter Furniture |
| PAKEN Hotel Furniture |
| Bernhardt Hospitality |
| Baker Furniture |
| Janus et Cie |
| MINGSUN |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EU REACH-compliant and standard-grade hospitality furniture creates a 30-40 percent landed cost spread that reshapes both procurement budgets and factory investment priorities across Vietnamese and Malaysian manufacturing nodes. This bifurcation concentrates margin capture among panel suppliers who have completed adhesive reformulation, while compressing returns for producers still navigating multi-jurisdiction compliance timelines.
Pricing Analysis
Volume-margins split sharply between standardized cafe seating programs and custom boutique hotel renovations. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity and lead-time flexibility, with REACH-compliant upholstered goods commanding premium positioning. Pricing pressure stems from compressed restaurant refresh cycles treating seating as consumable operational expense. Quick-service concepts exhibit highest price sensitivity, while independent boutique hoteliers prioritize craft integration over unit cost.
Supply Chain Analysis
Domestic-content mandates in US public-sector hospitality projects are reshaping sourcing patterns toward North Carolina veneer operations and regional assembly nodes. Factory clustering concentrates in Vietnam's Binh Duong province, China's Guangdong and Zhejiang bases, and North Carolina captive-sourcing facilities. Raw material dependencies center on thermally modified timber, fire-retardant foam formulations, and powder-coated aluminum systems. Single-source vulnerability sits with Binh Duong logistics concentration. Distribution runs through contract dealer networks, with direct-to-hotelier digital platforms gaining share in boutique renovation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as multi-jurisdiction compliance costs and upholstery craft scarcity force sub-scale fabricators toward exit or acquisition. Regulatory complexity acts as the primary filter eliminating players lacking dedicated certification resources.
For Market Incumbents: Lock in backward integration into veneer sourcing to sustain margin stability against raw material volatility, as Kimball Hospitality has demonstrated through North Carolina operations. Expand dedicated upholstery workshop networks to capture fabric-to-frame integration premiums before craft scarcity worsens. Defend against emerging digital platform disintermediation by embedding specification tools within existing dealer relationships.
For New Entrants and Emerging Players: Begin with weather-resistant aluminum and synthetic weave systems for coastal Mediterranean poolside applications, where established penetration remains limited and specification cycles favor new suppliers. Target standardized quick-turn cafe seating programs where aesthetic rotation frequency creates recurring demand windows. Pursue direct-to-hotelier digital specification platforms as the primary go-to-market angle, compressing traditional dealer markups in boutique renovation segments.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated upholstery workshops given fabric-to-frame expertise concentration and boutique hotel renovation demand acceleration. Long-term viability favors archetypes with captive raw material positions and multi-jurisdiction certification infrastructure already deployed. Watch REACH adhesive reformulation completion rates among Vietnamese panel suppliers as the inflection signal for preferential European contract access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Veneer Sourcing | Kimball Hospitality's North Carolina operations demonstrate margin stability on large hotel rollouts. |
| Dedicated Upholstery Workshop Expansion | Bernhardt Hospitality controls fabric-to-frame integration quality through captive craft concentration. |
| REACH Adhesive Reformulation | Vietnamese manufacturers securing CE marking eligibility gain preferential access to German contract buyers. |
| Weather-Resistant Outdoor System Development | Janus et Cie anchors positioning in powder-coated aluminum for humid-climate poolside installations. |
| Direct-to-Hotelier Digital Platform Launch | Online specification tools compress traditional dealer networks in North American boutique renovation segments. |
Study Parameters
Trade association filings, customs and import records, and hospitality procurement databases formed the secondary backbone, supplemented by SEC 10-K disclosures from publicly listed contract manufacturers. Primary interviews with hotel asset managers, restaurant procurement directors, furniture factory operations heads, and contract dealer network principals provided demand-side and supply-side validation. Bottom-up and top-down triangulation cross-checked shipment volumes against end-use installation timelines.
Bottom-up modeling aggregated product-type, material, and usage segment volumes across the projection horizon, while top-down analysis validated aggregate market scale against macro hospitality construction indicators. Segmentation dimensions included product type, material category, end-use environment, and design style tier. CAGRs were derived from historical replacement cycle compression patterns and regulatory compliance cost trajectories. Forecast inputs incorporated thermally modified timber substitution rates and boutique hotel expansion pipelines.
Underlying measurement precision varies by segment; standardized cafe seating carries tighter precision than custom boutique renovations due to more homogeneous specification patterns. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and raw material cost stability. Supply chain disruption events or accelerated state-level chemical disclosure laws could revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Airport Lounge Operation Services Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
US Catering Services Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Saudi Arabia Wedding Services Market
Hospitality Management and Services
US Wedding Services Market