
 Indonesia Hospitality Real Estate Market | 2026-2036
Indonesia Hospitality Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Hospitality Real Estate Market Foresight
The gap between premium branded assets and unflagged commodity lodging is expanding across Indonesian hospitality real estate. Marriott International leverages its management contract expertise to dominate Jakarta's five-star pipeline. Ciputra Development anchors resort development in Surabaya and secondary cities through integrated township models. Archipelago International differentiates via its homegrown portfolio spanning midscale to lifestyle segments.
Indonesia hospitality real estate comprises income-generating commercial properties designed for temporary accommodation, typically featuring room inventories from fifty to five hundred keys with food and beverage, meeting, and recreational amenities. These assets generate returns through nightly room revenue, ancillary services, and long-term land value appreciation in tourism corridors. Hotels and resorts command the largest share of institutional capital deployment, while serviced apartments capture extended-stay demand from expatriate corporate clients in Jakarta and Bali. Boutique lodging represents the fastest-growing property type, though REITs remain nascent due to regulatory complexity and shallow domestic capital markets.
Indonesia's Ministry of Tourism and Creative Economy coordinates investment incentives with BPN, the national land agency, which governs foreign ownership restrictions through Hak Guna Bangunan titles. Local zoning regulations and provincial spatial plans determine where hospitality development proceeds, directly constraining supply in high-demand zones like Bali's southern peninsula. Stakeholders must monitor pending omnibus law revisions affecting land acquisition timelines and the central bank's macroprudential rules for property sector lending.
Market Dynamics
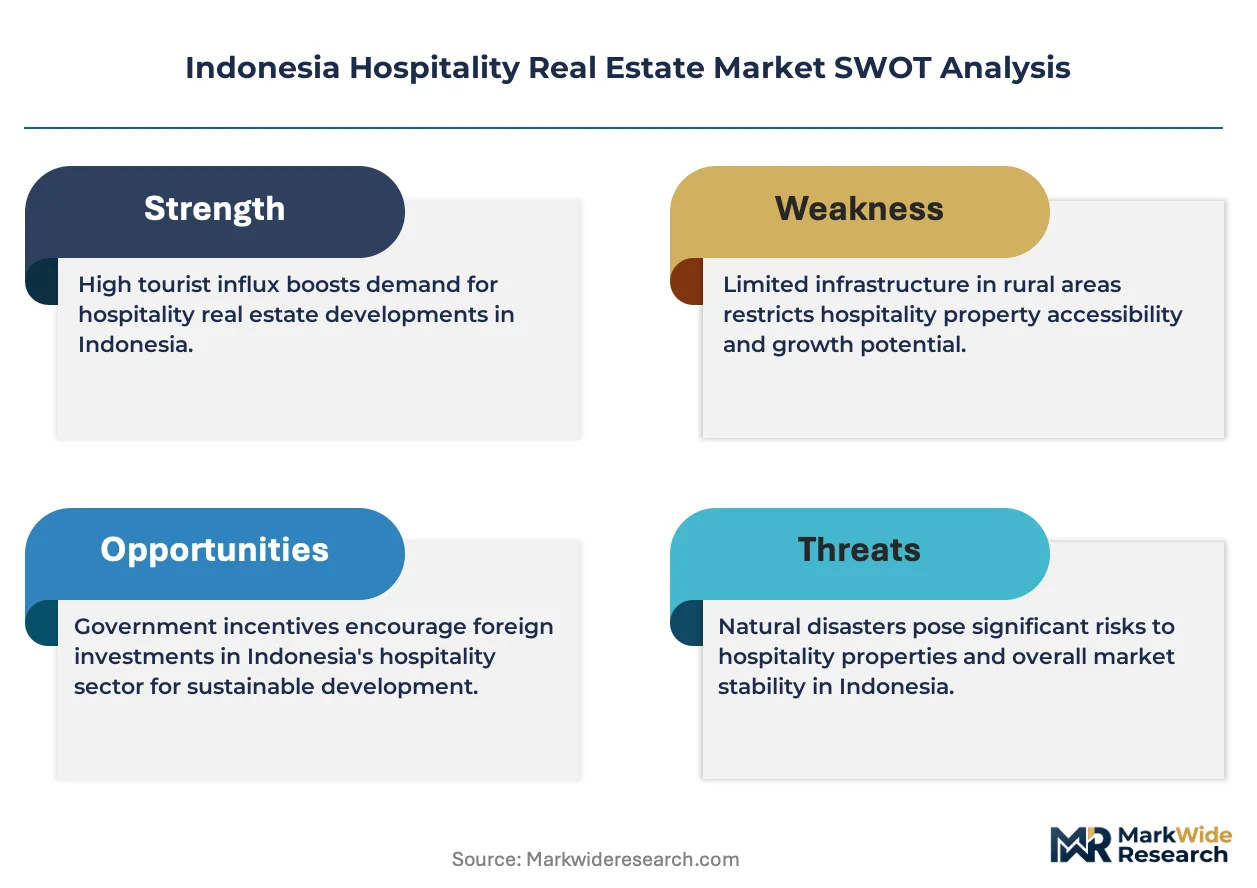
Indonesia's hospitality real estate sector is experiencing a fundamental repricing of land and construction costs as foreign ownership liberalization under Hak Guna Bangunan reforms attracts institutional capital. This capital influx is compressing development timelines and elevating design standards across Jakarta's CBD and Bali's southern corridor.
Growth Catalysts
- Ministry of Tourism and Creative Economy licensing reforms:Streamlined foreign investment approvals reduce project gestation periods from thirty-six to eighteen months. International developers now secure permits through single-window clearance mechanisms.
- Extended-stay corporate demand:Expatriate assignments in Jakarta's financial services and mining headquarters drive serviced apartment absorption. Operators capture thirty-plus night average length of stay versus seven for transient hotels.
- Secondary city infrastructure:New toll road connections between Surabaya and Malang unlock greenfield resort sites. Provincial governments compete through tax holiday packages for hospitality anchor investments.
Market Restraints
- Construction input cost volatility:Imported steel and aluminum pricing tied to Rupiah-USD exchange rate swings disturbs project feasibility modeling. Developers face margin erosion on fixed-price contracts.
- Land banking concentration:Ciputra Group and central Javanese conglomerates control prime parcels in Yogyakarta and Bandung corridors. New entrants pay scarcity premiums or accept peripheral locations.
- Shallow domestic capital markets:Absence of hospitality-focused REIT vehicles forces reliance on bilateral bank lending. BI macroprudential rules cap property sector credit expansion.
Strategic Opportunities
- Lombok Mandalika special economic zone:Government-backed infrastructure commitments position the island as Bali overflow destination. Integrated resort operators secure fifty-year concession terms.
- Wellness tourism convergence:Traditional Javanese healing practices merge with clinical diagnostics and longevity programming. Medical retreat operators target ASEAN high-net-worth segments.
- Digital nomad visa pathway:Ministry of Law and Human Rights residence permits enable thirty-day to six-month stays. Co-living operators in Ubud and Canggu retrofit villa inventory for monthly subscription models.
Industry Challenges
- Specialized asset management talent scarcity:Revenue management and food and beverage optimization expertise concentrates in Jakarta. Secondary city properties operate below GOPPAR benchmarks.
- Legacy PMS integration complexity:Independent hotels run on fragmented software stacks. Cloud migration requires capital outlay and operational disruption during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Hospitality Real Estate Market |
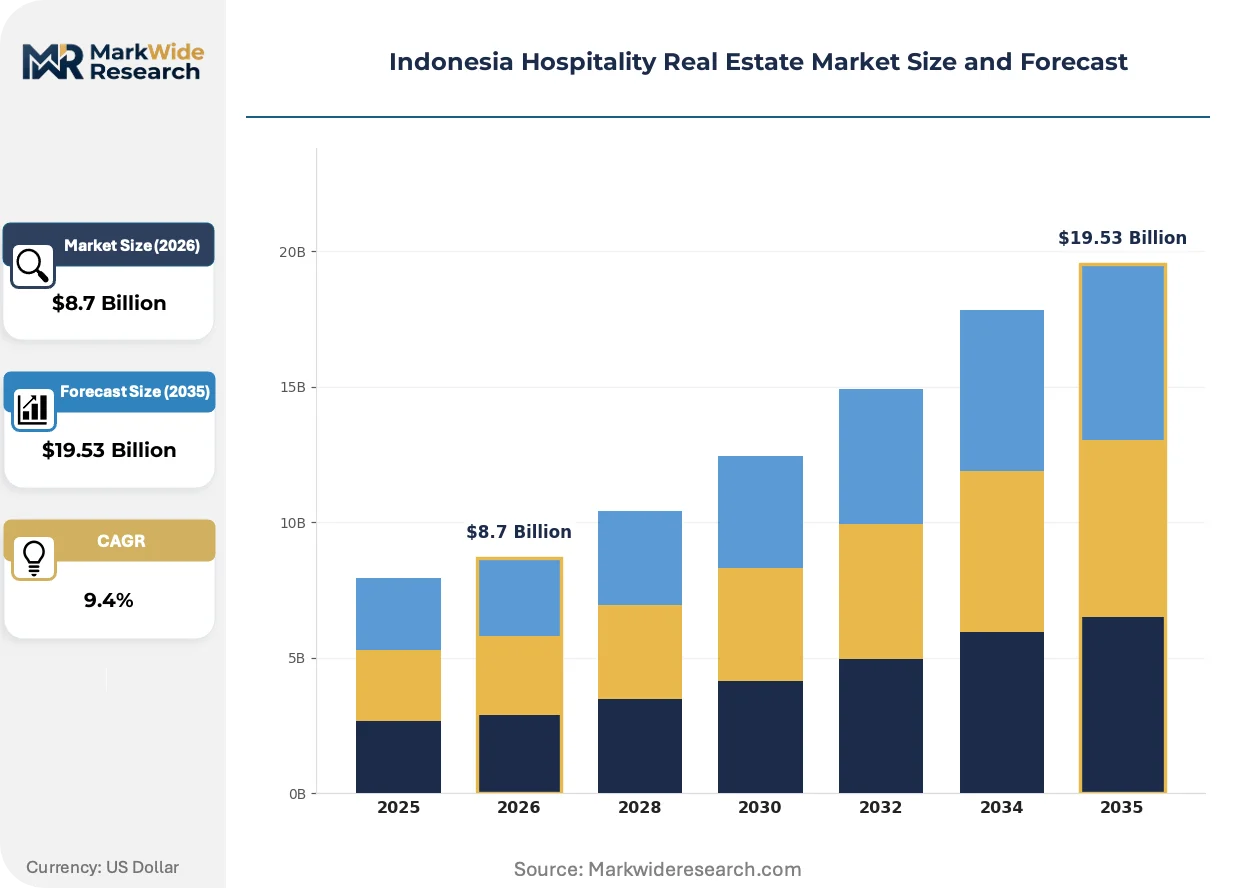
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Hotels, Resorts, Serviced Apartments, Boutique Lodging Investment Strategy: Equity Financing, Joint Ventures, Asset Management, REITs Client Type: Corporate Clients, Leisure Travelers, Event Planners, Government Contracts Operational Model: Franchise, Management Contract, Owner-Operator, Independent |
| Companies Covered | PT Lippo Karawaci Tbk, PT Agung Podomoro Land Tbk, Ciputra Development, Pakuwon Jati Tbk, PT Surya Semesta Internusa Tbk, Marriott International, Hilton Worldwide, The Ascott Limited, Archipelago International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Hospitality Real Estate Market Shifts & Advancements
Technology deployment across Indonesian hospitality assets is accelerating operational consolidation and guest experience personalization. Three interconnected developments are restructuring competitive positioning and capital allocation priorities.
Smart building management systems are unifying energy, security, and housekeeping workflows through centralized IoT dashboards. Premium Jakarta developments deploy these platforms to reduce utility costs by double-digit percentages. This convergence is compressing the performance gap between institutional-grade assets and independent competitors.
Ministry of Environment and Forestry green building mandates now require LEED or GREENSHIP certification for developments exceeding ten thousand square meters. Compliance adds six to nine months to design phases but unlocks preferential BI refinancing rates. Bali resort developers absorb these timelines to secure long-dated competitive positioning.
Corporate travel managers now mandate centralized booking platforms with sustainability scoring and duty-of-care tracking. This procurement evolution displaces traditional travel agency relationships in Jakarta's banking and energy sectors. International hotel chains capture disproportionate share through direct connectivity to enterprise expense management systems.
Indonesia Hospitality Real Estate Market Segmentation
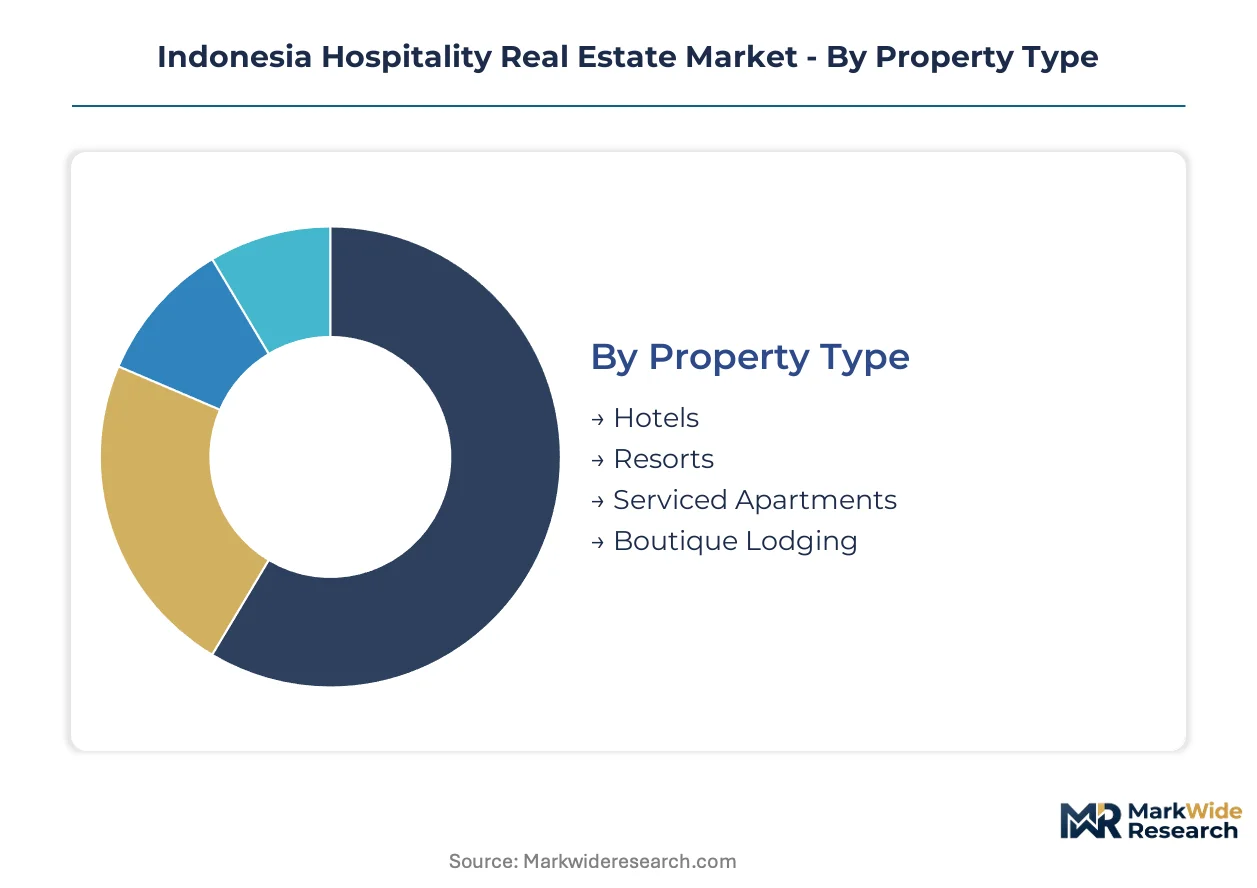
Segmentation in Indonesian hospitality real estate reveals how capital deployment, risk appetite, and operational control preferences split across investor and operator archetypes. Understanding these fault lines clarifies where institutional capital concentrates versus where entrepreneurial entry remains viable.
Property Type:
Capital intensity varies sharply across property types, with integrated resorts demanding the heaviest land assembly and amenity build-out commitments.
- Hotels:Purpose-built structures with standardized room configurations and centralized food and beverage operations dominate Jakarta's CBD and Surabaya's commercial corridors. Institutional investors favor this segment for its liquid transaction market and predictable cash flow profiles. Ministry of Tourism licensing reforms have compressed development timelines for branded properties in these locations.
- Resorts:Sprawling footprints incorporating multiple accommodation tiers, extensive recreational facilities, and experiential programming anchor Bali's southern peninsula and Lombok's emerging Mandalika zone. These assets require patient capital cycles and benefit from Hak Guna Bangunan title reforms enabling longer-dated foreign investment horizons.
- Serviced Apartments:Hybrid residential-hospitality products with kitchen-equipped units and reduced service intensity capture extended-stay demand from mining and financial services expatriates in Jakarta.
- Boutique Lodging:Small-format properties emphasizing design differentiation and localized guest experiences proliferate in Ubud and Canggu, often retrofitting existing villa inventory.
Hotels absorb the bulk of installed capacity; boutique lodging is expanding most quickly.
Investment Strategy:
Risk-return profiles diverge based on whether investors seek operational control, passive yield, or development-stage upside.
- Equity Financing:Direct capital deployment into development or acquisition vehicles offers full ownership and exit optionality. Indonesian conglomerates and regional sovereign wealth funds deploy this strategy for trophy assets in Jakarta and Bali, absorbing construction cost volatility in exchange for land value appreciation exposure.
- Joint Ventures:Partnership structures pairing foreign operators with local landholders mitigate Hak Guna Bangunan ownership restrictions while distributing construction and operational risk. These vehicles dominate greenfield resort development where land banking concentration among central Javanese groups forces collaboration.
- Asset Management:Third-party oversight of existing properties generates fee income without balance sheet exposure. International operators leverage this model to expand flagged presence where capital deployment constraints limit direct investment.
- REITs:Pooled vehicles for hospitality real estate exposure remain structurally constrained by shallow domestic capital markets and regulatory complexity around foreign ownership of underlying titles.
Joint ventures capture the majority of new development activity; asset management is gaining share fastest among foreign operators seeking scale without capital commitment.
Client Type:
Demand composition determines pricing power, length of stay, and ancillary revenue capture potential.
- Corporate Clients:Contracted room blocks and negotiated rate structures from banking, energy, and mining headquarters anchor weekday occupancy in Jakarta's CBD. These accounts demand centralized booking platforms with duty-of-care tracking and sustainability scoring, favoring international chains with direct enterprise system connectivity.
- Leisure Travelers:Discretionary demand concentrates in Bali and Lombok, with booking patterns increasingly mediated by online travel agencies and direct-to-consumer loyalty programs. This segment drives resort development and commands rate premiums during peak seasons.
- Event Planners:Conference and wedding demand requires dedicated meeting space inventory and catering scale, concentrating in larger-format hotels with ballroom capacity.
- Government Contracts:Official travel and state-function hosting provides base-load demand with payment security but compressed margins and bureaucratic procurement cycles.
Leisure travelers generate the highest rate premiums; corporate clients provide the most predictable revenue base.
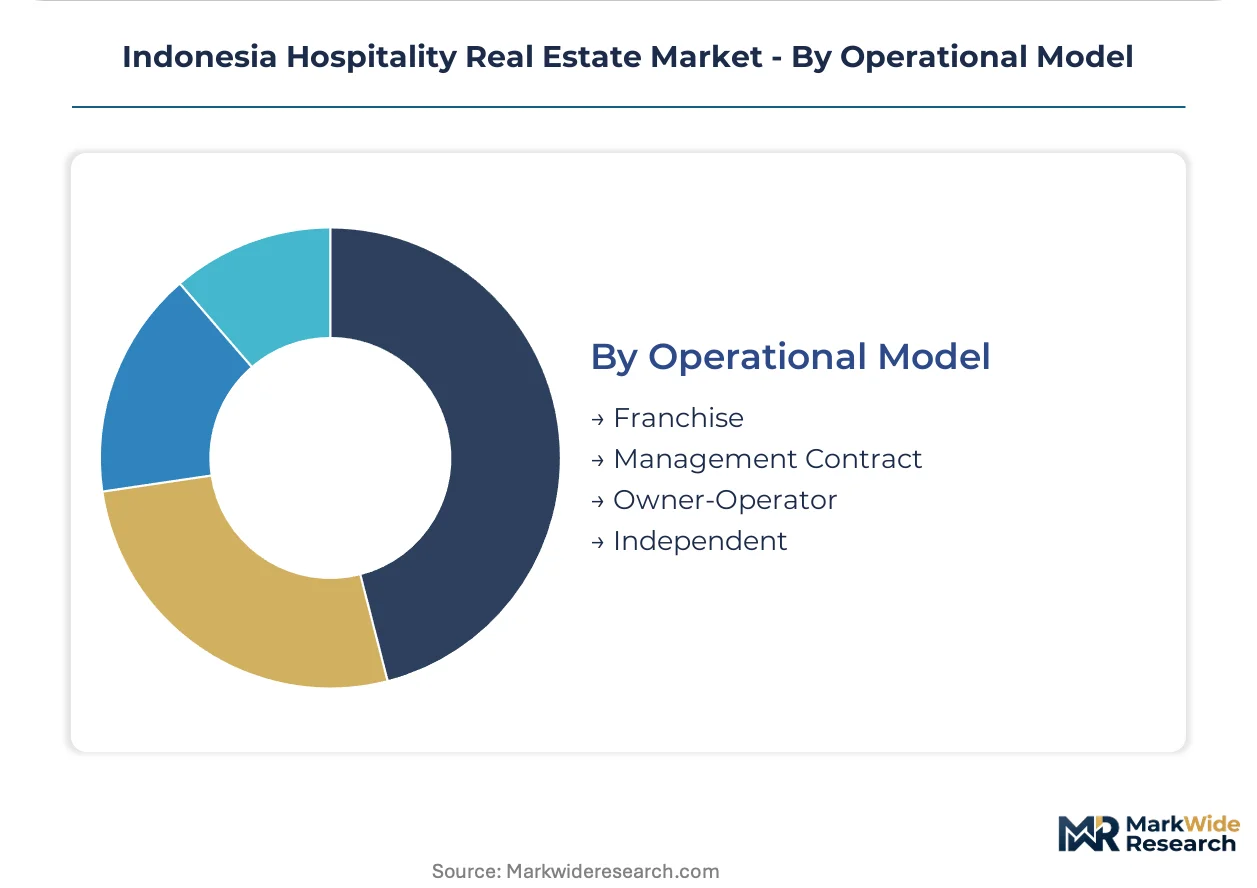
Operational Model:
Control over brand standards, revenue management, and capital allocation splits across four distinct governance structures.
- Management Contract:Owners retain asset ownership while delegating operational control to branded operators in exchange for base and incentive fees. Marriott International dominates Jakarta's five-star pipeline through this structure, capturing upside from rate premiums without capital at risk.
- Franchise:License agreements granting access to reservation systems and brand standards with owner-operated execution. Archipelago International deploys this model for midscale expansion across secondary cities where local knowledge outweighs operational complexity.
- Owner-Operator:Vertically integrated structures combining capital commitment with direct operational control. Ciputra Development anchors this approach in Surabaya and integrated township projects, capturing development margin and operational yield.
- Independent:Unflagged properties relying on direct booking channels and location-based demand, prevalent in boutique lodging and legacy assets yet facing compression from branded distribution power.
Management contracts command the greatest share of premium supply; owner-operator structures retain dominance in secondary city integrated developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta anchors Indonesia's hospitality real estate investment flows through its central business district luxury segment and integrated township developments. The Ministry of Tourism and Creative Economy coordinates licensing reforms with provincial governments to compress project timelines across priority corridors.
Jakarta Metropolitan Region
Corporate headquarters in banking and mining sectors drive serviced apartment absorption in the CBD and South Jakarta sub-markets. Bank Indonesia macroprudential rules cap property sector credit expansion while permitting preferential refinancing for green-certified developments. The SCBD and Mega Kuningan clusters concentrate five-star hotel pipelines under management contract structures.
Bali Island
Leisure traveler demand from ASEAN and Australian source markets accelerates resort development across the southern peninsula and Ubud hinterland. Ministry of Environment and Forestry green building mandates require LEED or GREENSHIP certification for developments exceeding ten thousand square meters. Canggu and Seminyak sub-districts host boutique lodging retrofitting of existing villa inventory for digital nomad visa holders.
Lombok Island
Mandalika special economic zone infrastructure commitments position the island as Bali overflow destination for integrated resort operators. Government-backed concession terms extend to fifty years for anchor investments meeting employment and local content thresholds. Kuta and Senggigi corridors attract greenfield development from foreign operators seeking longer-dated investment horizons.
Surabaya and East Java Corridor
Secondary city demand concentrates in Surabaya's commercial zones and the emerging Malang resort corridor connected by toll road infrastructure. Provincial governments compete through tax holiday packages for hospitality anchor investments in integrated township models. Pakuwon Jati and Ciputra Development control prime parcels through legacy land banking positions.
Bandung and West Java Highlands
Weekend leisure demand from Jakarta drives hospitality development in the Lembang and Dago Pakar mountain resort zones. Local zoning regulations under provincial spatial plans constrain supply in high-demand areas while permitting expansion in designated tourism corridors. Heritage villa conversions and wellness retreat programming target domestic high-net-worth segments.
Indonesia Hospitality Real Estate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across brand tier and operational control dimensions in Indonesian hospitality real estate. The market structures around three distinct tiers: international branded operators capturing Jakarta CBD premiums, integrated township developers controlling secondary city land banks, and homegrown midscale specialists expanding through franchise networks. Consolidation pressures favor management contract structures for foreign capital and joint ventures for greenfield resort development. Strategic moves concentrate on portfolio diversification into serviced apartments and wellness programming.
Within the integrated development tier, Ciputra Development exemplifies vertical control spanning land assembly through operational yield in Surabaya township projects. Among international operators, Marriott International anchors premium positioning through management contract expertise without capital at risk. Archipelago International occupies the homegrown specialist position, deploying franchise structures for midscale expansion across secondary cities where local market knowledge outweighs operational complexity. These three archetypes represent the dominant competitive configurations shaping capital deployment and operational control preferences across Indonesian hospitality real estate.
| Leading Market Players |
|---|
| PT Lippo Karawaci Tbk |
| PT Agung Podomoro Land Tbk |
| Ciputra Development |
| Pakuwon Jati Tbk |
| PT Surya Semesta Internusa Tbk |
| Marriott International |
| Hilton Worldwide |
| The Ascott Limited |
| Archipelago International |
| Others |
Supply & Pricing Matrix
Corporate travel managers mandating centralized booking platforms with sustainability scoring and duty-of-care tracking are forcing supply-side consolidation toward branded operators with direct enterprise connectivity, compressing margins for independent properties while elevating rate premiums for certified assets.
Pricing Analysis
Value-based pricing anchored to GOPPAR performance and land value appreciation exposure dominates institutional-grade transactions. Three-tier pricing structure across luxury branded, select-service, and unflagged economy assets reflects certification tier and management contract prestige. Pricing pressure stems from imported construction input volatility tied to Rupiah-USD exchange rate swings, eroding feasibility on fixed-price contracts. Corporate clients exhibit lowest price sensitivity given duty-of-care mandates, while leisure travelers through OTAs drive compression in unflagged inventory.
Supply Chain Analysis
GREENSHIP and LEED certification gating now constrains supplier qualification for developments exceeding ten thousand square meters, extending design phases. Construction inputs draw from China, South Korea, and domestic Indonesian sources for steel, aluminum, and finishing materials. Single-source vulnerability concentrates in imported MEP equipment and specialty hospitality FF&E. Distribution runs through bilateral bank lending channels with BI macroprudential caps, supplemented by sovereign wealth and conglomerate balance sheet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesian hospitality real estate is transitioning from legacy independent operations toward smart building management systems and cloud-native property management platforms, with IoT-enabled energy optimization displacing fragmented software stacks.
For Market Incumbents: Anchor management contract dominance in Jakarta's CBD through direct enterprise system connectivity, while absorbing GREENSHIP certification timelines to secure preferential BI refinancing rates. Defend against boutique lodging encroachment by retrofitting select inventory for digital nomad visa holders. Prioritize vertical integration into serviced apartments to capture extended-stay mining and financial services demand. For New Entrants and Emerging Players: The midscale price-point gap between Archipelago International's franchise network and international branded premiums offers white-space entry through localized lifestyle positioning. Target Lombok Mandalika's fifty-year concession terms before land banking concentration locks out greenfield access. Pursue wellness tourism convergence with Javanese healing programming to differentiate from commodity resort supply. For Investors and Strategic Acquirers: Re-rating potential sits with integrated township developers given provincial tax holiday competition and toll road infrastructure unlocking secondary city corridors. Long-term viability favors patient capital cycles aligned with Hak Guna Bangunan reform horizons. Monitor BI macroprudential rule relaxation as inflection signal for credit expansion capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building Management Deployment | IoT-enabled energy optimization reduces utility costs by double-digit percentages for premium Jakarta developments. |
| GREENSHIP Certification Investment | Compliance unlocks preferential Bank Indonesia refinancing rates for institutional-grade assets. |
| Serviced Apartment Portfolio Expansion | Captures thirty-plus night average length of stay from mining and financial services expatriates. |
| Digital Nomad Visa Inventory Retrofit | Co-living operators in Ubud and Canggu convert villa stock to monthly subscription models. |
| Lombok Mandalika Concession Securement | Fifty-year government-backed terms position anchor investments for Bali overflow demand. |
Research Methodology
Independent corroboration across hospitality asset managers, Ministry of Tourism licensing officials, and Bank Indonesia policy officers underwrites the qualitative findings. Primary interviews with resort developers, hotel operators, and institutional investors combined with secondary validation from BPN land registry data, Ministry of Environment and Forestry green building mandates, and provincial spatial plan documents. Bottom-up property-level absorption analysis triangulates against top-down capital flow estimates from sovereign wealth and conglomerate deployment disclosures.
Comparable historical reference periods across branded and unflagged asset performance anchored the forecast window to observed GOPPAR trajectories and land value appreciation cycles. Segmentation dimensions modeled include property type, investment strategy, client type, and operational model with regional regulatory cluster variations. CAGRs were derived from supply-constrained demand growth in priority corridors and construction timeline compression under licensing reforms. Forecast inputs incorporate Rupiah exchange rate volatility assumptions and macroprudential credit expansion limits.
Inputs from hospitality operators and provincial licensing authorities were available through the study window; gaps in forward-looking land banking transaction data introduce uncertainty bands around supply elasticity assumptions. Forecasts reflect documented assumptions regarding infrastructure completion timelines and foreign ownership liberalization continuity. A model refresh is warranted upon material change in Bank Indonesia property sector lending rules or omnibus law land acquisition revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Hotel Ice Dispensers Market