
 Turkey Hospitality Market | 2026-2036
Turkey Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Hospitality Market Insights
Multi-source procurement of hotel management services is shifting as Turkish owners diversify beyond single-brand affiliations. Marriott International leverages its Bonvoy loyalty ecosystem to sustain repeat bookings across Istanbul and Antalya properties. Rixos Hotels anchors its competitive position through all-inclusive resort concepts along the Mediterranean coastline. Dedeman Hotels & Resorts International specializes in convention-oriented properties that dominate Ankara's business-travel segment.
Turkey hospitality encompasses lodging, food service, and guest-experience operations governed by star-rating classifications from the Ministry of Culture and Tourism, with properties evaluated on room standards, amenity breadth, and service protocols. The sector's primary commercial purpose centers on accommodating domestic and inbound visitors while generating foreign-exchange revenue and regional employment. Leisure travelers represent the most substantial customer-type segment, with coastal resorts capturing premium rate structures during peak summer months. Vacation rentals are expanding fastest among property types, driven by platform-enabled supply and extended-stay demand from remote workers.
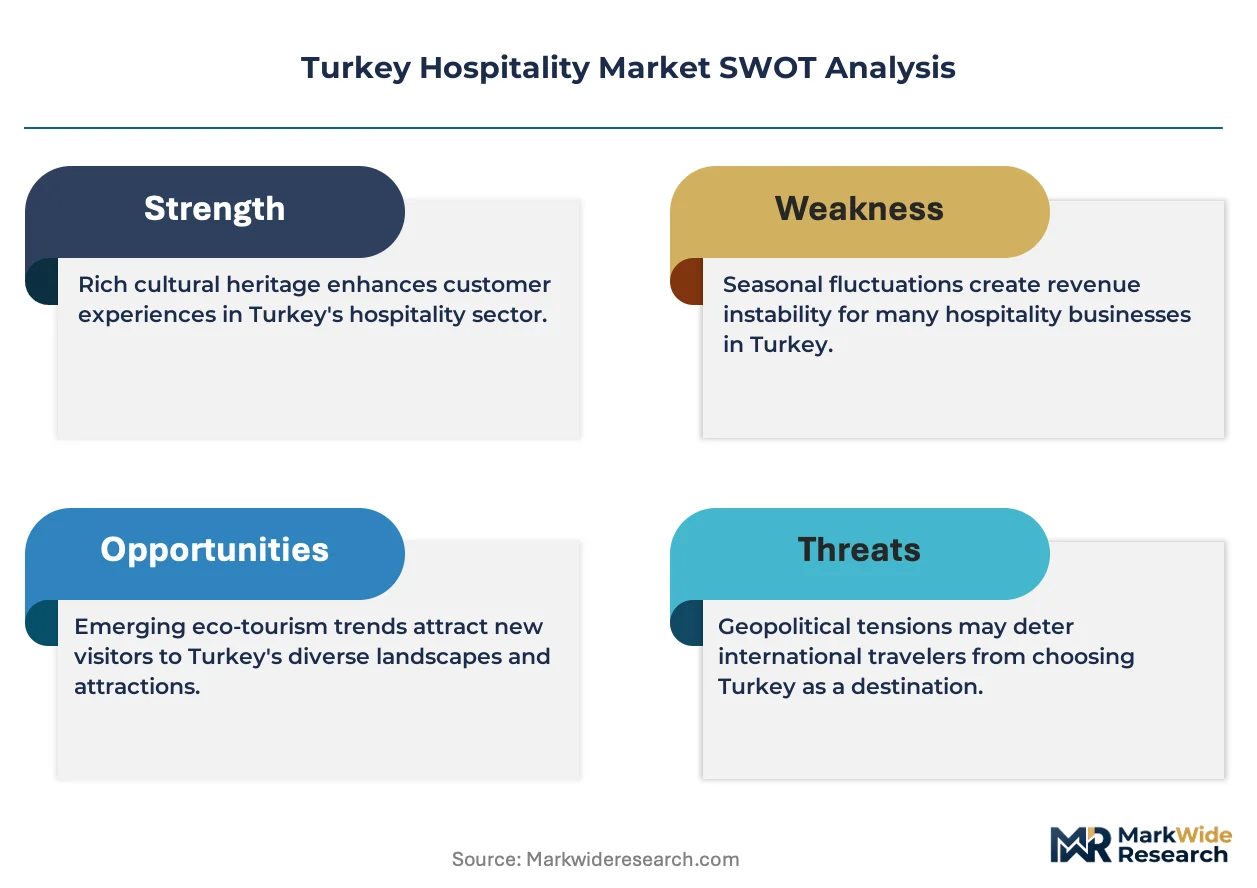
Turkey's Ministry of Culture and Tourism enforces licensing and classification standards that determine market access and pricing authority for hospitality operators. The country's central bank and banking regulation agency influence investment flows through credit conditions for property development and foreign-currency borrowing rules. Stakeholders must monitor regulatory adjustments to tourism incentives and exchange-rate policies that reshape capital allocation between Istanbul's urban hotel pipeline and resort expansion along the Aegean and Mediterranean coasts.
Market Dynamics
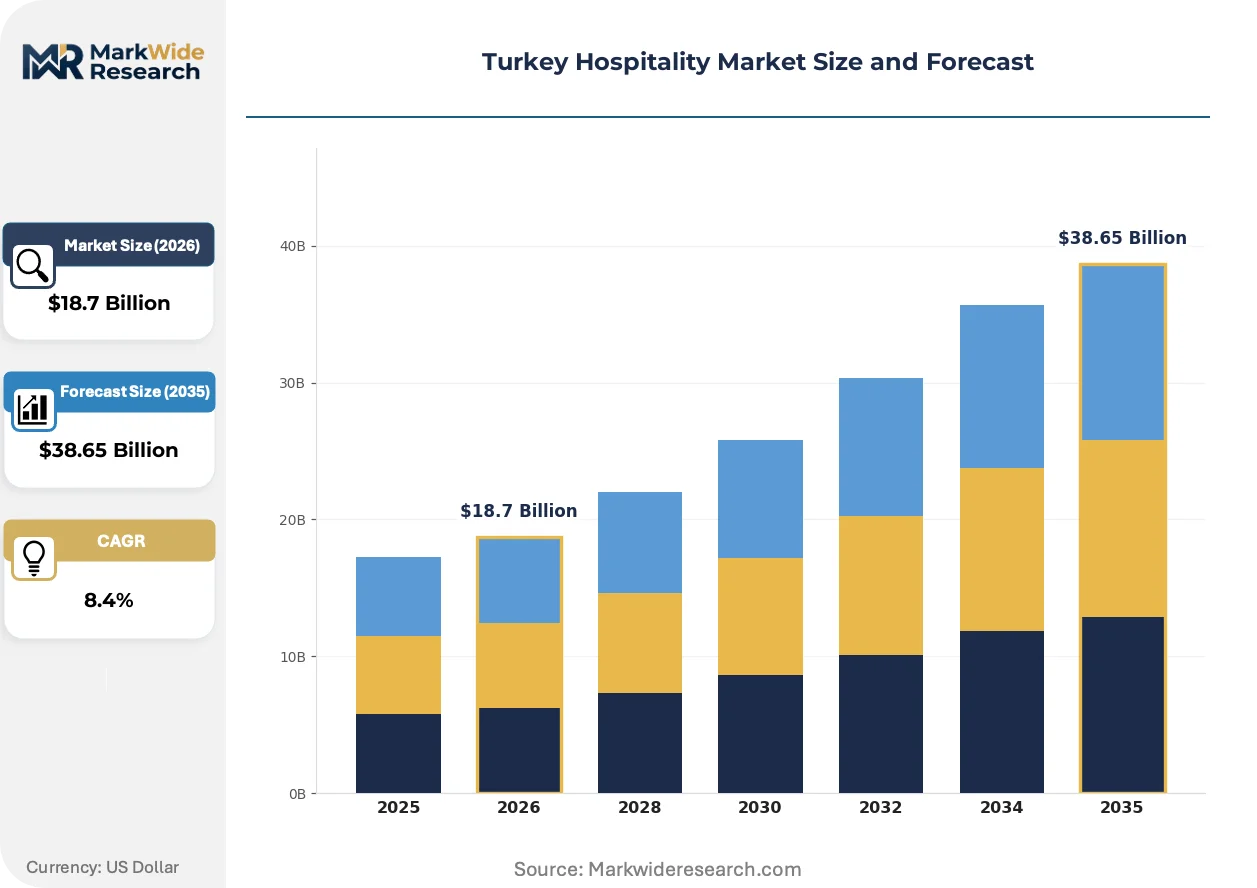
Turkey's hospitality sector is restructuring around platform-enabled distribution and Ministry of Culture and Tourism licensing reforms that compress approval timelines for new properties.
Growth Catalysts
- Boutique hotel licensing reforms:Turkey's Ministry of Culture and Tourism streamlined classification protocols for properties under fifty rooms, reducing bureaucratic friction for independent operators in Istanbul's Beyoğlu district.
- Gulf state leisure demand:Visitors from Saudi Arabia and the United Arab Emirates are extending average length of stay in coastal Aegean provinces, sustaining premium rate structures outside traditional European peak seasons.
- Remote worker extended stays:Digital nomad visa programs issued by the country's immigration authority are converting seasonal resort demand into twelve-month occupancy cycles for vacation rental platforms.
Market Restraints
- Foreign-currency borrowing constraints:Turkey's central bank maintains strict hedging requirements for dollar-denominated construction loans, elevating financing costs for Mediterranean coastline resort developments.
- Seasonal employment volatility:The Aegean and Mediterranean provinces depend on temporary labor pools that contract by sixty percent during winter months, degrading service consistency.
- Platform commission structures:Online travel aggregators extract fifteen to twenty-five percent of gross booking value, compressing net operating margins for independent hoteliers in Antalya.
Strategic Opportunities
- Convention infrastructure gaps:Ankara's business-travel segment lacks sufficient five-star inventory for medical congresses, creating white space for Dedeman Hotels & Resorts International and competing operators.
- Wellness tourism integration:Thermal resort properties in Afyonkarahisar province can leverage traditional hammam protocols to capture German and Austrian repeat visitors seeking certified health programs.
- Domestic rail connectivity:High-speed line extensions to İzmir and Konya are opening secondary city markets previously dependent on air access for corporate travel segments.
Industry Challenges
- Hospitality technology integration:Legacy property management systems in family-owned Istanbul hotels resist API connectivity with contemporary channel managers, fragmenting rate parity across distribution networks.
- Certification timeline compression:Green building standards required by municipal planning departments in Bodrum and Çeşme extend project completion by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Hospitality Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Leisure Travelers, Business Travelers, Event Attendees, Tourists Service Type: Accommodations, Food & Beverage, Events Planning, Concierge Services Property Type: Hotels, Resorts, Hostels, Vacation Rentals Booking Channel: Direct Booking, Online Travel Agencies, Travel Agents, Phone Reservations |
| Companies Covered | Marriott International Inc., Hilton Worldwide Holdings Inc., Accor S.A., InterContinental Hotels Group PLC (IHG), Wyndham Hotels & Resorts Inc., Radisson Hotel Group, Rixos Hotels, Limak Hotels, Dedeman Hotels & Resorts International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Hospitality Market Trends and Innovations
Platform-enabled supply distribution and sustainability certification requirements are compressing traditional operational models while opening new revenue streams for adaptive operators.
Smart room management systems integrating IoT sensors with energy grids are decentralizing operational control from central front desks to guest mobile applications. Coastal resorts in Antalya province are deploying these systems fastest, driven by utility cost pressures and Ministry of Environment carbon reporting mandates. The structural consequence is flattening organizational hierarchies and reducing night-shift staffing requirements by thirty to forty percent.
Turkey's Ministry of Culture and Tourism revised star-rating protocols in 2024 to mandate accessibility standards and digital service menus. Properties seeking five-star classification must now submit proof of automated check-in kiosks and multilingual chatbot deployment. Istanbul's Beyoğlu district boutique operators are responding fastest, converting heritage building constraints into technology-forward guest experiences that satisfy both regulators and platform algorithms.
Extended-stay demand from remote workers is fragmenting traditional weekly rate structures into daily-flexible pricing. Vacation rental platforms are capturing this segment through monthly subscription models that bypass conventional hotel front-desk relationships. The shift is most visible in coastal Aegean provinces where European Union passport holders combine Schengen-adjacent location with lower cost-of-living indices.
Turkey Hospitality Market Segmentation
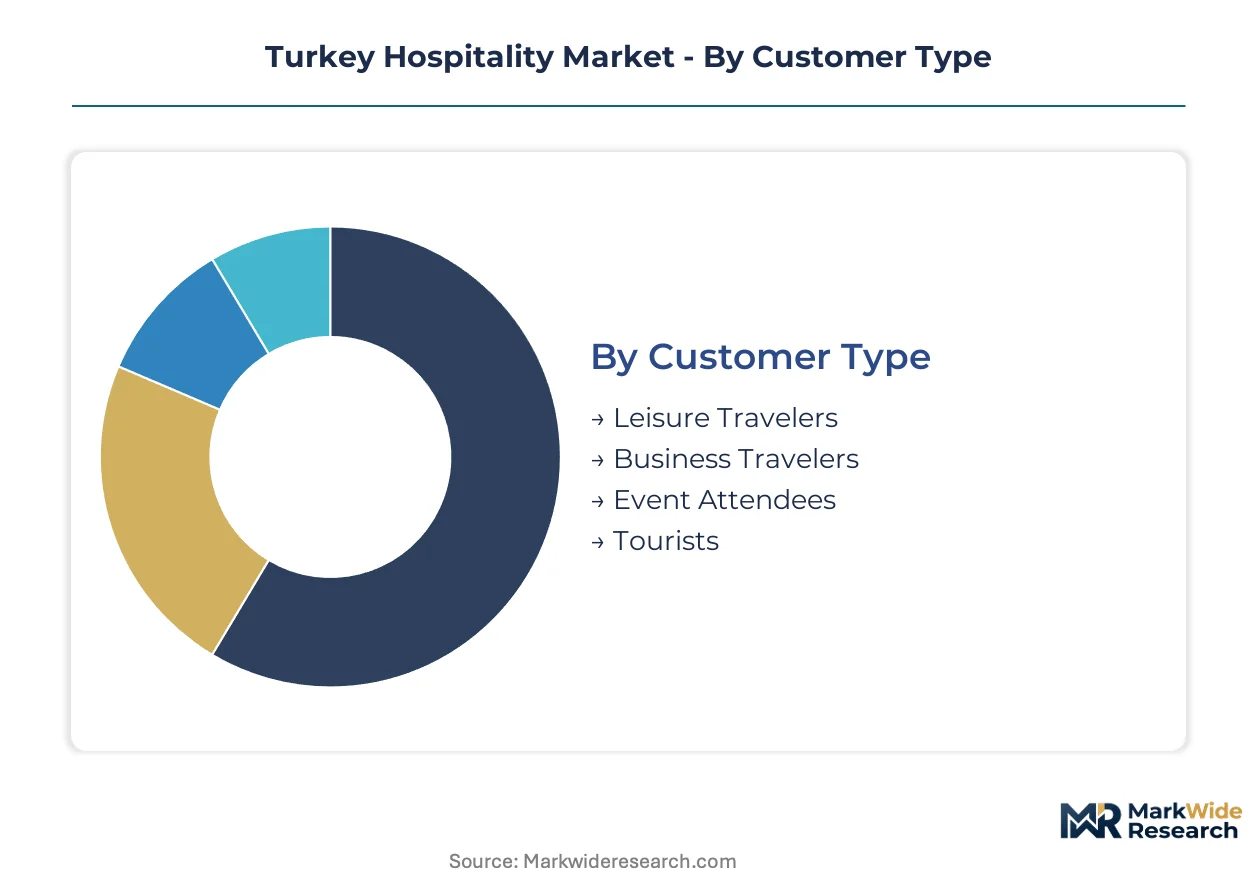
Turkey's hospitality operators configure service portfolios around distinct buyer profiles and property economics. Ministry of Culture and Tourism licensing tiers and platform distribution economics create divergent margin structures across these segments.
Customer Type:
Leisure travelers from Gulf states and European Union countries drive rate premiums through extended summer stays in coastal provinces.
- Leisure Travelers:Families and couples from Saudi Arabia, Germany, and Russia occupy Aegean and Mediterranean resorts during peak seasons. Gulf state visitors sustain premium pricing through autumn months outside traditional European demand windows.
- Business Travelers:Corporate accounts concentrated in Istanbul's Levent and Maslak districts demand proximity to financial centers. Ankara's government and embassy corridor generates consistent weekday occupancy for convention-oriented properties.
- Event Attendees:Medical congress participants and wedding parties seek block-booking arrangements with catering integration. Istanbul's exhibition centers in Yeşilköy and Ankara's ATO Congresium anchor this segment.
- Tourists:Cultural visitors to Cappadocia and Ephesus require location-specific inventory near UNESCO sites. Package tour operators negotiate volume rates that compress per-room profitability.
Volume sits with Leisure Travelers; growth tilts toward Business Travelers as Istanbul expands its financial services hub.
Service Type:
Revenue contribution per square meter varies dramatically across operational categories, with accommodations commanding asset-heavy investment and food service generating ancillary spend.
- Accommodations:Room inventory governed by Ministry of Culture and Tourism star classifications determines base-rate authority. Istanbul boutique properties in Beyoğlu leverage heritage building conversions to justify above-market nightly rates.
- Food & Beverage:All-inclusive resort concepts along the Mediterranean coastline capture captive dining spend through Rixos Hotels and competing operators. Independent restaurants in tourist districts face platform commission pressure from delivery aggregators.
- Events Planning:Wedding and conference coordination services attach to larger resort properties with dedicated ballroom infrastructure. Bodrum and Antalya venues compete for Gulf state celebration tourism through bespoke programming.
- Concierge Services:Thermal resort properties in Afyonkarahisar province integrate traditional hammam protocols with medical tourism facilitation. Digital concierge applications are displacing front-desk staffing in Istanbul's technology-forward independent hotels.
Accommodations anchor capital deployment; Events Planning climbs fastest as wedding tourism from Gulf states expands.
Property Type:
Investment intensity and regulatory burden diverge sharply between purpose-built hospitality assets and platform-enabled residential supply.
- Hotels:Star-rated properties subject to Ministry of Culture and Tourism inspection cycles require dedicated operational staffing and maintenance reserves. Istanbul's pipeline concentrates in the Asian side's Ataşehir and Kadıköy districts.
- Resorts:Coastal Aegean and Mediterranean properties capture concentrated foreign-exchange revenue through seasonal occupancy peaks. All-inclusive concepts dominate Antalya province with integrated entertainment and dining programming.
- Hostels:Budget inventory in Istanbul's Sultanahmet and Taksim districts serves backpacker and student segments through dormitory configurations. Platform reviews disproportionately influence booking conversion for this price-sensitive category.
- Vacation Rentals:Platform-supplied apartments in coastal provinces and Istanbul neighborhoods convert residential stock to hospitality use. Digital nomad visa holders from European Union countries sustain twelve-month demand cycles in İzmir and Antalya.
Hotels retain institutional investment preference; Vacation Rentals expand most quickly through supply elasticity.
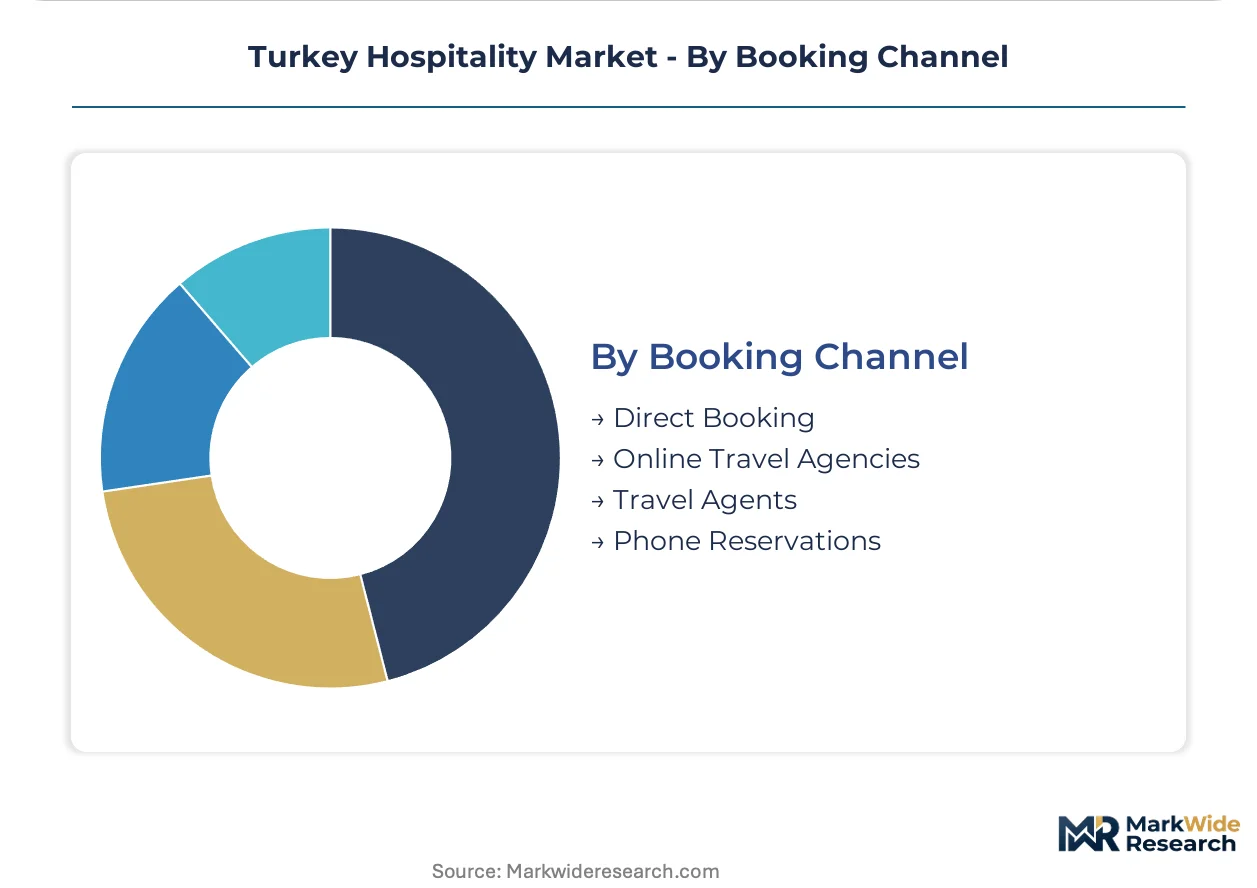
Booking Channel:
Distribution economics reshape net operating margins as platform intermediation extracts value from independent operators.
- Direct Booking:Brand.com reservations and property-level telephone sales bypass aggregator commissions. Marriott International's Bonvoy loyalty ecosystem sustains repeat direct bookings across Istanbul and Antalya assets.
- Online Travel Agencies:Booking.com and Expedia extract fifteen to twenty-five percent of gross transaction value from Antalya independent hoteliers. Algorithmic ranking systems pressure rate parity across competing properties.
- Travel Agents:Tour operators and corporate travel management companies negotiate net rates for package and MICE segments. German and Russian wholesale buyers dominate Mediterranean resort contracting.
- Phone Reservations:Legacy booking modality persists among domestic travelers and repeat guests with established property relationships. Family-owned Istanbul hotels maintain dedicated reservation lines despite digital migration.
Online Travel Agencies capture volume share; Direct Booking gains priority as operators seek margin recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bosphorus strait anchors Turkey's hospitality geography, linking Istanbul's urban hotel pipeline to coastal resort corridors along the Aegean and Mediterranean. This maritime connectivity shapes investment flows between metropolitan business-travel infrastructure and seasonal leisure destinations.
Marmara Region
Istanbul's Beyoğlu and Kadıköy districts concentrate boutique hotel conversions targeting Gulf state leisure demand. Turkey's Ministry of Culture and Tourism streamlined licensing protocols for properties under fifty rooms in 2024. The Asian-side Ataşehir corridor attracts convention-oriented developments as financial services expand.
Mediterranean Region
Antalya province captures all-inclusive resort investment from Saudi and Emirati visitors extending stays into autumn months. The central bank's foreign-currency hedging requirements elevate financing costs for new coastal construction. Alanya and Kemer sub-markets deploy smart room management systems fastest under Ministry of Environment carbon reporting mandates.
Aegean Region
İzmir and Bodrum convert residential stock to vacation rental supply through platform-enabled distribution. Municipal planning departments in Çeşme enforce green building standards extending project timelines. German and Austrian repeat visitors sustain thermal resort demand in Afyonkarahisar province.
Central Anatolia
Ankara's government and embassy corridor generates consistent weekday occupancy for business-oriented properties. The ATO Congresium anchors medical congress demand lacking sufficient five-star inventory. High-speed rail extensions to Konya open secondary corporate travel markets.
Black Sea Region
Trabzon and Rize provinces capture emerging domestic leisure demand from Istanbul-based travelers. The Ministry of Culture and Tourism's digital nomad visa programs extend seasonal demand cycles. Platform reviews disproportionately influence booking conversion for this developing category.
Turkey Hospitality Market Competitive Landscape
Global majors compete with regional champions across loyalty ecosystems and all-inclusive resort concepts. International chains anchor Istanbul's five-star segment through points-based retention systems, while Turkish operators dominate coastal provinces with integrated entertainment programming. Three archetypes define competitive positioning: global brand licensors, regional resort specialists, and independent boutique converters. Portfolio diversification and platform distribution partnerships constitute the dominant competitive moves.
Among global brand licensors, Marriott International Inc. and Hilton Worldwide Holdings Inc. occupy positions emphasizing loyalty ecosystem retention across Istanbul and Antalya assets. Rixos Hotels exemplifies the regional resort specialist archetype through all-inclusive Mediterranean coastline concepts. Dedeman Hotels & Resorts International anchors the convention-oriented segment within Ankara's business-travel corridor.
| Leading Market Players |
|---|
| Marriott International Inc. |
| Hilton Worldwide Holdings Inc. |
| Accor S.A. |
| InterContinental Hotels Group PLC (IHG) |
| Wyndham Hotels & Resorts Inc. |
| Radisson Hotel Group |
| Rixos Hotels |
| Limak Hotels |
| Dedeman Hotels & Resorts International |
| Others |
Pricing and Supply Chain Analysis
Gulf state leisure travelers concentrated in Antalya's all-inclusive resorts anchor Turkey's hospitality pricing model around bundled service packages that obscure rate transparency. This buyer archetype's preference for pre-paid convenience permits resort operators to capture ancillary spend while compressing net operating margins through platform commission structures.
Pricing Analysis
All-inclusive service bundling dominates Turkish coastal hospitality, wrapping accommodations, dining, and entertainment into single-rate packages that minimize guest transaction friction. Price differentiation separates five-star Ministry of Culture and Tourism classified properties from boutique conversions through star-rating certification and loyalty program integration. Pricing pressure stems from online travel agency commission extraction of fifteen to twenty-five percent of gross booking value, forcing independent hoteliers toward direct-booking investments. Leisure travelers from European Union countries exhibit highest price sensitivity, while Gulf state visitors demonstrate lowest sensitivity due to extended-stay premium positioning.
Supply Chain Analysis
Direct-to-property procurement channels handle bulk food and beverage supply for Mediterranean coastline resorts, bypassing intermediaries for perishable inventory. Turkey's hospitality sector draws construction materials from domestic cement and steel producers, hospitality technology from German and American vendors, and specialized linens from Pakistani textile manufacturers. Supply chain risk centers on single-source vulnerability for imported smart room management systems subject to foreign-currency volatility. Distribution runs through platform-enabled aggregators that intermediate guest acquisition while fragmenting rate parity control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's hospitality market represents a consolidation play as platform commission structures and foreign-currency borrowing constraints force undercapitalized independent operators toward exit. Ministry of Culture and Tourism licensing reforms favor scaled players with compliance resources.
For Market Incumbents: Anticipate margin compression from online travel agency algorithmic ranking systems by accelerating direct-booking infrastructure investment and Bonvoy-style loyalty ecosystem deployment. Acquire distressed boutique properties in Istanbul's Beyoğlu district to consolidate heritage inventory before licensing reform windows close. Vertical integration into food and beverage supply through captive catering operations reduces platform-dependent ancillary revenue leakage. For New Entrants and Emerging Players: Launch via vacation rental platform distribution targeting digital nomad visa holders in İzmir and coastal Aegean provinces, where residential stock conversion faces lighter regulatory burden than purpose-built hotel construction. Target Ankara's convention infrastructure gap with medical congress-oriented properties, exploiting Dedeman Hotels' insufficient five-star inventory coverage. White space exists in thermal resort wellness programming for German repeat visitors seeking certified health protocols. For Investors and Strategic Acquirers: The window for entry favors platform-enabled vacation rental aggregators and technology-forward boutique operators with Ministry of Culture and Tourism compliance capabilities. Long-term viability hinges on exposure to Gulf state demand sustainability and digital nomad visa program continuity. Monitor Turkey's central bank foreign-currency hedging requirement adjustments as inflection signal for resort development financing viability.| Strategic Initiative | Industry Significance |
|---|---|
| Loyalty Ecosystem Expansion | Marriott Bonvoy-style programs reduce OTA dependency across Istanbul and Antalya assets. |
| Direct Booking Platform Investment | Property-level reservation systems bypass fifteen to twenty-five percent aggregator commissions. |
| Thermal Resort Certification | Ministry of Culture and Tourism wellness protocols capture German medical tourism demand. |
| Smart Room Technology Deployment | IoT integration satisfies Ministry of Environment carbon mandates while reducing staffing costs. |
| Vacation Rental Supply Aggregation | Platform-enabled residential stock conversion serves twelve-month digital nomad demand cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Turkey hospitality market analysis. Primary interviews with hotel operations directors, Ministry of Culture and Tourism licensing officials, online travel agency partnership managers, and vacation rental platform supply coordinators combined with secondary validation from Turkey's central bank credit condition reports, tourism ministry statistics, and hospitality technology vendor disclosures. Bottom-up property-level capacity estimates and top-down foreign-exchange revenue projections underwent triangulation to reconcile segmentation outputs.
Data-stream reconciliation across accommodation type, customer segment, booking channel, and regional province dimensions shaped the analytical framework across the analysis window. CAGRs derived from historical occupancy rate trajectories, average daily rate movements, and supply pipeline tracking. Forecast inputs incorporated digital nomad visa issuance velocity, Gulf state airlift capacity expansion, and high-speed rail connectivity extensions to secondary cities.
The model assumes a particular technology adoption path for smart room management and platform-enabled distribution; alternative pathways for legacy property management system retention would alter the outlook. Forecasts reflect assumptions regarding Ministry of Culture and Tourism regulatory continuity, central bank foreign-currency policy stability, and Gulf state leisure demand persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Saudi Arabia Wedding Services Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Bowling Centers Market