
 US Catering Services Market | 2026-2036
US Catering Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Catering Services Market Insights
Event production revenue is reshaping competitive economics across the US catering landscape as operators shift from commodity meal delivery toward experience design and full-service event management. Compass Group leverages its institutional scale to dominate corporate and sports venue contracts across multiple states. Aramark Services anchors its position through deep penetration in education and healthcare foodservice channels. Sodexo differentiates via sustainability-certified menu programs and technology-integrated ordering platforms.
Catering services encompass the commercial preparation, transport, and service of food and beverages for off-site or on-site consumption at organized gatherings, typically involving batch production with holding temperatures maintained above 140°F for hot items and below 41°F for cold items to ensure HACCP compliance. The primary purpose spans business entertainment, celebratory occasions, institutional feeding, and hospitality augmentation where hosts outsource food production and service execution. Corporate events within the service type dimension command the largest revenue pool due to recurring contract structures and volume guarantees, while vegan and gluten-free categories within food type are expanding fastest as dietary accommodation becomes standard rather than premium. The off-premise delivery model has matured into a baseline expectation, though on-premise plated service retains the highest per-guest margin profile.
FDA food code provisions and state health departments enforce sanitation standards, allergen disclosure protocols, and temperature control documentation that shape operational costs and liability exposure for catering operators. OSHA workplace safety rules and Department of Labor wage-hour enforcement add compliance layers affecting staffing models and event labor pricing. Stakeholders must monitor evolving state-level organic labeling requirements and municipal composting mandates that will influence supplier selection and menu engineering decisions.
Market Dynamics
Corporate return-to-office mandates are accelerating contract renegotiations between Fortune 500 employers and institutional foodservice operators, compressing procurement cycles while expanding per-employee meal subsidy budgets across metropolitan business districts.
Growth Catalysts
- FDA Food Code modernization:Updated temperature control and allergen disclosure protocols are forcing smaller operators to upgrade HACCP documentation systems, creating acquisition opportunities for scaled providers with compliance infrastructure already in place.
- Sports venue concession conversion:Stadium and arena operators are outsourcing premium hospitality suites and club dining to full-service caterers, replacing in-house foodservice with contracted event specialists.
- Healthcare facility expansion:Hospital systems in Texas, California, and Florida are consolidating patient feeding and visitor hospitality under single-source catering contracts with guaranteed volume minimums.
Market Restraints
- Protein input cost volatility:Beef and poultry commodity price swings compress gross margins on fixed-price corporate catering contracts, particularly for operators locked into annual rate agreements.
- Specialized equipment supply concentration:Mobile hot-holding cabinets and refrigerated transport units rely on a consolidated Midwest manufacturing base, creating lead time vulnerability for regional expansion.
- Substitution by restaurant delivery aggregators:Corporate meal programs increasingly benchmark against DoorDash and Uber Eats corporate accounts, pressuring traditional caterers on price transparency and menu variety.
Strategic Opportunities
- Underpenetrated secondary metros:Nashville, Austin, and Raleigh-Durham office construction is outpacing established catering infrastructure, creating first-mover advantages for operators with mobile kitchen capabilities.
- USDA organic certification tailwind:Federal procurement preference for certified organic suppliers is opening institutional channels previously dominated by conventional foodservice contractors.
- AI-driven demand forecasting convergence:Machine learning platforms predicting event attendance and dietary preferences are enabling just-in-time production that reduces food waste below 5%.
Industry Challenges
- Certified food protection manager scarcity:State-level requirements for on-site ServSafe-certified supervisors at every event create staffing bottlenecks during peak wedding and conference seasons.
- Legacy POS integration complexity:Caterers with decades-old accounting systems face costly middleware development to connect with corporate client procurement platforms requiring real-time invoice reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Catering Services Market |
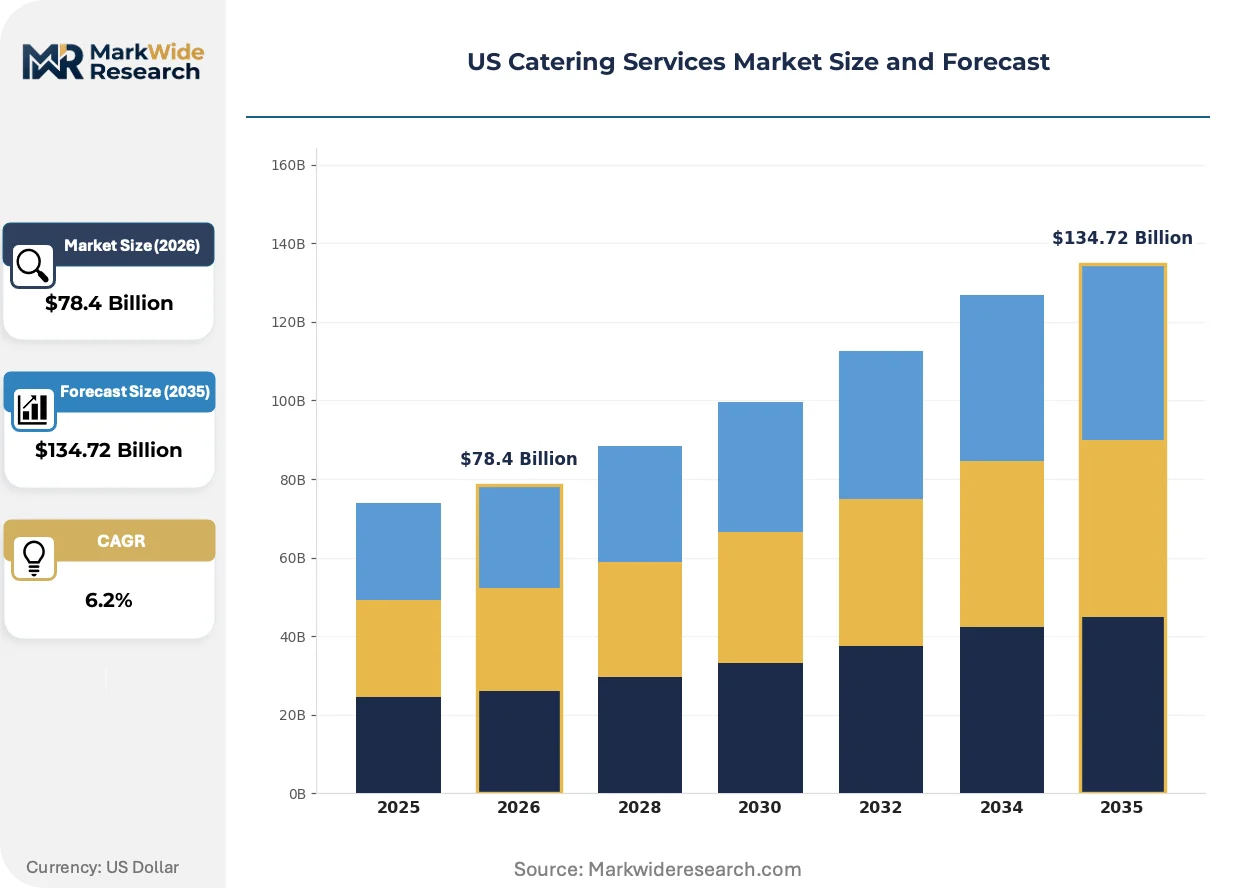
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Events, Weddings, Social Gatherings, Private Parties Delivery Model: Off-Premise, On-Premise, Drop-Off, Buffet Service Food Type: Vegetarian, Non-Vegetarian, Vegan, Gluten-Free Client Type: Businesses, Individuals, Schools, Non-Profit Organizations |
| Companies Covered | Compass Group, Aramark Services, Sodexo, Delaware North, HMS Host, Elior Group, American Dining Creations, AVI Foodsystems, Legends, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Catering Services Market Trends and Innovations
Kitchen automation and predictive logistics are compressing the gap between order placement and service execution, enabling caterers to operate with smaller prep footprints and tighter inventory turns than traditional batch production models allowed.
Cloud-based kitchen display systems with IoT temperature logging are digitizing the handoff between prep, transport, and service teams. Mid-market corporate clients now mandate API-accessible delivery tracking as a baseline RFP requirement. This connectivity layer is digitizing the operational transparency that previously required on-site supervision, allowing caterers to serve distributed office campuses with centralized production facilities.
State health departments are harmonizing digital inspection reporting formats under voluntary FDA Food Code adoption incentives. Operators in California and New York face accelerated audit frequencies but reduced on-site inspection duration through pre-submitted documentation portals. The compliance burden is shifting toward data infrastructure investment rather than physical facility upgrades, favoring scaled players with dedicated quality assurance technology staff.
Corporate procurement departments are consolidating preferred vendor lists and demanding unit-level pricing transparency previously treated as trade secrets. Buyers in technology and financial services verticals now require itemized ingredient cost breakdowns for sustainability scoring. This visibility mandate is compressing supplier margins while rewarding operators with direct agricultural sourcing relationships that bypass layered distribution markups.
US Catering Services Market Segmentation
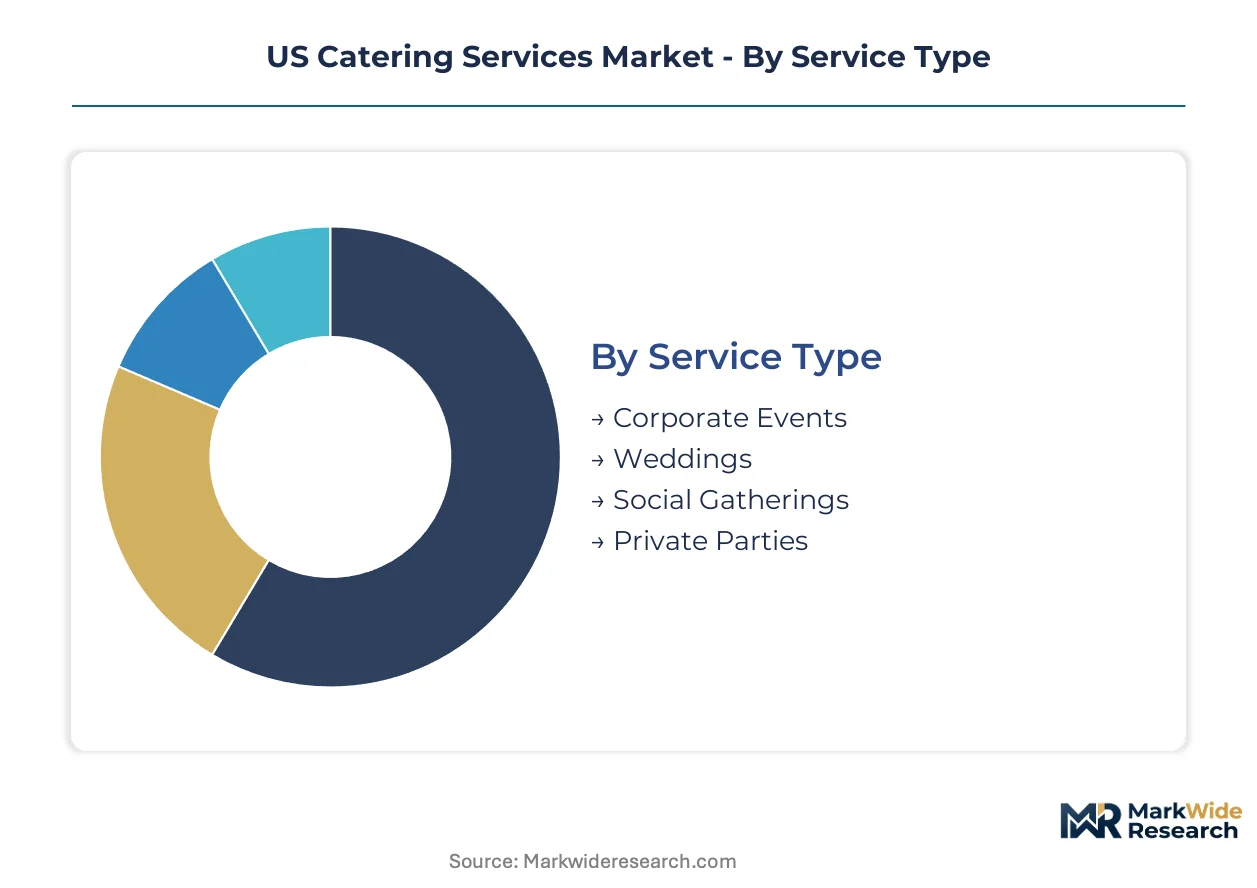
Service differentiation across the US catering landscape determines contract renewal rates and margin sustainability. Operators structure pricing and capacity around segment-specific production cycles and client procurement behaviors.
Service Type:
Corporate events turn over fastest with quarterly contract renegotiations, while weddings operate on 12-18 month booking cycles that lock capacity far in advance.
- Corporate Events:Recurring breakfast, lunch, and hospitality programs for Fortune 500 employers with guaranteed volume minimums and standardized menu rotations. Demand concentrates in Texas, California, and Florida metropolitan corridors where return-to-office mandates are accelerating per-employee meal subsidies.
- Weddings:High-touch plated service with customized menu development and dedicated event coordination staffing. Texas and California destination wedding markets are absorbing premium pricing as couples defer to professional event management over DIY coordination.
- Social Gatherings:Milestone celebrations and family reunions with flexible service formats.
- Private Parties:Intimate dining experiences for residential and small venue settings.
Corporate events dominate installed base. Weddings are where expansion concentrates.
Delivery Model:
Off-premise formats carry lower fixed-cost burdens, while on-premise service commands premium labor deployment and equipment investment.
- Off-Premise:Central kitchen production with hot-holding transport to client locations, enabling geographic coverage from single facilities. FDA temperature control documentation requirements are forcing upgrades to IoT-enabled transport monitoring systems.
- On-Premise:Full-service execution with on-site culinary teams and front-of-house staffing at client venues or dedicated event spaces. Corporate procurement departments in financial services and technology verticals are mandating this format for executive hospitality.
- Drop-Off:Pre-packaged meal delivery without service staff, competing directly with restaurant aggregator corporate accounts.
- Buffet Service:Self-service format with maintained holding equipment and minimal staffing ratios.
Off-premise delivery dominates installed base. On-premise service is where expansion concentrates.
Food Type:
Non-vegetarian categories maintain volume leadership, while specialized dietary formats are climbing the fastest as accommodation becomes baseline expectation rather than premium upsell.
- Non-Vegetarian:Protein-centered menus with beef, poultry, and seafood as primary components. Beef and poultry commodity price volatility is compressing margins on fixed-price annual contracts.
- Gluten-Free:Celiac-safe preparation protocols with segregated equipment and ingredient sourcing. Healthcare facility expansion in Texas, California, and Florida is driving institutional adoption as patient dietary accommodation standardizes.
- Vegetarian:Plant-forward menus with dairy and egg inclusion.
- Vegan:Exclusively plant-based preparation with allergen cross-contamination controls.
Non-vegetarian offerings dominate installed base. Gluten-free is where expansion concentrates.
Client Type:
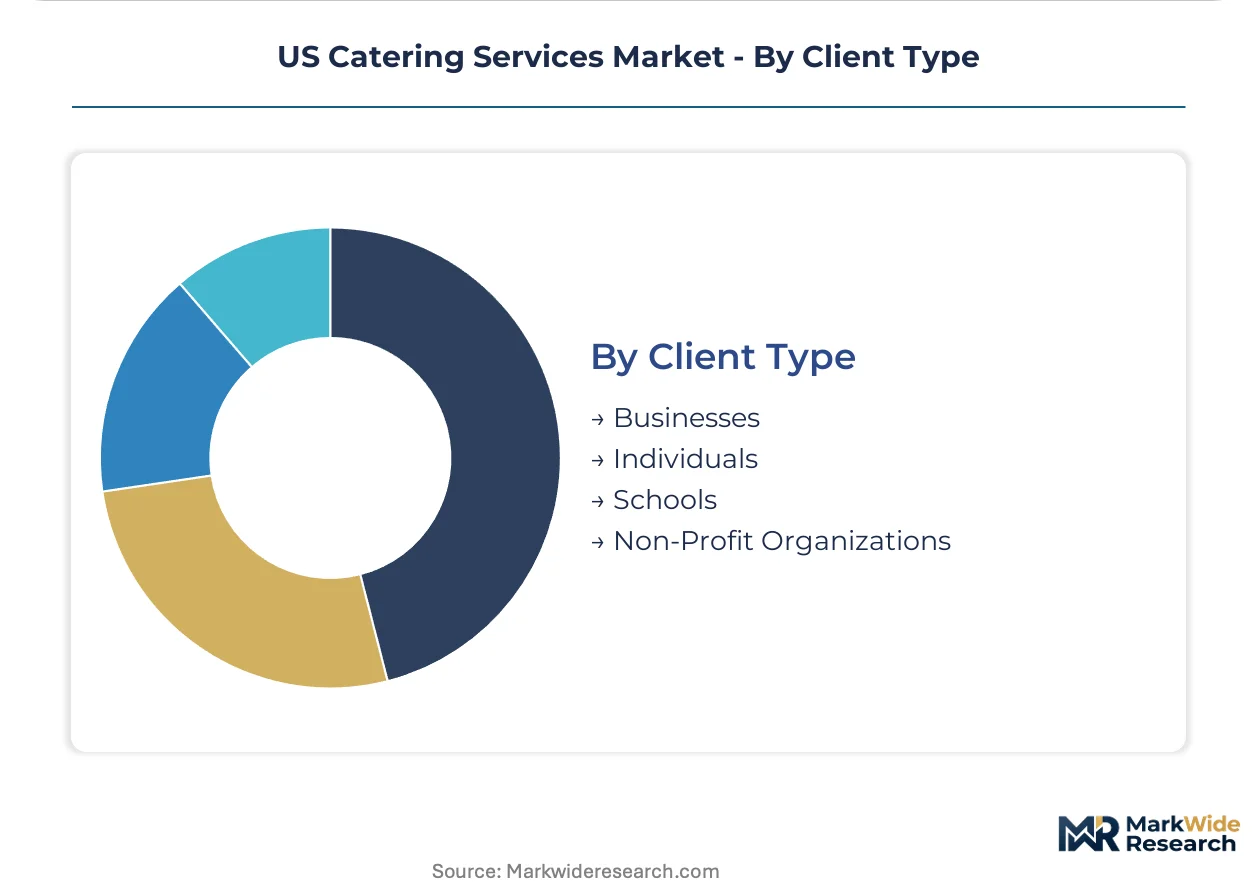
Business clients operate on annual procurement cycles with RFP-driven vendor consolidation, while individual bookings remain fragmented and price-sensitive.
- Businesses:Corporate dining programs, conference hospitality, and executive event outsourcing with contractually guaranteed volumes. Compass Group and Aramark leverage institutional scale to capture multi-year agreements with volume minimums.
- Schools:K-12 and university feeding programs with USDA nutritional compliance requirements. Federal procurement preference for certified organic suppliers is opening channels previously dominated by conventional contractors.
- Individuals:Personal celebrations and residential entertaining with high price elasticity.
- Non-Profit Organizations:Fundraising galas and community events with constrained budgets and volunteer coordination dependencies.
Business clients dominate installed base. Schools are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement in Texas and California demonstrates lowest price elasticity due to guaranteed volume contracts, while individual buyers in secondary metros show highest sensitivity to per-guest pricing fluctuations.
Texas
Hospital systems in Houston and Dallas are consolidating patient feeding under single-source catering contracts with guaranteed annual minimums. FDA Food Code temperature control documentation requirements are accelerating IoT-enabled transport monitoring adoption among Dallas-Fort Worth operators. Austin's office construction pipeline is outpacing established catering infrastructure, creating first-mover advantages for mobile kitchen-equipped providers.
California
Technology and financial services verticals in San Francisco and Los Angeles are mandating on-premise plated service for executive hospitality with itemized ingredient cost breakdowns. State health departments are harmonizing digital inspection reporting formats under voluntary FDA Food Code adoption incentives, reducing on-site inspection duration through pre-submitted documentation portals. San Diego's healthcare facility expansion is driving institutional adoption of gluten-free preparation protocols as patient dietary accommodation standardizes.
Florida
Sports venue operators in Miami and Orlando are outsourcing premium hospitality suites and club dining to full-service caterers, replacing in-house foodservice with contracted event specialists. State-level health codes are tightening operational compliance requirements for allergen disclosure protocols. Tampa's return-to-office acceleration is compressing procurement cycles while expanding per-employee meal subsidy budgets across metropolitan business districts.
New York Metro
Corporate dining programs in Manhattan are consolidating preferred vendor lists and demanding unit-level pricing transparency previously treated as trade secrets. OSHA workplace safety rules and Department of Labor wage-hour enforcement are adding compliance layers affecting staffing models and event labor pricing. Brooklyn and Queens secondary office markets are absorbing overflow demand as Midtown capacity constraints intensify.
Illinois
Chicago-based institutional foodservice operators are capturing multi-year agreements with Fortune 500 employers featuring standardized menu rotations and quarterly contract renegotiations. USDA organic certification is opening federal procurement channels previously dominated by conventional contractors. The city's legacy POS integration complexity is forcing costly middleware development to connect with corporate client procurement platforms requiring real-time invoice reconciliation.
US Catering Services Market Competitive Landscape
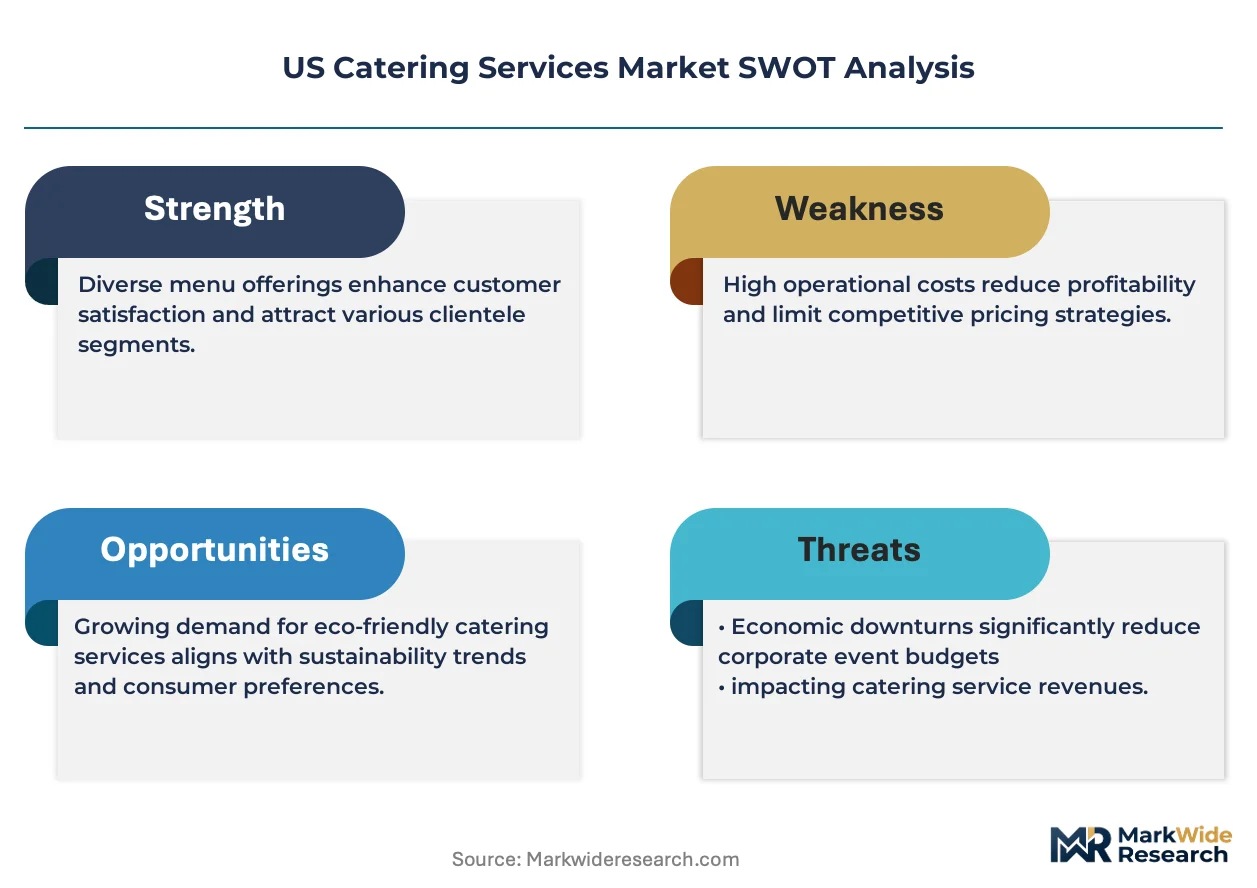
Capability concentration sits with full-service event specialists; scale advantage sits with institutional contractors. The market structures around three tiers: multinational operators with compliance infrastructure, regional specialists with mobile kitchen assets, and fragmented local providers competing on price. Strategic archetypes include experience-design aggregators, sustainability-certified menu platforms, and technology-integrated ordering specialists. Dominant competitive moves are M&A to absorb smaller operators facing FDA modernization costs, and strategic partnerships with sports venue operators for concession conversion.
Within the multinational tier, Compass Group and Aramark Services exemplify scale-driven positioning through institutional contract penetration, while Sodexo occupies a differentiated position via sustainability-certified program development. These operators represent the compliance-ready infrastructure tier that FDA Food Code modernization favors.
| Leading Market Players |
|---|
| Compass Group |
| Aramark Services |
| Sodexo |
| Delaware North |
| HMS Host |
| Elior Group |
| American Dining Creations |
| AVI Foodsystems |
| Legends |
| Others |
Pricing and Supply Chain Analysis
I-35 corridor freight economics from Dallas to San Antonio directly shape regional supply concentration and downstream price differentiation for Texas catering operators, compressing margins on outbound delivery while rewarding centralized kitchen investments that amortize transport costs across multiple contracts.
Pricing Analysis
Long-term offtake agreements with annual rate locks dominate corporate catering procurement, though quarterly renegotiation clauses are proliferating as buyers seek flexibility. Price differentiation rests on volume scale and HACCP certification tier, with FDA Food Code-compliant operators commanding premium positioning. Pricing pressure stems from protein input cost volatility squeezing fixed-price contracts. Individual buyers in secondary metros exhibit highest price sensitivity, while Fortune 500 procurement departments demonstrate lowest elasticity due to guaranteed volume minimums.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are standard for produce and protein suppliers serving mid-market operators, while supply-chain finance facilities anchor working capital for scaled players. Geographic supply concentration centers on California produce, Midwest protein processing, and Texas distribution hubs. Raw material dependencies include beef, poultry, and specialty dietary ingredients. Single-source vulnerability in mobile hot-holding cabinet manufacturing creates lead time risk. Distribution runs through regional cold-chain logistics providers with last-mile fleet partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the US catering landscape creates acquisition opportunities as FDA Food Code modernization forces smaller operators toward exit, while corporate return-to-office mandates generate niche demand for specialized dietary accommodation and executive hospitality formats.
For Market Incumbents: Insulate margin position through backward integration into direct agricultural sourcing relationships that bypass layered distribution markups. Acquire mobile kitchen-equipped regional specialists in Austin, Nashville, and Raleigh-Durham before competitors establish first-mover positions. Consolidate compliance infrastructure investments across acquired operators to spread FDA documentation system costs.
For New Entrants and Emerging Players: Secondary metro office construction in Austin and Raleigh-Durham represents the most penetrable entry point given infrastructure gaps relative to demand acceleration. Healthcare facility expansion in Texas, California, and Florida offers institutional contract opportunities with guaranteed volume minimums. Lead with AI-driven demand forecasting platforms that reduce food waste below 5% as differentiated value proposition in RFP responses.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate foodservice divisions lacking dedicated technology investment for procurement platform integration. Long-term viability favors operators with compliance-ready infrastructure and direct sourcing relationships over price-competitive local providers. Monitor state-level organic labeling requirement adoption as inflection indicator for USDA certification tailwinds opening federal procurement channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Infrastructure Acquisition | Absorbing smaller operators facing FDA Food Code modernization costs accelerates scale advantages in HACCP documentation. |
| Direct Agricultural Sourcing | Bypassing distribution markups enables itemized ingredient cost transparency demanded by technology and financial services buyers. |
| AI-Driven Demand Forecasting | Machine learning platforms predicting event attendance reduce food waste below 5% and improve inventory turns. |
| Sports Venue Concession Conversion | Replacing in-house foodservice with contracted event specialists captures premium hospitality suite revenue pools. |
| Mobile Kitchen Capability Expansion | Geographic coverage from centralized facilities addresses underpenetrated secondary metros with outpacing office construction. |
Research Methodology
Cross-validation between primary interviews with catering operations directors, corporate procurement managers, and food safety compliance officers and secondary sources including FDA Food Code documentation, state health department inspection records, and USDA procurement databases anchors the qualitative findings. Bottom-up demand modeling from individual contract analysis triangulates against top-down market sizing from institutional foodservice operator disclosures.
Calibration against historical contract renegotiation cycles and protein commodity price volatility informs the projection framework across the analysis window. Segmentation dimensions modeled include service type, delivery model, food type, and client vertical with regional regulatory cluster overlays. CAGRs derive from trend extrapolation adjusted for identified catalysts and restraints. Forecast inputs incorporate corporate return-to-office mandate intensity and healthcare facility expansion pipelines.
Macroeconomic conditions sit as an overlay; deviation in protein commodity prices, freight cost indices, or labor wage enforcement intensity would shift the trajectory. Regulatory acceleration in state-level organic labeling or municipal composting mandates could revise supplier selection and menu engineering assumptions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Hospitality Furniture Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Saudi Arabia Wedding Services Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
Airport Lounge Operation Services Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
France HRI Market