
 Malaysia Hospitality Market | 2026-2036
Malaysia Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Hospitality Market Insights
Five-star and boutique property specifications are redrawing competitive expectations in Malaysian hospitality. Marriott International leverages its Bonvoy ecosystem to sustain repeat corporate bookings across Kuala Lumpur's Golden Triangle. Shangri-La Hotels and Resorts anchors premium resort demand with its Rasa Sayang property on Penang's Batu Feringgi beach. Genting Group dominates the integrated resort segment through its hilltop casino-hotel complex outside the capital.
Malaysia hospitality encompasses lodging, food and beverage, event hosting, and ancillary guest services delivered through properties ranging from budget inns to integrated resorts, typically measured by average daily rate, revenue per available room, and occupancy percentage. The sector serves both leisure migration and business convention demand while functioning as a primary employment engine within Malaysia's services economy. Luxury hotels and resorts command the deepest margin pools along Langkawi and Penang coastlines where international guest spending elevates ancillary revenue. Serviced apartments are expanding fastest among business travelers seeking extended-stay configurations with kitchen facilities and workspace amenities. Budget hotels retain volume leadership in secondary cities where domestic tourism and pilgrimage routes sustain high occupancy turnover.
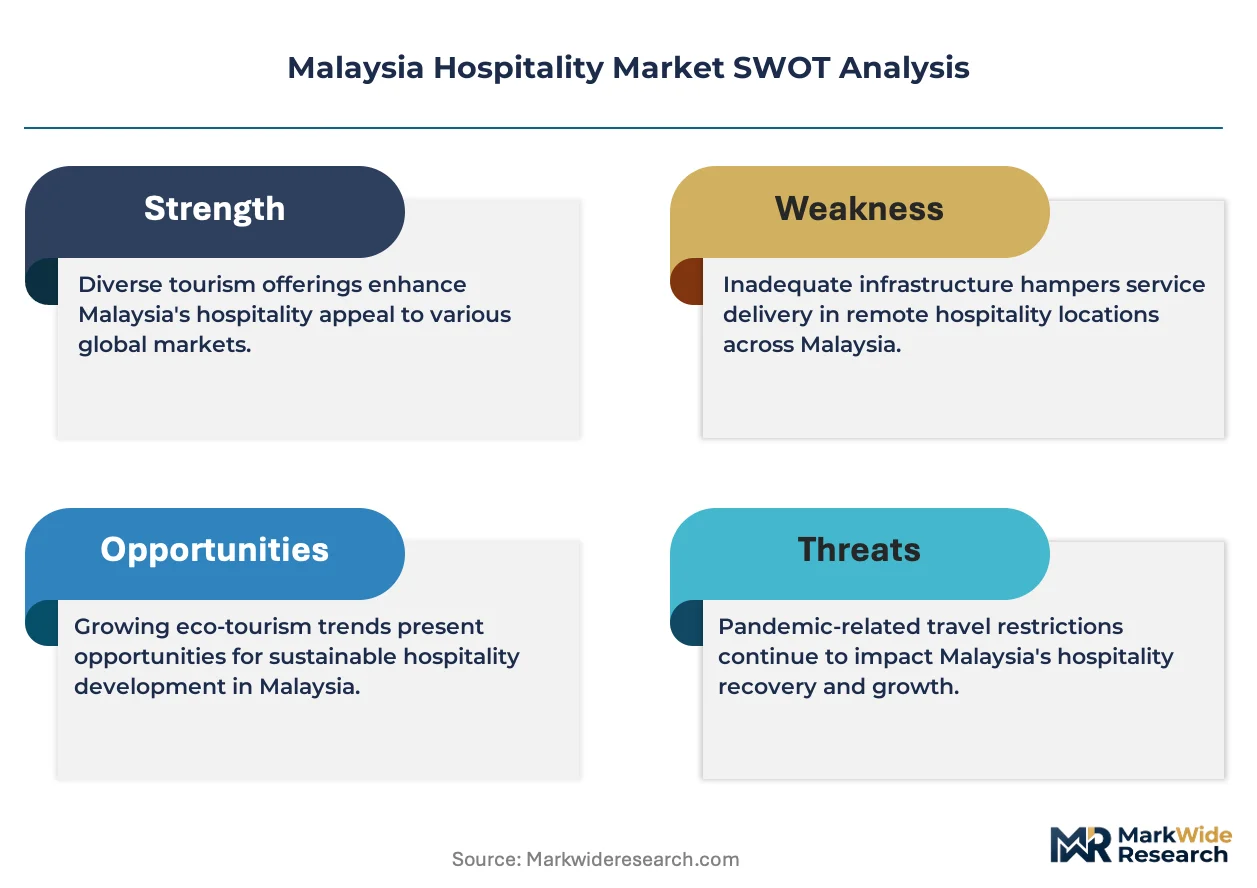
Malaysia's Ministry of Tourism, Arts and Culture coordinates with the Ministry of Housing and Local Government to enforce fire safety and accessibility standards across all licensed accommodation providers. Green Building Index Malaysia certification is becoming a prerequisite for new resort developments seeking preferential financing from Malaysian Investment Development Authority incentive schemes. Stakeholders must monitor how Penang Island's heritage conservation guidelines and Langkawi's UNESCO geopark status reshape permissible development density along environmentally sensitive coastlines.
Market Dynamics
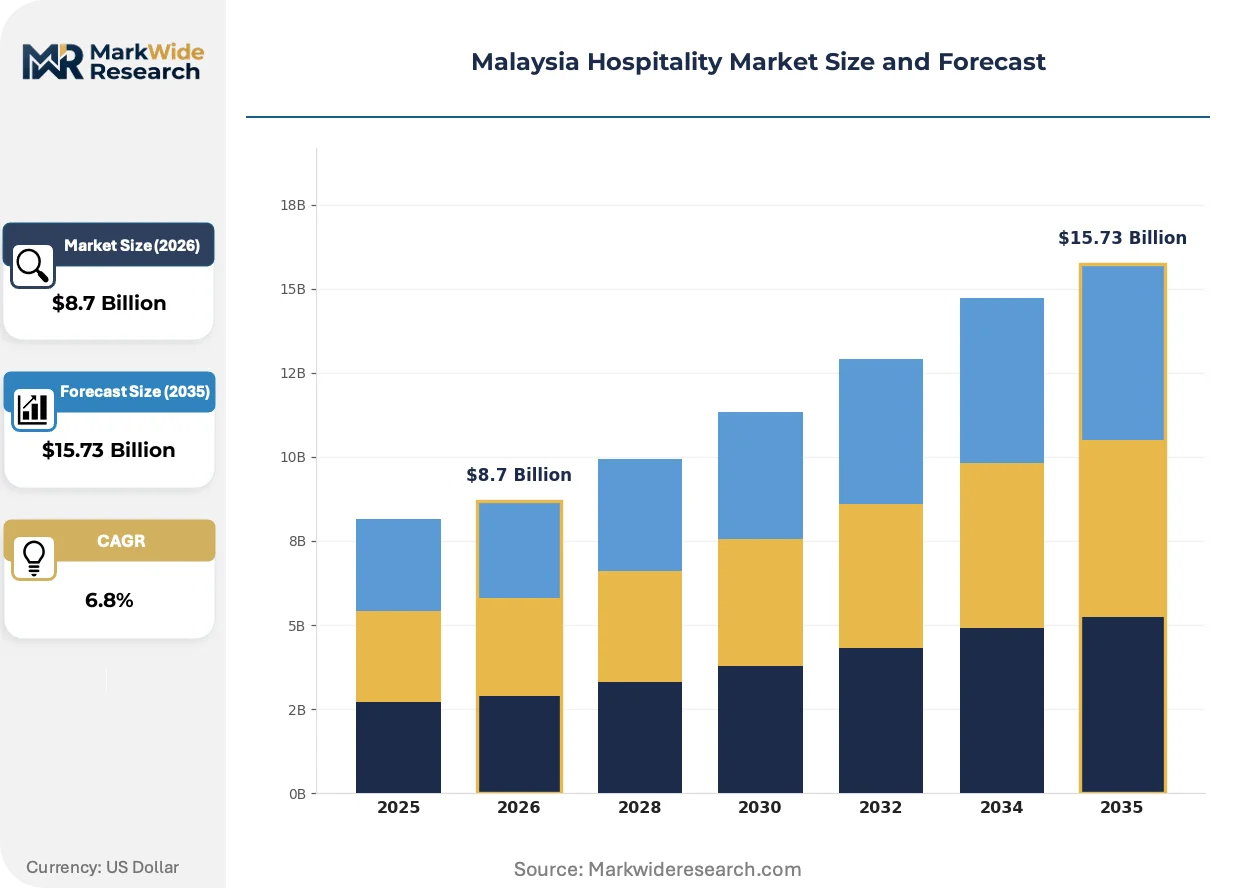
Malaysia's hospitality sector is undergoing structural recalibration as Green Building Index Malaysia certification becomes mandatory for new resort developments seeking preferential financing from Malaysian Investment Development Authority incentive schemes. This regulatory pivot is compressing development timelines while elevating capital requirements across the Penang and Langkawi corridors.
Growth Catalysts
- Green Building Index Malaysia:The certification framework is accelerating sustainable construction practices across new hotel developments in Langkawi and Penang. Developers securing this designation unlock preferential tax incentives and expedited permitting.
- Serviced apartment expansion:Corporate travelers in Kuala Lumpur's Golden Triangle are extending average stays beyond traditional hotel patterns. Kitchen facilities and dedicated workspace configurations are capturing extended-stay demand from regional headquarters relocations.
- Heritage conservation guidelines:Penang Island's UNESCO World Heritage Site status is channeling boutique hotel investment into restored colonial shophouses. This regulatory framework protects architectural authenticity while creating premium rate positioning.
Market Restraints
- Construction cost volatility:Imported sustainable timber and low-carbon steel inputs face price instability from Southeast Asian supply chain disruptions. Green material premiums add 15-25% to baseline construction budgets.
- Skilled labor concentration:Certified green building professionals cluster in Kuala Lumpur and Penang, creating talent scarcity for Langkawi developments. Migration restrictions limit cross-state workforce mobility.
- Heritage compliance friction:Penang's conservation guidelines impose strict facade preservation requirements that extend renovation timelines. Adaptive reuse projects face multi-agency approval processes.
Strategic Opportunities
- Johor Bahru corridor:The Iskandar Malaysia economic zone offers underpenetrated hospitality infrastructure adjacent to Singapore's demand spillover. Business travelers seeking cost arbitrage are driving serviced apartment interest.
- Digital nomad visa integration:Malaysia's DE Rantau program creates extended-stay demand for co-living hospitality formats. Properties combining accommodation with dedicated coworking infrastructure capture this emerging segment.
- Geopark status leverage:Langkawi's UNESCO Global Geopark designation supports premium ecotourism positioning. Nature-integrated resort concepts command rate premiums from European and Australian source markets.
Industry Challenges
- Fire safety retrofitting:Malaysia's Ministry of Housing and Local Government mandates sprinkler system upgrades across pre-2010 hotel stock. Legacy properties in George Town's heritage core face structural constraints for compliance.
- Accessibility standard implementation:Uniform barrier-free design requirements apply across all licensed accommodation tiers. Boutique properties in converted shophouses encounter spatial limitations for elevator installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Hospitality Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Hotels, Budget Hotels, Resorts, Serviced Apartments End User: Business Travelers, Tourists, Corporates, Event Planners Distribution Channel: Online Travel Agencies, Direct Booking, Corporate Partnerships, Travel Agents Customer Type: Domestic Guests, International Guests, Group Travelers, Solo Travelers |
| Companies Covered | Marriott International, Hilton Worldwide, Accor, InterContinental Hotels Group (IHG), Shangri-La Hotels and Resorts, Genting Group, Sunway Hotels & Resorts, Berjaya Hotels & Resorts, YTL Hotels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Hospitality Market Trends and Innovations
Technology integration and sustainability mandates are compressing traditional operational models across Malaysian hospitality. Properties are reconfiguring guest-facing systems and back-of-house infrastructure to align with certification requirements and shifting traveler expectations.
Contactless check-in and mobile key systems are displacing front-desk reception protocols across Kuala Lumpur's four-star and five-star inventory. Marriott International's Bonvoy ecosystem and comparable loyalty platforms are accelerating adoption among business travelers. This displacement is compressing staffing ratios while redirecting personnel investment toward concierge and experience curation functions.
Malaysia's Ministry of Tourism, Arts and Culture coordinates fire safety enforcement with the Ministry of Housing and Local Government through unified licensing inspections. Properties failing accessibility or environmental standards face operational permit suspensions. Heritage boutique operators in Penang are responding by engaging conservation architects to reconcile compliance with preservation mandates.
Extended-stay configurations are capturing corporate travel budgets previously allocated to traditional hotel room nights. Serviced apartments with kitchen facilities and workspace amenities are displacing conventional business hotel demand in Kuala Lumpur's Golden Triangle and Penang's Bayan Lepas corridor. Procurement managers at regional headquarters are consolidating vendor relationships around apartment-style providers.
Malaysia Hospitality Market Segmentation
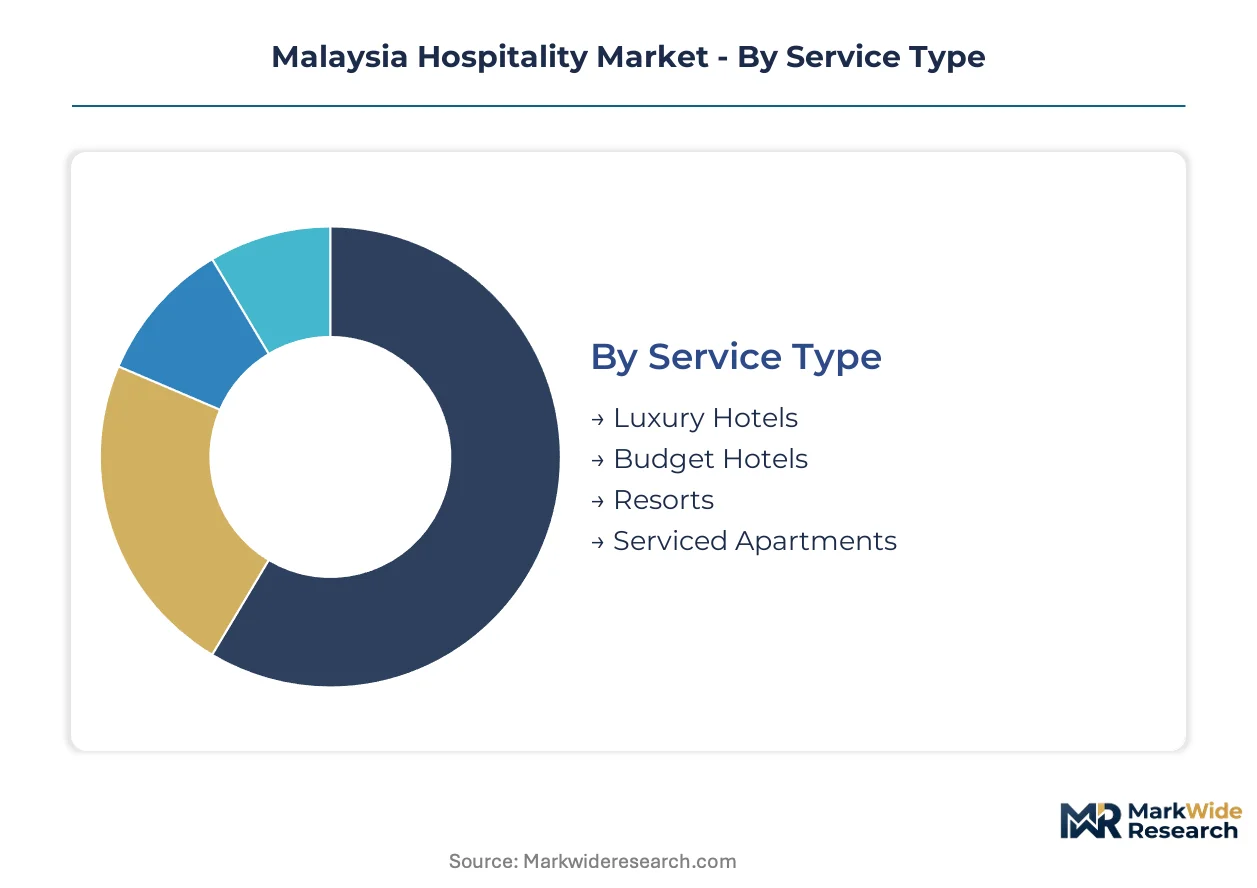
Malaysia's hospitality segmentation reflects divergent regulatory pressures and capital intensity across property tiers. Green Building Index Malaysia certification requirements and heritage conservation mandates reshape competitive positioning differently for each service category and customer channel.
Service Type:
Green Building Index Malaysia certification applies differentially across property tiers, with luxury developments facing the most stringent sustainability thresholds for MIDA incentive eligibility.
- Luxury Hotels:Properties in Kuala Lumpur's Golden Triangle and Langkawi's western coastline command premium rate positioning through integrated spa, F&B, and concierge ecosystems. Malaysia's Ministry of Tourism, Arts and Culture enforces elevated fire safety and accessibility standards that compress renovation timelines for pre-2010 stock.
- Serviced Apartments:Extended-stay configurations with kitchen facilities and dedicated workspace capture corporate relocation budgets across KL's Golden Triangle and Penang's Bayan Lepas corridor. Procurement managers at regional headquarters consolidate vendor relationships around apartment-style providers.
- Resorts:Beachfront and hilltop integrated properties anchor leisure demand through ancillary gaming, entertainment, and nature-integrated programming.
- Budget Hotels:Volume leadership in secondary cities relies on high occupancy turnover from domestic tourism and pilgrimage routes with minimal amenity overhead.
Established volume favors budget hotels; emerging adoption favors serviced apartments.
End User:
Corporate procurement patterns concentrate demand differently than leisure booking behaviors, with extended-stay contracts displacing traditional transient room-night purchasing.
- Business Travelers:Regional headquarters relocations in Kuala Lumpur drive serviced apartment demand with kitchen facilities and workspace amenities. Average stays extend beyond traditional hotel patterns as mobility restrictions ease.
- Corporates:Volume contracting for conference, training, and incentive travel concentrates in properties with certified green credentials for ESG reporting compliance.
- Tourists:Leisure migration splits between heritage boutique experiences in Penang's George Town and beachfront resort programming in Langkawi.
- Event Planners:Convention and wedding demand concentrates in properties with integrated ballroom infrastructure and preferential MIDA financing access.
Procurement consolidation favors corporates; experiential differentiation favors tourists.
Distribution Channel:
Commission structures and customer acquisition costs vary sharply between intermediary-dependent and direct-booking strategies.
- Online Travel Agencies:Aggregator platforms dominate transient leisure bookings with rate parity requirements that compress margin on inventory allocated to discount channels.
- Direct Booking:Loyalty ecosystems and mobile key systems displace front-desk protocols while capturing higher-margin repeat corporate demand.
- Corporate Partnerships:Master service agreements with regional headquarters lock in extended-stay volume across Kuala Lumpur and Penang properties.
- Travel Agents:Package tour operators channel group leisure demand, particularly from source markets with limited direct booking penetration.
Margin retention favors direct booking; volume scale favors online travel agencies.
Customer Type:
Domestic and international guest profiles impose divergent operational requirements around payment systems, language services, and regulatory compliance documentation.
- International Guests:European and Australian source markets command rate premiums at Langkawi's geopark-integrated resorts with nature-programming differentiation.
- Domestic Guests:High-frequency short-stay patterns in secondary cities sustain occupancy turnover with limited ancillary spending per visit.
- Group Travelers:Convention, pilgrimage, and incentive segments concentrate in properties with scalable F&B and transportation coordination capabilities.
- Solo Travelers:Digital nomad visa integration through Malaysia's DE Rantau program creates extended-stay demand for co-living hospitality formats with coworking infrastructure.
Rate premium positioning favors international guests; occupancy stability favors domestic guests.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian hospitality supply clusters around three distinct corridors. Kuala Lumpur anchors corporate and luxury demand. Penang and Langkawi concentrate leisure and resort investment. Johor Bahru captures Singapore spillover with cost-arbitrage positioning.
Kuala Lumpur and Selangor
Corporate relocation from Singapore and regional headquarters expansion drive serviced apartment absorption in the Golden Triangle. Malaysia's Ministry of Tourism, Arts and Culture enforces fire safety retrofit mandates for pre-2010 hotel stock. The KLCC-Bukit Bintang corridor hosts the densest concentration of five-star inventory competing on loyalty ecosystem integration.
Penang Island
UNESCO World Heritage Site status channels boutique hotel investment into restored George Town shophouses. Heritage conservation guidelines impose strict facade preservation requirements that extend renovation timelines. Batu Feringgi beach anchors premium resort demand with integrated spa and F&B programming.
Langkawi Archipelago
European and Australian source markets command rate premiums at nature-integrated resorts. Green Building Index Malaysia certification is becoming mandatory for new developments seeking Malaysian Investment Development Authority incentive schemes. Western coastline beachfront properties concentrate luxury supply with geopark-programming differentiation.
Johor Bahru and Iskandar Malaysia
Business travelers seeking cost arbitrage against Singapore pricing drive serviced apartment interest. The Iskandar Malaysia economic zone offers underpenetrated hospitality infrastructure adjacent to cross-border demand spillover. Nusajaya and Johor Bahru city center cluster new supply targeting extended-stay corporate contracts.
East Malaysia
Domestic tourism and pilgrimage routes sustain budget hotel occupancy turnover in Kota Kinabalu and Kuching. Sabah's ecotourism positioning around Mount Kinabalu and marine parks attracts nature-integrated resort investment. Sarawak's cultural tourism assets support boutique property development in heritage districts.
Malaysia Hospitality Market Competitive Landscape
Concentration sits with international brand operators controlling premium-tier positioning in Kuala Lumpur and resort corridors. The market structure tiers across global hospitality groups, domestic integrated resort developers, and regional boutique specialists. Three archetypes dominate: loyalty ecosystem operators, heritage-anchored resort developers, and serviced apartment platform managers. Competitive moves center on portfolio diversification into extended-stay formats and strategic partnerships for green certification compliance.
Within the global brand tier, Marriott International and Hilton Worldwide occupy positions as loyalty ecosystem anchors across Kuala Lumpur's corporate corridor. Shangri-La Hotels and Resorts exemplifies the heritage-resort archetype through its Penang and Langkawi beachfront positioning. Genting Group sits within the integrated resort developer category, dominating hilltop casino-hotel complexes with gaming-anchored ancillary revenue streams.
| Leading Market Players |
|---|
| Marriott International |
| Hilton Worldwide |
| Accor |
| InterContinental Hotels Group (IHG) |
| Shangri-La Hotels and Resorts |
| Genting Group |
| Sunway Hotels & Resorts |
| Berjaya Hotels & Resorts |
| YTL Hotels |
| Others |
Pricing and Supply Chain Analysis
Green Building Index Malaysia certification gates both supply qualification and price differentiation simultaneously. Developers securing this designation unlock preferential tax incentives from the Malaysian Investment Development Authority while commanding rate premiums from corporate buyers with ESG procurement mandates. This regulatory pivot compresses margins for uncertified competitors while elevating capital requirements across new developments.
Pricing Analysis
Green Building Index Malaysia dictates the pricing tier structure across Malaysian hospitality. Three-tier pricing separates certified luxury resorts from standard business hotels from economy budget properties. Certification level and geographic delivery cost drive price differentiation, with Langkawi beachfront properties capturing premiums over secondary city inventory. Pricing pressure stems from green material premiums adding fifteen to twenty-five percent to baseline construction budgets. Domestic tourists in secondary cities exhibit highest price sensitivity; international corporate buyers in Kuala Lumpur's Golden Triangle show lowest.
Supply Chain Analysis
Malaysia and Indonesia anchor sustainable timber and construction material supply for hospitality developments. China and South Korea furnish low-carbon steel inputs and smart building systems. Raw material dependencies center on imported certified timber, green concrete additives, and energy-efficient HVAC components. Single-source vulnerability concentrates in green building professional talent clustered in Kuala Lumpur and Penang. Distribution runs through consolidated contractor networks serving the Penang-Langkawi-Kuala Lumpur development corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian hospitality operates as a regulatory entrenchment story. Green Building Index certification creates switching costs that lock in preferred developer status with Malaysian Investment Development Authority financing schemes.
For Market Incumbents: Shield market position by accelerating heritage conservation architect partnerships in Penang and securing captive green material supply contracts. Marriott International's Bonvoy ecosystem demonstrates how loyalty platform investment defends against serviced apartment disruptors. Vertical integration into sustainable timber sourcing mitigates construction cost volatility threatening margin compression. For New Entrants and Emerging Players: Anchor in Johor Bahru's Iskandar Malaysia corridor where Singapore demand spillover meets underpenetrated hospitality infrastructure. The DE Rantau digital nomad visa program creates white-space opportunity for co-living formats with integrated coworking infrastructure. Target corporate procurement managers consolidating extended-stay vendor relationships around apartment-style providers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across green-certified resort developments. Long-term viability favors portfolios with Malaysian Investment Development Authority incentive access and heritage conservation expertise. Acquisition targets should demonstrate compliance architect relationships and Langkawi-Penang geographic concentration. Monitor Green Building Index Malaysia certification application backlogs as inflection signal for development pipeline constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Index Certification | Unlocks Malaysian Investment Development Authority preferential financing and expedited permitting timelines. |
| Serviced Apartment Platform Expansion | Captures corporate relocation budgets from regional headquarters consolidating vendor relationships. |
| Heritage Conservation Architect Partnership | Reconciles UNESCO World Heritage Site compliance with boutique hotel premium rate positioning. |
| DE Rantau Visa Integration | Targets digital nomad extended-stay demand with co-living hospitality formats. |
| Geopark Programming Differentiation | Commands rate premiums from European and Australian source markets at Langkawi resorts. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation across regulatory and trade sources. Hotel development executives, heritage conservation architects, corporate procurement managers, and Malaysian Investment Development Authority incentive program officers provided operational perspective. Secondary sources encompassed Green Building Index Malaysia certification records, tourism ministry licensing databases, and hospitality trade association construction cost surveys. Bottom-up property-level data triangulated against top-down sector expenditure estimates.
Across the projection horizon, the analytical framework modeled demand segmentation by service type, end user, distribution channel, and customer type. CAGRs derived from historical absorption patterns and forward-looking development pipeline assessments. Forecast inputs incorporated green certification adoption curves, corporate relocation trends, and heritage conservation guideline evolution.
Material uncertainties — regulatory enforcement intensity, green material supply disruptions, and cross-border labor mobility restrictions — sit outside the modeled envelope. Forecasts reflect assumptions about incentive scheme continuity and certification timeline stability. Recalibration cycles align with material shifts in Green Building Index Malaysia mandate scope and Malaysian Investment Development Authority financing availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Airport Lounge Operation Services Market
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
Saudi Arabia Wedding Services Market
Hospitality Management and Services
Hotel Ice Dispensers Market