
 Bowling Centers Market | 2026-2036
Bowling Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Bowling Centers Market Analysis
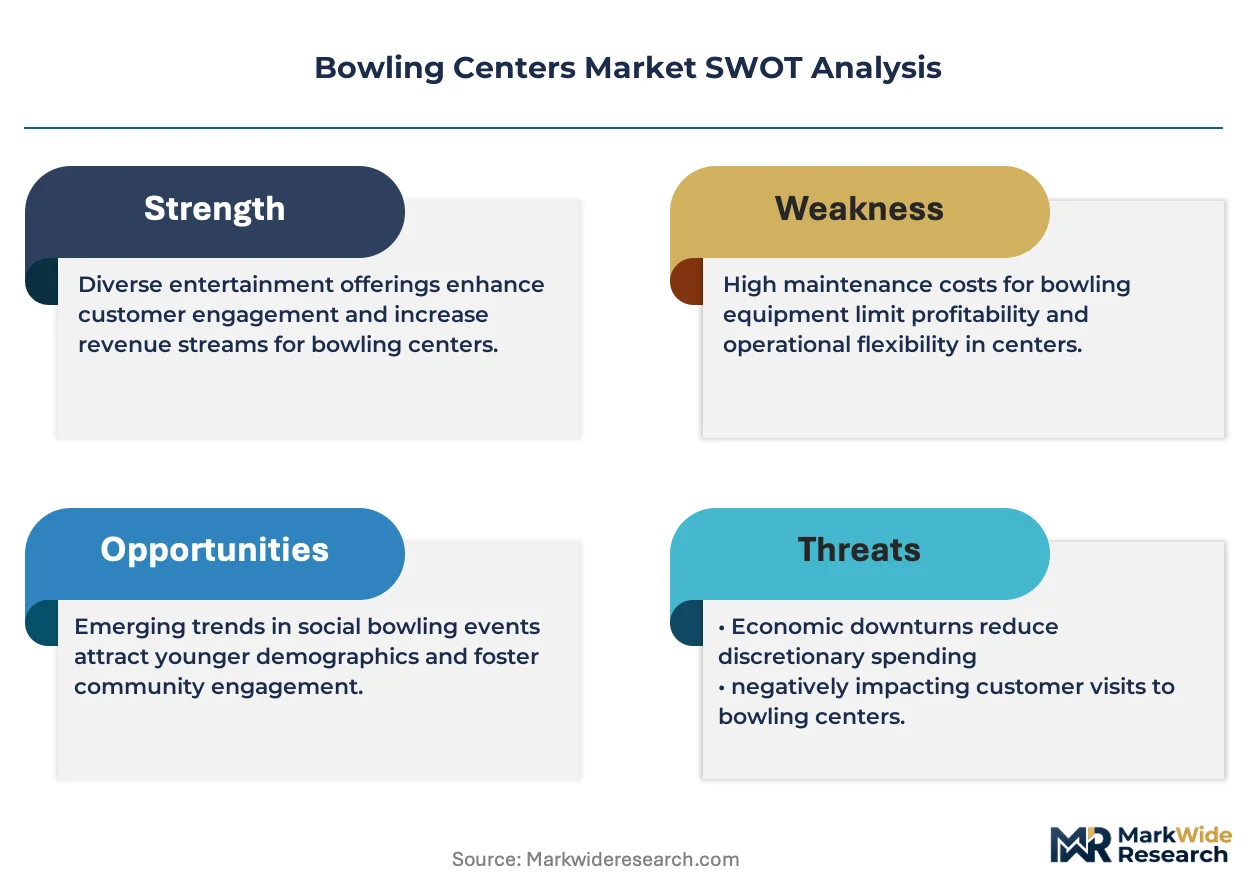
The split between premium experience-driven bowling centers and commodity lane-rental facilities is realigning capital allocation across the industry. Hollywood Bowl Group anchors its position through estate-scale venues combining dining, arcades, and competitive leagues. Main Event Entertainment differentiates via integrated entertainment complexes that capture extended dwell time. Brunswick Bowling Products leverages equipment innovation to sustain technology leadership in automated scoring and lane conditioning systems.
Bowling centers are commercial entertainment venues built around engineered maple and synthetic lane surfaces, typically measuring 60 feet from foul line to head pin, designed for recreational and competitive pinfall activities. The facility type dimension shows entertainment complexes capturing disproportionate margin pools through cross-selling food, beverage, and ancillary attractions, while standalone centers face pressure to diversify revenue. Customer type dynamics reveal corporate groups and young adults as the fastest-growing segments, with families remaining the mature, high-volume base that supports weekday utilization.
US operators navigate OSHA workplace safety standards, state-level amusement ride and venue regulations, and ADA Title III accessibility requirements that mandate lane-side wheelchair spaces and approach ramps. Local fire codes and alcohol licensing boards further constrain site selection and operating hours in many municipalities. Stakeholders must monitor evolving state tax treatment of experiential entertainment versus traditional retail to anticipate margin shifts from policy changes.
Market Dynamics
Corporate group bookings and multi-attraction entertainment complexes are restructuring revenue composition across the bowling center industry, pulling capital away from standalone lane operations toward integrated food, beverage, and gaming venues.
Growth Catalysts
- ADA Title III Mandates:Federal accessibility requirements for wheelchair-accessible lanes and approach ramps are accelerating facility renovation cycles and modernizing aging real estate stock.
- Experience Economy:Young adult and corporate segments are prioritizing social entertainment venues over traditional retail, extending average dwell time and per-visit spend at multi-attraction complexes.
- State Amusement Tax Variability:Favorable tax treatment of experiential entertainment versus retail in Texas, Florida, and California is directing venue development toward these high-density population corridors.
Market Restraints
- Maple Lane Supply Concentration:Premium lane surface production depends on North American hardwood suppliers, exposing operators to lumber price volatility and extended lead times for quality-grade materials.
- Real Estate Intensity:60-foot lane specifications plus ancillary space requirements constrain site selection to suburban and exurban locations with sufficient footprint and parking capacity.
- Alcohol Licensing Friction:Municipal licensing boards in many jurisdictions impose restrictive operating hours and proximity requirements that limit revenue diversification into beverage service.
Strategic Opportunities
- Underpenetrated Secondary Markets:Mid-sized metropolitan areas in the US Southeast lack modern entertainment complexes, presenting whitespace for estate-scale venue development.
- Automated Scoring Convergence:Integration of camera-based pin detection with mobile app platforms is enabling real-time league management and remote tournament participation.
- Corporate Wellness Programs:Employer-sponsored recreational leagues represent an emerging channel for guaranteed weekday lane utilization and recurring group revenue.
Industry Challenges
- Certified Lane Technician Shortage:Specialized maintenance skills for lane conditioning machines and pinsetter electronics are scarce, driving up labor costs and service response times.
- Legacy System Integration:Retrofitting automated scoring and reservation platforms into decades-old facilities creates operational downtime and customer experience friction during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bowling Centers Market |
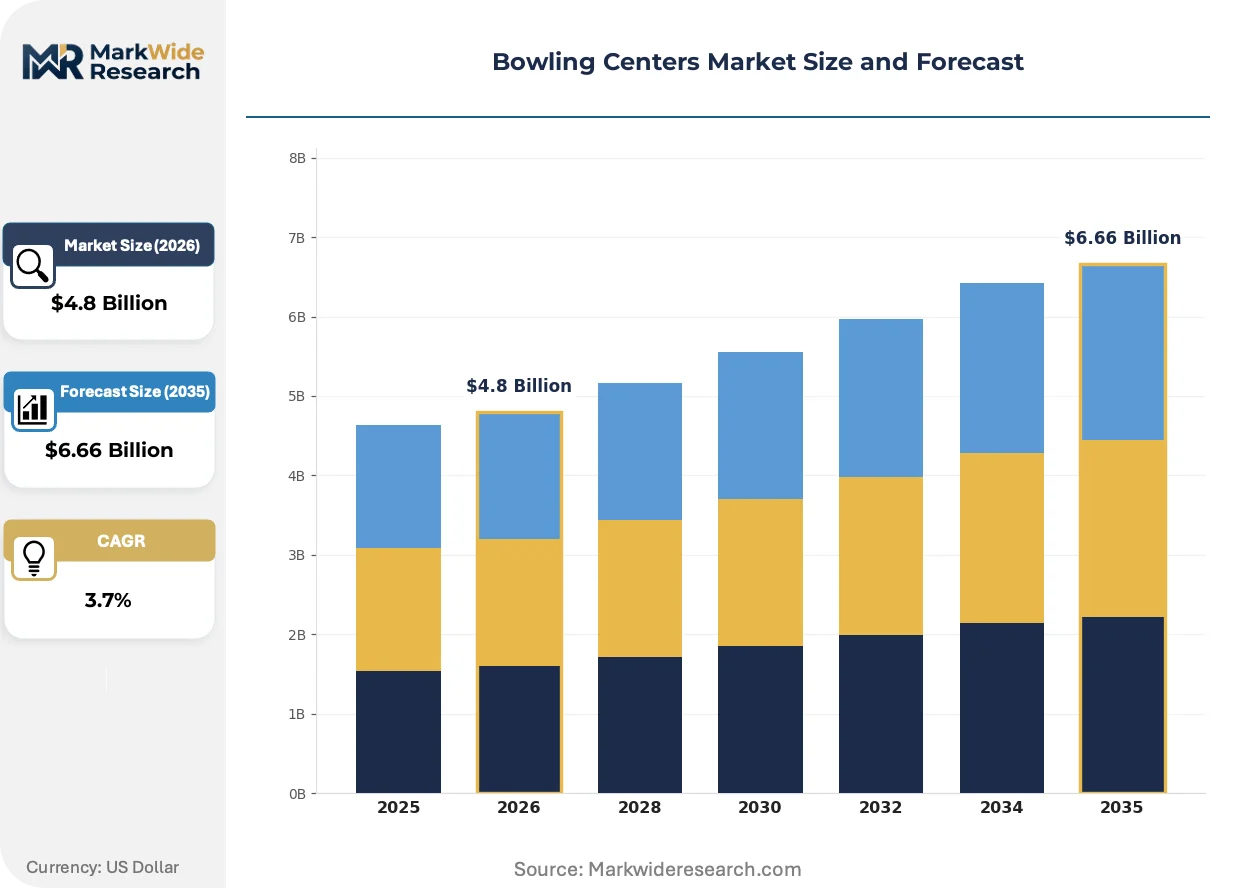
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Traditional Bowling, Cosmic Bowling, Bowling Leagues, Party Events Customer Type: Families, Young Adults, Seniors, Corporate Groups Facility Type: Standalone Centers, Bowling Alleys, Entertainment Complexes, Recreation Centers Revenue Stream: Lane Rentals, Food & Beverage Sales, Equipment Rentals, Membership Fees |
| Companies Covered | Hollywood Bowl Group, Main Event Entertainment, Lucky Strike Entertainment Corporation, Switch Bowling, Ten Entertainment Group, QubicaAMF Worldwide, Round One Entertainment, Steltronic, Brunswick Bowling Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bowling Centers Market Emerging Trajectories
Digital reservation platforms and camera-based scoring systems are compressing the gap between recreational and competitive bowling experiences, while regulatory pressure on accessibility and safety standards accelerates capital deployment toward modernization.
Camera-based automated scoring is automating pin detection and frame recording with precision that eliminates manual error and enables instant replay features for league validation. Multi-attraction entertainment complexes are deploying these systems fastest, using the technology to support tournament broadcasting and social media integration. The shift is automating back-of-house labor requirements while compressing the skill threshold for competitive participation.
OSHA workplace safety standards and state-level amusement venue regulations are tightening inspection protocols for pinsetter machinery and lane surface conditions. Operators face expanded documentation requirements for maintenance logs and incident reporting. Facilities in California and New York are responding with dedicated compliance personnel and third-party audit contracts to preempt enforcement actions.
Corporate procurement of entertainment venues is consolidating around multi-year exclusive agreements with integrated complexes rather than transactional lane rentals. Human resources departments are replacing ad-hoc team-building bookings with contracted league programs that guarantee recurring revenue. This pattern is most visible in Texas and Illinois metropolitan corridors where employer density supports volume commitments.
Bowling Centers Market Segmentation
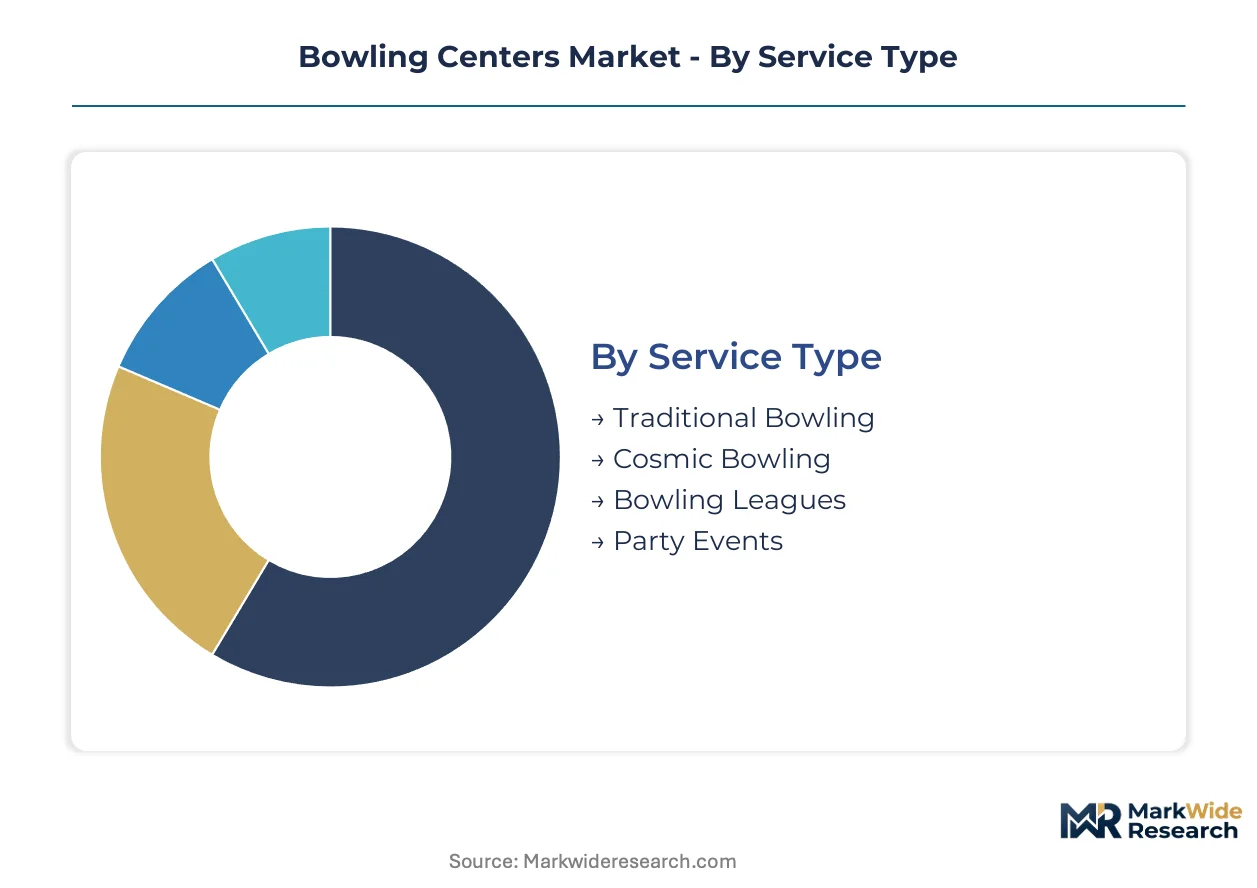
Segmentation in bowling centers reveals how revenue pools concentrate across experience tiers rather than simple lane counts. Operators configure service mixes, customer targeting, and facility formats to capture differentiated margin profiles in an increasingly stratified competitive landscape.
Service Type:
Customization ranges from standardized lane rentals to highly programmed experiential formats requiring specialized lighting, sound systems, and event coordination infrastructure.
- Traditional Bowling:Standard ten-pin gameplay on maple or synthetic lanes with manual or automated scoring. Demand concentrates in suburban markets where families and league bowlers prioritize consistency and value pricing over atmospheric effects.
- Cosmic Bowling:Blacklight-enhanced sessions with fluorescent pins, laser effects, and curated music playlists. Young adult segments in Texas and Florida metropolitan areas drive this format's expansion, with venues reporting extended dwell times and premium pricing acceptance during evening sessions.
- Bowling Leagues:Organized competitive play with scheduled seasons, handicapping systems, and prize structures. Corporate procurement departments in Illinois and Ohio metropolitan corridors are contracting multi-year league programs to secure guaranteed weekday lane utilization.
- Party Events:Packaged celebrations incorporating lane reservations, catering, and dedicated event coordination. Children's birthday segments dominate volume, though adult milestone celebrations command higher per-capita spend in entertainment complex settings.
Leading the category by volume: Traditional Bowling. Growing fastest: Cosmic Bowling.
Customer Type:
Margin profiles diverge sharply between high-frequency, price-sensitive segments and occasional, experience-seeking spenders willing to pay premium rates.
- Families:Multi-generational groups with children under 18, typically visiting during weekend daytime slots. This segment anchors baseline lane utilization but exhibits high price elasticity, pushing operators toward value-menu food and beverage bundling.
- Young Adults:Individuals aged 21-34 seeking social entertainment venues as alternatives to traditional nightlife. California and Florida operators are retrofitting facilities with craft beverage programs and lounge seating to capture this segment's higher per-visit spend.
- Seniors:Retired bowlers participating in daytime leagues and discounted matinee sessions. Morning lane availability and specialized equipment (lighter balls, ramp-assisted delivery) shape facility design requirements for this loyal, high-frequency cohort.
- Corporate Groups:Employer-sponsored team-building events and recreational leagues. Human resources departments in Texas metropolitan areas are shifting from transactional bookings to contracted annual programs that guarantee recurring revenue and predictable capacity planning.
Volume leadership rests with Families. Steepest expansion trajectory belongs to Corporate Groups.
Facility Type:
Real estate intensity and capital deployment scale separate purpose-built bowling venues from multi-attraction complexes sharing infrastructure across entertainment categories.
- Standalone Centers:Single-use facilities with 24-40 lanes, parking-optimized suburban locations, and limited ancillary revenue streams. These operations face margin compression from rising property taxes and labor costs in mature markets.
- Bowling Alleys:Traditional lane-focused venues with basic food service and limited arcade integration. Midwestern and Southeastern states retain concentration of this format, though renovation cycles lag accessibility mandates.
- Entertainment Complexes:Multi-attraction venues combining bowling with arcades, laser tag, escape rooms, and full-service dining. Texas, Florida, and California operators are deploying this format to capture extended dwell time and cross-selling opportunities across customer segments.
- Recreation Centers:Municipal or nonprofit facilities incorporating bowling as one component within broader community fitness and programming missions. These sites operate under distinct subsidy and pricing structures, often serving as entry points for youth league development.
Entertainment Complexes command the highest revenue per square foot. Standalone Centers are contracting in count.
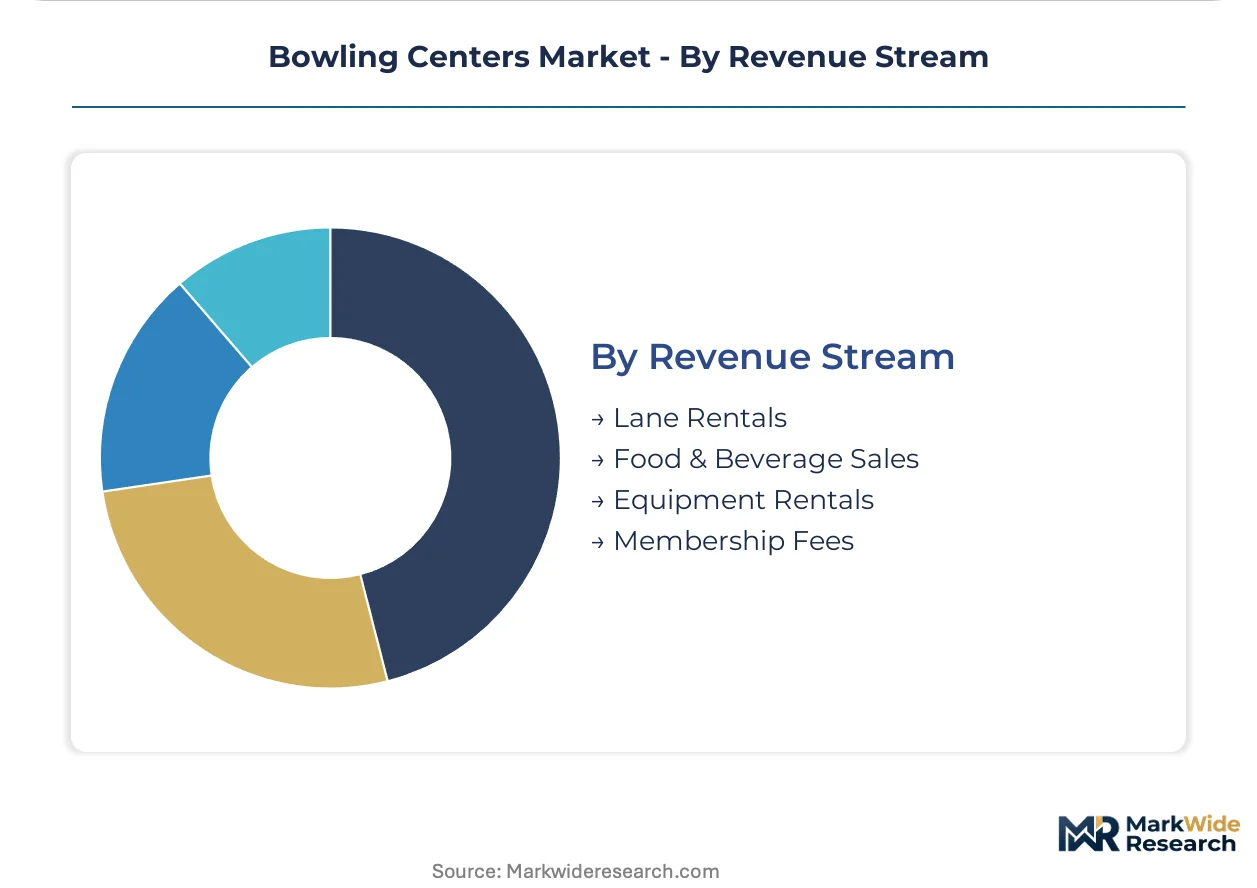
Revenue Stream:
Operational complexity increases as centers diversify beyond lane rentals into perishable inventory management and subscription-based recurring revenue models.
- Lane Rentals:Time-based lane access charges, the foundational revenue unit. Dynamic pricing algorithms are displacing flat-rate structures, with Texas operators testing surge pricing for peak cosmic bowling sessions.
- Food & Beverage Sales:On-premise dining and alcohol service capturing margin pools unavailable to lane-only competitors. California's alcohol licensing friction constrains this stream's growth in many municipalities.
- Equipment Rentals:Shoe rental fees and premium ball access charges. This high-margin, low-variable-cost stream supports profitability during promotional lane pricing periods.
- Membership Fees:Monthly subscriptions offering unlimited lane access, priority reservations, and merchandise discounts. Young adult segments in Florida are showing strongest adoption of this recurring revenue model.
Lane Rentals still generates the largest absolute dollar volume. Membership Fees are climbing the fastest as operators seek predictable cash flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American venue development, with entertainment complexes clustering along the I-10 corridor and Energy Corridor submarkets where corporate procurement budgets sustain multi-year league contracts.
United States
Texas, Florida, and California concentrate new entertainment complex openings, with Dallas-Fort Worth and Miami metropolitan areas leading square footage additions. OSHA workplace safety standards and ADA Title III accessibility mandates accelerate renovation cycles for aging suburban lanes. Corporate procurement departments in Chicago and Houston are shifting from transactional bookings to contracted annual programs.
Canada
Toronto and Vancouver metropolitan areas drive premium-format venue development, with young adult segments accepting higher per-visit spend for cosmic bowling and craft beverage integration. Provincial alcohol licensing boards in Ontario and British Columbia impose operating hour constraints that limit late-night revenue capture. Calgary's Beltline district hosts emerging multi-attraction complexes targeting weekday corporate utilization.
United Kingdom
London and Manchester anchor estate-scale venue networks, with operators retrofitting historic industrial buildings into entertainment complexes. Health and Safety Executive regulations govern pinsetter machinery inspection protocols and lane surface maintenance documentation. Birmingham's Digbeth regeneration zone attracts capital deployment for integrated food, beverage, and gaming concepts.
Germany
Bavaria and North Rhine-Westphalia retain concentration of traditional lane-focused venues, though Berlin and Hamburg operators are testing multi-attraction formats. CE marking requirements and regional workplace safety ordinances mandate certified technician presence for automated scoring system maintenance. Munich's Sendling district exemplifies the retrofit challenge of integrating modern accessibility ramps into 1970s-era facilities.
Japan
Tokyo and Osaka metropolitan areas sustain high lane utilization through dense urban populations, with Round One Entertainment complexes capturing extended dwell time. METI industrial standards and local fire codes constrain site selection for new construction in central business districts. Yokohama's Minato Mirai waterfront district demonstrates premium pricing power for venues combining bowling with karaoke and dining concepts.
Bowling Centers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the experience-versus-transaction dimension, with integrated entertainment complexes commanding revenue per square foot multiples of standalone lane operations. The vendor base organizes into three tiers: estate-scale multi-attraction developers, equipment technology suppliers, and regional lane-rental operators. Consolidation pressure favors acquisition of undercapitalized standalone centers by integrated complex developers. Technology licensing agreements and strategic partnerships dominate competitive moves, with equipment suppliers embedding scoring systems into venue management platforms.
Within the estate-scale developer tier, Hollywood Bowl Group and Main Event Entertainment exemplify the integrated complex archetype, while Brunswick Bowling Products occupies a position bridging equipment supply and venue technology integration. These three anchors demonstrate how capital deployment favors multi-attraction formats over lane-rental commodity operations.
| Leading Market Players |
|---|
| Hollywood Bowl Group |
| Main Event Entertainment |
| Lucky Strike Entertainment Corporation |
| Switch Bowling |
| Ten Entertainment Group |
| QubicaAMF Worldwide |
| Round One Entertainment |
| Steltronic |
| Brunswick Bowling Products |
| Others |
Supply Flow & Price Mechanics
Corporate procurement departments shifting toward multi-year contracted league programs are forcing lane operators to bundle fixed-price guarantees with food and beverage minimums, compressing margin flexibility and tethering pricing power to ancillary revenue capture.
Pricing Analysis
Per-visit spend anchored to dwell time and cross-category consumption sets the value-based pricing foundation for entertainment complexes. Three-tier pricing structure across premium cosmic bowling sessions, standard league rates, and economy daytime matinees segments the customer base by occasion type. Cost compression in the standalone center tier is intensifying because families exhibit high price elasticity and readily substitute toward discounted lane rental promotions. Young adult segments at integrated complexes show lowest price sensitivity, accepting surge pricing for peak evening slots.
Supply Chain Analysis
Direct-to-venue equipment installation channels handle large-format entertainment complex deployments, while regional distributors serve retrofit and maintenance demand for standalone operators. North American maple hardwood suppliers, Chinese synthetic lane surface manufacturers, and German pinsetter electronics producers concentrate critical component sourcing. Supply chain vulnerability rests on single-source dependency for certified lane conditioning machines and specialized pin detection camera modules. Distribution runs through Brunswick Bowling Products and QubicaAMF Worldwide for integrated scoring systems, with secondary parts flowing via certified technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around multi-attraction entertainment complexes, with ADA renovation mandates and corporate procurement centralization squeezing undercapitalized standalone operators toward acquisition or exit.
For Market Incumbents: Cement estate-scale positioning by acquiring distressed suburban lane assets in Texas and Florida corridors for conversion into integrated complexes. Prioritize backward integration into in-house food service operations to capture margin pools currently leaking to third-party caterers. Lock in multi-year corporate league contracts before competitors can match bundled pricing.
For New Entrants and Emerging Players: Mid-sized metropolitan areas in the US Southeast present whitespace for modern entertainment complex development, with Nashville and Raleigh-Durham showing particular underpenetration. Target employer wellness program managers with turnkey league management platforms that guarantee weekday lane utilization. Lead with automated scoring and mobile reservation technology as differentiated entry points.
For Investors and Strategic Acquirers: The window for entry favors regional lane-rental operators with underutilized real estate footprints and renovation-ready suburban locations. Long-term viability hinges on conversion potential to multi-attraction formats rather than standalone lane economics. Monitor corporate procurement RFP volumes as the inflection signal for contracted revenue expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Attraction Complex Conversion | Captures extended dwell time and cross-selling revenue across bowling, dining, and gaming segments. |
| Corporate League Contracting | Guarantees recurring weekday lane utilization and reduces revenue volatility from transactional bookings. |
| Automated Scoring Integration | Enables real-time tournament broadcasting and mobile app engagement for young adult segments. |
| ADA Accessibility Retrofit | Preempts enforcement action and unlocks municipal incentive programs for facility modernization. |
| Certified Technician Network Expansion | Reduces service response times and captures aftermarket maintenance revenue from competitor installations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with bowling center operators, equipment manufacturer sales directors, corporate event procurement managers, and municipal licensing officials. Financial disclosures from Hollywood Bowl Group and Main Event Entertainment, state amusement tax code compilations, and OSHA enforcement databases provided validation layers. Bottom-up lane count and revenue-per-square-foot estimates triangulated against top-down metropolitan market sizing.
Segment-level granularity modeled facility type, service format, customer archetype, and revenue stream dimensions across the analysis window. CAGRs derived from regression against population density, corporate employer counts, and entertainment spending indices. Bowling league participation rates and alcohol licensing restrictiveness served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to corporate real estate relocation patterns and municipal zoning amendments. Projections reflect assumptions regarding sustained young adult preference for experiential entertainment over traditional retail. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
US Restaurant Management Market