
 US Hedge Fund Market | 2026-2036
US Hedge Fund Market Size, Share, and Industry Trends Forecast 2026-2036
US Hedge Fund Market Insights
The split between premium multi-strategy platforms and commodity single-strategy offerings is hardening in the US hedge fund landscape. Millennium Management leverages its pod-based structure to sustain diversified alpha generation across asset classes. Citadel Advisors anchors its position through captive prime brokerage and technology infrastructure. Bridgewater Associates differentiates via systematic macro processes and risk parity frameworks.
A hedge fund constitutes an investment vehicle pooling capital from accredited or institutional investors to deploy active strategies across public and private markets, typically charging management fees near 2% and performance fees near 20% while targeting absolute returns uncorrelated to benchmark indices. Long/Short Equity commands mature capital deployment with established margin compression, while Event-Driven strategies occupy expanding niche opportunities in corporate restructurings. Institutional Investors dominate capital flows, though Family Offices represent the fastest-growing allocator segment seeking customized exposure.
SEC oversight through Form ADV and Form PF disclosures shapes operational transparency requirements, while CFTC regulations govern derivatives positioning and commodity pool operator status. The Investment Advisers Act of 1940, as amended by Dodd-Frank, defines registration thresholds and reporting obligations for managers exceeding $150 million in assets under management. Stakeholders must monitor evolving private fund adviser rules and potential changes to accredited investor definitions that could reshape capital access.
Market Dynamics
The US hedge fund market is undergoing structural recalibration as SEC private fund adviser rules intensify compliance burdens while pension fund allocations to alternative strategies deepen. Fee compression and operational scale requirements are forcing business model bifurcation between institutional-scale platforms and specialized boutiques.
Growth Catalysts
- Form PF Transparency Mandates:Enhanced disclosure requirements under SEC rules are accelerating institutional capital flows toward compliant managers with robust operational infrastructure.
- Pension Fund Reallocation:Public and corporate pension systems are expanding target allocations to hedge fund strategies as fixed income yields remain structurally compressed.
- Quantitative Infrastructure:Cloud-based data analytics and machine learning platforms are democratizing systematic strategy deployment across mid-sized managers.
Market Restraints
- Prime Brokerage Concentration:Custody and financing services cluster among three major Wall Street banks, creating counterparty vulnerability during stress events.
- Accredited Investor Threshold Rigidity:SEC definitions restricting retail access cap the addressable investor base below mass-affluent wealth segments.
- Fee Compression Mechanics:Passively managed alternatives and liquid alts products are eroding traditional two-and-twenty economics across single-strategy offerings.
Strategic Opportunities
- Texas and Florida Wealth Migration:High-net-worth relocations to no-income-tax states are creating new family office clusters outside traditional Northeast corridors.
- Insurance-Linked Securities:Catastrophe bond and reinsurance strategies offer uncorrelated return profiles attracting institutional liability-driven investors.
- Registered Fund Structures:40-Act interval and tender offer funds are opening hedge fund exposure to broader accredited investor pools through simplified compliance pathways.
Industry Challenges
- Quantitative Talent Scarcity:PhD-level data science and signal-generation expertise commands premium compensation, squeezing mid-tier manager economics.
- Operational Due Diligence Intensity:Institutional investors now require 12-18 month track records and third-party administrator verification before capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hedge Fund Market |
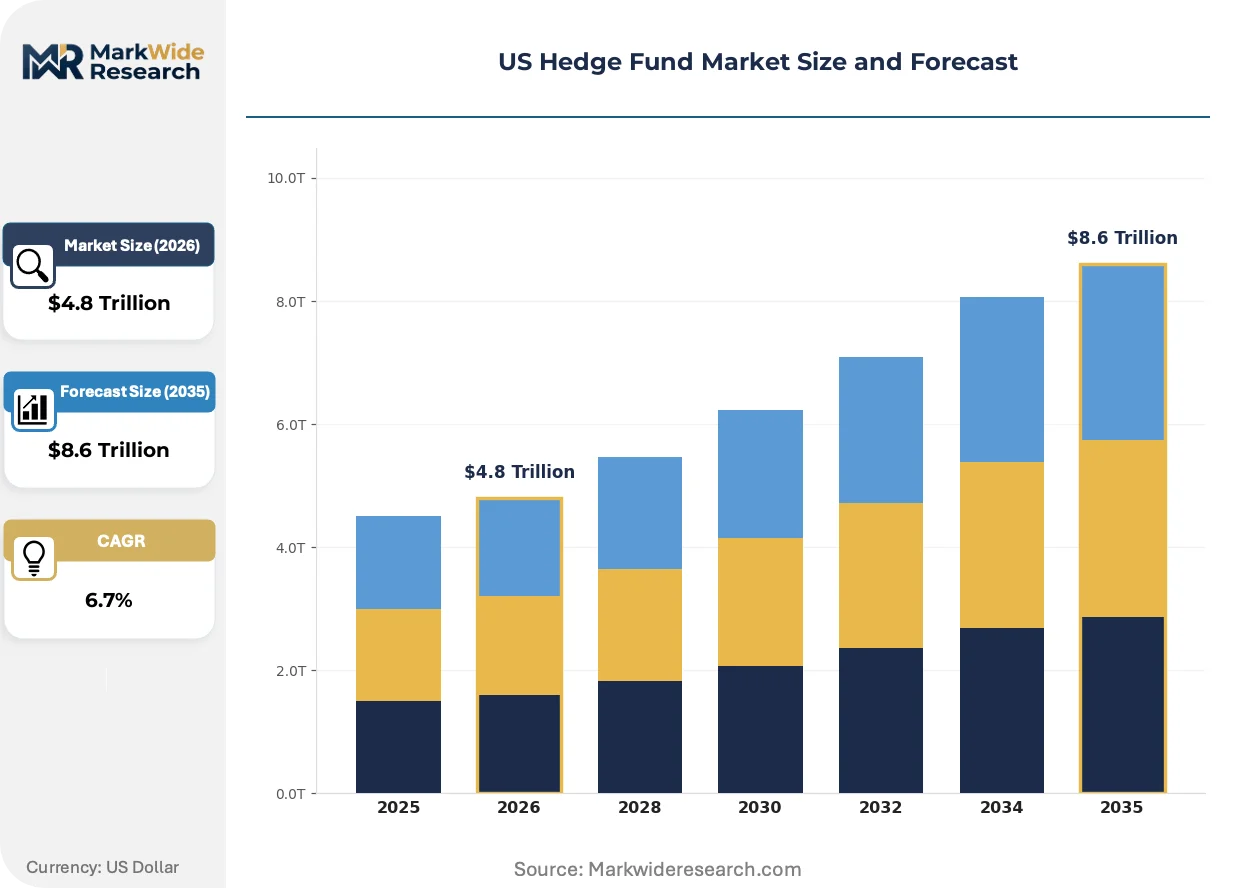
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $8.6 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Long/Short Equity, Global Macro, Event-Driven, Relative Value Fund Structure: Offshore Funds, Onshore Funds, Master-Feeder Structure, Single Manager Investor Type: Institutional Investors, High-Net-Worth Individuals, Family Offices, Pension Funds Asset Class: Equities, Fixed Income, Commodities, Alternatives |
| Companies Covered | Millennium Management, Citadel Advisors, Bridgewater Associates, Renaissance Technologies, D.E. Shaw & Co., Two Sigma Investments, Elliott Investment Management, AQR Capital Management, Point72 Asset Management, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hedge Fund Market Trends and Innovations
Technology and regulatory adaptation are compressing traditional hedge fund operating models while creating new competitive axes. Managers are reconfiguring around data infrastructure, regulatory technology, and alternative capital channels.
Machine learning-driven signal generation is rewriting alpha extraction across systematic strategies. Multi-strategy platforms are deploying natural language processing for earnings call sentiment analysis at scale. This capability compression is forcing discretionary managers to demonstrate differentiated sourcing or exit liquid equity markets entirely.
SEC private fund adviser rule amendments are restructuring disclosure and audit requirements for US-domiciled funds. Quarterly statement standardization and adviser-led secondaries restrictions are elevating operational costs. Smaller managers are responding through sub-advisory arrangements or conversion to exempt reporting adviser status where thresholds permit.
Family offices are consolidating discretionary hedge fund relationships around five-to-seven core manager partnerships rather than fifteen-plus fund portfolios. This concentration is displacing fund-of-funds intermediaries and driving direct co-investment demands. The pattern is most pronounced among multi-generational offices in California and Texas managing generational wealth transitions.
US Hedge Fund Market Segmentation
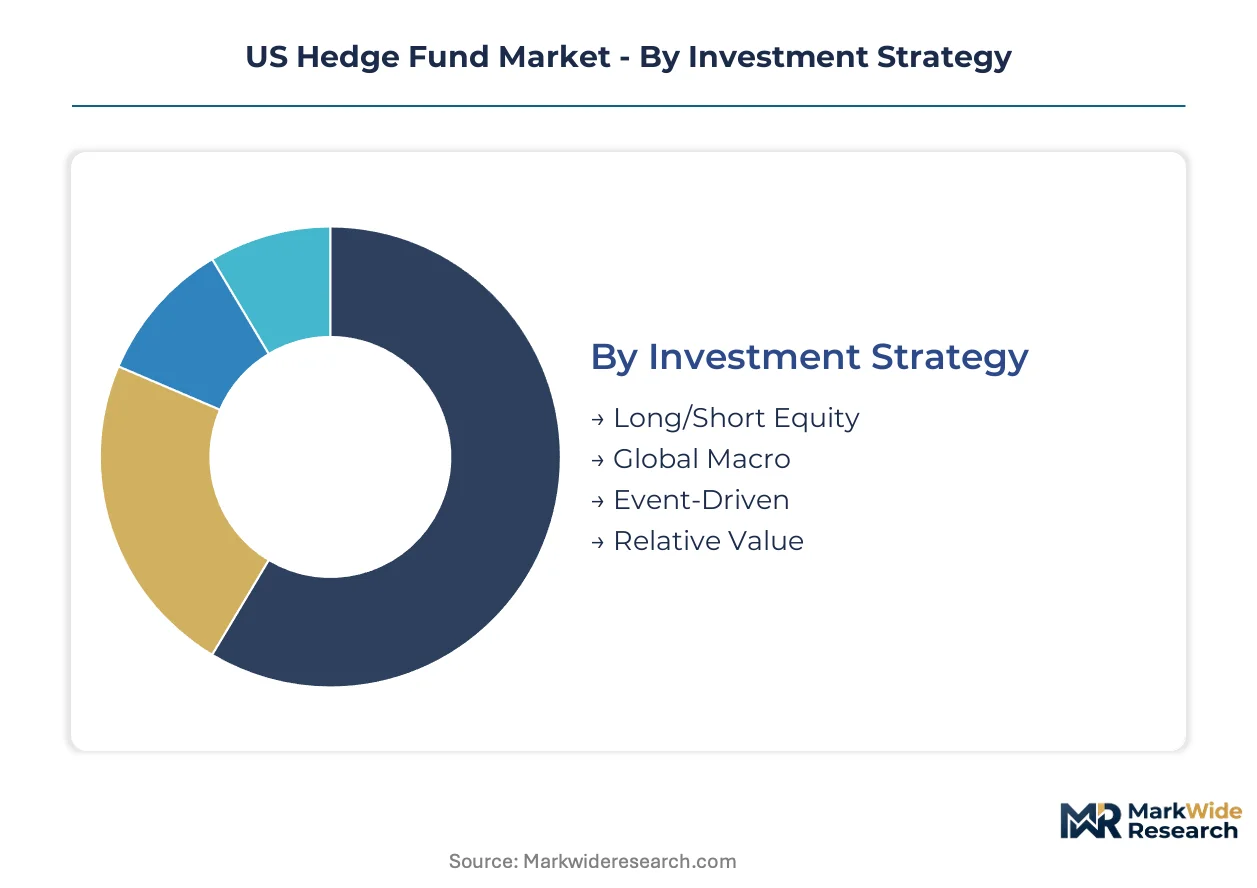
US hedge fund segmentation reveals how capital flows, regulatory structures, and investor sophistication create distinct operational requirements. Each dimension shapes manager infrastructure, fee negotiations, and distribution channels differently.
Investment Strategy:
Strategy differentiation determines fee structures, liquidity terms, and the talent pools managers must access.
- Long/Short Equity:Pairs long positions in undervalued securities against short sales in overvalued equities, deploying fundamental or quantitative stock selection. Capital concentrates among established managers in New York and Connecticut, though fee compression from liquid alternatives is eroding traditional economics.
- Global Macro:Positions across currencies, rates, and sovereign instruments based on macroeconomic forecasting and geopolitical analysis. Bridgewater Associates and similar systematic macro platforms anchor institutional allocations, with demand strengthening as inflation volatility persists.
- Event-Driven:Exploits corporate restructurings, mergers, and distressed situations. Merger arbitrage and special situations desks at multi-strategy platforms capture flows as deal activity cycles.
- Relative Value:Identifies pricing discrepancies between related securities while maintaining market-neutral exposure. Convertible arbitrage and fixed income relative value strategies attract liability-driven investors seeking uncorrelated returns.
Volume sits with Long/Short Equity; growth tilts toward Global Macro.
Fund Structure:
Structural choices reflect tax optimization goals, investor domicile patterns, and SEC registration thresholds.
- Offshore Funds:Cayman Islands and Bermuda-domiciled vehicles serving non-US taxable investors and tax-exempt entities. These structures dominate capital from European and Asian institutions seeking US exposure without immediate tax recognition.
- Onshore Funds:Delaware limited partnerships and LLCs subject to SEC oversight and US tax jurisdiction. Pension funds and taxable US institutions favor these for regulatory transparency and operational familiarity.
- Master-Feeder Structure:Parallel offshore and onshore feeders pooling into a single master fund for consolidated portfolio management. This architecture minimizes operational duplication while accommodating diverse investor tax profiles.
- Single Manager:Standalone funds without feeder complexity, typical of emerging managers below $500 million in assets. Lower administrative overhead appeals to specialized boutiques in Texas and Florida.
Capital aggregates through Master-Feeder structures; formation rates are climbing fastest for Onshore Funds.
Investor Type:
Investor category dictates minimum commitments, due diligence intensity, and customization demands.
- Institutional Investors:Endowments, foundations, and sovereign wealth funds deploying $50 million-plus tickets. These allocators require third-party administrator verification and 12-18 month track records before deployment.
- High-Net-Worth Individuals:Accredited investors meeting SEC thresholds through personal wealth or income tests. Direct platform access is expanding through registered fund structures and lower minimums.
- Family Offices:Single and multi-family offices consolidating around five-to-seven core manager relationships. Texas and Florida offices are displacing traditional Northeast concentration as wealth migration accelerates.
- Pension Funds:Public and corporate systems expanding target allocations as fixed income yields remain compressed. CalPERS and similar large systems drive fee negotiation leverage across the industry.
Deployment volume concentrates with Pension Funds; Family Offices are expanding most quickly.
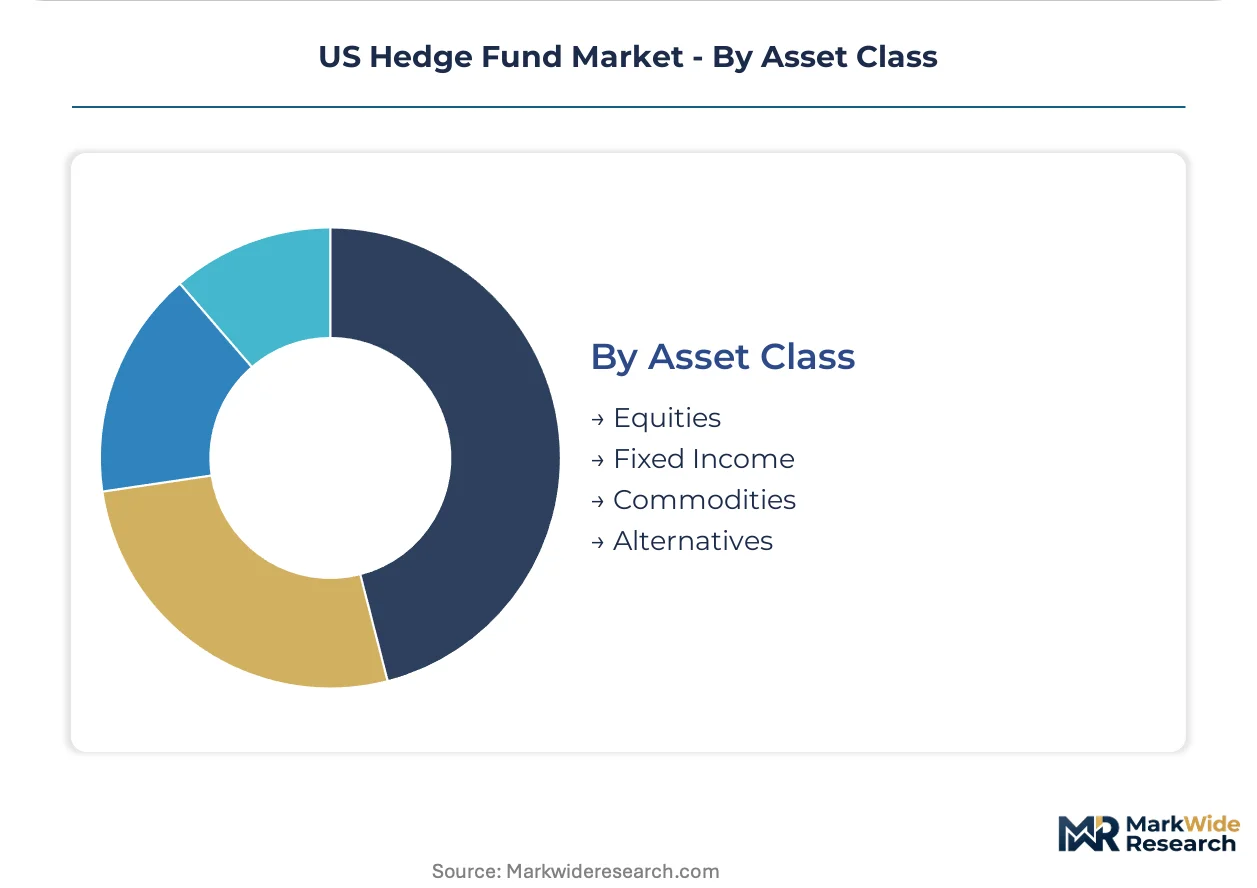
Asset Class:
Asset class exposure shapes prime brokerage relationships, data infrastructure requirements, and regulatory filings.
- Equities:Long/short and market-neutral strategies across developed and emerging markets. Commission compression and alternative trading systems are eroding traditional equity strategy margins.
- Fixed Income:Rates, credit, and structured product strategies benefiting from volatility in Treasury and corporate bond markets. CFTC registration requirements apply to many derivatives-heavy approaches.
- Commodities:Energy, metals, and agricultural exposure through futures, swaps, and physical holdings. CPO and CTA designations trigger specific disclosure obligations under CFTC rules.
- Alternatives:Private credit, real estate, and insurance-linked securities offering return streams uncorrelated to traditional markets. Catastrophe bonds and reinsurance strategies attract institutional liability-driven investors.
Capital deployment favors Equities; steepest expansion trajectory belongs to Alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manhattan's Midtown corridor anchors US hedge fund concentration, with Greenwich and Stamford extending the metropolitan footprint into Connecticut. Texas and Florida are capturing accelerating manager migration and family office formation.
New York Metro
Pension fund capital deployment and prime brokerage infrastructure concentrate hedge fund activity in Manhattan and Greenwich. SEC Form PF disclosure requirements and Investment Advisers Act registration thresholds shape compliance architecture for managers domiciled here. Midtown Manhattan hosts Millennium Management and Citadel Advisors, while Stamford's Greenwich corridor sustains pod-based multi-strategy platforms.
Texas Triangle
High-net-worth migration and zero state income tax are accelerating family office formation across Dallas, Houston, and Austin. Texas regulatory environment defers to federal SEC oversight without layering additional state-level investment adviser requirements. Dallas-Fort Worth corridor is attracting emerging manager spinouts from Northeast platforms seeking operational cost arbitrage.
Florida Gold Coast
Wealth relocation from New York and Connecticut is clustering family offices and single-manager boutiques in Miami and Palm Beach. Florida's absence of personal income tax and homestead protections align with multi-generational wealth preservation objectives. Miami's Brickell financial district is developing prime brokerage service outposts to support local manager infrastructure.
California Coastal
Technology crossover strategies and quantitative talent pipelines from Stanford and Berkeley sustain Bay Area hedge fund formation. California Department of Financial Protection and Innovation coordinates with SEC on state-registered adviser examinations. Silicon Valley family offices are deploying direct co-investment capital into quantitative and systematic strategies.
Chicago Metro
Commodities trading heritage and CFTC regulatory proximity sustain derivatives-focused managers in Chicago and its northern suburbs. CFTC registration requirements for commodity pool operators and commodity trading advisors apply to strategies with significant futures exposure. The Loop and North Shore suburbs host relative value and fixed income specialists with exchange connectivity.
US Hedge Fund Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fee structure and operational scale dimensions. The US hedge fund market bifurcates between institutional-scale multi-strategy platforms with captive infrastructure and specialized single-strategy boutiques. Three archetypes dominate: pod-based multi-strategy operators with internalized prime services, systematic quantitative platforms with heavy technology investment, and event-driven specialists with concentrated activist positions. Competitive moves center on talent acquisition from rival platforms and technology infrastructure buildout to reduce external vendor dependence.
Within the multi-strategy tier, Millennium Management and Citadel Advisors exemplify pod-based architectures with diversified alpha generation across asset classes. Bridgewater Associates occupies a distinct position in systematic macro and risk parity frameworks. These three anchors represent divergent approaches to scale, technology deployment, and investor access structures.
| Leading Market Players |
|---|
| Millennium Management |
| Citadel Advisors |
| Bridgewater Associates |
| Renaissance Technologies |
| D.E. Shaw & Co. |
| Two Sigma Investments |
| Elliott Investment Management |
| AQR Capital Management |
| Point72 Asset Management |
| Others |
Pricing and Supply Chain Analysis
Pension fund fee compression mandates are forcing managers to absorb operational costs internally or surrender margin, compelling supply chain reconfiguration toward captive infrastructure and technology ownership rather than outsourced vendor relationships.
Pricing Analysis
Performance-linked fee structures anchor value-based pricing across the US hedge fund landscape, with management fees compressing toward 1% and incentive fees resetting to 15% for institutional mandates. Price differentiation rests on track record length and operational infrastructure certification, while liquid alternatives erode traditional two-and-twenty economics. Fee pressure intensifies as pension funds consolidate manager relationships and demand fee holidays for seed capital. Single-strategy boutiques exhibit highest price sensitivity; multi-strategy platforms with captive prime brokerage maintain pricing power.
Supply Chain Analysis
Quantitative talent scarcity in New York and Connecticut constrains strategy deployment capacity, forcing managers to expand recruiting pipelines to Austin, Miami, and Chicago. Technology infrastructure draws from cloud computing providers, alternative data vendors, and proprietary signal-generation platforms. Single-source vulnerability concentrates in prime brokerage relationships among three Wall Street banks. Distribution runs through institutional consultant channels, family office direct relationships, and registered fund platforms for accredited investor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SEC compliance cost escalation is accelerating consolidation, eliminating sub-scale managers unable to sustain Form PF reporting and audit infrastructure investments.
For Market Incumbents: Hedge operational risk through captive prime brokerage buildout or strategic partnerships with technology vendors, countering fee compression from liquid alternatives. Deepen vertical integration into data infrastructure and signal-generation capabilities to reduce external vendor dependence and defend margin position. For New Entrants and Emerging Players: Capture white-space opportunity in Texas and Florida family office formation, where wealth migration creates allocator base expansion outside saturated Northeast corridors. Target insurance-linked securities strategies for liability-driven investors seeking uncorrelated return profiles, deploying through simplified registered fund structures. For Investors and Strategic Acquirers: The window for entry favors systematic quantitative platforms with proven infrastructure and established institutional relationships. Long-term viability hinges on technology ownership and talent retention architecture. Monitor SEC private fund adviser rule implementation pace as inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Prime Brokerage Buildout | Internalized financing and custody reduces counterparty exposure to Wall Street bank concentration. |
| Cloud Infrastructure Migration | Scalable data analytics platforms democratize systematic strategy deployment for mid-sized managers. |
| Quantitative Talent Acquisition | PhD-level signal-generation expertise commands premium compensation and drives competitive differentiation. |
| Registered Fund Structure Launch | 40-Act interval funds open hedge fund exposure to broader accredited investor pools through simplified compliance. |
| Family Office Direct Relationship | Consolidation around five-to-seven core managers displaces fund-of-funds intermediaries and drives co-investment. |
Research Methodology
Independent corroboration across portfolio manager interviews, institutional allocator discussions, and regulatory compliance officer consultations underwrites the qualitative findings in this study. Primary fieldwork engaged fund-of-funds strategists, prime brokerage relationship managers, and SEC examination staff alongside secondary validation through Form ADV filings, Form PF disclosure databases, and Investment Advisers Association membership records. Bottom-up manager surveys and top-down pension fund allocation data triangulate market sizing.
Comparable-period anchoring to historical AUM flows and fee structure evolution frames the projection horizon across the analysis window. Segmentation modeling incorporates investment strategy, fund structure, investor type, and regional domicile patterns. CAGRs derive from regression analysis of capital deployment velocity, regulatory cost trajectories, and alternative return premium persistence. Forecast inputs include pension fund reallocation targets and quantitative infrastructure investment cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SEC accredited investor definition changes and prime brokerage consolidation events. Material deviation in regulatory implementation timelines or counterparty stress events warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Denmark POS Terminals Market
Investment Analysis and Financial Strategies
United Kingdom Payment Market
Investment Analysis and Financial Strategies
Financial App Market
Investment Analysis and Financial Strategies
China Trade Finance Market
Investment Analysis and Financial Strategies
Cloud AI in Fintech Market
Investment Analysis and Financial Strategies
Japan Data Analytics in Banking Market
Investment Analysis and Financial Strategies
Disclosure Management Market
Investment Analysis and Financial Strategies
Digital Transaction Management Market
Investment Analysis and Financial Strategies
Japan Parametric Insurance Market
Investment Analysis and Financial Strategies
United Kingdom Accounting Software Market
Investment Analysis and Financial Strategies
E-Scooter Financing Market
Investment Analysis and Financial Strategies
Financial Risk Management Software Market
Investment Analysis and Financial Strategies
Italy Gift Cards Market
Investment Analysis and Financial Strategies
China Home Loan Market
Investment Analysis and Financial Strategies
Asia-Pacific Payment Gateway Market
Investment Analysis and Financial Strategies
Middle East and Africa Private Equity Market