
 Middle East and Africa Private Equity Market | 2026-2036
Middle East and Africa Private Equity Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Private Equity Market Foresight
Local fund management talent scarcity is redrawing deployment timelines across the Middle East and Africa. Investcorp leverages its Bahrain headquarters to sustain cross-border deal flow between Gulf sovereign capital and North African targets. Actis anchors its competitive position through specialized energy and infrastructure mandates in Egypt and Nigeria. Helios Investment Partners dominates growth-stage allocations across Francophone West Africa through on-ground investment teams.
Private equity denotes pooled capital investment into non-publicly traded companies, typically structured as limited partnerships with ten-to-twelve-year fund lives and carried-interest compensation for general partners. The asset class generates returns through operational improvements, financial engineering, and eventual exit via trade sale or secondary buyout. Buyout and growth-stage funds currently capture the majority of committed capital in the region, while technology and healthcare verticals attract premium valuations due to structural underinvestment in prior decades. Mega funds face deployment constraints as deal flow in target markets remains fragmented across multiple jurisdictions with varying legal frameworks.
The Dubai Financial Services Authority and the Financial Sector Conduct Authority in South Africa impose divergent disclosure and investor protection standards that complicate pan-regional fundraising. Saudi Arabia's Capital Market Authority has relaxed qualified investor thresholds, directly expanding the eligible limited partner base for domestic fund managers. Stakeholders must monitor evolving sharia compliance requirements alongside conventional regulatory developments as Islamic finance structures gain share in Gulf fundraising.
Market Dynamics
Sovereign wealth fund capital deployment into technology verticals is restructuring deal flow patterns across the Middle East and Africa, compressing traditional fundraising cycles and elevating sharia-compliant structures as a prerequisite for Gulf-based limited partner access.
Growth Catalysts
- Vision 2030 diversification mandates:Saudi Arabia's economic transformation agenda redirects sovereign capital toward private markets, creating dedicated allocation pools for domestic fund managers targeting non-oil sectors.
- Fintech regulatory sandboxes:The UAE's DFSA framework accelerates licensing timelines for digital payment platforms, enabling venture capital deployment into previously restricted financial services segments.
- Healthtech infrastructure gaps:Chronic underinvestment in Sub-Saharan African healthcare delivery systems generates acquisition opportunities for growth-stage funds specializing in hospital networks and pharmaceutical distribution.
Market Restraints
- Local currency volatility:Nigerian naira and Egyptian pound depreciation erodes dollar-denominated returns for offshore limited partners, forcing hedging costs into fund structures.
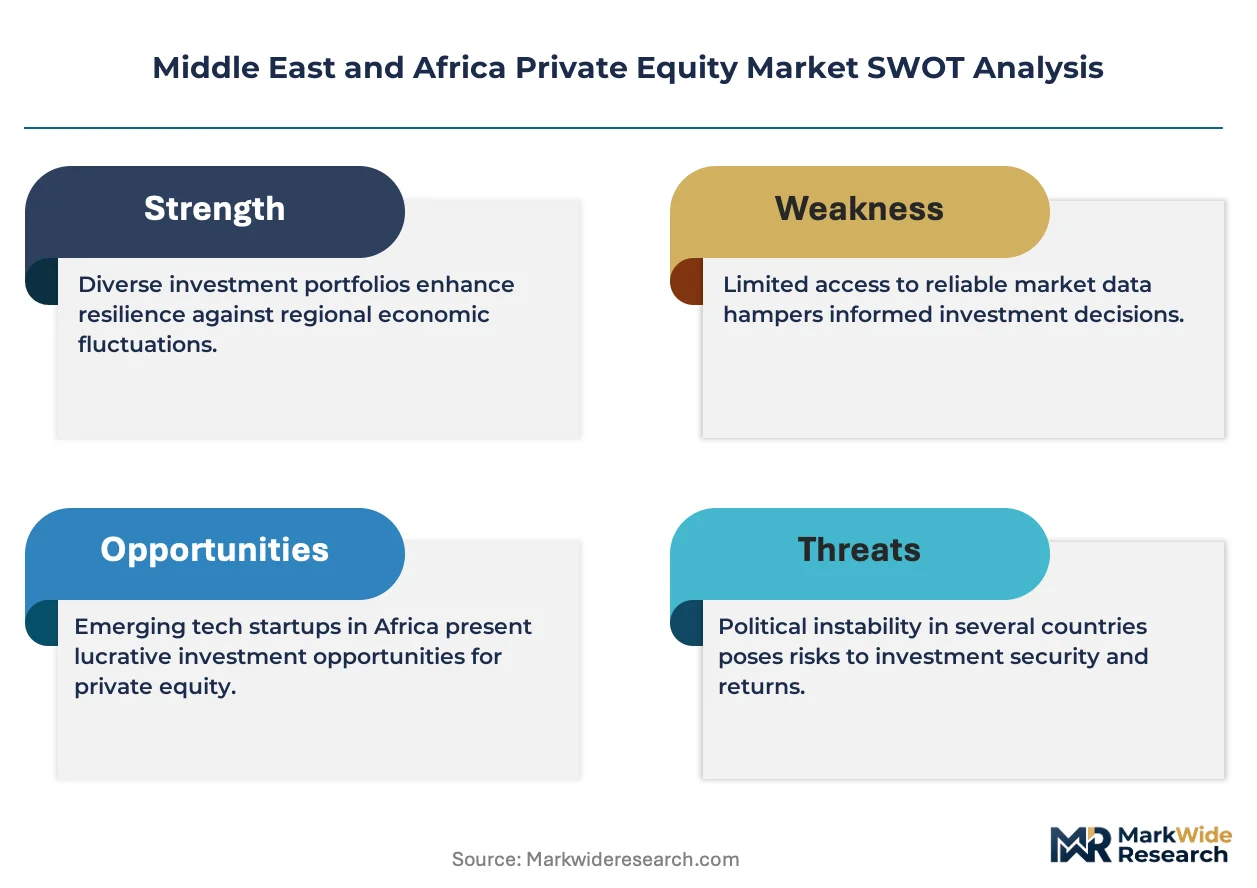
- Legal framework fragmentation:Divergent commercial codes across Francophone and Anglophone African jurisdictions multiply transaction documentation complexity and enforcement risk.
- Secondary market illiquidity:Absence of organized limited partner stake exchanges in the Gulf extends fund lifelines beyond standard ten-to-twelve-year horizons.
Strategic Opportunities
- Kenya's growth-stage ecosystem:Nairobi's concentration of mobile money infrastructure and technical talent creates venture-scale entry points for East African expansion.
- Islamic finance convergence:Sukuk issuance frameworks in Bahrain and Malaysia enable sharia-compliant fund structures that access dual-source capital pools.
- Renewable energy offtake agreements:Egypt's feed-in tariff mechanisms for solar and wind projects generate contracted revenue streams attractive to infrastructure specialists.
Industry Challenges
- Investment professional scarcity:Experienced deal originators with regional language capabilities and sector expertise command compensation premiums that compress management fee margins.
- Portfolio company governance gaps:Founder-managed enterprises in Nigeria and Kenya often lack standardized financial reporting systems, extending due diligence timelines and post-acquisition integration requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Private Equity Market |
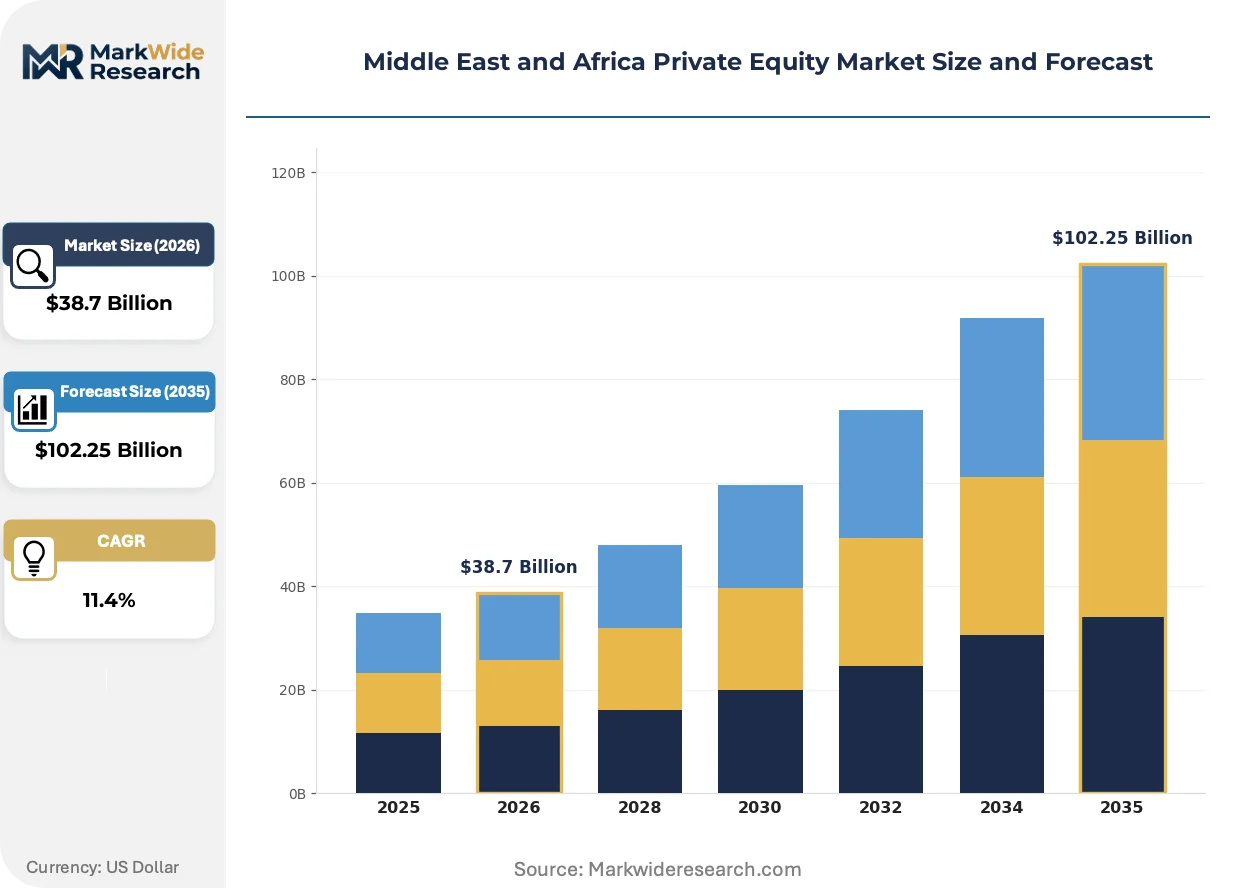
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fund Size: Small Cap, Mid Cap, Large Cap, Mega Fund Industry Vertical: Technology, Healthcare, Retail, Consumer Goods Investment Stage: Early-Stage, Growth-Stage, Expansion, Buyout Client Type: Institutional Investors, High Net-Worth Individuals, Family Offices, Corporates |
| Companies Covered | Investcorp, Actis, AfricInvest, Gulf Capital, EFG Hermes PE, Mubadala Investment Company, Helios Investment Partners, Development Partners International, NBK Capital, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Private Equity Market Shifts & Advancements
Digital due diligence platforms and alternative data sources are compressing investment decision timelines while sovereign wealth funds demand granular ESG tracking that legacy reporting infrastructure cannot deliver.
Artificial intelligence-powered risk scoring is fragmenting traditional credit assessment methodologies across Middle Eastern fintech portfolios. Regional banks and non-bank lenders deploy machine learning models trained on alternative data streams including mobile money transaction histories and utility payment patterns. This capability is fragmenting the competitive moat previously held by established credit bureaus, enabling direct lending platforms to undercut incumbent pricing in small business and consumer segments.
Saudi Arabia's Capital Market Authority has relaxed qualified investor thresholds, expanding the eligible limited partner base for domestic fund managers beyond institutional entities to high-net-worth individuals. This regulatory recalibration intensifies competition for retail capital and pressures fee structures downward. Domestic managers respond by developing lower-cost co-investment vehicles and simplified fund documentation.
Limited partners now mandate granular ESG disclosure frameworks that extend beyond carbon metrics to encompass workforce diversity and supply chain labor practices. Gulf-based sovereign funds and European development finance institutions lead this requirement shift. Fund managers in the UAE and South Africa accelerate hiring of dedicated sustainability officers and deploy third-party verification services to maintain allocator relationships.
Middle East and Africa Private Equity Market Segmentation
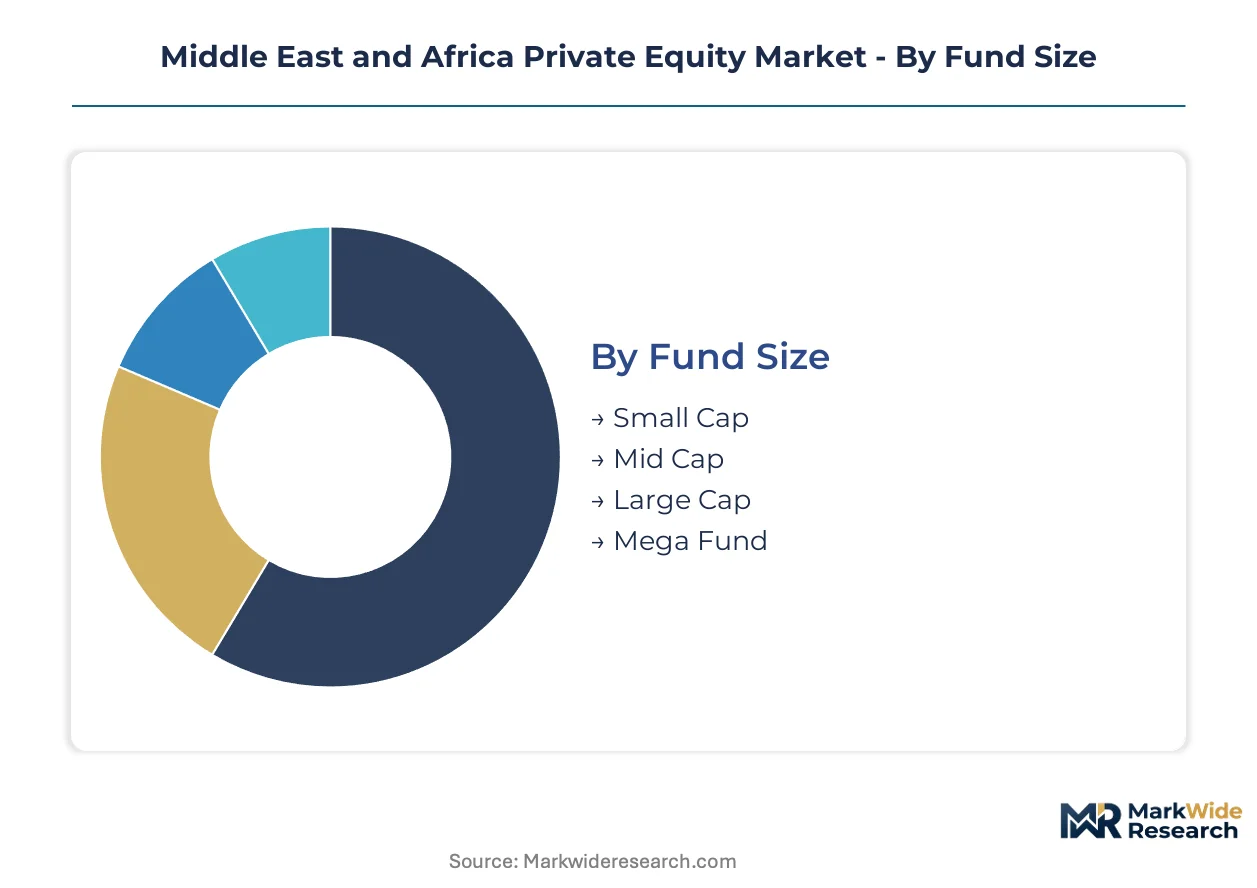
Fund size tiers and investment stage classifications determine fee structures and return expectations across Middle East and Africa private equity. Institutional allocators match mandate specifications to segment liquidity profiles and governance requirements.
Fund Size:
Substitution pressure concentrates in the mid-cap tier, where sovereign wealth funds bypass traditional fund structures for direct co-investment rights.
- Small Cap:Funds below $150 million target niche operational improvements in founder-managed enterprises across Kenya and Nigeria. Deployment timelines stretch due to limited local deal origination capacity and fragmented exit pathways.
- Mid Cap:$150 million to $750 million vehicles balance sector specialization with geographic diversification. Saudi Arabia's Capital Market Authority threshold reductions intensify retail capital competition, compressing management fee margins.
- Large Cap:Regional buyout specialists command premium allocations from European development finance institutions seeking exposure to North African infrastructure.
- Mega Fund:Multi-billion-dollar structures face deployment constraints as deal flow across Gulf Cooperation Council jurisdictions remains jurisdictionally fragmented.
Mid Cap retains volume leadership; Small Cap holds the steepest expansion curve.
Industry Vertical:
Cost tier differentiation separates premium valuation verticals from commoditized segments with compressed multiples.
- Technology:Fintech and healthtech sub-verticals attract Gulf sovereign capital at premium entry multiples due to structural underinvestment in prior decades. The UAE's DFSA regulatory sandboxes accelerate licensing timelines for digital payment platforms.
- Healthcare:Hospital networks and pharmaceutical distribution in Sub-Saharan Africa generate contracted revenue streams. Chronic infrastructure gaps create acquisition opportunities for growth-stage specialists with operational improvement capabilities.
- Retail:Modern trade formats expand across Egypt and Morocco, displacing traditional souk-based distribution.
- Consumer Goods:Packaged food and personal care brands leverage established distribution relationships in Francophone West Africa.
Technology captures allocator attention; Healthcare delivers the most predictable cash yield profile.
Investment Stage:
Application-specific risk-return profiles align with limited partner liquidity preferences and liability duration.
- Early-Stage:Pre-revenue technology ventures in Nairobi and Lagos require extensive governance scaffolding. Founder-managed enterprises often lack standardized financial reporting systems, extending due diligence timelines.
- Growth-Stage:Revenue-positive companies with proven unit economics attract Helios Investment Partners and comparable regional specialists. Mobile money infrastructure and technical talent concentration in Kenya create scalable entry points.
- Expansion:Geographic rollout mandates demand established operational playbooks and local management recruitment capabilities.
- Buyout:Control transactions in Saudi non-oil sectors align with Vision 2030 diversification mandates and sovereign capital allocation pools.
Buyout commands committed capital share; Growth-Stage demonstrates the most rapid deployment velocity.
Client Type:
Customer-type concentration shapes fundraising strategy and fee negotiation leverage across the capital structure.
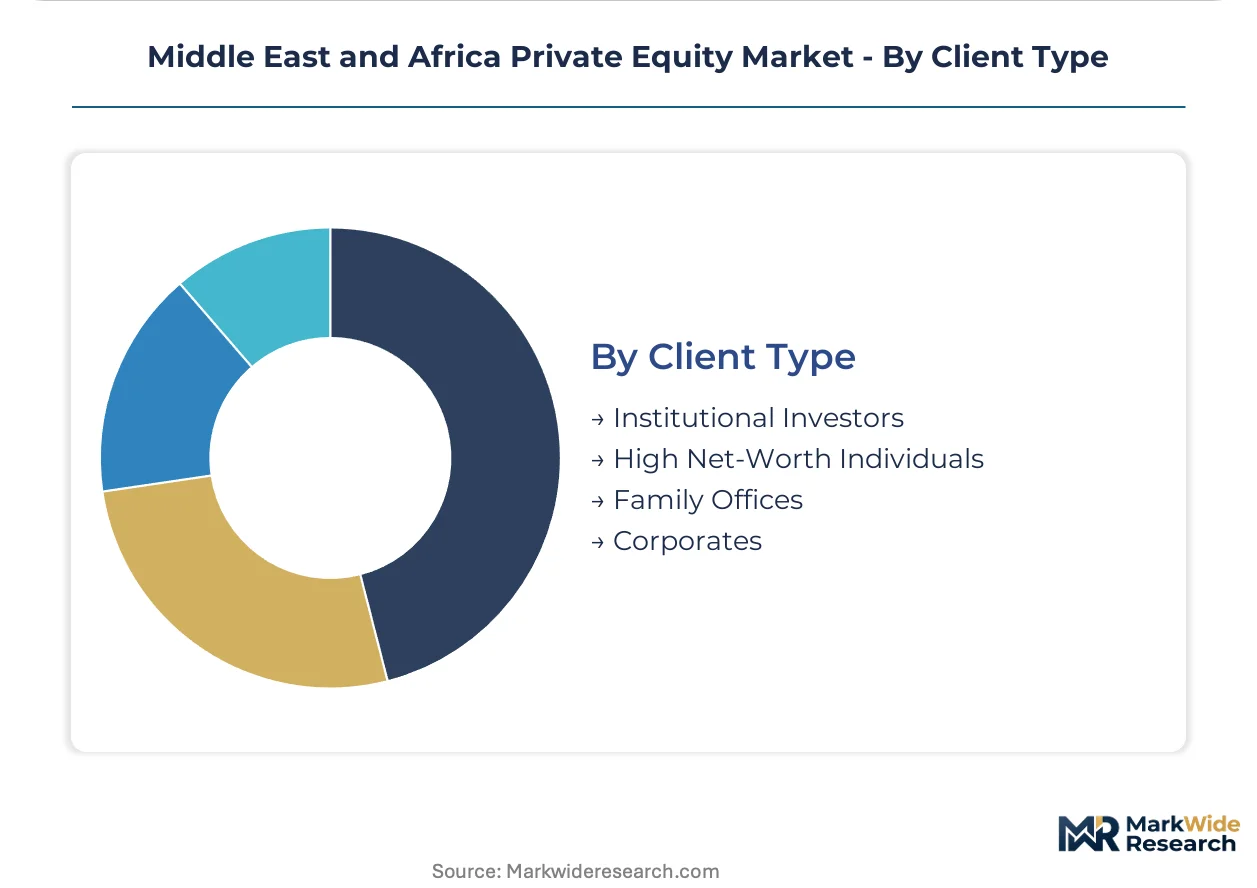
- Institutional Investors:Sovereign wealth funds and pension mandates drive the largest allocation flows. Granular ESG disclosure requirements now extend beyond carbon metrics to workforce diversity and supply chain labor practices.
- High Net-Worth Individuals:Saudi Arabia's expanded qualified investor thresholds intensify retail capital competition. Domestic managers respond with simplified fund documentation and lower-cost co-investment vehicles.
- Family Offices:Gulf-based dynastic wealth seeks sharia-compliant structures alongside conventional mandates.
- Corporates:Strategic balance sheet deployment targets vertical integration opportunities and technology acquisition.
Institutional Investors anchor aggregate commitments; High Net-Worth Individuals expand most quickly as regulatory thresholds ease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment patterns diverge sharply between Gulf sovereign wealth vehicles and Sub-Saharan growth-stage specialists. The former concentrates on technology and infrastructure buyouts, while the latter targets operational improvements in founder-managed enterprises.
United Arab Emirates
Dubai International Financial Centre anchors cross-border fundraising for North African and Levantine targets. The Dubai Financial Services Authority's regulatory sandbox frameworks compress licensing timelines for fintech portfolio companies. Abu Dhabi Global Market houses sovereign-backed fund administrators managing capital pools exceeding regional competitors.
Saudi Arabia
Vision 2030 diversification mandates redirect sovereign capital toward non-oil private markets at unprecedented velocity. The Capital Market Authority's relaxed qualified investor thresholds expand the eligible limited partner base to high-net-worth individuals beyond institutional entities. Riyadh's King Abdullah Financial District concentrates domestic fund management headquarters competing for retail capital.
Nigeria
Lagos-based growth-stage specialists target mobile money infrastructure and consumer distribution networks. Central Bank of Nigeria foreign exchange restrictions force dollar-denominated funds into complex hedging structures. The Victoria Island financial district hosts Francophone West African deal origination teams serving regional expansion mandates.
Egypt
Cairo's concentration of hospital networks and pharmaceutical distribution attracts healthcare-focused buyout specialists. The Egyptian Financial Regulatory Authority's qualified investor framework lags Gulf standards, constraining domestic fundraising scale. New Cairo's emerging business district houses regional headquarters for infrastructure funds targeting renewable energy offtake agreements.
South Africa
Johannesburg anchors Sub-Saharan Africa's deepest limited partner base spanning pension funds and development finance institutions. The Financial Sector Conduct Authority imposes disclosure standards divergent from Gulf frameworks, complicating pan-regional fund structures. Cape Town's venture ecosystem concentrates healthtech and fintech early-stage deployment targeting Anglophone African expansion.
Middle East and Africa Private Equity Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Middle East and Africa private equity. Sovereign-backed mega-funds deploy multi-billion-dollar mandates across technology and infrastructure verticals, while mid-cap specialists compete for operational improvement opportunities in founder-managed enterprises. Three archetypes dominate: Gulf-headquartered cross-border platforms, Anglophone Africa growth-stage specialists, and Francophone regional operators. Competitive intensity manifests through direct co-investment rights negotiations and sharia-compliant structure development rather than traditional fee compression.
Within the sovereign-backed tier, Mubadala Investment Company and Investcorp exemplify integrated capital deployment models spanning direct investments and fund commitments. Among growth-stage specialists, Helios Investment Partners occupies a position representing operational improvement capabilities across Francophone West Africa, while Actis anchors energy and infrastructure mandates in Egypt and Nigeria. Development Partners International and AfricInvest sit within the regional specialist tier targeting Sub-Saharan operational improvements.
| Leading Market Players |
|---|
| Investcorp |
| Actis |
| AfricInvest |
| Gulf Capital |
| EFG Hermes PE |
| Mubadala Investment Company |
| Helios Investment Partners |
| Development Partners International |
| NBK Capital |
| Others |
Supply & Pricing Matrix
Saudi Arabia's Capital Market Authority qualified investor threshold relaxations gate both fund manager qualification and retail capital pricing tiers simultaneously. This regulatory recalibration compresses management fee margins as domestic managers compete for high-net-worth individual allocations while sovereign wealth funds demand direct co-investment rights at reduced cost structures.
Pricing Analysis
Long-term offtake agreements dominate infrastructure mandates, while growth-stage venture capital employs hybrid pricing combining management fees with performance-linked carried interest. Price differentiation rests on fund size tier and sharia compliance certification, with Gulf-based limited partners paying premiums for Islamic finance structures. Pricing pressure intensifies as Saudi retail capital competition forces fee compression across mid-cap vehicles. Family offices demonstrate highest price sensitivity; sovereign wealth funds prioritize governance rights over cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites Gulf capital deployment timelines, with Bahrain and UAE anchoring cross-border fund administration. Capital sourcing draws from Saudi sovereign pools, UAE family offices, and European development finance institutions. Raw material dependencies include local currency hedging instruments, sharia-compliant legal documentation, and specialized investment professional talent. Single-source vulnerability concentrates in experienced deal originators with regional language capabilities. Distribution runs through Dubai International Financial Centre and Riyadh's King Abdullah Financial District.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where fund administration and portfolio company governance support expand faster than direct deployment capital. Recurring advisory fees and operational improvement retainers now exceed traditional transaction-based revenue at leading regional platforms.
For Market Incumbents: Compound defensive positioning through backward integration into portfolio company financial reporting infrastructure and captive development of local deal origination talent pools. Sovereign wealth fund direct investment mandates threaten traditional fund structures. Priority lever: proprietary data platforms tracking ESG metrics across Sub-Saharan African holdings. For New Entrants and Emerging Players: Anchor in Kenya's growth-stage ecosystem where mobile money infrastructure and technical talent concentration outpaces Francophone West African alternatives. Most penetrable segment: healthtech hospital networks in Egypt and Nigeria underserved by established buyout specialists. Go-to-market angle: simplified sharia-compliant fund documentation for Gulf family office capital. For Investors and Strategic Acquirers: Saudi Arabia's Capital Market Authority threshold relaxations reshape the acquisition landscape by expanding retail-eligible fund structures and intensifying domestic manager competition. Long-term viability favors integrated platforms spanning direct investment and fund commitments. Target archetype: mid-cap specialists with operational improvement playbooks in founder-managed enterprises. Signal to watch: secondary market liquidity mechanisms emerging in Dubai International Financial Centre.| Strategic Initiative | Industry Significance |
|---|---|
| Sharia-Compliant Structure Development | Dual-source capital access from Gulf sovereign funds and Malaysian sukuk markets expands allocator base. |
| Portfolio Company Governance Platform | Standardized financial reporting infrastructure reduces due diligence timelines for Nigerian and Kenyan targets. |
| Local Deal Origination Talent Development | Regional language capabilities and sector expertise command compensation premiums that compress competitor margins. |
| Direct Co-Investment Vehicle Launch | Simplified documentation and lower-cost structures capture Saudi high-net-worth individual capital inflows. |
| ESG Tracking Infrastructure Deployment | Granular disclosure frameworks beyond carbon metrics satisfy European development finance institution mandates. |
Research Methodology
A standing panel of fund managers, sovereign wealth allocation officers, regulatory compliance leads, and portfolio company CFOs provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against Capital Market Authority filings, Dubai Financial Services Authority regulatory notices, and fund commitment databases. Bottom-up deployment velocity tracking and top-down allocator survey data triangulated market size estimates.
Consistency checks validated outputs against external benchmarks including development finance institution disclosure reports and sovereign fund annual reviews. The analytical framework modeled fund size tiers, investment stages, industry verticals, and client types across the projection horizon. CAGRs derived from historical commitment patterns and projected allocator mandate shifts. Forecast inputs incorporated regulatory threshold changes and currency volatility assumptions for Nigerian naira and Egyptian pound exposures.
Underlying assumptions cover sovereign capital diversification mandates, sharia finance adoption curves, and local professional talent availability, with deviation risk concentrated in foreign exchange regime shifts and secondary market liquidity development. Forecasts reflect these conditions with acknowledged sensitivity to regulatory pacing in Saudi Arabia and UAE sandbox frameworks. Practitioners should keep alternative scenarios live as Vision 2030 implementation velocity and Sub-Saharan African infrastructure gap closure rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Pension Fund Management Software Market
Investment Analysis and Financial Strategies
Regtech Market
Investment Analysis and Financial Strategies
Hand Account Software Market
Investment Analysis and Financial Strategies
Europe Mutual Fund Market
Investment Analysis and Financial Strategies
Cancer Insurance Market
Investment Analysis and Financial Strategies
Mobile Money Market
Investment Analysis and Financial Strategies
France Data Analytics in Banking Market
Investment Analysis and Financial Strategies
Argentina Payments Market
Investment Analysis and Financial Strategies
Buy Now Pay Later Market
Investment Analysis and Financial Strategies
Japan Mobile Payments Market
Investment Analysis and Financial Strategies
Asia-Pacific EV Insurance Market
Investment Analysis and Financial Strategies
Australia Payments Market
Investment Analysis and Financial Strategies
Virtual Teller Machine (VTM) Market
Investment Analysis and Financial Strategies
United Arab Emirates Payment Market
Investment Analysis and Financial Strategies
Cryptocurrency Payment Apps Market
Investment Analysis and Financial Strategies
Russia Car Insurance Market