
 Disclosure Management Market | 2026-2036
Disclosure Management Market Size, Share, and Industry Trends Forecast 2026-2036
Disclosure Management Market Intelligence
European software engineering capacity is expanding as specialized vendors build disclosure management platforms for complex regulatory environments. Wolters Kluwer N.V. leverages deep domain expertise in tax and accounting compliance to anchor its position across continental Europe. SAP SE sustains competitive relevance through native ERP integration that reduces implementation friction for enterprise clients. Workiva, Inc. specializes in cloud-native collaborative reporting tools that dominate the U.S. public company segment.
Disclosure management encompasses the technology-enabled processes for collecting, validating, formatting, and submitting regulated information to authorities and stakeholders, typically incorporating XBRL tagging engines, audit trail logs, and workflow orchestration layers that ensure data lineage from source systems through final publication. The primary commercial purpose centers on eliminating manual spreadsheet dependencies while reducing restatement risk and accelerating filing timelines for quarterly and annual reports. Cloud-based deployment leads solution architecture decisions as organizations prioritize scalable infrastructure over capital-intensive on-premise installations, while regulatory reporting commands the largest solution type margin pool due to the complexity of jurisdiction-specific rule engines and the penalty costs of non-compliance. Financial consolidation represents the fastest-growing solution category as multinational enterprises seek unified close-to-disclose automation.
The U.S. Securities and Exchange Commission shapes product requirements through mandated inline XBRL adoption and evolving climate disclosure rules, while the European Securities and Markets Authority drives demand via the European Single Electronic Format and forthcoming sustainability reporting standards under CSRD. The U.K. Financial Conduct Authority's ongoing alignment with international disclosure frameworks adds a third regulatory vector that vendors must architect around. Stakeholders should monitor how jurisdictional rule divergence affects platform configurability requirements and whether consolidation of point solutions into broader governance suites accelerates vendor selection criteria.
Market Dynamics
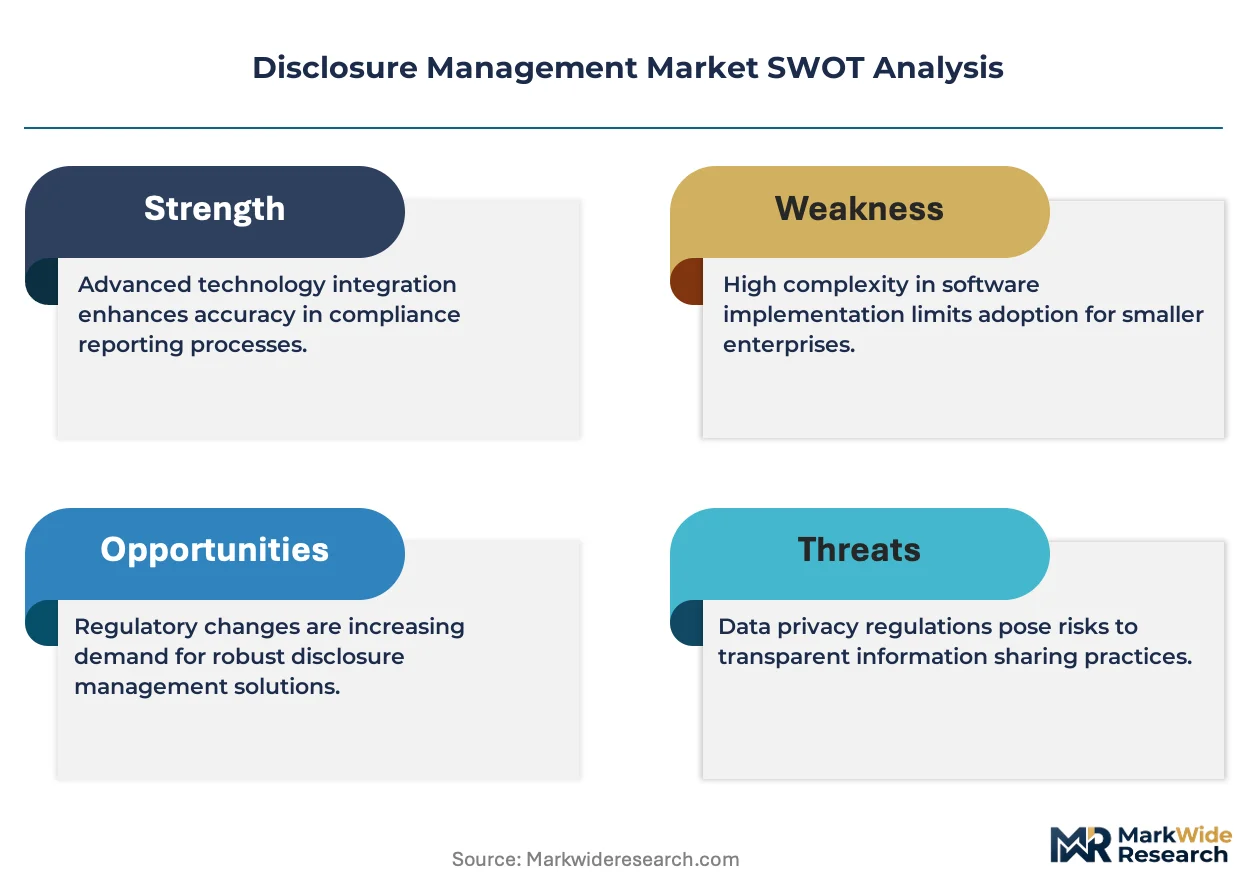
Inline XBRL mandates from the SEC are compressing filing timelines and forcing financial services firms to abandon manual spreadsheet workflows for automated disclosure platforms with embedded audit trails.
Growth Catalysts
- SEC Inline XBRL Mandate:The United States securities regulator requires machine-readable tagging for all periodic filings, creating immediate replacement demand for legacy document preparation tools.
- Climate Disclosure Rules:Emerging environmental reporting obligations in the European Union and California are expanding the scope of regulated disclosures beyond traditional financial statements.
- Cloud Infrastructure:Scalable SaaS architectures are absorbing capital expenditure constraints that previously blocked mid-market adopters from enterprise-grade compliance automation.
Market Restraints
- Implementation Complexity:Multi-jurisdictional rule engines require specialized configuration expertise that concentrates among a limited pool of systems integrators in London and New York.
- Data Sovereignty Requirements:European GDPR constraints and Chinese data localization rules fragment cloud deployment architectures and inflate operational overhead.
- Legacy ERP Lock-In:Deep integration dependencies with SAP and Oracle installations create switching costs that delay platform replacement cycles.
Strategic Opportunities
- CSRD Expansion:The European Union's Corporate Sustainability Reporting Directive mandates assurance-ready sustainability disclosures for thousands of previously unregulated mid-cap enterprises.
- AI-Powered Validation:Natural language processing and anomaly detection algorithms are converging with XBRL engines to automate narrative disclosure consistency checks.
- India Market Entry:SEBI's phased adoption of XBRL for listed companies creates a greenfield opportunity as domestic firms build first-generation disclosure infrastructure.
Industry Challenges
- XBRL Taxonomy Expertise Gap:The specialized skill set required for regulatory taxonomy mapping and extension creation remains scarce relative to implementation demand.
- Cross-Border Reconciliation:Divergent filing formats between the SEC, ESMA, and Japan's FSA force multinational issuers to maintain parallel disclosure production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disclosure Management Market |
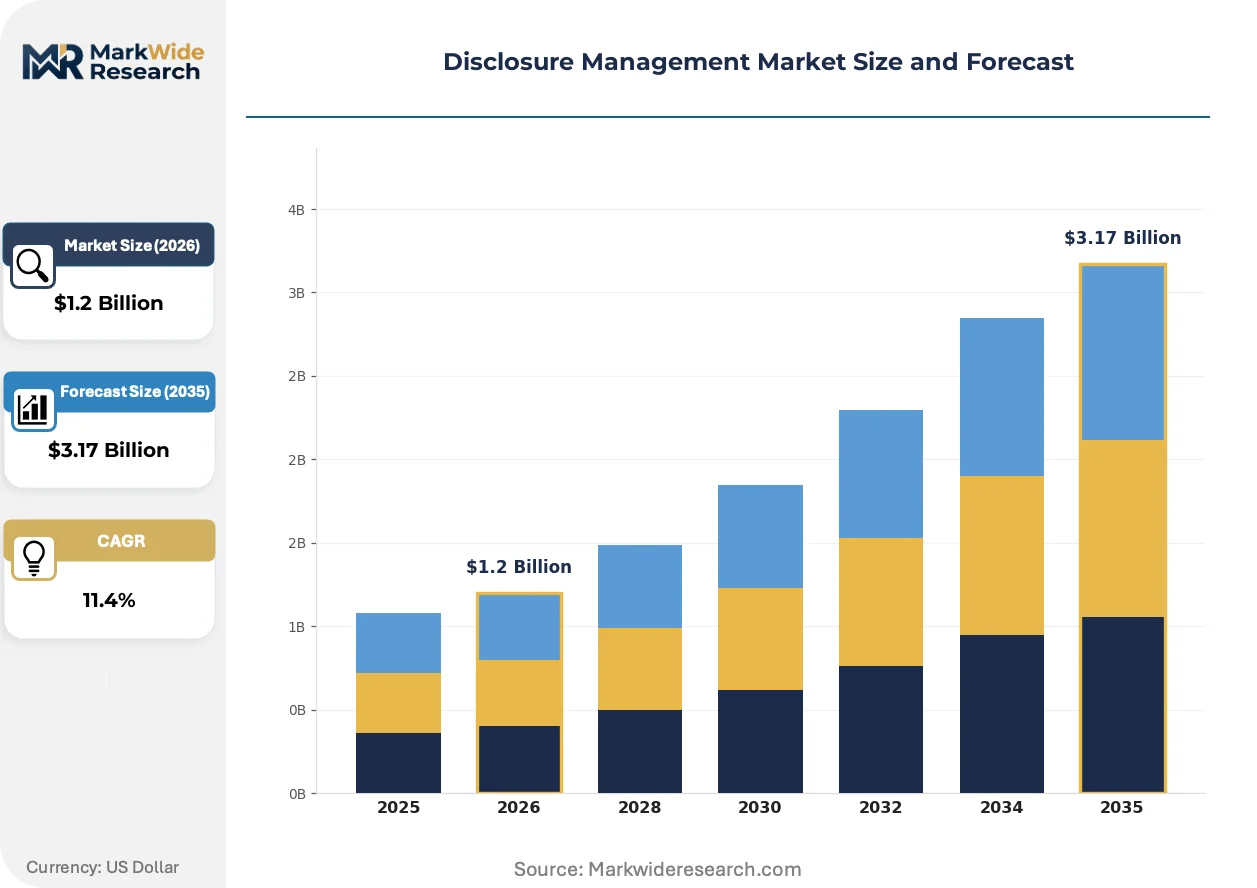
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Regulatory Reporting, Financial Consolidation, Risk Management, Audit Trail, Data Collection End User Industry: BFSI, Telecom, Manufacturing, Energy, Pharmaceuticals Integration Capability: ERP Systems, Business Intelligence, Workflow Automation, Data Visualization, Document Management |
| Companies Covered | Wolters Kluwer N.V., BlackLine Inc., SAP SE, LucaNet AG, insightsoftware, Oracle Corporation, NAVEX Global, Inc., Donnelley Financial Solutions, Workiva, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disclosure Management Market Strategic Shifts & Innovations
Disclosure management platforms are absorbing artificial intelligence capabilities that compress the gap between financial close and regulatory filing, while sustainability reporting obligations expand the addressable data universe.
Natural language generation engines are absorbing the drafting of management discussion and analysis sections from structured financial data. Large-cap banks in the United States are deploying these tools for quarterly earnings releases. The technology is absorbing hours of analyst time previously consumed by narrative formatting and consistency verification.
The European Securities and Markets Authority's European Single Electronic Format mandate is forcing issuers to restructure annual reports into machine-readable XHTML with embedded XBRL. Asset managers and insurance conglomerates face the steepest compliance curves. Continental European software vendors are capturing implementation services revenue as domestic firms race toward deadline adherence.
Buy-side institutions are consolidating vendor relationships by demanding unified platforms that span financial consolidation, regulatory reporting, and investor communications. Subscription pricing models are displacing perpetual license arrangements for enterprise deployments. This concentration is most visible among North American asset managers with complex multi-entity structures.
Disclosure Management Market Segmentation
Segmentation in disclosure management reveals how capital allocation, regulatory complexity, and IT architecture preferences split demand across divergent customer profiles. Vendors configure pricing and implementation approaches around deployment models and integration depth rather than treating the market as uniform.
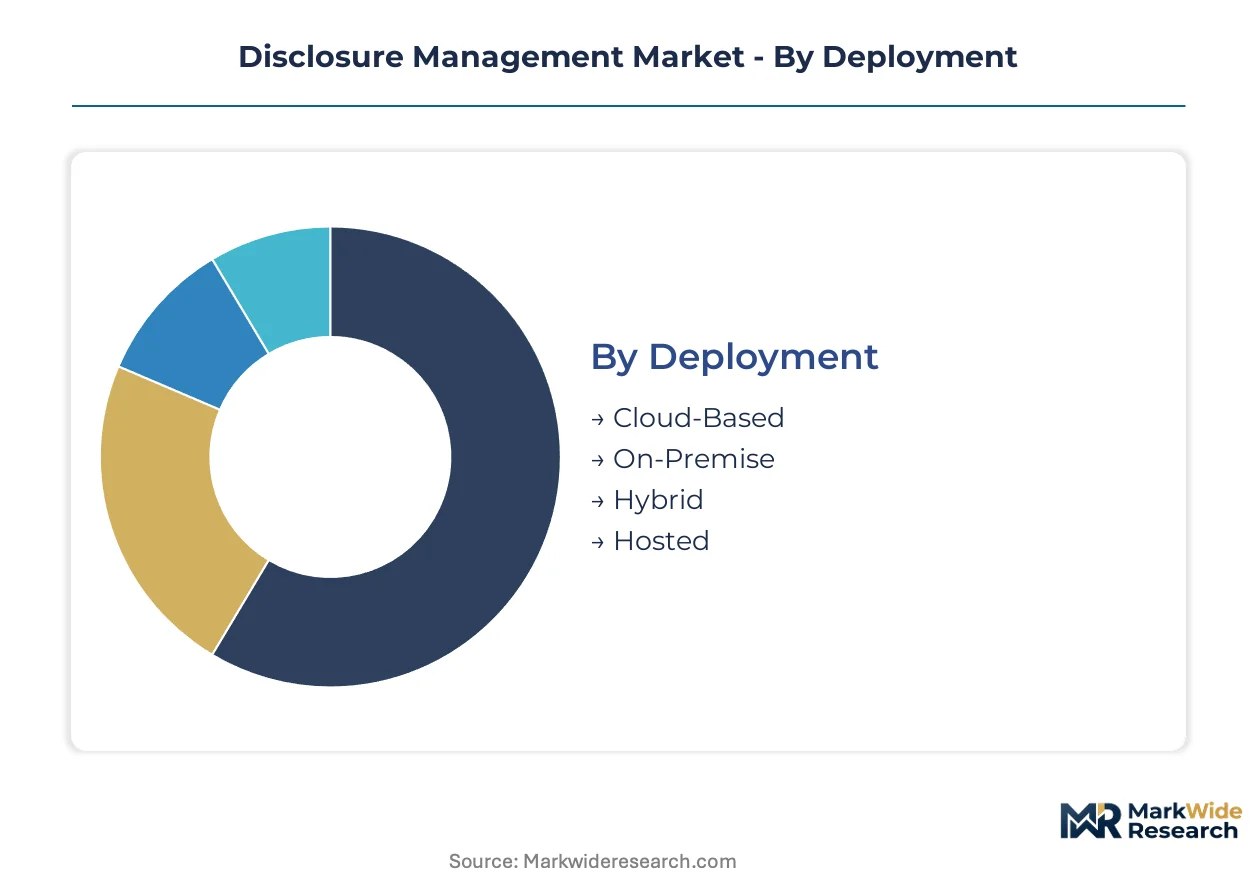
Deployment:
Capital intensity varies sharply across deployment modes, with upfront infrastructure commitments distinguishing enterprise preferences.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server procurement and shift expenditure to recurring subscriptions. Large-cap banks in the United States favor this model for SEC inline XBRL compliance, prioritizing elastic capacity during quarterly filing surges.
- On-Premise:Dedicated hardware installations demand substantial capital outlay for servers, security appliances, and data center space. European insurance conglomerates with strict data sovereignty requirements under GDPR absorb these costs to maintain physical control over audit trails.
- Hybrid:Split workloads between private infrastructure and public cloud, balancing sensitive data retention with burst computing. Manufacturing conglomerates with dispersed operations across multiple jurisdictions deploy hybrid models to satisfy local data residency rules.
- Hosted:Single-tenant managed services where vendors operate dedicated instances in third-party facilities. Mid-market BFSI firms in India leverage hosted deployments to access enterprise-grade XBRL engines without internal IT specialization.
Cloud-Based deployments absorb the bulk of installed capacity; Hybrid configurations are expanding most quickly as data sovereignty requirements fragment pure cloud strategies.
Solution Type:
Margin profiles diverge based on regulatory complexity and the penalty costs of non-compliance.
- Regulatory Reporting:Jurisdiction-specific rule engines for SEC, ESMA, and national regulators demand continuous taxonomy updates and specialized compliance expertise. This segment commands premium pricing due to the litigation exposure of filing errors.
- Financial Consolidation:Automated aggregation of multi-entity financials with intercompany elimination and currency translation. Multinational enterprises with complex subsidiary structures drive demand as they seek close-to-disclose automation.
- Risk Management:Integrated controls for financial statement accuracy and internal control documentation. Energy sector issuers facing climate disclosure obligations deploy these tools to link operational risk data with regulatory submissions.
- Audit Trail:Immutable logging of data lineage from source systems through final publication. Pharmaceutical firms subject to FDA validation requirements invest heavily in audit trail capabilities to satisfy inspection protocols.
- Data Collection:Structured gathering of narrative and quantitative inputs from distributed business units. Telecom operators with geographically dispersed finance teams utilize these tools to standardize inputs across regional reporting centers.
Regulatory Reporting captures the largest margin pool; Financial Consolidation is climbing the fastest as enterprises unify close and disclosure workflows.
End User Industry:
Customer concentration patterns reflect sector-specific regulatory pressure and reporting frequency.
- BFSI:Banks, insurers, and asset managers face the densest filing calendars and the steepest XBRL mandates. The SEC's inline XBRL requirements and the Federal Reserve's stress testing disclosures create sustained replacement demand for legacy spreadsheet workflows.
- Telecom:Operators with multi-country footprints require consolidated reporting across divergent national accounting standards. European telecom groups preparing for CSRD sustainability disclosures are expanding procurement of integrated platforms.
- Manufacturing:Industrial conglomerates with complex supply chains need disclosure management for segment reporting and environmental compliance. California-based manufacturers are absorbing new climate disclosure rules alongside traditional financial filings.
- Energy:Oil, gas, and utility companies navigate overlapping emissions reporting and financial disclosure obligations. The EPA's evolving greenhouse gas reporting requirements intersect with SEC climate rules to expand scope of regulated disclosures.
- Pharmaceuticals:Life sciences firms combine FDA submission requirements with financial reporting under strict data integrity standards. Clinical trial disclosure obligations and quarterly earnings filings create dual-track reporting complexity.
BFSI dominates current revenue concentration; Pharmaceuticals is gaining share fastest as drug developers integrate clinical and financial disclosure systems.
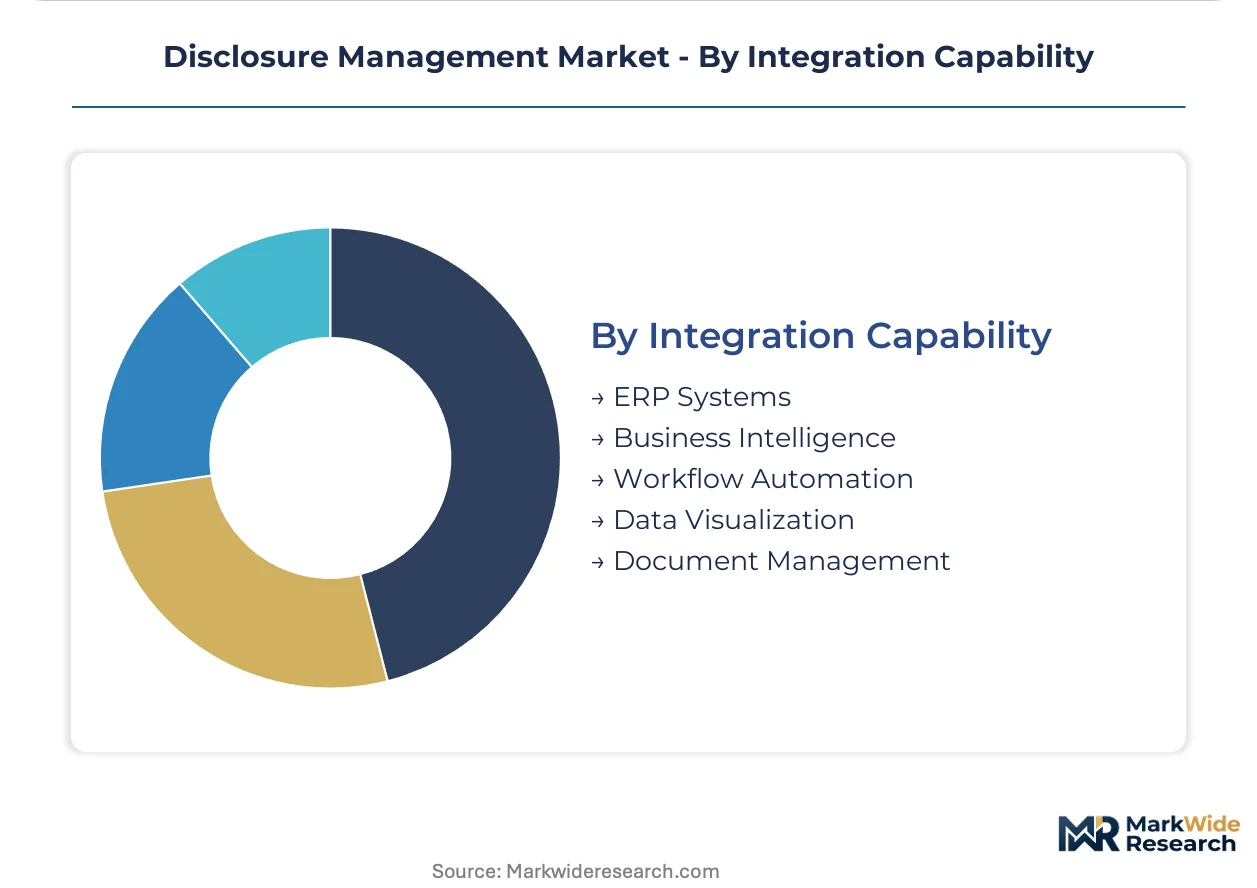
Integration Capability:
Technical architecture choices determine implementation friction and long-term switching costs.
- ERP Systems:Native connectors to SAP, Oracle, and Workday eliminate manual data extraction and reduce reconciliation risk. Enterprise clients prioritize pre-built integrations over custom middleware development.
- Business Intelligence:Feeds from Tableau, Power BI, and similar platforms enable disclosure drafting from existing analytics outputs. Finance teams leverage BI investments to accelerate narrative section preparation.
- Workflow Automation:Orchestration of approval chains, commentary collection, and version control across distributed contributors. Large issuers with 50-plus person disclosure committees require sophisticated workflow engines.
- Data Visualization:Embedded charting and graphical disclosure elements for management discussion sections. Asset managers emphasize visualization capabilities for shareholder communications and regulatory supplements.
- Document Management:Repository functions for historical filings, supporting workpapers, and audit documentation. Insurance conglomerates with decades of filing archives demand robust search and retrieval capabilities.
ERP Systems integration anchors the largest implementation budgets; Workflow Automation is expanding most quickly as remote collaboration requirements persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure anchors disclosure management software development, while regulatory mandates in Washington D.C., Brussels, and London shape demand geography.
United States
The SEC's inline XBRL mandate drives replacement demand among S&P 500 issuers. Large-cap banks and asset managers in New York and Chicago accelerate procurement of automated filing platforms. Cloud-native vendors dominate procurement cycles as quarterly reporting surges strain legacy spreadsheet workflows.
Germany
Industrial conglomerates in Baden-Württemberg and Bavaria seek unified close-to-disclose automation for multi-entity structures. ESMA's European Single Electronic Format deadline pressures DAX-listed manufacturers to restructure annual reports into machine-readable XHTML. Frankfurt's insurance sector absorbs specialized compliance expertise from domestic systems integrators.
United Kingdom
The FCA's alignment with international disclosure frameworks forces FTSE 100 firms to maintain parallel production lines. London's asset management cluster consolidates vendor relationships around unified governance suites. Lloyd's insurers invest heavily in audit trail capabilities to satisfy inspection protocols.
India
SEBI's phased XBRL adoption for listed companies creates greenfield infrastructure demand. Mumbai-headquartered banks and IT services firms build first-generation disclosure platforms without legacy ERP lock-in. Bangalore's SaaS ecosystem spawns domestic vendors targeting mid-market BFSI procurement.
Japan
METI's sustainability disclosure guidelines expand reporting scope beyond traditional financial statements. Tokyo-based trading houses and automotive groups integrate emissions data with regulatory submissions. Osaka's regional banks lag in automation adoption, creating implementation services opportunities for foreign vendors.
Disclosure Management Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized compliance niches. The vendor base clusters around three maturity tiers: global ERP-integrated suites, cloud-native collaborative platforms, and regional specialists with deep taxonomy expertise. Strategic differentiation centers on native ERP connectors, multi-jurisdictional rule engines, and AI-powered validation layers. Consolidation pressure intensifies as buy-side institutions demand unified platforms spanning financial consolidation, regulatory reporting, and investor communications.
Within the ERP-integrated tier, SAP SE and Oracle Corporation anchor enterprise procurement cycles through pre-built connectors that reduce implementation friction. Cloud-native specialists exemplified by Workiva, Inc. dominate the U.S. public company segment with collaborative reporting tools. Wolters Kluwer N.V. occupies a position across continental Europe leveraging deep domain expertise in tax and accounting compliance.
| Leading Market Players |
|---|
| Wolters Kluwer N.V. |
| BlackLine Inc. |
| SAP SE |
| LucaNet AG |
| insightsoftware |
| Oracle Corporation |
| NAVEX Global, Inc. |
| Donnelley Financial Solutions |
| Workiva, Inc. |
| Others |
Cost & Logistics Intelligence
Enterprise-grade SaaS tiers with embedded XBRL validation engines command substantial subscription premiums over basic cloud offerings, while mid-market hosted deployments absorb pricing compression through standardized implementation packages. This bifurcation concentrates vendor margins among North American financial services firms facing SEC mandates, whereas European data sovereignty requirements inflate operational costs for on-premise installations.
Pricing Analysis
Annual subscription bundling with unlimited taxonomy updates and dedicated support channels dominates enterprise procurement, while unbundled per-filing transactional pricing serves occasional issuers. Price differentiation hinges on jurisdictional rule engine breadth and pre-built ERP connector availability. Pricing pressure stems from cloud-native entrants undercutting legacy perpetual-license incumbents. Mid-market BFSI firms in India exhibit highest price sensitivity; large-cap U.S. banks prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Regional distribution centers in Ireland, Singapore, and Virginia anchor cloud infrastructure delivery for disclosure management platforms. Software development draws from engineering talent pools in Germany, India, and Poland, while XBRL taxonomy expertise concentrates in London and New York. Single-source vulnerability in specialized compliance consulting creates bottleneck risk for complex multi-jurisdictional implementations. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disclosure management sits at a technology-transition inflection as AI-powered validation engines displace manual narrative review workflows. Natural language processing convergence with XBRL tagging represents the decisive capability gap between legacy spreadsheet-dependent processes and next-generation automation.
For Market Incumbents: Deepen native ERP connector development to raise switching costs against cloud-native challengers. Prioritize SAP and Oracle integration depth as a defensive moat. Expand implementation services capacity in Frankfurt and Mumbai to capture CSRD and SEBI-driven demand surges before specialized regional vendors consolidate local relationships.
For New Entrants and Emerging Players: Enter via sustainability reporting modules as a beachhead into established financial consolidation accounts. Target European mid-cap manufacturers preparing for first-time CSRD compliance as the most penetrable segment. Pursue partnership-led distribution through ESG consulting firms rather than direct enterprise sales buildout.
For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists possessing deep taxonomy expertise given accelerating regulatory complexity across jurisdictions. Long-term viability favors platforms with demonstrated multi-jurisdictional rule engine configurability. Monitor SEBI implementation timeline acceleration as the critical inflection signal for India market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| XBRL Taxonomy Engine Expansion | ESMA's ESEF deadline forces DAX-listed issuers toward machine-readable annual report restructuring. |
| AI-Powered Validation Layer | NLP anomaly detection compresses financial close-to-file timelines for quarterly SEC submissions. |
| CSRD Compliance Module Launch | European sustainability disclosure mandates create assurance-ready reporting demand among mid-cap enterprises. |
| Strategic Partnership with Systems Integrators | London and New York consulting capacity constraints limit implementation velocity without channel expansion. |
| Geographic Expansion into India | SEBI's phased XBRL adoption generates greenfield infrastructure procurement without legacy ERP displacement friction. |
Research Approach
Independent corroboration across disclosure management vendor product documentation, SEC and ESMA regulatory filing databases, and systems integrator implementation case studies underwrites the qualitative findings. Primary interviews with CFOs at multinational BFSI firms, compliance officers at asset managers, XBRL taxonomy specialists at consulting firms, and procurement leads at insurance conglomerates combined with secondary validation from SEC EDGAR filings, ESMA transparency reports, and SEBI circulars. Bottom-up deployment model sizing and top-down regulatory mandate impact assessment provided cross-check triangulation.
Comparable historical adoption curves from SOX implementation and initial XBRL mandates anchored the forecast window construction. The analytical framework modeled deployment mode, solution type, end-user industry, and integration complexity across the projection horizon. CAGRs derived from segment-level growth rate synthesis calibrated against macroeconomic sensitivity factors. Forecast inputs incorporated regulatory deadline acceleration scenarios and cloud infrastructure cost curve trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under jurisdictional rule divergence or extended ERP replacement cycles. Outputs reflect documented assumptions regarding SEC enforcement consistency and ESMA taxonomy stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market
Risk Management and Compliance
Cyber Security in BFSI Market
Risk Management and Compliance
Global Strategy Consulting Market
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
Corporate Investigation Services Market
Risk Management and Compliance
Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Clinical Risk Grouping Solutions Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Sell-Side Due Diligence Services Market
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
Healthcare Safety and Risk Management Solutions Market