
 United Kingdom Accounting Software Market | 2026-2036
United Kingdom Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Accounting Software Market Insights
SME advisory demand is decoupling from traditional desktop accounting suites as hybrid work models persist across Britain. Sage anchors its position through deep integration with HMRC compliance workflows, while Xero competes aggressively on real-time bank feed connectivity. FreeAgent specializes in freelancer-centric tax automation, carving defensible share among sole traders navigating self-assessment complexity.
United Kingdom accounting software encompasses cloud-deployed, on-premise, and hybrid financial management applications engineered for general ledger reconciliation, automated VAT computation, and audit trail preservation under UK GAAP and IFRS standards. Cloud-based deployment leads structural momentum as multi-entity consolidation and API-native architectures displace siloed desktop installations. SMEs represent the fastest-growing end-user category, driven by regulatory filing obligations and subscription pricing that eliminates capital expenditure barriers. Tax management solutions command premium positioning as Making Tax Digital phases expand reporting frequency beyond annual returns.
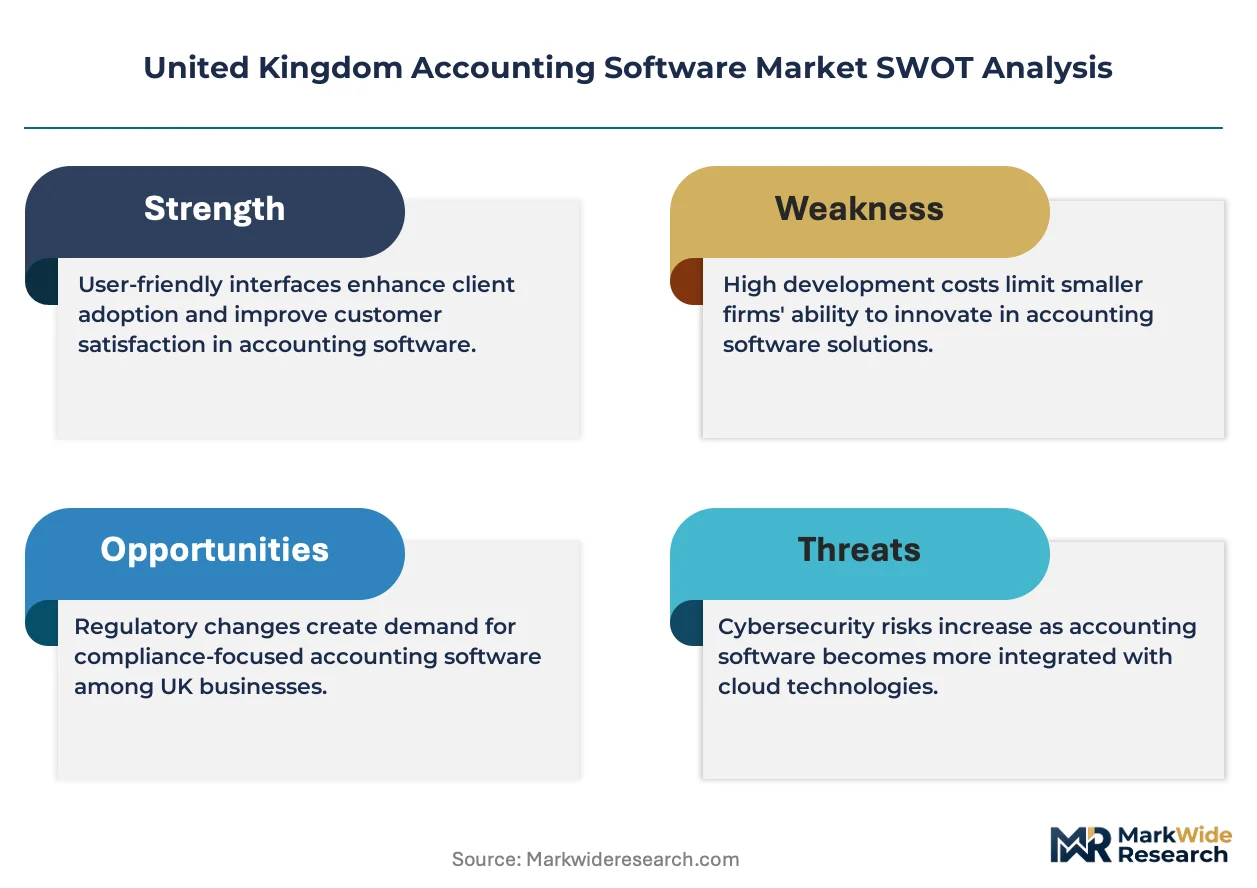
HMRC's Making Tax Digital framework and the Financial Reporting Council's audit quality standards jointly elevate software compliance requirements, forcing vendors to embed real-time validation engines. The Information Commissioner's Office GDPR enforcement adds data residency specifications that favor UK-hosted cloud infrastructure. Stakeholders must weigh the pace of HMRC mandate expansion against the interoperability limitations of vertically integrated platform ecosystems.
Market Dynamics
HMRC's Making Tax Digital mandate is compressing software replacement cycles across British accountancy practices, forcing vendors to embed real-time validation engines that eliminate manual quarterly filing workflows.
Growth Catalysts
- Making Tax Digital Phase Expansion:HMRC's quarterly reporting obligations for income tax self-assessment and corporation tax are compelling sole traders and limited companies to adopt cloud-native platforms with automated submission capabilities.
- API-Native Architecture Migration:Open banking standards and real-time bank feed integration are enabling continuous reconciliation that displaces batch-processed monthly closes in mid-sized practices.
- Freelancer Economy Density:The concentration of self-employed contractors in London, Manchester, and Bristol is generating concentrated demand for tax automation tools that handle IR35 complexity and self-assessment compliance.
Market Restraints
- GDPR Data Residency Requirements:The Information Commissioner's Office enforcement of UK-hosted cloud infrastructure specifications limits vendor options and elevates hosting costs for providers without domestic data centers.
- Desktop Legacy Lock-In:Decades of historical data trapped in proprietary on-premise formats creates switching friction that extends replacement timelines and depresses near-term cloud migration velocity.
- Interoperability Fragmentation:Vertically integrated platform ecosystems resist third-party API connections, forcing practices to accept workflow discontinuities or pay premium integration fees.
Strategic Opportunities
- Scotland and Northern England Underpenetration:Professional services density outside London and Manchester remains substantially lower, creating whitespace for regionally focused distribution partnerships and localized support models.
- AI-Assisted Tax Advisory Convergence:Machine learning classification of expenses combined with natural language query interfaces is opening adjacent revenue streams beyond core bookkeeping subscriptions.
- Mid-Market Consolidation Tools:Multi-entity consolidation capabilities for growing accountancy practices with 10-50 clients represent an underserved segment between SME solutions and enterprise ERP systems.
Industry Challenges
- HMRC API Reliability and Versioning:Frequent changes to submission protocols and intermittent service disruptions force vendors to maintain dedicated compliance engineering teams that strain R&D budgets.
- MTD-Ready Talent Scarcity:The shortage of accountants trained in both traditional UK GAAP standards and digital-first compliance workflows is constraining implementation velocity at client firms.
Report Scope
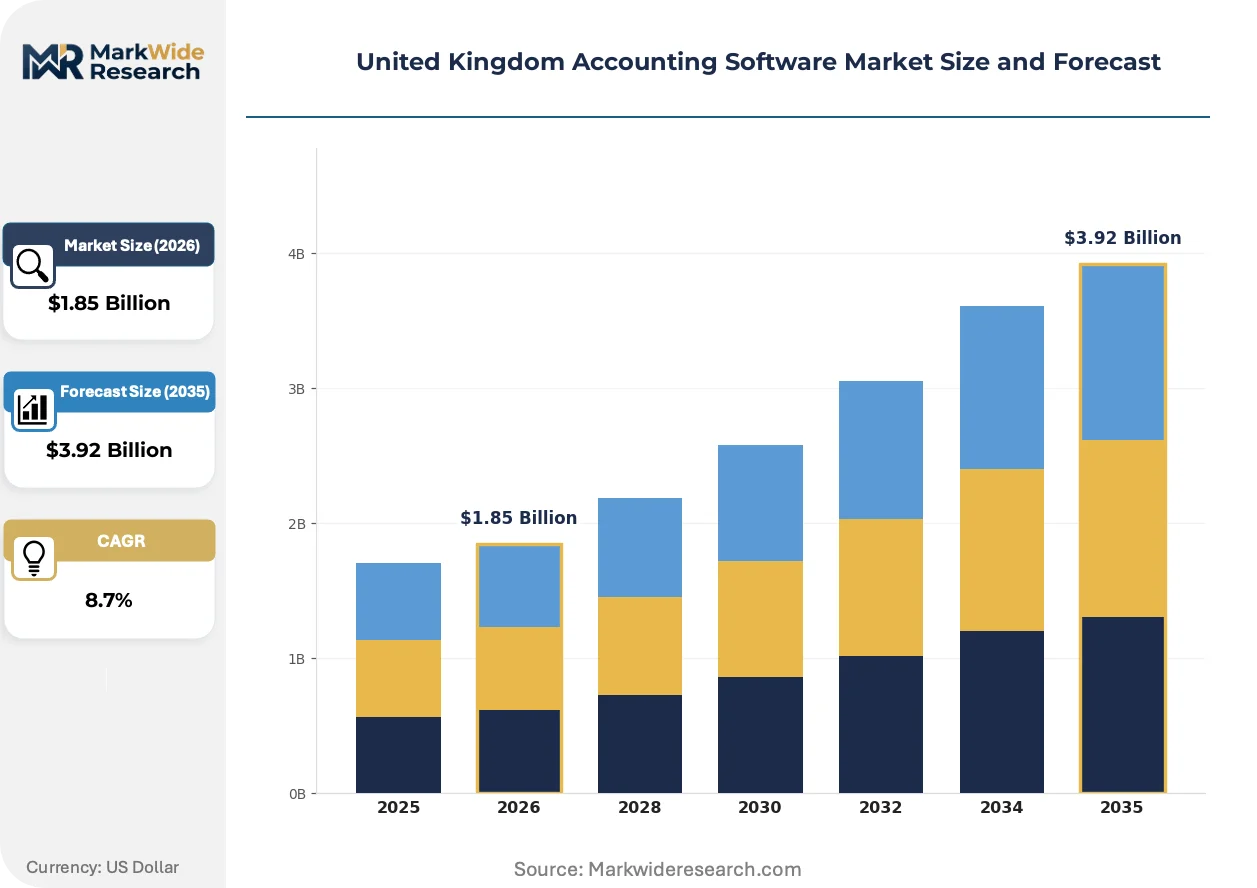
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Accounting Software Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed End User: SMEs, Large Enterprises, Freelancers, Accountants Solution: Invoicing, Payroll, Tax Management, Expense Tracking Integration Level: APIs, Third-Party Tools, E-commerce Platforms, ERP Systems |
| Companies Covered | Sage, Xero, QuickBooks, Intuit, FreeAgent, AccountsIQ, Sage Intacct, NetSuite, Xledger, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Accounting Software Market Trends and Innovations
Artificial intelligence and machine learning capabilities are embedding deeper into core accounting workflows, transforming software from passive ledger repositories into active compliance engines that anticipate filing obligations and flag anomalies before submission.
Machine learning expense classification is automating the categorization of bank transactions against HMRC-allowable deductions, reducing manual coding hours for sole traders and micro-businesses. Mid-sized accountancy practices in Birmingham and Leeds are deploying these tools at accelerating rates to maintain margin pressure from fixed-fee compliance engagements. The technology is automating the shift from retrospective bookkeeping to real-time financial advisory, compressing the traditional monthly reporting cycle into continuous visibility.
HMRC's phased expansion of Making Tax Digital requirements for income tax self-assessment is mandating quarterly digital updates from millions of additional taxpayers by 2026. The regulation is forcing software vendors to rebuild user interfaces around proactive deadline management rather than annual retrospective filing. Sole traders and landlords with property portfolios across England's southeast are experiencing the most acute disruption, driving demand for mobile-first applications with push notification compliance alerts.
Subscription-based pricing with embedded advisory services is displacing perpetual license models that separated software procurement from ongoing compliance support. Small accountancy practices in Manchester's fintech corridor are bundling software access with quarterly review calls that justify recurring fees. This bundling pattern is most visible among practices serving the creative and professional services sectors, where clients expect technology-enabled human guidance rather than self-service platforms.
United Kingdom Accounting Software Market Segmentation
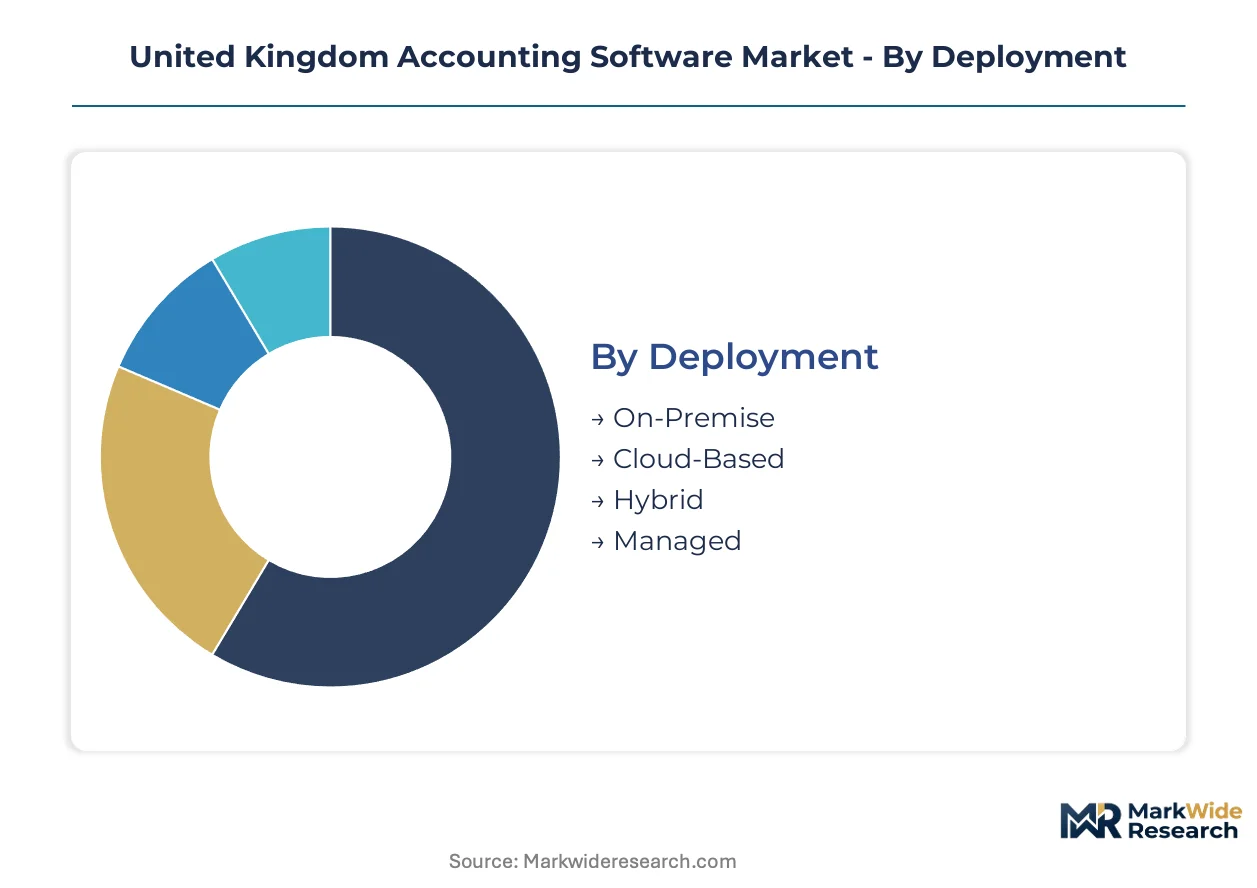
HMRC's Making Tax Digital mandate creates divergent compliance burdens across deployment modes and end-user categories. Segmentation reveals which customer clusters face the steepest regulatory engineering requirements and where vendor R&D investments concentrate.
Deployment:
GDPR data residency specifications from the Information Commissioner's Office impose distinct certification pathways on each deployment architecture, with cloud infrastructure facing the most intensive UK-hosting verification protocols.
- Cloud-Based:Multi-tenant SaaS architectures with automatic HMRC API synchronization dominate procurement among mid-sized Manchester and Birmingham accountancy practices. Real-time validation engines eliminate manual quarterly filing workflows for income tax self-assessment compliance.
- Hybrid:Split configurations maintain sensitive client data on local servers while pushing submission-ready reports to cloud endpoints. London-based professional services clusters favor this model for GDPR risk mitigation during MTD transition periods.
- On-Premise:Legacy server installations with manual HMRC portal uploads persist in rural England practices with limited broadband reliability.
- Managed:Outsourced infrastructure where vendors handle both hosting and compliance engineering, attracting sole traders lacking IT staff.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as practices hedge regulatory uncertainty.
End User:
Cost tier stratification separates subscription-based SME tools from enterprise ERP integrations and micro-business freemium offerings.
- SMEs:Limited companies with 10-250 employees drive the steepest expansion trajectory, compelled by corporation tax MTD phases and subscription pricing that eliminates capital expenditure barriers.
- Freelancers:Self-employed contractors concentrated in London and Bristol generate concentrated demand for mobile-first IR35 navigation and self-assessment automation.
- Accountants:Multi-client practices require multi-entity consolidation capabilities and white-label client portals.
- Large Enterprises:Complex group structures needing IFRS consolidation alongside UK GAAP statutory reporting.
SMEs command the largest addressable base, with Freelancers gaining share fastest amid gig economy density.
Solution:
Application criticality varies by regulatory proximity, with tax-facing modules commanding premium positioning over operational tools.
- Tax Management:Embedded MTD submission engines with real-time HMRC validation and quarterly deadline orchestration. Sole traders with property portfolios across England's southeast experience acute disruption here, driving mobile-first demand.
- Payroll:RTI-compliant real-time information systems with automated PAYE calculations and pension auto-enrolment tracking.
- Invoicing:VAT-compliant sales documentation with sequential numbering and audit trail preservation.
- Expense Tracking:Machine learning classification of bank transactions against HMRC-allowable deductions for micro-businesses.
Tax Management leads revenue concentration, with Expense Tracking expanding most quickly through AI automation.
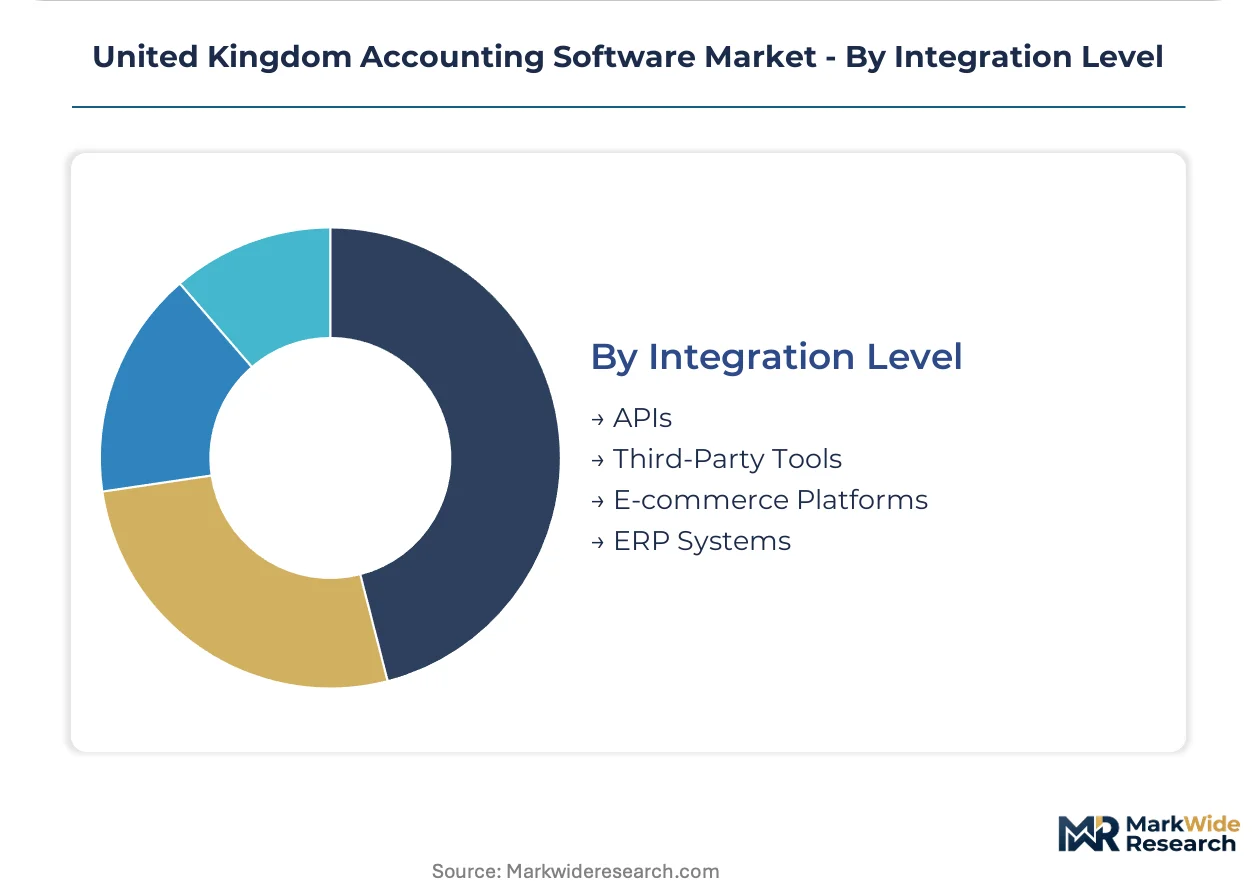
Integration Level:
Customer type determines interoperability expectations, with accountant-facing platforms requiring deeper ecosystem connectivity than sole trader standalone tools.
- APIs:Open banking standards and real-time bank feed integration enable continuous reconciliation that displaces batch-processed monthly closes.
- Third-Party Tools:Vertical integrations with practice management and document signing platforms streamline workflow for multi-client accountants.
- E-commerce Platforms:Automated sales channel synchronization for digital-first retailers requiring multi-currency VAT handling.
- ERP Systems:Enterprise resource planning connectors for large enterprises consolidating statutory reporting with operational finance.
APIs anchor the integration hierarchy, with Third-Party Tools climbing fastest as platform ecosystems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting software procurement toward jurisdictions with streamlined compliance infrastructure. HMRC's Making Tax Digital framework creates cost-of-compliance gaps that favor cloud-native vendors with domestic UK hosting over continental alternatives bearing cross-border data transfer overhead.
London and the Southeast
Professional services density in the capital drives concentrated demand for multi-entity consolidation tools. The Financial Conduct Authority's operational resilience requirements push large accountancy practices toward API-native architectures with real-time validation. Canary Wharf and the City host the densest clusters of mid-market firms accelerating desktop-to-cloud migration.
Midlands
Birmingham and Leicester manufacturing bases generate steady demand for VAT automation bridging industrial accounting and HMRC quarterly submissions. The West Midlands Combined Authority's digital adoption programs subsidize SME software procurement. Coventry's automotive supply chain concentration favors hybrid deployment models balancing legacy ERP connectivity with cloud tax compliance.
North England
Manchester's fintech corridor anchors the fastest-growing regional cluster for freelancer-centric tax tools. Greater Manchester Combined Authority's business support schemes reduce switching costs for sole traders adopting MTD-ready platforms. Leeds and Sheffield accountancy practices drive mid-market consolidation tool demand as client bases expand across Yorkshire.
Scotland
Edinburgh and Glasgow financial services centers sustain enterprise-grade procurement for IFRS-compliant statutory reporting. Scottish Enterprise innovation grants accelerate AI-assisted advisory adoption among smaller practices. Aberdeen's energy sector concentration creates specialized demand for multi-currency consolidation handling North Sea operational accounts.
Wales and Northern Ireland
Rural broadband limitations sustain on-premise legacy systems longer than elsewhere, though Cardiff and Belfast metro areas show accelerating cloud migration. Invest Northern Ireland's digital transformation vouchers compress procurement timelines for Belfast-based professional services firms. Welsh Government SME support programs target quarterly filing automation for agricultural and tourism sector micro-businesses.
United Kingdom Accounting Software Market Competitive Landscape
API-native platform expansion dominates the current landscape as vendors embed real-time HMRC synchronization to capture MTD-mandated replacement cycles. The vendor base stratifies across three tiers: established incumbents with deep compliance integration, challenger platforms competing on user experience, and specialist tools serving narrow freelancer segments. Two strategic archetypes have emerged: horizontally integrated suites spanning tax, payroll, and advisory workflows, and vertically focused applications optimizing single compliance workflows. M&A activity concentrates on acquiring API infrastructure and machine learning classification capabilities, while geographic expansion through localized support partnerships targets underpenetrated regional markets.
Within the incumbent tier, Sage and Intuit anchor positions through decades-long HMRC workflow integration and established accountant channel relationships. Xero occupies the challenger platform archetype, competing aggressively on real-time bank feed connectivity and mobile-first interfaces. FreeAgent exemplifies the specialist vector, carving defensible share among sole traders navigating self-assessment complexity and IR35 obligations. These three patterns—incumbent compliance depth, challenger connectivity, and specialist tax automation—structure competitive positioning across the United Kingdom accounting software market.
| Leading Market Players |
|---|
| Sage |
| Xero |
| QuickBooks |
| Intuit |
| FreeAgent |
| AccountsIQ |
| Sage Intacct |
| NetSuite |
| Xledger |
| Others |
Pricing and Supply Chain Analysis
Mid-sized accountancy practices in Manchester and Birmingham concentrate procurement power, driving subscription-based SaaS pricing that eliminates perpetual license capital expenditure barriers. This buyer archetype's preference for bundled compliance-advisory packages reshapes how vendors structure tiered offerings across deployment modes.
Pricing Analysis
Channel margins for accountant-facing platforms compress through direct-to-practice digital sales, bypassing traditional software distributors. Three-tier pricing structure across premium, standard, and economy levels segments by HMRC API synchronization depth and multi-entity consolidation capability. Price differentiation hinges on real-time validation engine sophistication and white-label client portal customization. Pricing pressure stems from FreeAgent and challenger platforms undercutting incumbent subscription tiers with freelancer-centric freemium entry points. Sole traders and micro-businesses exhibit highest price sensitivity, while multi-client practices in London's professional services clusters prioritize compliance reliability over cost minimization.
Supply Chain Analysis
Freight and data residency costs elevate for vendors without UK-hosted cloud infrastructure, compelling domestic server deployment or hybrid configurations. Software engineering talent concentrates in India, Poland, and Romania for offshore development centers supporting HMRC API maintenance. Raw material inputs encompass cloud compute capacity from AWS, Azure, and Google Cloud; machine learning training data from open banking feeds; and compliance engineering expertise from London and Edinburgh financial services labor pools. Single-source vulnerability attaches to HMRC API versioning changes that force emergency engineering sprints. Distribution runs through direct SaaS provisioning, accountant channel partnerships, and regional software resellers serving underpenetrated Scottish and Northern English markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications in tax automation are hardening as HMRC's Making Tax Digital phases demand real-time validation engines that eliminate submission errors. This shift favors vendors with embedded compliance engineering over generic bookkeeping platforms.
For Market Incumbents: Anchor market position through deeper HMRC workflow integration that challenger platforms cannot replicate without dedicated compliance engineering teams. Invest in machine learning classification capabilities for expense automation to defend against AI-native entrants. Vertical integration into UK-hosted cloud infrastructure mitigates GDPR data residency enforcement risks that elevate competitor hosting costs. For New Entrants and Emerging Players: Capture whitespace in Scotland and Northern England where professional services density remains substantially below London levels. Target Leeds and Sheffield accountancy practices with mid-market consolidation tools positioned between SME solutions and enterprise ERP systems. Partner with regional business support schemes to reduce customer acquisition costs in underpenetrated geographies. For Investors and Strategic Acquirers: Private equity firms specializing in vertical software are the most active acquirer in this space, consolidating API infrastructure and machine learning capabilities across fragmented specialist vendors. Long-term viability hinges on regulatory engineering moats that compound with each HMRC mandate expansion. Acquisition target archetypes include freelancer-centric tax automation tools with IR35 workflow depth and regionally focused platforms with localized support infrastructure. Monitor HMRC income tax self-assessment phase rollout velocity as the critical inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| HMRC API Integration Deepening | Real-time validation engines eliminate manual quarterly filing workflows for income tax self-assessment compliance. |
| AI-Assisted Tax Advisory Development | Machine learning expense classification opens adjacent revenue streams beyond core bookkeeping subscriptions. |
| Geographic Expansion Partnerships | Regional distribution alliances target Scotland and Northern England underpenetration with localized support models. |
| Multi-Entity Consolidation Platform Launch | Mid-market tools serve growing accountancy practices with 10-50 clients between SME and enterprise tiers. |
| UK Cloud Infrastructure Investment | Domestic data centers satisfy ICO GDPR enforcement and reduce cross-border transfer compliance overhead. |
Research Methodology
Coverage spans England, Scotland, Wales, and Northern Ireland, with primary inputs from each jurisdiction's accountancy practice clusters. Primary interviews incorporated software vendor product managers, HMRC compliance engineering leads, multi-client practice partners in Manchester and London, and channel distribution specialists. Secondary validation drew from Companies House filing data, HMRC MTD implementation guidance, ICO GDPR enforcement notices, and Financial Reporting Council audit quality reviews. Bottom-up sizing of subscription revenue by deployment mode and end-user category triangulated against top-down market value estimates from cloud infrastructure spending and professional services software procurement patterns.
Rate-of-change decomposition separated volume expansion from pricing evolution across the projection horizon. Segmentation modeling incorporated deployment architecture, organization size tier, solution application, and regional adoption intensity. CAGR derivation weighted historical replacement cycle compression against regulatory mandate phase timing. Forecast inputs included HMRC API reliability metrics, open banking feed penetration rates, and accountant workforce MTD readiness surveys.
HMRC mandate expansion delays, API service disruption frequency, and GDPR enforcement escalation are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about regulatory timeline adherence and cloud migration velocity that may shift with political or economic conditions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Integrated Accounting Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
France Forensic Accounting Market
Accounting and Taxation Services
Tax Management Market
Accounting and Taxation Services
Global Sales Tax Compliance Software Market
Accounting and Taxation Services
Bookkeeper Software Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
France Accounting Software Market
Accounting and Taxation Services
Germany Accounting Software Market
Accounting and Taxation Services
Global Auditing Services Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
Accounting Services Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
Asia-Pacific Accounting & Budgeting Software Market
Accounting and Taxation Services
Global Business Accounting Software Market