
 US Halloween Decorations Market | 2026-2036
US Halloween Decorations Market Size, Share, and Industry Trends Forecast 2026-2036
US Halloween Decorations Market Outlook
Subscription-based curated decoration boxes is restructuring how consumers build annual collections, shifting one-time purchases toward recurring revenue relationships. Spirit Halloween leverages temporary retail footprints to dominate seasonal real estate in high-traffic corridors. Gemmy Industries anchors inflatable decoration innovation through proprietary airblown technology platforms. Amscan sustains broad catalog depth across paper and plastic categories, competing on manufacturing scale rather than exclusivity.
US Halloween decorations encompass manufactured ornamental items designed for seasonal display, typically fabricated from thermoplastic polymers, synthetic textiles, or cellulose-based substrates using rotational molding, thermoforming, or die-cutting processes, intended to transform residential and commercial environments during the October retail cycle. Outdoor Decor leads volume contribution due to lawn inflatable and lighting system replacement cycles, while Online Retail captures the fastest growth trajectory as platform algorithms surface trend-responsive inventory to pre-season browsers. Specialty Stores retain margin concentration through licensed character exclusives and experiential merchandising that Discount Stores cannot replicate.
The Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1500 that govern textile and plastic decoration surfaces, while California's Proposition 65 labeling requirements extend compliance obligations for phthalate and lead content disclosures to all interstate sellers. The Federal Trade Commission's Green Guides further constrain environmental marketing claims on biodegradable or recyclable packaging, forcing material transparency in product descriptions. Stakeholders must monitor how state-level extended producer responsibility legislation evolves to determine whether seasonal decoration take-back obligations shift cost structures toward reusable or modular design formats.
Market Dynamics
Subscription-based curation is restructuring how US households build annual decoration collections, shifting one-time purchases toward recurring revenue relationships while compressing traditional retail seasonality.
Growth Catalysts
- 16 CFR Part 1500 Compliance:The Consumer Product Safety Commission's flammability standards for textile and plastic surfaces drive material innovation and premium positioning among safety-conscious suburban buyers.
- Airblown Technology Platforms:Proprietary inflatable manufacturing processes reduce unit costs and enable larger-scale lawn displays, expanding addressable household penetration.
- Texas-Florida-California Concentration:Suburban markets in these three states combine household density, disposable income, and strong seasonal participation rates to anchor national demand.
Market Restraints
- Petroleum-Based Input Volatility:Thermoplastic polymer feedstock costs fluctuate with crude oil markets, compressing margins on injection-molded and rotomolded products.
- Single-Use Cellulose Waste:Paper and cardboard decoration categories face mounting landfill pressure and municipal disposal restrictions.
- California Proposition 65:Phthalate and lead content disclosure requirements extend compliance costs to all interstate sellers, disproportionately burdening small catalog operators.
Strategic Opportunities
- Modular Reusable Formats:Extended producer responsibility legislation in select states is forcing design shifts toward take-back-ready components and disassembly-friendly construction.
- Licensed Character Exclusives:Specialty retail channels capture margin concentration through experiential merchandising that discount competitors cannot replicate.
- Platform Algorithm Distribution:Online retail algorithms surface trend-responsive inventory to pre-season browsers, compressing discovery-to-purchase cycles.
Industry Challenges
- Rotational Molding Technician Scarcity:Skilled labor gaps in thermoforming and die-cutting operations constrain production scaling during compressed September-October demand windows.
- Green Guides Marketing Compliance:The Federal Trade Commission's environmental claim constraints force material transparency investments that smaller manufacturers struggle to document.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Halloween Decorations Market |
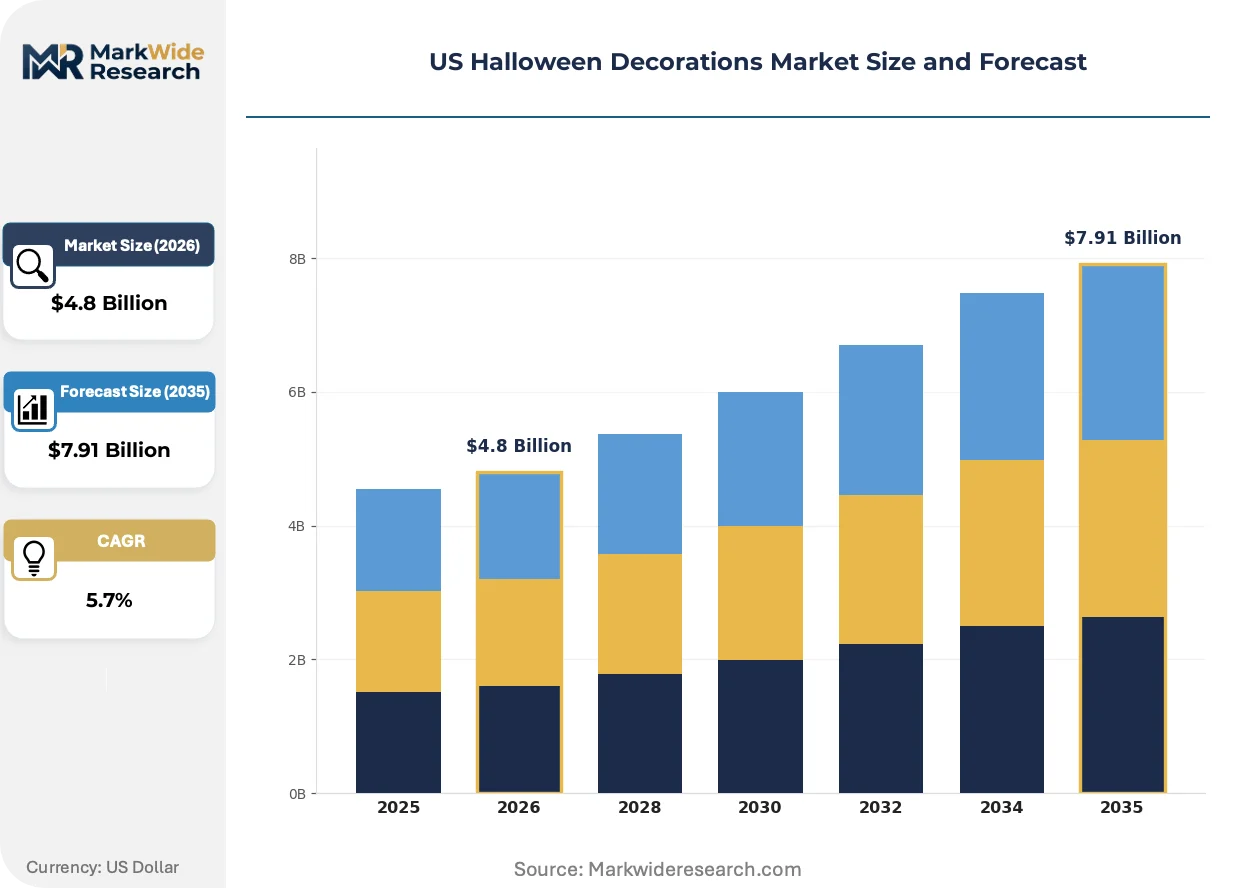
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Decor, Outdoor Decor, Costumes, Props Material: Plastic, Fabric, Paper, Foam Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Discount Stores Price Tier: Premium, Mid-Range, Economy, Value |
| Companies Covered | Distortions Unlimited, Gemmy Industries, Spirit Halloween, Amscan, Russ Berrie and Company, Home Depot, The Horror Dome, Rubies Costume Company, Crate and Barrel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Halloween Decorations Market Strategic Shifts
Smart connectivity and sustainable materials are converging to redefine how US consumers deploy and experience seasonal displays, with implications for manufacturing specifications and retail merchandising.
App-controlled lighting systems is expanding into mainstream residential outdoor installations. These Bluetooth and Wi-Fi enabled products allow programmable color sequencing and synchronization with music. Middle-income suburban households in Texas and Florida are adopting these systems at accelerating rates. This technology is expanding into adjacent holiday categories, forcing traditional incandescent manufacturers to reposition around price-sensitive legacy segments.
The Consumer Product Safety Commission maintains active enforcement of 16 CFR Part 1500 surface flammability protocols for textile and plastic decorations. Testing laboratory backlogs and documentation requirements now extend product development timelines by four to six weeks. Small-batch importers and domestic craft producers face disproportionate compliance burdens, driving consolidation toward scaled manufacturers with captive testing capabilities.
Rental and subscription procurement models are displacing outright ownership among younger household formations. Curated decoration boxes delivered in August-September cycles allow consumers to refresh aesthetics annually without storage obligations. This behavior concentrates in coastal metropolitan markets where apartment living limits attic and garage inventory capacity. Specialty retailers and direct-to-consumer platforms are capturing this shift through tiered membership structures that bundle delivery, setup guidance, and post-season return logistics.
US Halloween Decorations Market Segmentation
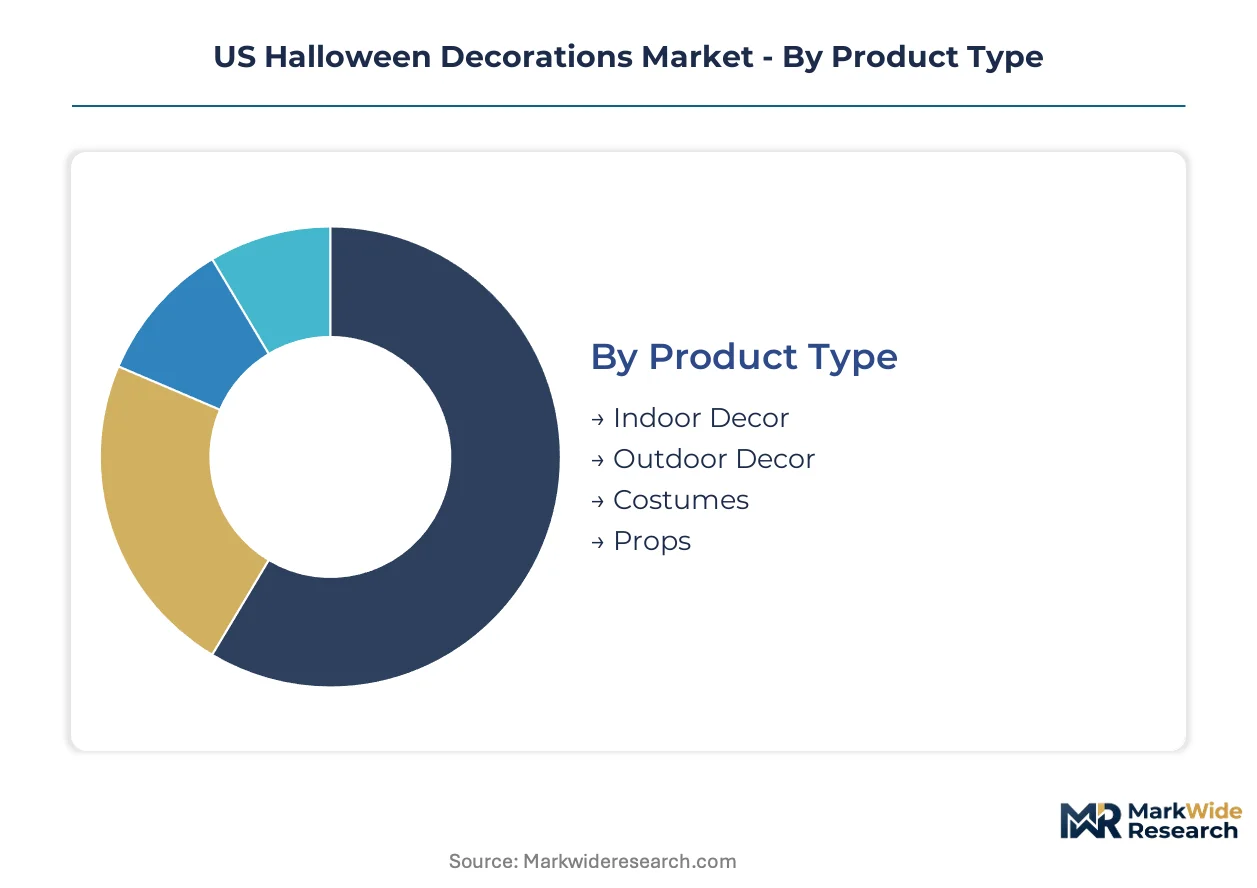
Segmentation in US Halloween decorations reveals how replacement cycles, material durability, and channel accessibility fragment purchasing behavior across suburban households. Upgrade patterns differ sharply between lawn display investments and disposable interior accents.
Product Type:
Replacement-cycle intensity varies dramatically by display location, with outdoor installations demanding weather-resistant engineering and indoor pieces prioritizing storage efficiency.
- Outdoor Decor:Thermoplastic polymer and inflatable constructions dominate lawn and facade installations. Texas and Florida suburban households drive volume through annual lighting system upgrades and airblown technology refreshes, constrained by compressed September-October installation windows.
- Indoor Decor:Synthetic textile and cellulose-based substrates furnish residential interiors with tabletop, wall-mounted, and suspended ornamental pieces. California metropolitan markets concentrate demand for compact, apartment-appropriate formats where storage limitations favor disposability.
- Costumes:Apparel and accessory combinations fabricated from synthetic textiles and foam substrates for personal wear during seasonal events.
- Props:Freestanding accent pieces including animatronics, figurines, and themed display objects for residential and commercial environments.
Volume placements concentrate in Outdoor Decor; the faster expansion belongs to Indoor Decor.
Material:
Cost tier alignment shapes material selection, with petroleum-derived inputs competing against sustainable alternatives under mounting regulatory pressure.
- Plastic:Rotationally molded and thermoformed thermoplastic polymers enable weather-resistant lawn inflatables and injection-molded props. Suburban Texas markets absorb the highest volume of these durable, multi-season formats despite crude oil price volatility compressing manufacturer margins.
- Fabric:Synthetic textile substrates including polyester and nylon blends furnish costumes, drapery, and soft decorative elements. Florida coastal households drive replacement demand for humidity-resistant, quick-dry formulations in outdoor applications.
- Paper:Die-cut and printed cellulose substrates produce disposable window displays, hanging decorations, and craft-oriented accent pieces facing municipal landfill restrictions.
- Foam:Expanded polystyrene and polyurethane formulations create lightweight tombstones, architectural props, and carved decorative elements.
Plastic commands the largest placement volumes; fabric gains share fastest among material categories.
Distribution Channel:
Geographic penetration patterns diverge between platform-native discovery and experiential retail formats that anchor suburban shopping corridors.
- Specialty Stores:Curated assortments emphasizing licensed character exclusives and immersive merchandising environments. California and Texas suburban markets sustain margin concentration through destination shopping experiences that discount competitors cannot replicate.
- Online Retail:Algorithm-driven inventory surfacing responds to pre-season browsing patterns and trend velocity. Platform distribution compresses discovery-to-purchase cycles fastest among younger household formations in metropolitan coastal markets.
- Supermarkets:Seasonal aisle placement capturing impulse purchases alongside grocery shopping routines in high-frequency retail locations.
- Discount Stores:Price-competitive basic assortments targeting value-sensitive buyers with limited SKU depth and minimal experiential investment.
Specialty Stores anchor volume concentration; Online Retail climbs the fastest among channel alternatives.
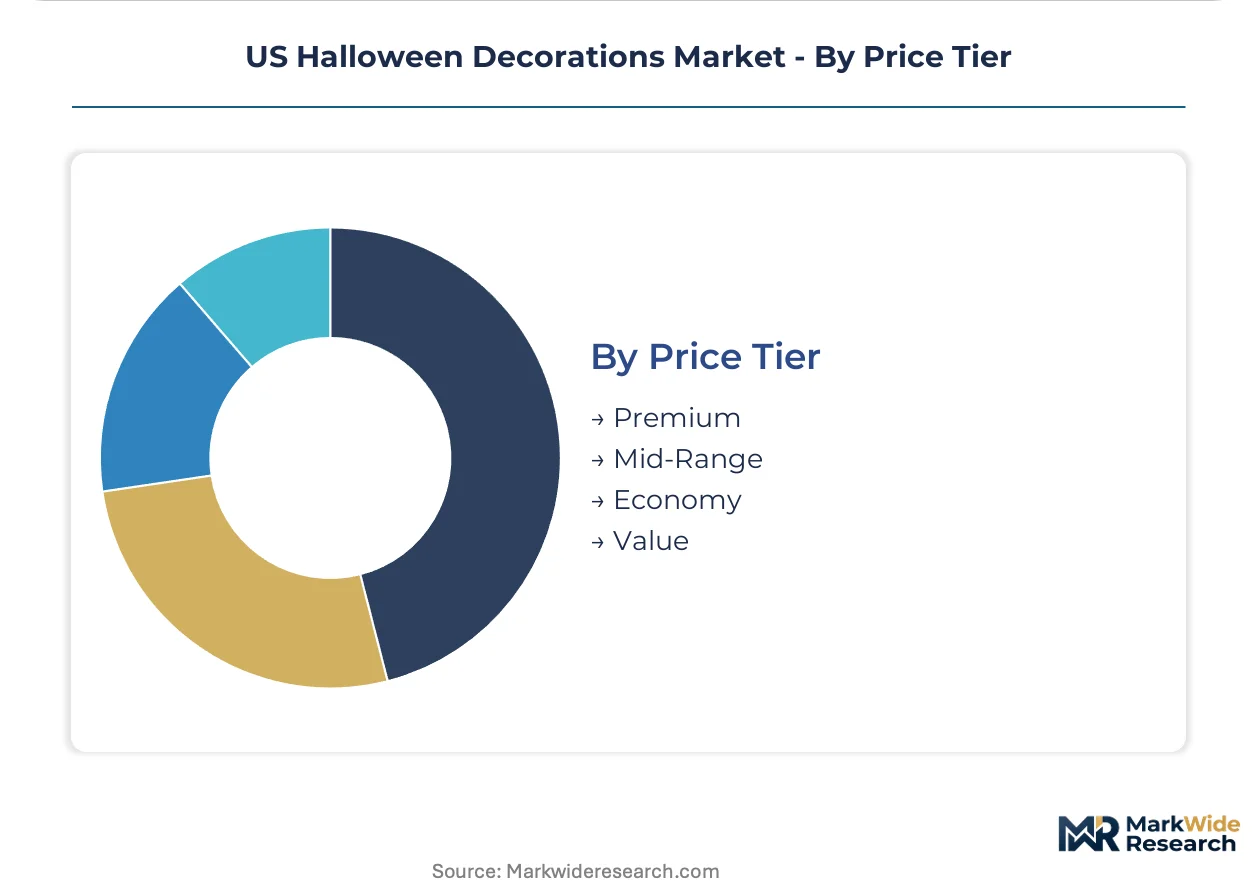
Price Tier:
Customer type stratification separates collectors building multi-year inventories from single-season participants prioritizing immediate visual impact.
- Premium:Proprietary technology platforms, licensed intellectual property, and smart-connected features command elevated price positioning. Affluent suburban households across California's Bay Area and Dallas-Fort Worth metroplex sustain this tier through technology-forward lawn display investments.
- Mid-Range:Branded assortments balancing durability and design sophistication for repeat purchasers building annual collections. Texas and Florida suburban markets concentrate this segment's volume through established retail relationships.
- Economy:Functional decorations meeting basic seasonal display needs without proprietary features or extended durability guarantees.
- Value:Entry-level price positioning targeting first-time participants and single-season usage with minimal reuse intent.
Mid-Range captures placement concentration; Premium expands most quickly among price tier alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing clusters in the Midwest and Southeast supply decoration products to consumption centers concentrated in suburban Sun Belt markets. Texas, Florida, and California absorb disproportionate volume due to household density intersecting with strong seasonal participation rates.
Texas
Suburban Dallas-Fort Worth and Houston metroplexes drive outdoor decoration volume through annual lawn display upgrades and airblown technology refreshes. The Texas Commission on Environmental Quality oversees municipal landfill restrictions affecting paper and cardboard decoration disposal. San Antonio's distribution corridor channels inventory to South Texas markets where Hispanic cultural celebrations extend seasonal display periods.
Florida
Coastal suburban households from Tampa to Miami generate replacement demand for humidity-resistant synthetic textiles and quick-dry fabric formulations. The Florida Department of Environmental Protection administers extended producer responsibility frameworks pressuring single-use material reduction. Orlando's retail logistics cluster supports temporary pop-up store networks that compress September-October deployment windows.
California
Bay Area and Los Angeles metropolitan markets concentrate premium-tier demand for smart-connected lighting systems and compact apartment-appropriate formats. Proposition 65 mandates phthalate and lead content disclosures that extend compliance costs to all interstate sellers shipping into the state. Sacramento's Central Valley distribution hubs coordinate West Coast fulfillment for platform-native retailers.
Illinois
Greater Chicago anchors Midwest consumption for mid-range branded assortments balancing durability with design sophistication. The Illinois Environmental Protection Agency monitors seasonal waste streams from disposable paper and foam decoration categories. Rockford's manufacturing corridor houses rotational molding operations supplying thermoplastic lawn inflatables to national distribution networks.
Ohio
Cleveland and Columbus suburban markets sustain steady demand for traditional decoration categories with established retail relationships. The Ohio Environmental Protection Agency enforces landfill diversion targets affecting post-season disposal economics for cellulose-based products. Cincinnati's polymer processing cluster feeds injection-molded prop manufacturing for multi-season durability specifications.
US Halloween Decorations Market Competitive Environment
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base fragments between scaled manufacturers with captive testing capabilities and small-batch importers facing disproportionate compliance burdens. Three archetypes dominate: temporary retail footprint operators, proprietary technology platform holders, and broad-catalog scale manufacturers. Competitive moves concentrate on licensed character exclusives and experiential merchandising investments that discount competitors cannot replicate.
Within the technology-forward tier, Gemmy Industries anchors proprietary airblown manufacturing platforms that reduce unit costs and enable larger-scale lawn displays. Spirit Halloween exemplifies the temporary retail archetype through seasonal real estate dominance in high-traffic suburban corridors. Amscan occupies a position as the broad-catalog scale manufacturer competing on manufacturing depth rather than exclusivity across paper and plastic decoration categories.
| Leading Market Players |
|---|
| Distortions Unlimited |
| Gemmy Industries |
| Spirit Halloween |
| Amscan |
| Russ Berrie and Company |
| Home Depot |
| The Horror Dome |
| Rubies Costume Company |
| Crate and Barrel |
| Others |
Value Chain & Pricing Dynamics
Airblown technology platform adoption simultaneously compresses per-unit manufacturing costs and concentrates production among scaled rotomolded thermoplastic specialists, reshaping margin distribution between captive technology holders and commodity fabricators. This production-method transition rewards vertical integration into polymer feedstock sourcing while penalizing small-batch importers facing disproportionate CPSC testing documentation burdens.
Pricing Analysis
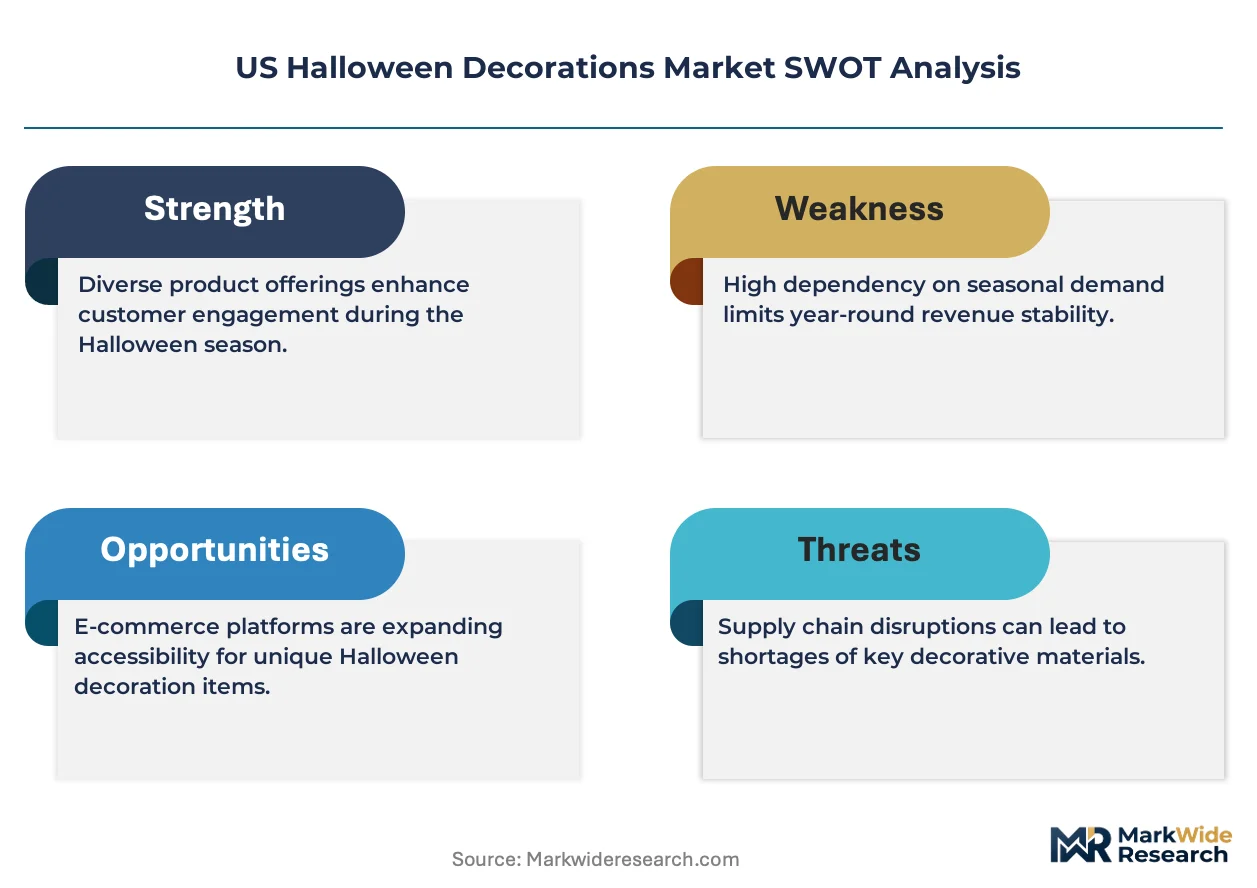
Margin tightening in the mid-range tier reflects petroleum-based input volatility and California Proposition 65 compliance cost absorption. Three-tier pricing structure across premium, standard, and economy levels differentiates through smart-connectivity features and licensed character exclusives. Cost-down pressure on economy-tier cellulose products accelerates because municipal landfill restrictions compress disposability economics. Value-sensitive first-time participants in Texas discount channels exhibit highest price sensitivity; affluent Bay Area households purchasing app-controlled lighting systems show least.
Supply Chain Analysis
Reverse-logistics flows for subscription-curated decoration boxes concentrate post-season returns processing in Orlando and Sacramento distribution clusters, creating secondary refurbishment channels for reusable modular components. Manufacturing draws from China for thermoplastic polymer injection molding, Vietnam for synthetic textile fabrication, and domestic Midwest rotational molding operations for airblown platforms. Single-source vulnerability concentrates in specialty-grade thermoplastic feedstock suppliers. Distribution runs through temporary pop-up networks anchored by Spirit Halloween's seasonal real estate dominance and platform-native algorithmic inventory surfacing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where proprietary airblown technology platforms and captive CPSC testing capabilities constitute the decisive upstream levers separating scaled incumbents from margin-compressed assemblers.
For Market Incumbents: Anticipate subscription-model displacement of one-time purchases by securing exclusive licensed character portfolios that specialty retail channels cannot replicate. Defend margin position through backward integration into thermoplastic polymer compounding and captive 16 CFR Part 1500 testing laboratories that accelerate September-October production windows. Channel control through temporary real estate dominance in Texas-Florida-California suburban corridors remains essential. For New Entrants and Emerging Players: Begin with coastal metropolitan apartment-dwelling segments where storage constraints favor rental and subscription procurement models over ownership. White-space targets include curated decoration boxes with tiered membership structures bundling delivery and post-season return logistics. Go-to-market through direct-to-consumer platforms leveraging algorithmic trend-responsive inventory surfacing to compress discovery-to-purchase cycles among younger household formations. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by broad-catalog scale manufacturers seeking proprietary technology platforms and licensed character exclusives. Long-term viability favors targets with modular reusable design capabilities aligned to extended producer responsibility legislation evolution. Monitor state-level take-back obligation mandates as the critical inflection signal for reusable format adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Technology Licensing | Airblown platform holders license manufacturing processes to capture royalty streams from scaled rotomolded production. |
| Licensed Character Portfolio Expansion | Exclusive IP agreements with entertainment studios differentiate specialty retail assortments from discount competitors. |
| Subscription Model Infrastructure Buildout | Tiered membership structures with post-season reverse logistics capture recurring revenue from storage-constrained urban households. |
| CPSC Testing Capability Integration | Captive 16 CFR Part 1500 documentation laboratories compress product development timelines and consolidate small-batch competitors. |
| Modular Reusable Design Transition | Disassembly-friendly construction formats anticipate extended producer responsibility take-back obligations in select states. |
Study Parameters
Trade association filings, customs import records, and CPSC enforcement databases formed the secondary backbone, cross-referenced against primary interviews with rotational molding plant managers, specialty retail category buyers, polymer procurement leads at downstream manufacturers, and subscription platform operations directors. Bottom-up demand modeling across suburban household penetration rates and replacement-cycle frequencies triangulated against top-down retail channel revenue allocation estimates.
Historical trendline analysis of September-October sales velocity patterns and pre-season browsing-to-purchase conversion ratios anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material substrate, distribution channel, and price tier, with smart-connectivity adoption rates and licensed character refresh cycles as industry-specific forecast inputs. CAGRs derived from weighted average of segment-level growth trajectories and channel shift elasticity parameters.
Underlying measurement precision varies by segment; outdoor decor and online retail carry tighter precision than costume and prop categories due to data availability disparities. Forecasts reflect assumptions regarding suburban household formation rates, crude oil price bands, and state-level environmental regulation evolution. Practitioners should monitor Texas-Florida-California seasonal participation intensity and extended producer responsibility legislative advancement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Window Blinds Market
Homecare and Decor
Europe Flower Pots and Planters Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Europe Decorative Laminates Market