
 Europe Flower Pots and Planters Market | 2026-2036
Europe Flower Pots and Planters Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flower Pots and Planters Market Insights
CE marking under the Construction Products Regulation is rotating as the primary gate for durable outdoor planters entering the European Economic Area. Scheurich GmbH & Co. KG anchors its position through deep R&D ties with German horticultural research stations. Deroma Group leverages extensive kiln infrastructure across Italy's Emilia-Romagna ceramics belt to sustain cost advantages in terracotta. LECHUZA competes through proprietary sub-irrigation reservoir systems that differentiate its self-watering range from commodity alternatives.
Europe flower pots and planters comprise vessels engineered from fired clay, thermoplastic polymers, or metal alloys, designed to contain growing media and manage root-zone moisture for ornamental or food plants, typically rated for UV stability, frost resistance, and load-bearing capacity between 5 kg and 200 kg depending on scale. Plastic dominates volume across mass retail channels where injection-molded polypropylene offers the lowest unit cost per liter of soil capacity, yet ceramic commands margin pools in the residential segment where Italian and Portuguese artisan workshops supply hand-finished vessels to premium garden centers. The commercial end user category is expanding fastest as facility management contractors specify lightweight polymer planters for rooftop installations where structural load limits apply.
REACH compliance through ECHA governs chemical migration from colored plastics and glazed ceramics into soil matrices, while the EU Green Deal's packaging and packaging waste directive shapes recycled content mandates that resurface in retailer procurement specifications. EFSA guidelines on food contact materials extend to planters used for edible cultivation, narrowing the supplier base for herb and vegetable containers. Stakeholders must monitor how the CSRD's scope expansion will force mid-tier manufacturers to document supply chain emissions or surrender shelf space to certified competitors.
Market Dynamics
The EU Green Deal's circular economy mandates are compressing material choices across European planter manufacturing, forcing rapid substitution of virgin polypropylene with recycled and bio-based alternatives while rewiring supplier qualification criteria at major retail chains.
Growth Catalysts
- Urban balcony gardening:Apartment-dwelling consumers in German and Dutch cities are accelerating replacement cycles for compact self-watering systems suited to limited outdoor space.
- REACH compliance differentiation:Manufacturers investing in ECHA-certified chemical migration testing for colored plastics are securing preferred supplier status with garden center chains prioritizing soil safety documentation.
- Rooftop installation specifications:Facility management contractors across France and Italy are specifying lightweight polymer planters where structural load limits restrict traditional ceramic deployment.
Market Restraints
- Natural gas cost volatility:Italian and Portuguese artisan workshops firing terracotta face margin compression from fluctuating kiln energy inputs, concentrating premium ceramic supply in Emilia-Romagna's established ceramics belt.
- Recycled polypropylene supply concentration:Post-industrial plastic feedstock availability clusters with German and Benelux reprocessors, creating geographic bottlenecks for southern European manufacturers.
- Frost resistance technical ceiling:Bio-based material formulations currently fail EN 771 durability standards for outdoor winter exposure, limiting application in Nordic climates.
Strategic Opportunities
- CSRD disclosure preparation:Mid-tier manufacturers documenting supply chain emissions ahead of mandatory reporting deadlines can capture shelf space from competitors surrendering retail access due to documentation gaps.
- Sub-irrigation technology convergence:Integration of moisture sensors with LECHUZA-style reservoir systems creates premium positioning for connected home gardening applications in Dutch and Belgian markets.
- Food contact certification expansion:EFSA-compliant containers for edible cultivation represent underdeveloped white space as herb and vegetable balcony growing accelerates in Paris and Milan apartment complexes.
Industry Challenges
- Materials engineering talent scarcity:Formulation chemists capable of balancing bio-content ratios with UV stability and load-bearing specifications command premium compensation in Germany's polymer research clusters.
- CE marking timeline compression:Construction Products Regulation certification for durable outdoor planters requires extended laboratory testing cycles that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flower Pots and Planters Market |
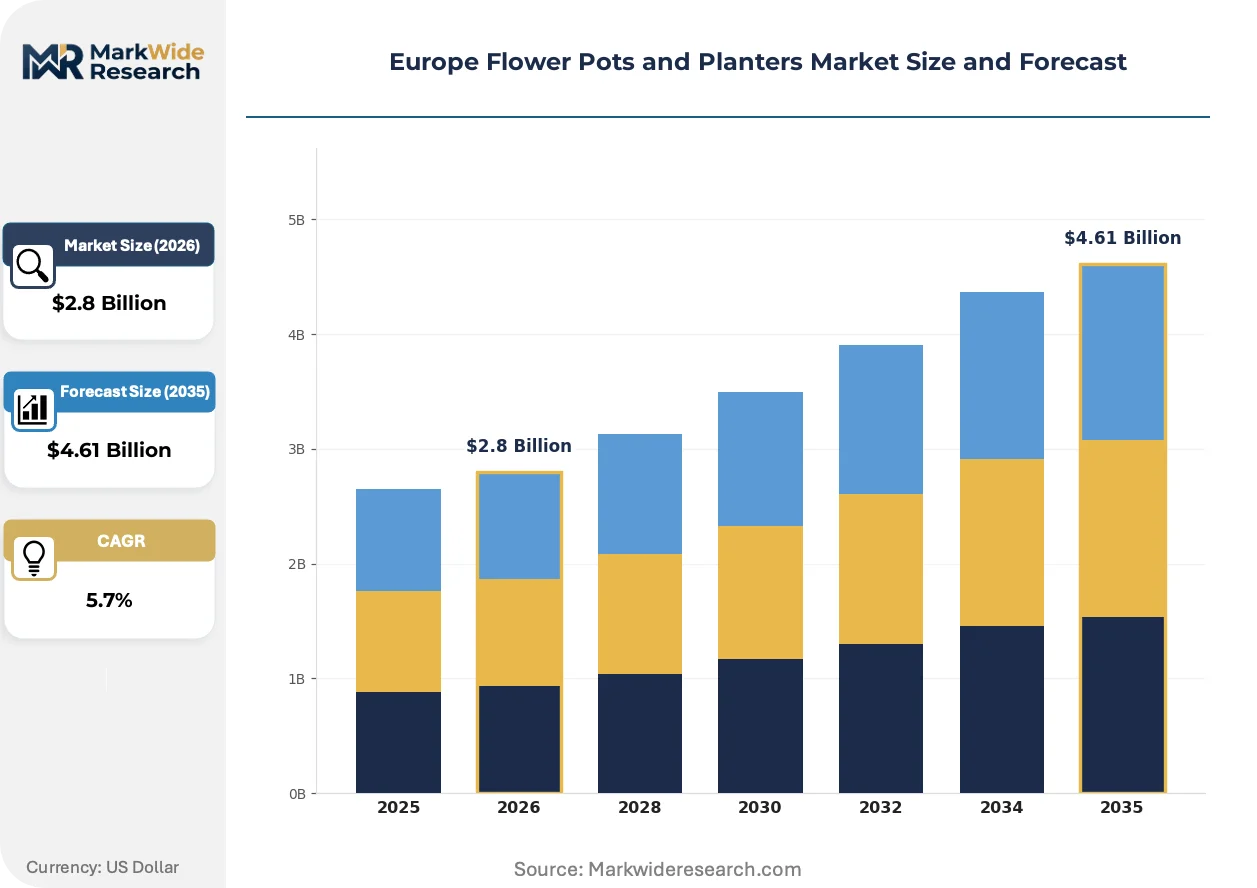
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Terracotta, Ceramic, Metal End User: Residential, Commercial, Landscaping, Retail Size: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail Stores, Garden Centers, Wholesale |
| Companies Covered | elho B.V., Scheurich GmbH & Co. KG, Deroma Group, LECHUZA, Keter Group, Poppelmann GmbH and Co. KG, Stefanplast S.p.A., BigPlast, The HC Companies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flower Pots and Planters Market Trends and Innovations
Material science advances and regulatory disclosure requirements are converging to reshape competitive positioning across European planter manufacturing, with sustainability verification replacing aesthetic differentiation as the primary purchasing filter.
Sub-irrigation reservoir technology is miniaturizing. LECHUZA's proprietary wick-based systems now scale below 5-liter soil capacity for desktop herb cultivation. German apartment retailers are adopting these compact units at triple the rate of conventional drainage-hole alternatives. The format compression is enabling year-round indoor sales cycles that decouple revenue from traditional spring planting seasons.
CSRD scope expansion is forcing supply chain transparency. The EU's Corporate Sustainability Reporting Directive will require mid-tier manufacturers to document Scope 3 emissions from 2026. Italian ceramic producers with captive clay sourcing are responding faster than polymer converters dependent on fragmented recycled feedstock networks. Premium garden centers in France are already screening suppliers for preliminary carbon footprint disclosures.
Balcony gardening behaviors are professionalizing equipment expectations. Amateur urban growers in Amsterdam and Copenhagen now specify load-bearing capacity, UV stability ratings, and frost resistance grades previously demanded only by commercial landscapers. This specification elevation is compressing price tolerance for unbranded commodity alternatives while expanding margin pools for certified performance tiers in Benelux retail channels.
Europe Flower Pots and Planters Market Segmentation
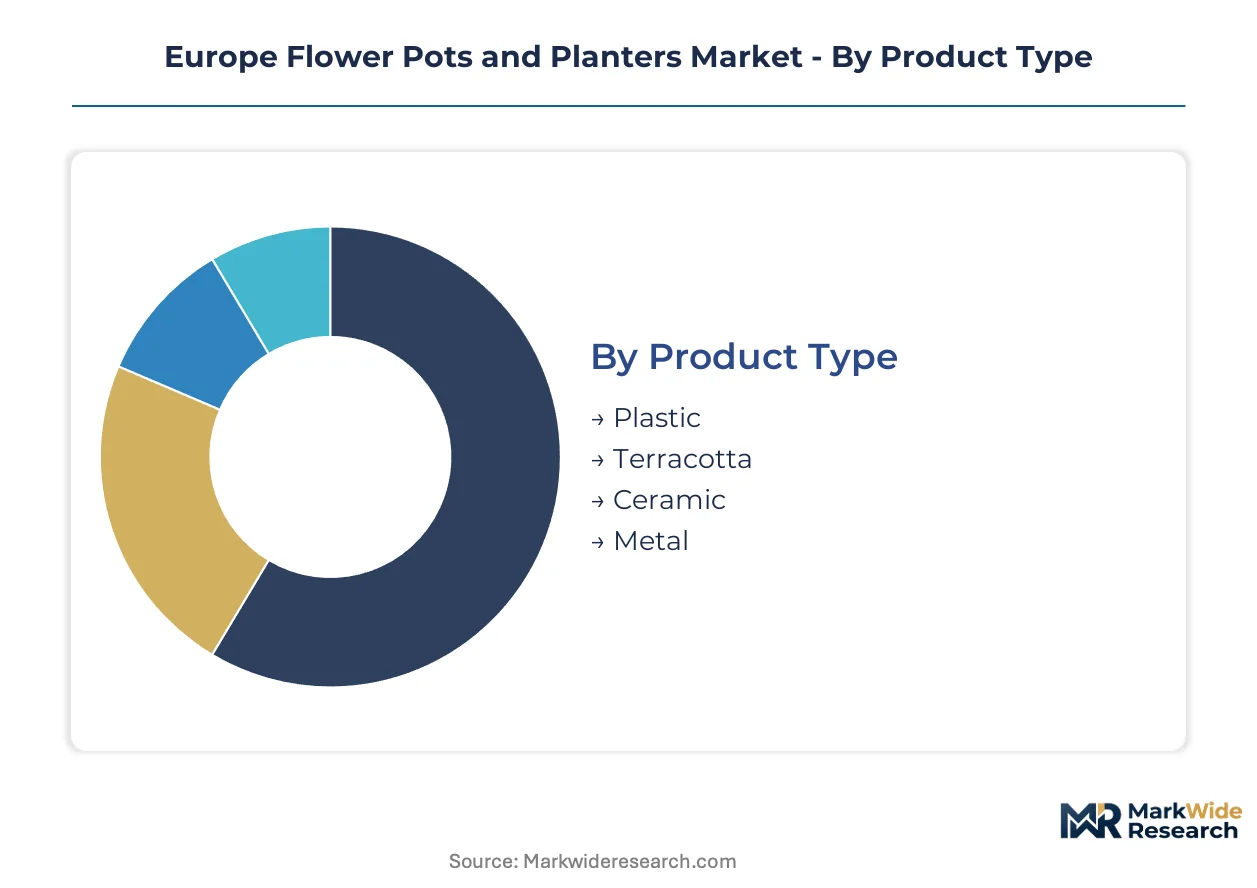
Channel dynamics in the Europe flower pots and planters market create distinct segmentation pressures. Mass retailers favor high-volume plastic formats while premium garden centers drive ceramic and terracotta margins. Understanding how each segment flows through specific distribution pathways shapes procurement and pricing strategy.
Product Type:
Channel-mix patterns concentrate plastic through mass retail and DIY chains, while terracotta and ceramic command shelf space in specialized garden centers and artisan workshops across Italy and Portugal.
- Plastic:Injection-molded polypropylene dominates unit economics with the lowest cost per liter of soil capacity. German and Dutch mass retailers move these formats at highest velocity, though recycled content mandates under the EU Green Deal are rewiring supplier qualification criteria.
- Terracotta:Fired clay vessels from Emilia-Romagna's ceramics belt sustain margin pools through hand-finishing differentiation. Italian garden centers and Parisian terrace specialists stock these as premium alternatives, though natural gas cost volatility compresses workshop margins.
- Ceramic:Glazed stoneware offers frost resistance and aesthetic durability for permanent outdoor installation. Portuguese artisan producers supply French and Belgian premium channels.
- Metal:Zinc and corten steel planters target commercial rooftop specifications where load-bearing and wind resistance matter. Facility management contractors in Milan and Copenhagen specify these for structural installations.
By volume, plastic leads. By growth pace, recycled polymer formulations are climbing the fastest as retailer procurement specifications harden.
End User:
Cost tier stratification separates commodity residential purchases from specification-driven commercial contracts, with margin structures inverting across these boundaries.
- Residential:Balcony gardeners in Amsterdam and Berlin drive compact self-watering system adoption. LECHUZA-style reservoir formats now scale below 5-liter capacity for desktop herb cultivation.
- Commercial:Facility management contractors across France and Italy specify lightweight polymer planters where structural load limits restrict traditional ceramic deployment on rooftops and terraces.
- Landscaping:Professional installers demand frost resistance certification and UV stability documentation previously required only in Nordic climates.
- Retail:Garden center chains prioritize REACH-compliant chemical migration testing for colored plastics, narrowing supplier pools to ECHA-certified manufacturers.
Residential captures highest unit volume. Commercial contracts deliver steepest expansion trajectory as urban greening mandates proliferate.
Size:
Application logic governs size selection, with permanent plantings demanding larger soil volumes and seasonal rotations favoring compact formats.
- Small:Under 10-liter formats suit desktop herb cultivation and annual bedding displays. German apartment retailers adopt these at triple the rate of conventional drainage-hole alternatives.
- Medium:10-30 liter capacity serves terrace perennials and compact shrubs. French courtyard culture sustains year-round replacement cycles in this bracket.
- Large:30-80 liter vessels accommodate specimen trees and permanent rooftop installations. Benelux facility managers specify load-bearing ratings here.
- Extra Large:Above 80-liter formats target commercial landscaping and public realm projects. CE marking under the Construction Products Regulation gates durable outdoor deployment.
Medium sizes dominate revenue. Small formats are gaining share fastest as indoor cultivation professionalizes.
Distribution Channel:
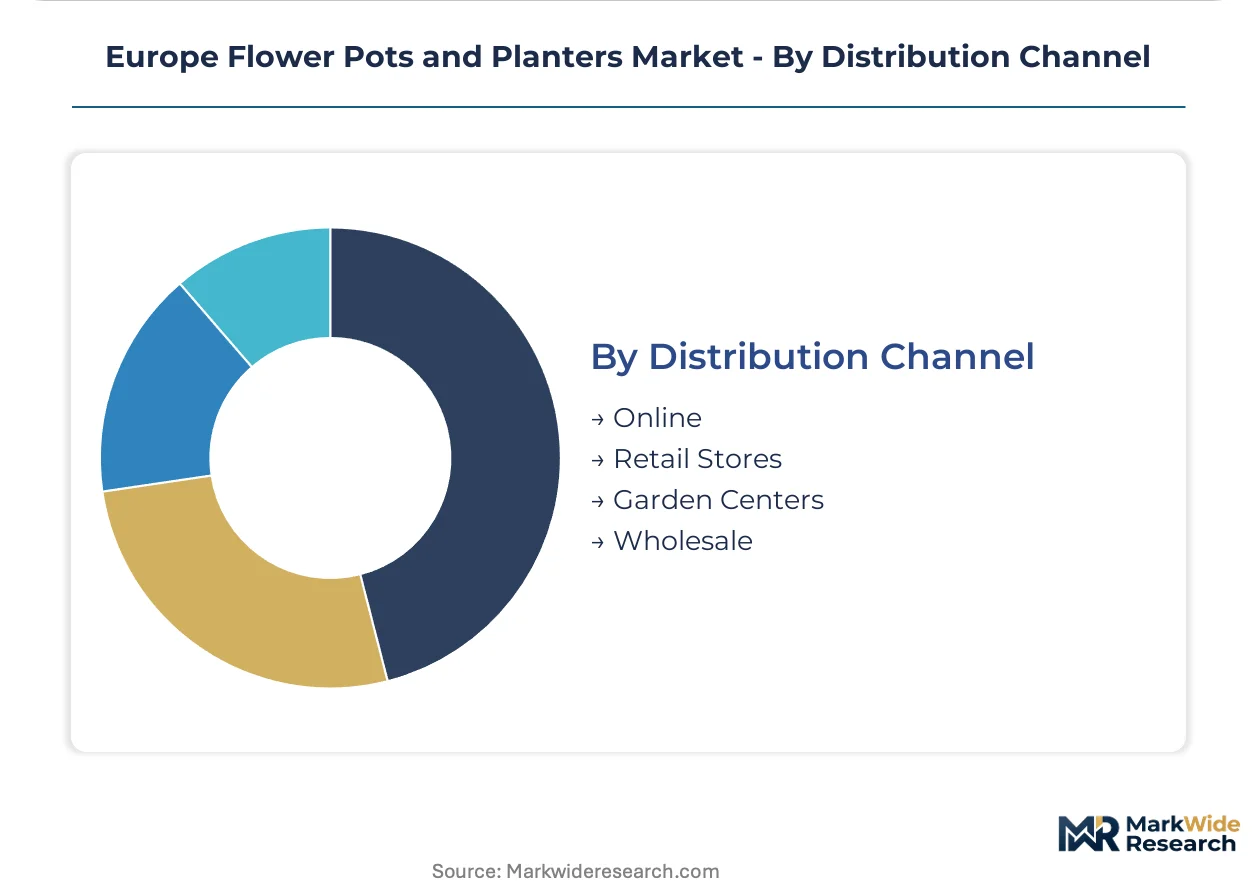
Customer type and purchase occasion split across channels, with impulse buying concentrated in physical retail and planned procurement shifting online.
- Online:Direct-to-consumer platforms capture replacement cycle purchases from experienced balcony gardeners. Dutch and Belgian markets show highest digital penetration for self-watering system reorders.
- Retail Stores:Mass merchants and DIY chains move high-volume plastic formats through seasonal displays. Spring planting season concentrates traffic here.
- Garden Centers:Premium independent and chain specialists stock certified ceramic and terracotta tiers. CSRD disclosure screening is already filtering supplier access in France.
- Wholesale:Landscape contractors and facility managers source large-format and commercial-grade specifications through trade distributors. Italian and German reprocessors cluster recycled polypropylene supply here.
Retail stores lead by transaction volume. Online channels show steepest expansion as subscription and reorder models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network connects Rotterdam's container terminals to Milan's industrial basin, underwriting planter distribution logistics across the continent's densest consumption belt.
Germany
Balcony gardening in Berlin and Hamburg apartment blocks drives compact self-watering system demand. REACH compliance through ECHA governs chemical migration testing for colored polypropylene formats. Bavarian polymer research clusters near Munich host formulation chemists developing bio-based material alternatives.
Netherlands
Amsterdam and Rotterdam urban densification accelerates vertical gardening installations on high-rise facades. The EU Green Deal's circular economy mandates pressure manufacturers toward recycled content thresholds. Dutch reprocessors in the Port of Rotterdam hinterland concentrate post-industrial plastic feedstock supply.
France
Parisian terrace culture and courtyard replacement cycles sustain year-round ceramic planter demand. EFSA guidelines on food contact materials extend to containers used for edible balcony cultivation. Île-de-Fance garden center chains already screen suppliers for preliminary CSRD carbon footprint disclosures.
Italy
Terrace and courtyard traditions in Milan and Rome support premium terracotta vessel replacement. CE marking under the Construction Products Regulation gates durable outdoor planter deployment. Emilia-Romagna's ceramics belt around Modena and Sassuolo sustains cost advantages in hand-finished kiln production.
United Kingdom
London's rooftop gardening initiatives and balcony cultivation trends expand polymer planter specifications. GDPR compliance shapes data handling for connected sub-irrigation systems with moisture sensors. Southeast England distribution hubs near the Channel Tunnel terminal handle cross-border fulfillment into Benelux markets.
Europe Flower Pots and Planters Market Competitive Landscape
Listed leaders compete with private specialists across material technology and distribution channel access, creating a tiered structure where scale-driven polymer converters face artisan ceramic workshops. Three archetypes dominate: German-Dutch polymer research specialists, Italian-Portuguese ceramic artisans, and Israeli-Belgian connected-hardware integrators. Competitive moves concentrate on M&A for recycled feedstock security and strategic partnerships with horticultural research stations for cultivar-specific vessel design.
Among German fabricators, Scheurich GmbH & Co. KG and Poppelmann GmbH and Co. KG occupy positions within the polymer conversion tier, representing scale-driven manufacturing archetypes. LECHUZA exemplifies the sub-irrigation technology specialist segment. Italian private specialists including Deroma Group and Stefanplast S.p.A. anchor the Mediterranean ceramic and polymer hybrid tier.
| Leading Market Players |
|---|
| elho B.V. |
| Scheurich GmbH & Co. KG |
| Deroma Group |
| LECHUZA |
| Keter Group |
| Poppelmann GmbH and Co. KG |
| Stefanplast S.p.A. |
| BigPlast |
| The HC Companies |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Italian ceramic workshops and Emilia-Romagna natural gas distributors lock in kiln energy costs while preserving margin visibility for terracotta vessel production. These contracts insulate artisan producers from spot market volatility that has compressed margins across Portugal's unhedged kiln operations.
Pricing Analysis
Volume-discount tiering structures separate garden center procurement from mass retail purchasing, with three-tier pricing stratification across premium hand-finished ceramic, standard injection-molded polymer, and economy virgin polypropylene formats. Certification grade under REACH and CE marking drives price differentiation between ECHA-compliant colored plastics and uncertified commodity alternatives. Cost compression in economy tiers is intensifying because recycled polypropylene feedstock bottlenecks concentrate pricing power with German and Benelux reprocessors. Mass retailers exhibit highest price sensitivity, while French terrace specialists tolerate premium positioning for documented frost resistance ratings.
Supply Chain Analysis
Port congestion at Rotterdam's container terminals elevates inbound logistics costs for Portuguese ceramic exporters serving Parisian garden center chains. Manufacturing gravity centers on Germany's polymer research clusters, Italy's Emilia-Romagna ceramics belt, and Portugal's artisan workshop regions. Raw material dependencies rest on natural gas for kiln firing, post-industrial polypropylene flake from Dutch reprocessors, and clay deposits from captive Italian quarries. Single-source vulnerability concentrates in recycled feedstock networks where German reprocessors control southern European supply. Distribution runs through Rhine-Alpine freight rail corridors connecting Rotterdam to Milan's industrial basin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution defense defines strategic priority as DIY upcycling and 3D-printed vessel alternatives threaten commoditized plastic tiers. Incumbents must differentiate through performance certification and circular economy compliance to retain shelf access.
For Market Incumbents: Fortify backward integration into recycled polypropylene feedstock through offtake partnerships with Rotterdam-area reprocessors, securing supply continuity as EU Green Deal mandates harden. Invest in ECHA-certified chemical migration testing to preempt garden center procurement screening. Capacity addition in Germany's polymer research clusters anchors formulation talent for bio-based material transitions.
For New Entrants and Emerging Players: Anchor in EFSA-compliant food contact certification for edible cultivation containers, the most penetrable white space as Paris and Milan balcony herb growing accelerates. Target compact sub-irrigation formats below 5-liter capacity where LECHUZA-style systems have established demand but supply concentrates with established brands. Direct-to-consumer subscription models for replacement wick components offer defensible go-to-market positioning.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sub-irrigation technology specialists with proprietary reservoir consumables and subscription reorder platforms. Long-term viability across the projection horizon favors acquisition targets with captive clay sourcing and in-house kiln infrastructure that insulate against energy cost volatility. Italian ceramic producers with preliminary CSRD carbon footprint documentation signal readiness for premium garden center channel expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Feedstock Security | Backward integration into German and Benelux reprocessor networks secures EU Green Deal compliance. |
| EFSA Food Contact Certification | Edible cultivation container approval unlocks Paris and Milan balcony gardening demand pools. |
| Sub-Irrigation Sensor Integration | Moisture sensor convergence with LECHUZA-style reservoirs targets Dutch connected home markets. |
| CSRD Disclosure Preparation | Scope 3 emissions documentation preserves garden center shelf access ahead of mandatory reporting. |
| Emilia-Romagna Kiln Modernization | Natural gas efficiency investments defend terracotta margin pools against Portuguese competition. |
Research Methodology
A spread of perspectives from polymer formulation chemists, Italian ceramic workshop owners, French garden center procurement managers, and Dutch facility management contractors converged on the working assumptions. Primary interviews combined with secondary validation from ECHA REACH registration databases, EU customs trade data, and SEC filings of listed polymer converters. Bottom-up triangulation across product type, end user, size, and distribution channel dimensions anchored volume estimates, while top-down cross-checks against construction sector expenditure data refined value projections.
Segmentation dimensions modeled include material composition, end user category, vessel capacity tier, and distribution channel structure across the projection horizon. CAGRs were derived from regression analysis of historical replacement cycle patterns, urban densification indices, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated EU Green Deal recycled content threshold trajectories and EFSA food contact material guideline expansion scenarios.
Underlying assumptions cover stable natural gas supply to Emilia-Romagna kilns and continued Rotterdam port throughput capacity, with deviation risk concentrated in bio-based material durability failures under Nordic frost exposure testing. Recalibration cycles align with material shifts in CSRD scope expansion and REACH substance restriction updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Window Covering Market
Homecare and Decor
Soundproof Door Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
Fireplace and Stove Market