
 Interior Design Services Market | 2026-2036
Interior Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
Interior Design Services Market Outlook
The interior design services industry is pivoting on a widening split between hyper-customized, technology-integrated premium offerings and standardized, cost-driven commodity packages for mid-market clients. Gensler leverages its global studio network to sustain dominance in large-scale commercial projects across multiple continents. CannonDesign anchors its competitive position through deep specialization in healthcare and science facility interiors. Decorilla competes by extending affordable digital-first design services to homeowners through proprietary visualization platforms.
Interior design services encompass the professional planning, specification, and coordination of spatial environments, materials, lighting, and furnishings to achieve functional and aesthetic objectives for built interiors. Practitioners employ building information modeling, photorealistic rendering, and material lifecycle databases to deliver code-compliant, occupant-centered spaces for residential, commercial, and institutional clients. Residential design leads absolute revenue contribution as homeowners prioritize wellness-oriented layouts and smart home integration. Commercial design represents the fastest-expanding margin pool, driven by corporations seeking hybrid workplace configurations that balance collaboration density with individual focus zones. Space planning occupies a mature but essential position, particularly within renovation projects where structural constraints limit layout flexibility.
The United States Environmental Protection Agency and the Department of Energy shape material specifications through indoor air quality standards and energy efficiency mandates for lighting and HVAC integration. The European Union's Energy Performance of Buildings Directive and CE marking requirements for furnishings constrain product selection while creating demand for certified sustainable design expertise. Stakeholders must monitor evolving carbon disclosure rules for construction materials and decide whether to build in-house environmental consulting capabilities or partner with specialized sustainability firms.
Market Dynamics
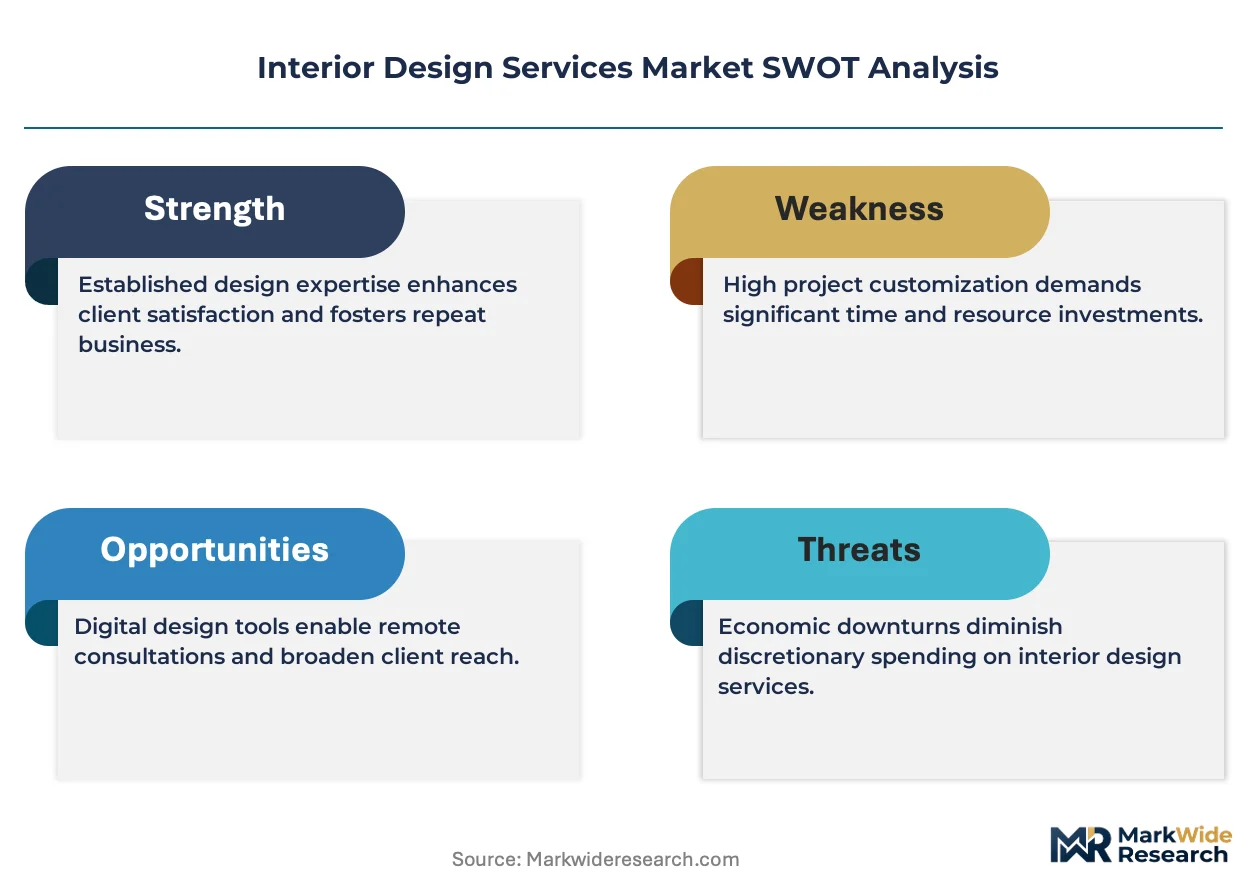
The interior design services market is bifurcating under pressure from building energy codes that mandate material transparency and HVAC integration, forcing studios to either build certified sustainability capabilities or cede premium contracts to specialized competitors.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Mandates for energy-efficient retrofits across Germany, France, and Italy are accelerating renovation project pipelines and expanding fee pools for compliance-certified designers.
- Smart home integration:Residential clients in the United States and China are specifying wellness-oriented layouts with automated lighting and air quality systems, extending project scopes beyond traditional decoration.
- Hospitality sector expansion:Luxury hotel developers across Dubai, Singapore, and Miami are increasing design budgets to differentiate properties through immersive, locally-sourced interiors.
Market Restraints
- Certified material scarcity:EPA indoor air quality standards and EU REACH compliance requirements constrain specification options, extending procurement timelines and compressing project margins.
- Specialized labor concentration:Building information modeling expertise pools in London, New York, and Shanghai, creating talent access bottlenecks for studios outside these clusters.
- Freelance platform commoditization:Digital-first services are absorbing mid-market residential demand, pressuring fee structures for traditional hourly billing models.
Strategic Opportunities
- Carbon disclosure acceleration:The EU Corporate Sustainability Reporting Directive creates demand for lifecycle assessment capabilities that most competitors lack, opening consulting revenue streams.
- Saudi Arabia giga-projects:Neom and Red Sea developments are importing international design expertise at premium rates, offering first-mover positioning before local capacity matures.
- Generative design convergence:AI-powered space planning tools combined with photorealistic rendering are enabling fixed-fee productization of services previously billed hourly.
Industry Challenges
- BIM-LEED coordination complexity:Projects requiring both building information modeling and LEED or BREEAM certification demand cross-functional teams that smaller studios struggle to assemble.
- Client expectation compression:Visualization platforms have conditioned residential buyers to expect photorealistic previews before contract signature, frontloading unpaid labor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interior Design Services Market |
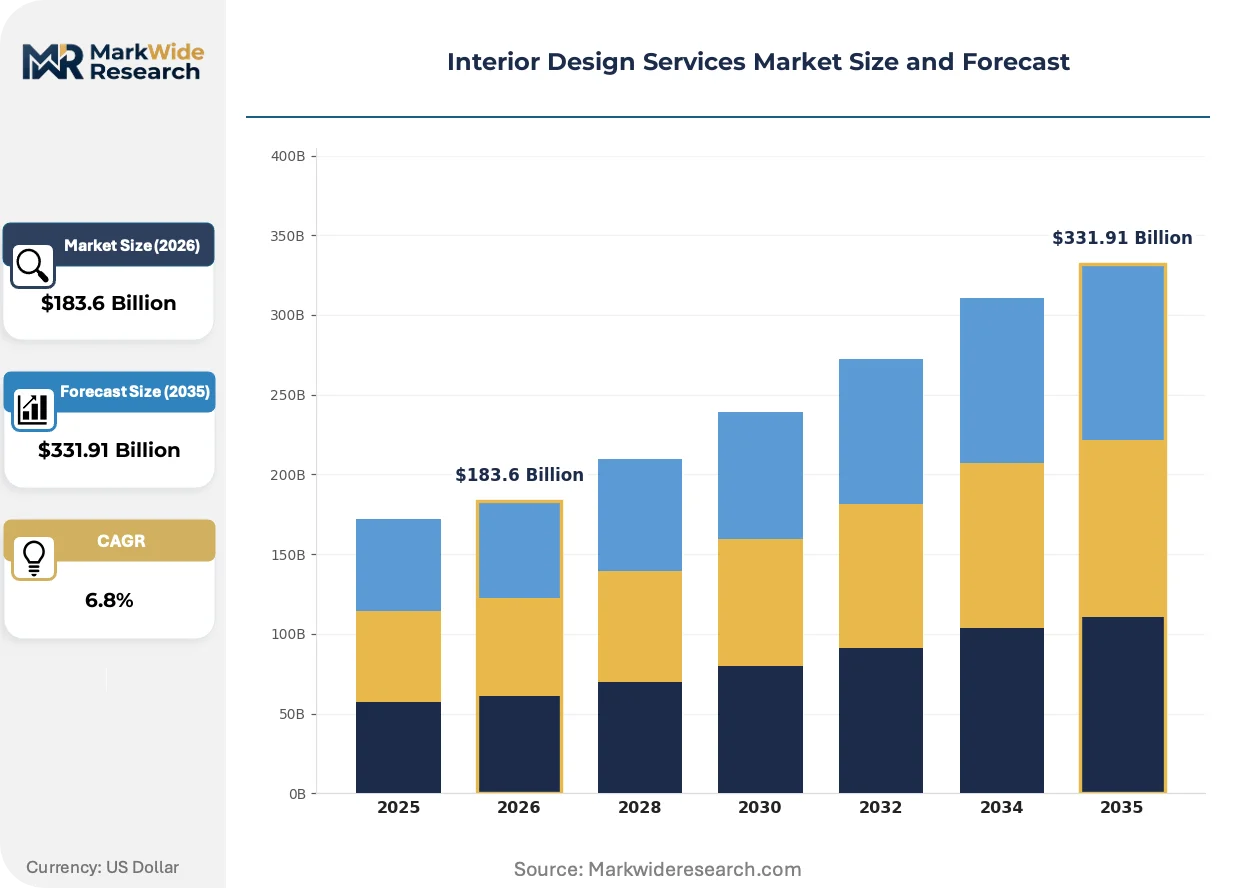
| Market Size in 2026 | $183.6 Billion |
| Market Size in 2035 | $331.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Design, Commercial Design, Landscape Design, Space Planning Customer Type: Homeowners, Corporations, Contractors, Developers Project Size: Small Scale, Medium Scale, Large Scale, Renovation Design Style: Modern, Traditional, Rustic, Minimalist |
| Companies Covered | AECOM, CannonDesign, Gensler, HBA International, SmithGroup, Jacobs, Stantec, Decorilla, Perkins&Will, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interior Design Services Market Strategic Shifts
Computational tools and regulatory transparency mandates are restructuring how design value is created, captured, and delivered across residential and commercial engagements.
Generative artificial intelligence is absorbing routine space planning tasks previously executed by junior designers, compressing entry-level hiring while elevating demand for professionals who can curate and refine algorithmic outputs. Large commercial studios in Chicago and Sydney are deploying these tools for test-fit scenarios, reducing schematic phase timelines. The technology is absorbing labor hours from commodity layout work and reallocating them toward material specification and client-facing conceptual development.
The EU F-Gas Regulation and parallel EPA mandates on hydrofluorocarbon refrigerants are forcing HVAC-integrated design decisions earlier in project timelines. Studios must now coordinate mechanical system specifications with spatial layouts, blurring traditional boundaries between interior design and MEP engineering. Healthcare and laboratory projects in Germany and the Netherlands are most affected, with clients demanding proof of compliance documentation before final fee release.
Subscription-based design access is displacing traditional project-based contracting in the residential segment, particularly among urban millennials in London, Toronto, and Melbourne. Platforms offering ongoing spatial refresh services at flat monthly rates are capturing clients who previously engaged designers for single renovations. This model compresses customer acquisition costs while extending lifetime value through recurring material and furnishing commissions.
Interior Design Services Market Segmentation
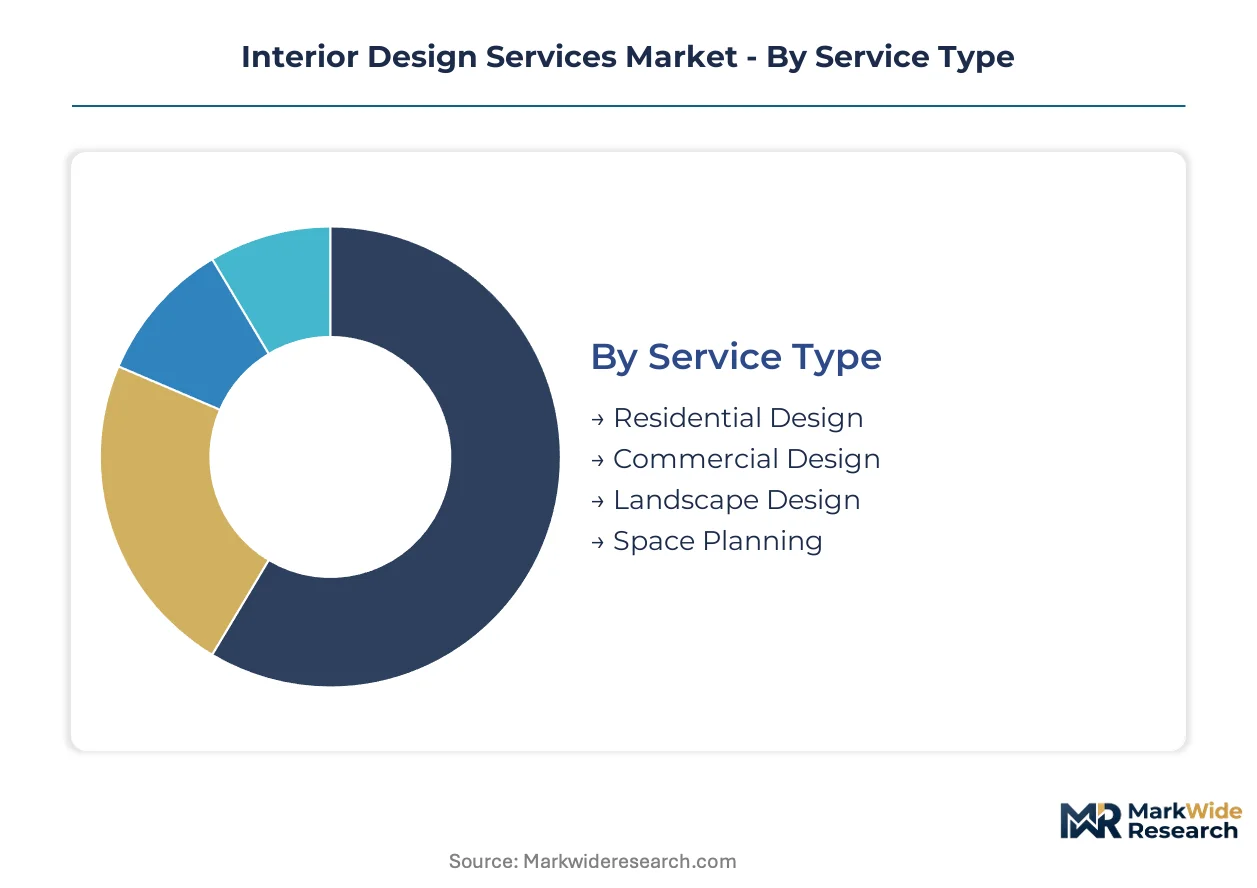
Interior design services fragment across service type, customer profile, project scale, and aesthetic preference, with each dimension carrying distinct certification burdens and margin structures. Understanding these splits reveals where compliance costs concentrate and where digital tools are compressing traditional fee models.
Service Type:
Certification requirements vary sharply across service types, with commercial and healthcare-adjacent work demanding LEED, BREEAM, or WELL credentials that residential projects rarely require.
- Residential Design:Wellness-oriented layouts and smart home integration dominate specification requests. Homeowners in the United States and China are extending project scopes beyond decoration to include automated lighting, air quality systems, and biophilic elements that require coordination with MEP contractors.
- Commercial Design:Hybrid workplace configurations balancing collaboration density with individual focus zones are absorbing the fastest fee growth. Corporations in Germany and the Netherlands demand proof of EU Energy Performance of Buildings Directive compliance before final payment release, elevating documentation costs.
- Landscape Design:Exterior spatial planning with hardscape and planting specifications.
- Space Planning:Layout optimization within structural constraints, particularly essential in renovation pipelines across mature urban markets.
Residential design sits at the top of the volume ranking, with commercial design climbing the fastest.
Customer Type:
Cost tier stratification separates luxury bespoke engagements from standardized packages, with homeowner and developer clients occupying opposite ends of the fee flexibility spectrum.
- Homeowners:Subscription-based access models are displacing traditional project contracting among urban millennials in London, Toronto, and Melbourne. Flat monthly rates for ongoing spatial refresh services extend lifetime value through recurring furnishing commissions while compressing upfront acquisition costs.
- Corporations:Enterprise clients in Chicago and Sydney are deploying generative AI tools for test-fit scenarios, reducing schematic phase timelines and reallocating labor toward material specification. These engagements carry the highest documentation burdens for carbon disclosure and indoor air quality compliance.
- Contractors:Build-firm partnerships requiring rapid turnaround on specification packages.
- Developers:Volume-driven clients prioritizing speed and repeatability across multiple units.
Homeowners generate the highest transaction frequency, with corporations delivering the steepest expansion trajectory in absolute fee value.
Project Size:
Scale determines team composition and technology deployment, with large-scale work demanding building information modeling expertise concentrated in London, New York, and Shanghai.
- Large Scale:Giga-projects in Saudi Arabia including Neom and Red Sea developments are importing international design expertise at premium rates. These engagements require cross-functional teams capable of BIM-LEED coordination that smaller studios cannot assemble.
- Renovation:EU Energy Performance of Buildings Directive mandates across Germany, France, and Italy are accelerating retrofit pipelines. Certified sustainable design expertise commands fee premiums as studios navigate material lifecycle databases and energy efficiency mandates.
- Small Scale:Single-room or limited-scope engagements absorbing digital-first platform competition.
- Medium Scale:Multi-room residential or small commercial fit-outs with moderate documentation requirements.
Renovation work dominates current project pipelines, with large-scale engagements gaining share fastest in the Gulf region.
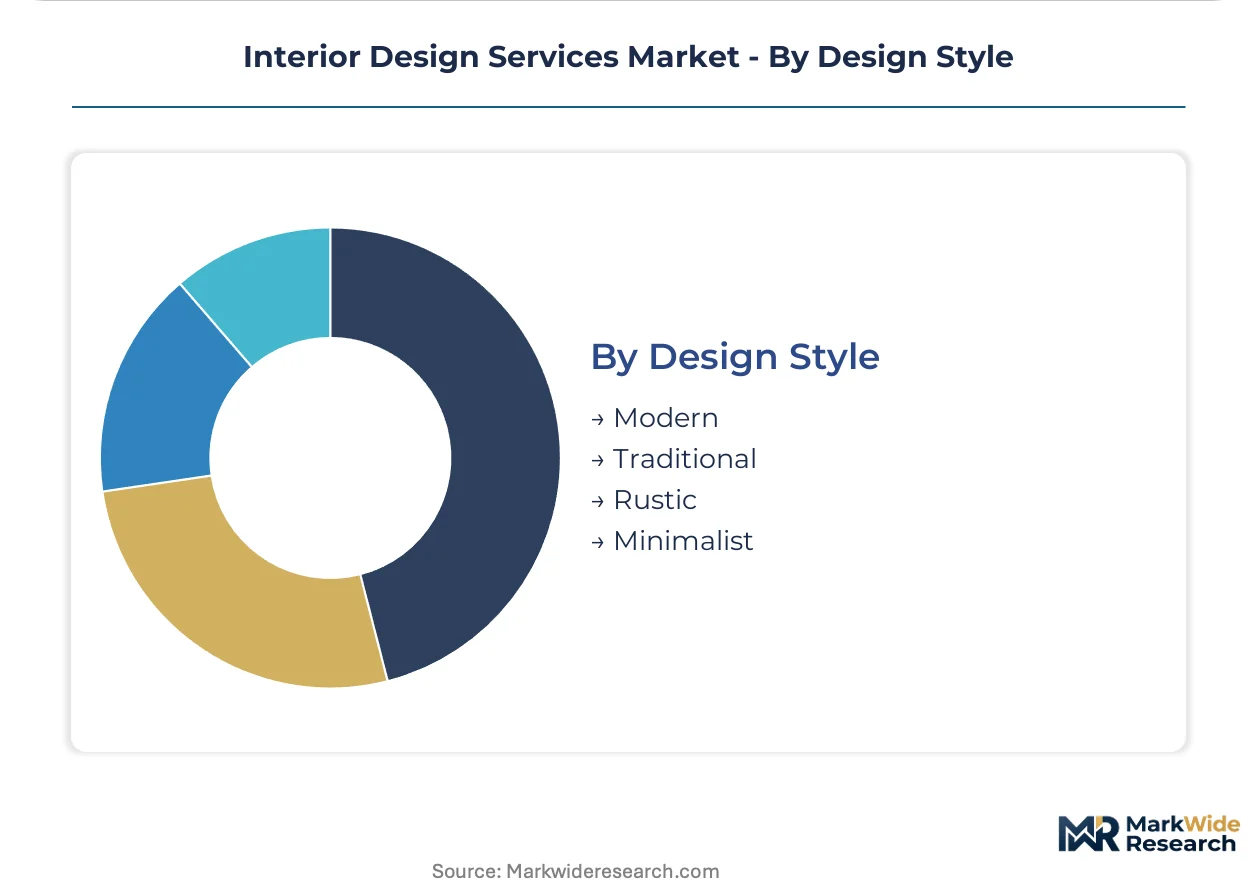
Design Style:
Geographic origin of aesthetic preference influences material sourcing networks and artisan labor access, with traditional and rustic styles demanding specialized supplier relationships.
- Modern:Clean lines and minimal ornamentation align with smart home integration requirements in the United States and China. Specification libraries emphasize manufactured materials with consistent performance data and supply chain transparency.
- Minimalist:Spatial reduction principles requiring precise proportion control and concealed storage solutions. Japanese and Scandinavian influence clusters in Melbourne and Toronto are driving demand for certified sustainable materials with documented carbon footprints.
- Traditional:Historic reference and ornamental detail dependent on craft-specialist networks.
- Rustic:Natural material emphasis with regional sourcing constraints and weathering performance considerations.
Modern style commands the largest specification volume, with minimalist aesthetics expanding most quickly among environmentally certified projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands deeper renovation pipelines than Germany, yet both markets face tightening energy codes that elevate certification costs for design studios.
United States
Wellness-oriented residential layouts and smart home integration drive specification expansion across metropolitan clusters. The EPA enforces indoor air quality standards that constrain material selection timelines. Chicago and New York studios concentrate building information modeling expertise, creating talent access bottlenecks for competitors outside these hubs.
Germany
EU Energy Performance of Buildings Directive mandates accelerate retrofit project pipelines across residential and commercial segments. REACH compliance requirements limit certified material availability, extending procurement cycles. Berlin and Munich design clusters command premium fees for lifecycle assessment capabilities that carbon disclosure rules now require.
China
Urban redevelopment across major metropolitan areas concentrates demand for luxury residential and hospitality interiors. The Ministry of Ecology and Environment enforces dual carbon goals that shape HVAC-integrated design decisions. Shanghai and Shenzhen studios leverage photorealistic rendering capabilities to compress schematic phase timelines for developer clients.
Saudi Arabia
Neom and Red Sea giga-projects import international design expertise at premium rates before local capacity matures. The Saudi Food and Drug Authority and building regulators enforce standards for hospitality and healthcare-adjacent interiors. Riyadh and Jeddah clusters attract cross-functional teams capable of BIM-LEED coordination that smaller regional studios cannot assemble.
United Kingdom
Subscription-based design access models displace traditional project contracting among urban millennials in London. BREEAM certification requirements for commercial interiors elevate documentation burdens. London studios absorb the fastest adoption of generative AI tools for test-fit scenarios, reallocating labor toward material specification and client-facing conceptual development.
Interior Design Services Market Competitive Environment
Top-tier vendors anchor large-scale commercial and institutional projects, while mid-tier studios compete on specialized healthcare or residential expertise. The market structures around three strategic archetypes: global network firms with multi-continent studio footprints, deep specialists in regulated verticals like healthcare and science facilities, and digital-first platforms productizing fixed-fee residential services. Dominant competitive moves include geographic expansion into Gulf region giga-projects and technology licensing for generative design tools.
Among global network firms, Gensler and AECOM exemplify the scale-driven archetype with multi-continent commercial project dominance. CannonDesign occupies a position within the deep specialist tier, anchoring competitive positioning through healthcare and science facility concentration. Decorilla represents the digital-first platform model, extending affordable visualization-driven services to residential homeowners.
| Leading Market Players |
|---|
| AECOM |
| CannonDesign |
| Gensler |
| HBA International |
| SmithGroup |
| Jacobs |
| Stantec |
| Decorilla |
| Perkins&Will |
| Others |
Value Chain & Pricing Dynamics
EU Energy Performance of Buildings Directive mandates for certified material specifications are forcing procurement teams toward vetted supplier networks in Italy and Spain, compressing margins for studios unable to secure preferred vendor status.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for mid-tier fit-out materials, intensifying competition with established German and French suppliers. Three-tier pricing structure across premium certified, standard compliant, and economy unverified levels dominates commercial engagements. Cost compression in the economy tier is intensifying because freelance platform commoditization absorbs residential demand. Developer clients exhibit highest price sensitivity, while hospitality developers in Dubai and Singapore accept premium positioning for immersive design differentiation.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for certified sustainable materials. Italy, China, and Turkey concentrate artisan furnishing production. Procurement draws from FSC-certified timber, low-VOC coatings, and reclaimed stone aggregates. Single-source vulnerability runs through Shanghai-based photorealistic rendering software providers. Distribution runs through design-build contractor networks rather than direct retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification cost differentials between Germany and Poland create geographic-arbitrage opportunities for studios willing to base compliance documentation in lower-cost EU member states while maintaining client-facing presence in premium markets.
For Market Incumbents: Hedge against freelance platform commoditization by acquiring proprietary visualization technology or licensing generative design tools. Build certified sustainability capabilities in-house to prevent ceding premium contracts to specialized competitors. Channel control through exclusive supplier partnerships protects margin position in hospitality and healthcare verticals. For New Entrants and Emerging Players: Enter via Saudi Arabia giga-projects before local capacity matures, securing first-mover positioning at premium rates. Target renovation pipelines across Germany, France, and Italy where EU Energy Performance of Buildings Directive mandates accelerate project flow. Go-to-market through BIM-LEED coordination service bundles that smaller regional studios cannot assemble. For Investors and Strategic Acquirers: Asymmetric upside sits with digital-first platforms productizing fixed-fee residential services through subscription models. Long-term viability hinges on recurring revenue capture extending lifetime value through furnishing commissions. Acquisition target archetype: visualization-technology providers with established homeowner user bases. Signal to watch: carbon disclosure rule enforcement tightening material specification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Tool Licensing | Compresses schematic phase timelines for Chicago and Sydney commercial studios. |
| Certified Sustainability Capability Buildout | Captures EU Energy Performance of Buildings Directive compliance premiums in Germany. |
| Gulf Region Studio Expansion | Secures Neom and Red Sea giga-project positioning before local capacity matures. |
| Subscription Model Productization | Displaces traditional project contracting among urban millennials in London. |
| Lifecycle Assessment Consulting Launch | Opens revenue streams from EU Corporate Sustainability Reporting Directive mandates. |
Study Parameters
Direct dialogue with design studio principals, sustainability certification consultants, hospitality procurement directors, and BIM software engineers grounded qualitative findings. Secondary validation drew from EPA indoor air quality standards documentation, EU Energy Performance of Buildings Directive filings, REACH compliance databases, and SEC disclosures from publicly traded construction services firms. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates.
Segment-level outputs across service type, customer profile, project scale, and design style informed the analytical framework over the projection horizon. Modeled dimensions included certification burden tier, MEP integration complexity, and regional regulatory cluster. CAGRs derived from historical fee growth patterns adjusted for mandate acceleration effects. Forecast inputs incorporated EU F-Gas Regulation enforcement trajectories and generative AI adoption curves in commercial test-fit scenarios.
Inputs from hospitality developers, corporate real estate executives, and material certification bodies were available through the study window; gaps in Saudi Arabia giga-project pipeline visibility introduce uncertainty bands around Gulf region expansion trajectories. Forecasts reflect documented assumptions regarding regulatory enforcement timing and technology diffusion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
Balcony Accessories Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
Hearth Market
Homecare and Decor
Home Decor and Accessories Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
Door Handles Market
Homecare and Decor
Garden Sheds Market