
 Interior Design Market | 2026-2036
Interior Design Market Size, Share, and Industry Trends Forecast 2026-2036
Interior Design Market Analysis
Reclaimed timber and low-carbon concrete is realigning specification economics across high-end commercial fit-outs. Gensler leverages its global studio network to sustain cross-border project delivery for multinational tenants. Perkins&Will anchors its competitive position through deep expertise in LEED-certified building interiors.
Interior design encompasses the planning, specification, and coordination of spatial layouts, surface finishes, lighting systems, and furnishings to optimize human occupancy, comfort, and operational efficiency within built environments. The practice integrates structural constraints with ergonomic parameters, acoustic performance targets, and visual coherence to deliver functional spaces for residential, commercial, and institutional clients. Residential design leads service-type revenue by volume, though commercial design commands larger per-project fees and longer engagement cycles. New construction projects dominate the project-type category in developing markets, while renovation and remodeling activity prevails in mature building stock across North America and Western Europe.
LEED certification requirements from the US Green Building Council, EU Green Deal building performance standards, and China's GB standards for indoor environmental quality are elevating material disclosure and energy modeling obligations across all project scales. The US EPA's formaldehyde emissions regulations for composite wood products further constrain substrate selection for interior applications. Stakeholders must monitor evolving jurisdictional compliance thresholds before committing to multi-year material supply agreements or regional expansion plans.
Market Dynamics
The EU Green Deal's building performance standards are compressing material specification timelines and elevating compliance costs across commercial fit-out projects, forcing design firms to restructure procurement relationships and accelerate sustainability credentialing.
Growth Catalysts
- Hospitality Fit-Out Expansion:Asia-Pacific hotel and resort operators are expanding capital deployment into signature interior experiences, creating sustained demand for specialized design services and custom fabrication.
- LEED Certification Mandates:US Green Building Council requirements are embedding energy modeling and material disclosure into standard project workflows across commercial and institutional segments.
- Reclaimed Material Specification:Low-carbon concrete and reclaimed timber are achieving cost parity with conventional substrates in premium commercial applications, accelerating specification velocity.
Market Restraints
- Formaldehyde Emission Compliance:US EPA regulations for composite wood products constrain substrate selection flexibility and extend material vetting cycles for residential and commercial interiors.
- Supply Concentration Risk:Specialty finish manufacturers cluster in Italy and Germany, creating vulnerability to regional energy cost volatility and logistics disruption.
- Technical Limitation:Acoustic performance targets in open-plan commercial layouts conflict with exposed structural aesthetic preferences, forcing expensive remediation retrofits.
Strategic Opportunities
- China Tier-One City Premium Residential:Luxury tower developments in Shanghai, Beijing, and Shenzhen command design fee multiples above regional averages, attracting international studio expansion.
- EU CSRD Alignment Services:Corporate Sustainability Reporting Directive requirements are creating advisory revenue streams around embodied carbon tracking and circular material documentation.
- Digital-Physical Convergence:Building information modeling integrated with virtual reality visualization is compressing client approval cycles and reducing change-order frequency.
Industry Challenges
- Certified Specialist Scarcity:LEED-accredited professionals and WELL-certified designers remain concentrated in major metropolitan markets, constraining project bandwidth for mid-size firms.
- Legacy System Integration:Established design practices face friction migrating project archives and client relationship databases to cloud-based collaboration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interior Design Market |
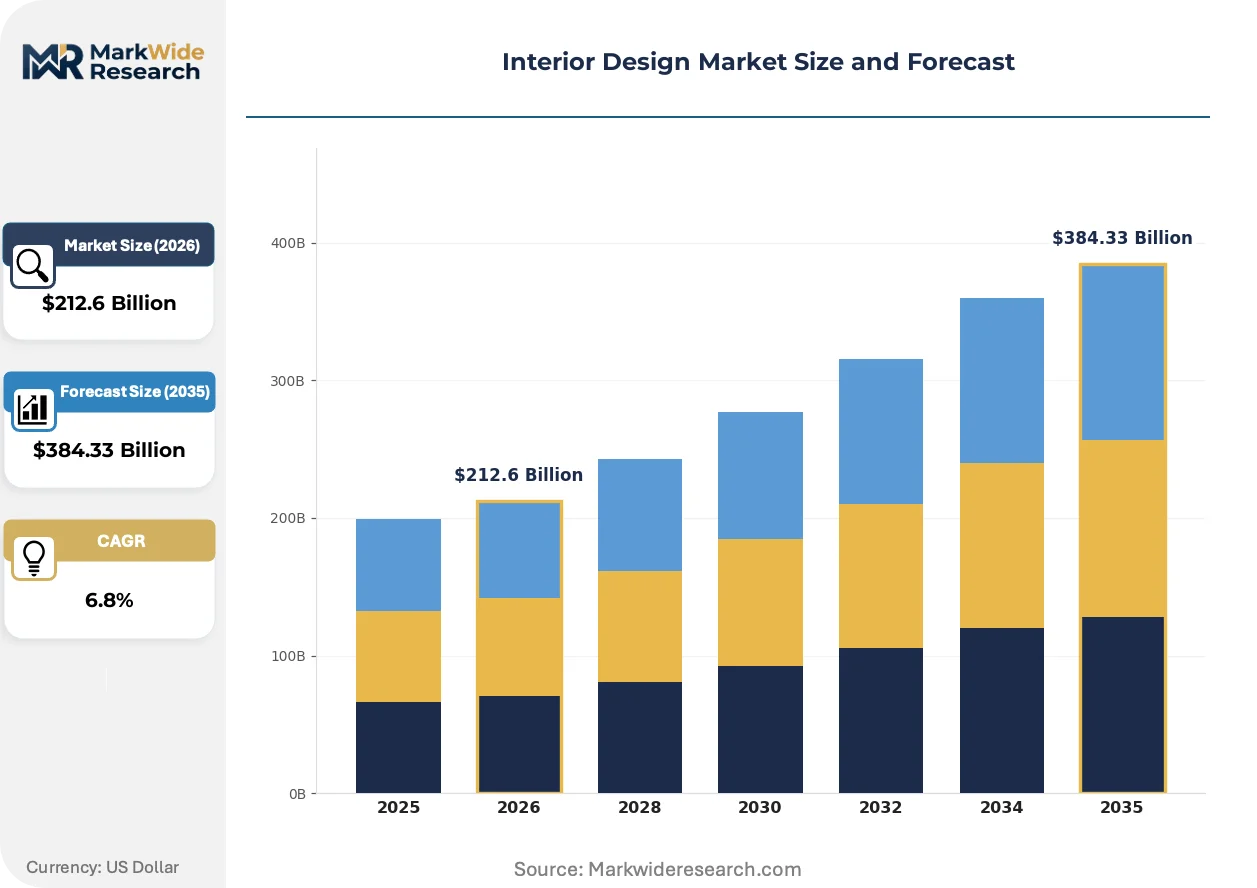
| Market Size in 2026 | $212.6 Billion |
| Market Size in 2035 | $384.33 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Design, Commercial Design, Landscape Design, Interior Styling Project Type: Renovation, New Construction, Remodeling, Retail Space Design Design Style: Modern, Traditional, Minimalist, Rustic End User: Homeowners, Businesses, Contractors, Property Developers |
| Companies Covered | HDR, Rockwell Group, Gensler, Stantec, Interior Architects, Perkins&Will, Skidmore, Owings & Merrill, AECOM, DLR Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interior Design Market Emerging Trajectories
Computational design tools and biomaterial advances are restructuring how spatial concepts move from visualization to fabrication, compressing the traditional handoff between creative direction and construction documentation.
Parametric design software is expanding into hospitality and workplace fit-outs, enabling real-time customization of millwork patterns and lighting geometries based on occupancy sensor data. Large-scale hotel operators in Dubai and Singapore are deploying these platforms to accelerate prototype approval while maintaining brand consistency across properties. The technology is expanding into mid-market segments as subscription pricing models reduce capital barriers for smaller design studios.
REACH chemical restrictions are eliminating legacy flame retardants and volatile organic compounds from surface coating specifications across EU commercial projects. Manufacturers serving this geography are reformulating product lines to maintain CE marking eligibility, shifting competitive advantage toward firms with in-house toxicology assessment capabilities. Healthcare and education interiors face the steepest compliance ramps due to stringent indoor air quality thresholds.
Developer-led design-build procurement is consolidating vendor relationships and compressing traditional architect-designer-contractor hierarchies into integrated delivery teams. Single-source accountability models are displacing competitive bid sequences in UK and Australian commercial developments, rewarding firms with captive fabrication capacity or exclusive material partnerships. This restructuring is most visible in speculative office and multifamily residential projects where speed-to-market determines financing viability.
Interior Design Market Segmentation
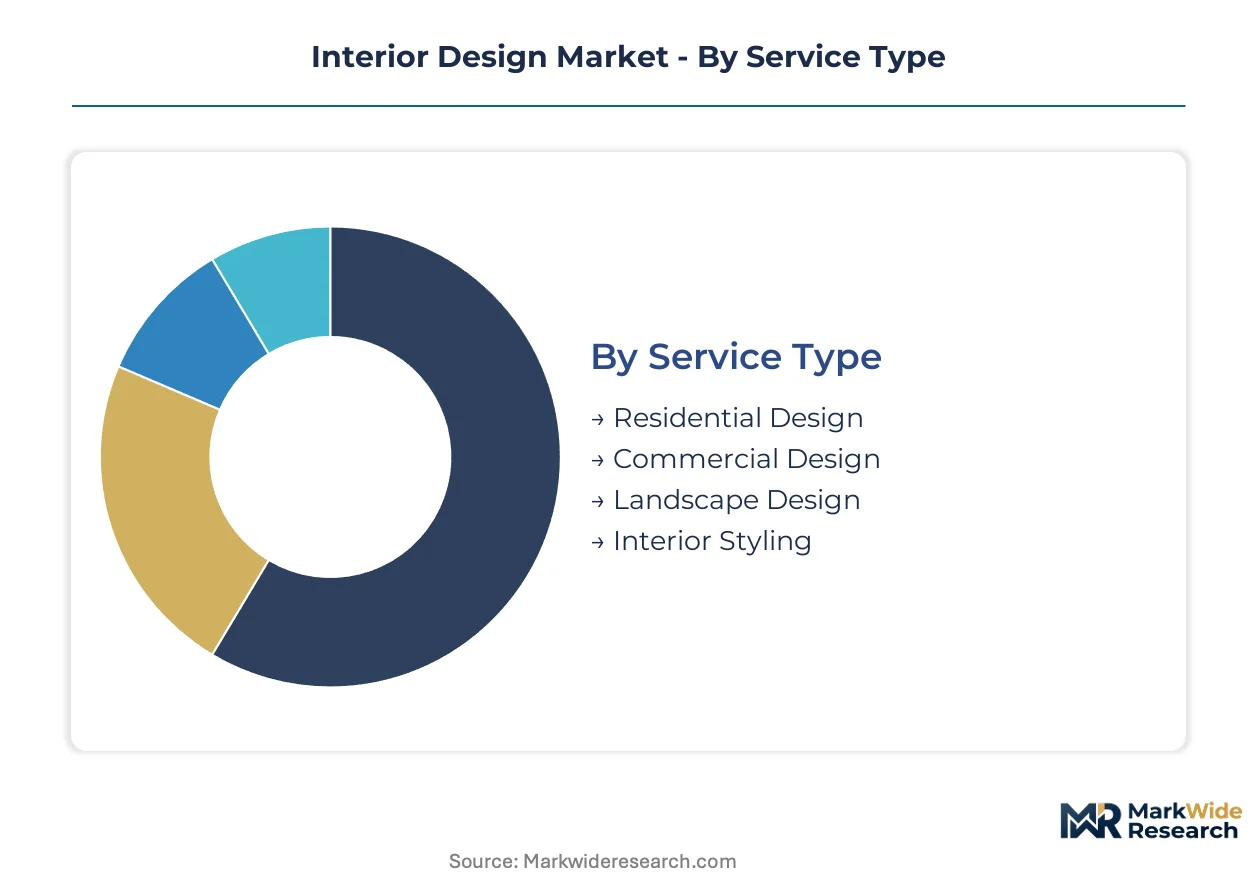
Interior design market segmentation reveals divergent compliance burdens and margin structures across service delivery models. Certification requirements from LEED, WELL, and regional building codes create asymmetric cost pressures that reshape competitive positioning within each category.
Service Type:
LEED certification mandates from the US Green Building Council and EU Green Deal performance standards impose tiered disclosure obligations depending on project scale and occupancy type.
- Residential Design:Single-family and multifamily interiors face EPA formaldehyde emission standards for composite wood substrates. Demand concentrates in China's tier-one cities where luxury towers command premium fees for bespoke spatial planning and imported finish specifications.
- Commercial Design:Workplace, hospitality, and institutional fit-outs carry the heaviest energy modeling and material disclosure burdens under LEED v4.1 and CSRD alignment requirements. Corporate headquarters in Singapore and Dubai drive specification of low-carbon concrete and reclaimed timber systems.
- Landscape Design:Exterior spatial planning integrates with interior visual continuity through hardscape material selection and biophilic transition zones.
- Interior Styling:Furnishing curation and accessory specification operate with lighter regulatory overhead, though EU REACH chemical restrictions constrain textile and surface coating options.
Leading the category by volume: Residential Design. Expanding most quickly: Commercial Design.
Project Type:
Cost tier stratification separates high-margin bespoke engagements from standardized delivery models with compressed fee structures.
- Renovation:Mature building stock across North America and Western Europe drives adaptive reuse projects requiring asbestos abatement coordination and historic preservation compliance. Aging commercial towers in Manhattan and London demand phased occupancy maintenance during system upgrades.
- New Construction:Ground-up developments in developing markets offer integrated design-build procurement with consolidated vendor relationships. Speculative office and multifamily projects in Mumbai and São Paulo reward speed-to-market capabilities.
- Remodeling:Residential kitchen and bath updates carry shorter engagement cycles and lower per-project fees than full renovations.
- Retail Space Design:Brand rollout programs for hospitality and fashion operators require repeatable prototype systems across multiple geographies.
Highest margin concentration: New Construction. Steepest volume trajectory: Renovation.
Design Style:
Application context determines specification economics, with certain aesthetic preferences demanding specialized material sourcing and skilled fabrication.
- Modern:Clean lines and open plans rely on imported European millwork and Italian specialty finishes vulnerable to supply concentration risk. Hospitality operators in Asia-Pacific deploy this vocabulary for signature property differentiation.
- Traditional:Ornamentation and period detailing require artisan fabrication capacity concentrated in heritage manufacturing clusters. Historic hotel renovations in Paris and Vienna sustain demand for conserved craft techniques.
- Minimalist:Reduced material palettes emphasize acoustic performance engineering and concealed storage integration.
- Rustic:Reclaimed timber and natural stone specifications align with low-carbon material mandates in EU commercial projects.
Dominant specification share: Modern. Gaining share fastest: Rustic.
End User:
Customer type dictates procurement sophistication, contract scale, and sustainability credentialing intensity.
- Homeowners:Individual residential clients in China's tier-one cities drive demand for imported luxury finishes and smart home integration. Project scale remains constrained by single-unit economics compared to commercial engagements.
- Businesses:Corporate tenants and hospitality operators command the longest engagement cycles and largest per-project fees. Multinational headquarters in Frankfurt and Sydney require cross-border studio coordination for brand consistency.
- Contractors:Builder-led procurement compresses traditional design hierarchies into integrated delivery teams with single-source accountability.
- Property Developers:Speculative commercial and residential developers prioritize speed-to-market financing viability over bespoke design investment.
Revenue concentration leader: Businesses. Fastest client-base expansion: Homeowners.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities concentrate luxury residential design fees at multiples exceeding regional benchmarks, while EU Green Deal compliance costs reshape procurement economics for commercial fit-outs across member states. The United States maintains institutional demand through LEED mandates, and hospitality capital deployment in the UAE and Singapore drives signature interior experiences.
United States
Corporate headquarters in Manhattan and Chicago sustain demand for WELL-certified workplace interiors with extended engagement cycles. US EPA formaldehyde emission standards for composite wood products constrain substrate selection flexibility across residential and commercial applications. Los Angeles and San Francisco studios lead specification of reclaimed timber systems for technology sector clients.
China
Luxury residential towers in Shanghai, Beijing, and Shenzhen command premium design fees for bespoke spatial planning and imported European finishes. GB standards for indoor environmental quality elevate material disclosure obligations across all project scales. Guangzhou and Chengdu emerging as secondary hubs for mid-market commercial fit-out expansion.
Germany
REACH chemical restrictions eliminate legacy flame retardants from surface coating specifications, forcing manufacturer reformulation for CE marking eligibility. EU Corporate Sustainability Reporting Directive creates advisory revenue streams around embodied carbon tracking for Frankfurt and Munich corporate clients. Specialty finish manufacturers cluster in Stuttgart and Cologne, vulnerable to regional energy cost volatility.
United Arab Emirates
Hospitality operators in Dubai and Abu Dhabi deploy parametric design platforms to accelerate prototype approval for signature hotel properties. MOHAP indoor air quality standards influence healthcare and education interior specifications. Design-build procurement consolidates vendor relationships in speculative commercial developments across the emirates.
Singapore
Multinational headquarters demand cross-border studio coordination for brand consistency across Asia-Pacific portfolios. BCA Green Mark certification requirements embed energy modeling into standard commercial project workflows. Marina Bay and Orchard Road districts concentrate high-end retail and hospitality fit-out activity with compressed speed-to-market timelines.
Interior Design Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service studios capturing premium fees in commercial and institutional categories while regional boutiques dominate residential renovation. The vendor base organizes into three tiers: global networks with cross-border delivery capability, national specialists with LEED or WELL credentialing depth, and local contractors with fabrication partnerships. Consolidation pressures favor M&A activity among mid-size firms seeking geographic expansion, and strategic partnerships with specialty finish manufacturers securing exclusive material access.
Within the global network tier, Gensler and Perkins&Will exemplify archetypes of scale-driven cross-border coordination, while Rockwell Group occupies a position as a branded specialist in hospitality-centric experiential design. HDR and Stantec represent the engineering-integrated model where interior services anchor within multidisciplinary infrastructure practices. These firms sit within competitive dynamics where LEED-accredited professional scarcity in secondary metros constrains project bandwidth, and cloud-based collaboration platform migration creates friction for legacy archive systems.
| Leading Market Players |
|---|
| HDR |
| Rockwell Group |
| Gensler |
| Stantec |
| Interior Architects |
| Perkins&Will |
| Skidmore, Owings & Merrill |
| AECOM |
| DLR Group |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between LEED-accredited studios and unverified regional contractors manifests in fee multiples exceeding three-to-one for equivalent square footage, while simultaneously concentrating specification power among Italian and German specialty finish manufacturers who command premium positioning through exclusive distributor networks.
Pricing Analysis
Volume-driven residential renovations in North American suburbs generate thin margins through standardized material packages, whereas signature hospitality fit-outs in Dubai and Singapore sustain project-based fee structures with customization premiums. Price differentiation rests on WELL or LEED credential tier and the geographic reach of cross-border studio coordination. Cost compression in mid-market commercial segments intensifies as developer-led design-build procurement consolidates vendor relationships. Individual homeowners in China's tier-one cities show lowest price sensitivity for imported European finishes, while speculative multifamily developers in Mumbai and São Paulo prioritize speed-to-market over bespoke design investment.
Supply Chain Analysis
EU Green Deal local-content rules for embodied carbon disclosure are reshaping sourcing toward reclaimed timber suppliers in Scandinavia and low-carbon concrete producers in Germany and France. Raw material dependencies center on Italian specialty finishes, German engineered wood substrates, and Chinese smart home hardware components. Single-source vulnerability concentrates in Stuttgart and Cologne manufacturing clusters exposed to regional energy cost volatility. Distribution runs through exclusive manufacturer-distributor partnerships rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as design firms pursue captive fabrication capacity to secure material access and compress delivery timelines against developer-led procurement consolidation.
For Market Incumbents: Anticipate margin compression from parametric design platform subscriptions eroding traditional visualization fees by securing exclusive partnerships with reclaimed timber suppliers in Scandinavia and low-carbon concrete producers in Germany. Deepen WELL and LEED certification depth to defend against emerging studios leveraging AI-enabled spatial planning tools. Channel control through captive millwork fabrication in tier-one cities anchors pricing power against design-build procurement consolidation. For New Entrants and Emerging Players: EU CSRD in Germany opens a window for advisory services around embodied carbon tracking and circular material documentation for Frankfurt and Munich corporate clients. White-space targets include mid-market residential renovation in Guangzhou and Chengdu where LEED-accredited professional scarcity constrains incumbent bandwidth. Go-to-market through BIM-VR visualization subscriptions reduces capital barriers for smaller studios competing on client approval cycle compression. For Investors and Strategic Acquirers: Re-rating potential sits with WELL-certified boutique studios given hospitality capital deployment acceleration across Asia-Pacific properties. Long-term viability favors firms with backward integration into specialty finish manufacturing or exclusive material partnerships insulating against supply concentration risk. Monitor parametric design platform adoption rates in Dubai and Singapore as inflection indicator for technology-enabled margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Material Partnership | Secures priority access to Italian specialty finishes amid supply concentration in Stuttgart and Cologne clusters. |
| LEED Certification Investment | Unlocks corporate headquarters engagements in Manhattan and Chicago with extended fee cycles. |
| Captive Fabrication Capacity | Enables single-source accountability models displacing competitive bid sequences in UK developments. |
| BIM-VR Platform Integration | Compresses client approval cycles and reduces change-order frequency for hospitality operators in Singapore. |
| Cross-Border Studio Expansion | Sustains brand consistency for multinational tenants requiring coordination across Asia-Pacific portfolios. |
Methodological Framework
Independent corroboration across primary interviews with design firm principals, hospitality procurement directors, and specialty finish manufacturer executives, combined with secondary validation through USGBC LEED project databases, EU CSRD disclosure filings, and BCA Green Mark certification records, underwrites the qualitative findings. Bottom-up triangulation across service-type segmentation and top-down validation against construction expenditure flows anchored the market sizing.
Comparable-period anchoring to historical fit-out expenditure patterns across the projection horizon informed the analytical framework. Segmentation dimensions modeled include service type, project type, design style, and end-user procurement sophistication. CAGRs were derived from regression analysis against hospitality capital deployment trends and residential tower completions. Forecast inputs incorporated EU Green Deal compliance cost trajectories and parametric design platform adoption curves.
The model assumes a particular technology adoption path; alternative pathways for AI-enabled spatial planning would alter the outlook for traditional visualization fee structures. Forecasts reflect assumptions around LEED mandate expansion and REACH chemical restriction enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
Stained Glass Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
India Wall Decor Market