
 Global Hip Implant Market | 2026-2036
Global Hip Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hip Implant Market Analysis
Switzerland is reconfiguring European hip implant supply chains through Medacta International's precision manufacturing campus near Lugano. Stryker Corporation leverages its robotic-arm assisted surgery platforms to sustain premium positioning across North American hospital networks. Zimmer Biomet Holdings anchors reconstructive portfolios through ceramic-on-ceramic bearing systems that dominate academic medical center procurement.
A hip implant constitutes a prosthetic replacement device comprising femoral stems, acetabular cups, and bearing surfaces engineered from cobalt-chromium alloys, titanium porous structures, or alumina ceramic with tolerances below 50 micrometers to restore biomechanical function in degenerated hip joints. Cementless fixation with porous titanium plasma spray coatings leads volume share as osseointegration protocols improve primary stability outcomes. Ceramic bearing segments command margin concentration due to reduced wear debris profiles and extended survivorship in younger patient cohorts.
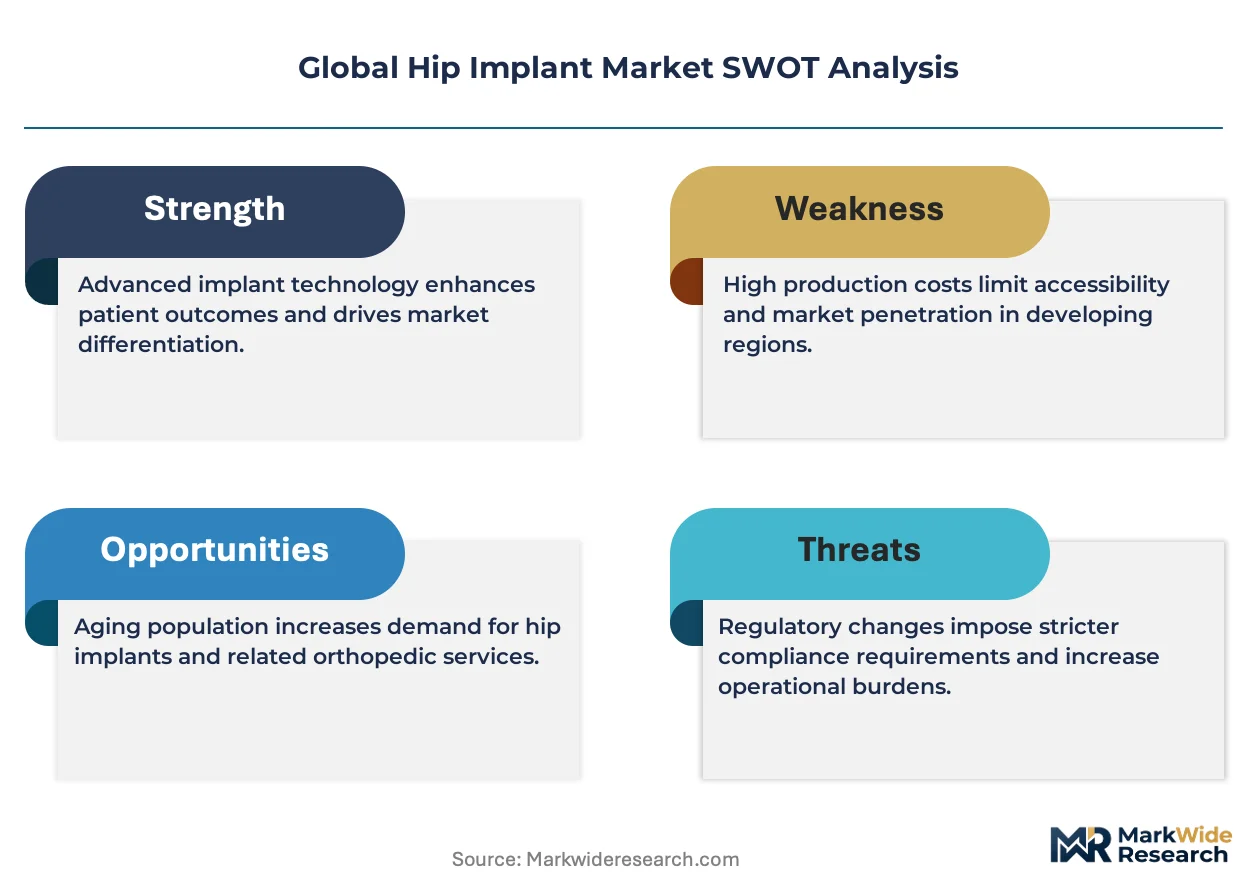
FDA premarket notification pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence thresholds for market authorization. Japan's PMDA and Australia's TGA impose additional biocompatibility testing protocols that filter entrants without dedicated regulatory affairs infrastructure. Stakeholders must monitor reimbursement compression signals from CMS and parallel health technology assessment bodies as value-based procurement frameworks expand.
Market Dynamics
The hip implant market is reconfiguring around EU MDR clinical evidence requirements that extend product development timelines by 18-24 months while simultaneously compressing procurement budgets across OECD hospital systems. This regulatory-cost squeeze is forcing manufacturers to consolidate manufacturing footprints and prioritize ceramic-bearing platforms with demonstrable long-term survivorship data.
Growth Catalysts
- Japan's PMDA streamlined approval pathways:The regulator's Sakigake designation accelerates market access for ceramic-on-ceramic bearing systems, pulling manufacturers toward Tokyo's orthopedic research corridors.
- Robotic surgical platforms:Computer-navigated implant positioning is expanding addressable patient populations to younger, active cohorts previously deferred to conservative management.
- Titanium porous plasma spray:Osseointegration surface engineering is displacing cemented fixation in primary arthroplasty across Australian and Swiss academic medical centers.
Market Restraints
- Cobalt-chromium alloy supply concentration:Three specialty foundries in Germany and the United States control high-purity vacuum-melted feedstock, creating input vulnerability.
- EU MDR technical documentation burdens:Clinical evaluation report requirements for legacy implants force portfolio rationalization decisions before certificate expiration deadlines.
- Metal-on-metal bearing retreat:Adverse local tissue reaction surveillance data has eliminated this construct from surgeon preference cards, constraining material options for high-demand patients.
Strategic Opportunities
- Brazil's ANVISA harmonization:Alignment with IMDRF standards reduces redundant testing for manufacturers with existing FDA or CE dossiers, opening South American access.
- Same-day discharge protocols:Minimally invasive surgical approaches paired with enhanced recovery after surgery pathways enable ambulatory surgical center channel expansion.
- Additive manufacturing convergence with patient-specific instrumentation:CT-derived implant geometries matched to 3D-printed cutting guides compress operative time and revision risk profiles.
Industry Challenges
- Biomaterials toxicology expertise scarcity:Wear debris characterization and lymphocyte transformation testing require specialized analytical chemistry capabilities concentrated in Basel and Minneapolis research clusters.
- Legacy enterprise resource planning integration:EU MDR unique device identifier mandates force serialization system overhauls across multi-site manufacturing networks with decades-old quality management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hip Implant Market |
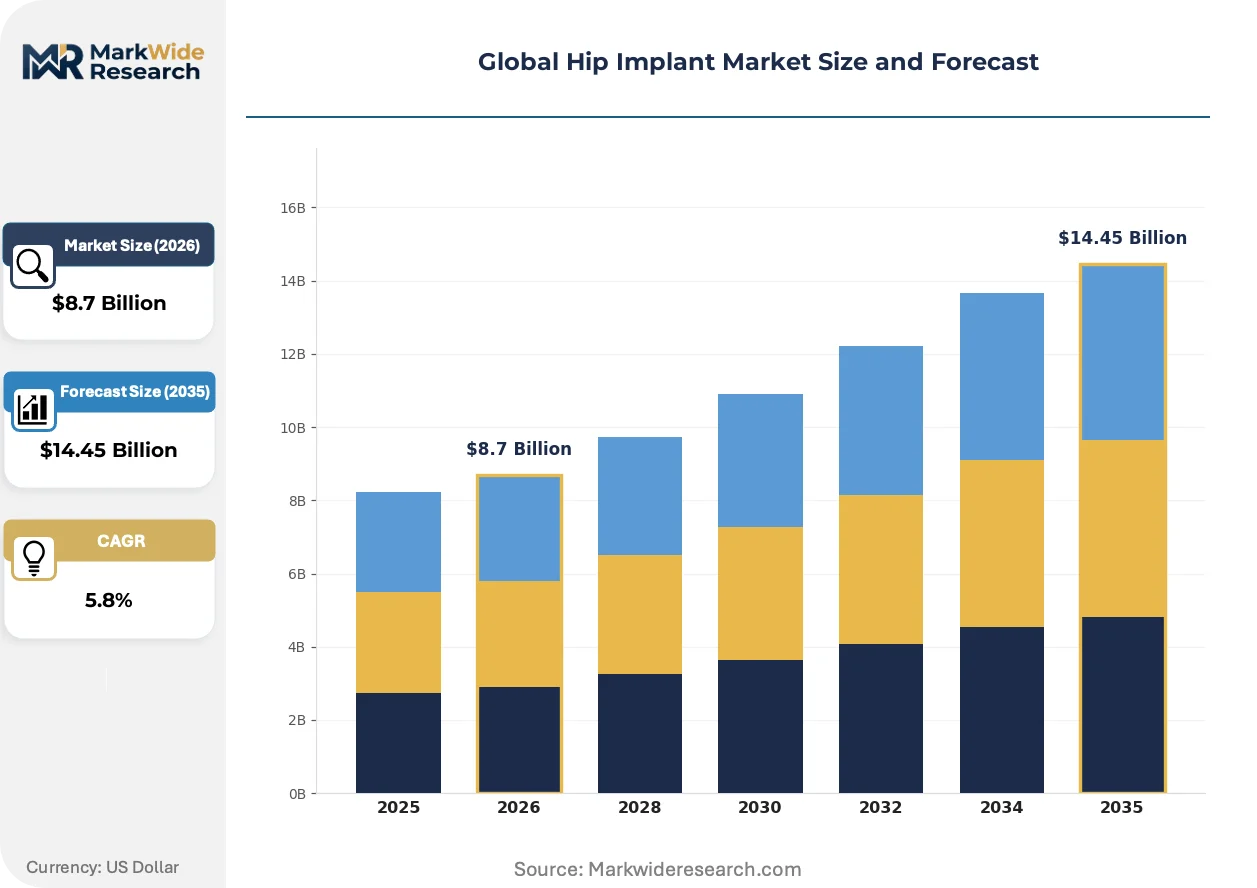
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cemented, Cementless, Hybrid, Resurfacing Material: Metal, Ceramic, Plastic, Composites End User: Hospitals, Clinics, Rehabilitation Centers, Orthopedic Practices Sales Channel: Direct Sales, Distributors, Online Retail, Medical Device Companies |
| Companies Covered | Zimmer Biomet Holdings, Stryker Corporation, DePuy Synthes, Smith & Nephew, Johnson & Johnson, Exactech, B. Braun Melsungen, MicroPort Scientific Corporation, Medacta International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hip Implant Market Emerging Trajectories
Digital thread technologies are penetrating hip implant development workflows, compressing design-validation-manufacturing cycles while simultaneously enabling mass customization. These converging capabilities are redrawing competitive boundaries between established orthopedic conglomerates and precision manufacturing specialists.
Artificial intelligence-driven preoperative planning software is digitizing templating accuracy across academic medical centers in the United States and Germany. Orthopedic surgeons at Mayo Clinic and Charité Berlin are adopting cloud-based implant sizing algorithms that reduce operative time and inventory waste. The technology is digitizing traditional sales representative involvement in case preparation, shifting value capture toward software licensing models.
EU MDR Article 10 clinical evidence requirements are extending post-market surveillance obligations to legacy devices with decades of implantation history. Manufacturers must now commission systematic literature reviews and registry analyses for products previously grandfathered under the Medical Devices Directive. High-volume hip stem portfolios face portfolio triage decisions as notified body audit backlogs stretch certificate renewal timelines.
Hospital procurement consortia in the Netherlands and Sweden are consolidating orthopedic implant purchasing through framework agreements that bundle primary and revision components. Traditional distributor networks face disintermediation as direct manufacturer-contracting models capture volume commitments through multi-year sole-source arrangements. The shift is most visible in Stockholm's Karolinska University Hospital procurement reforms and the Dutch Zorginstituut Nederland health technology assessment integration.
Global Hip Implant Market Segmentation
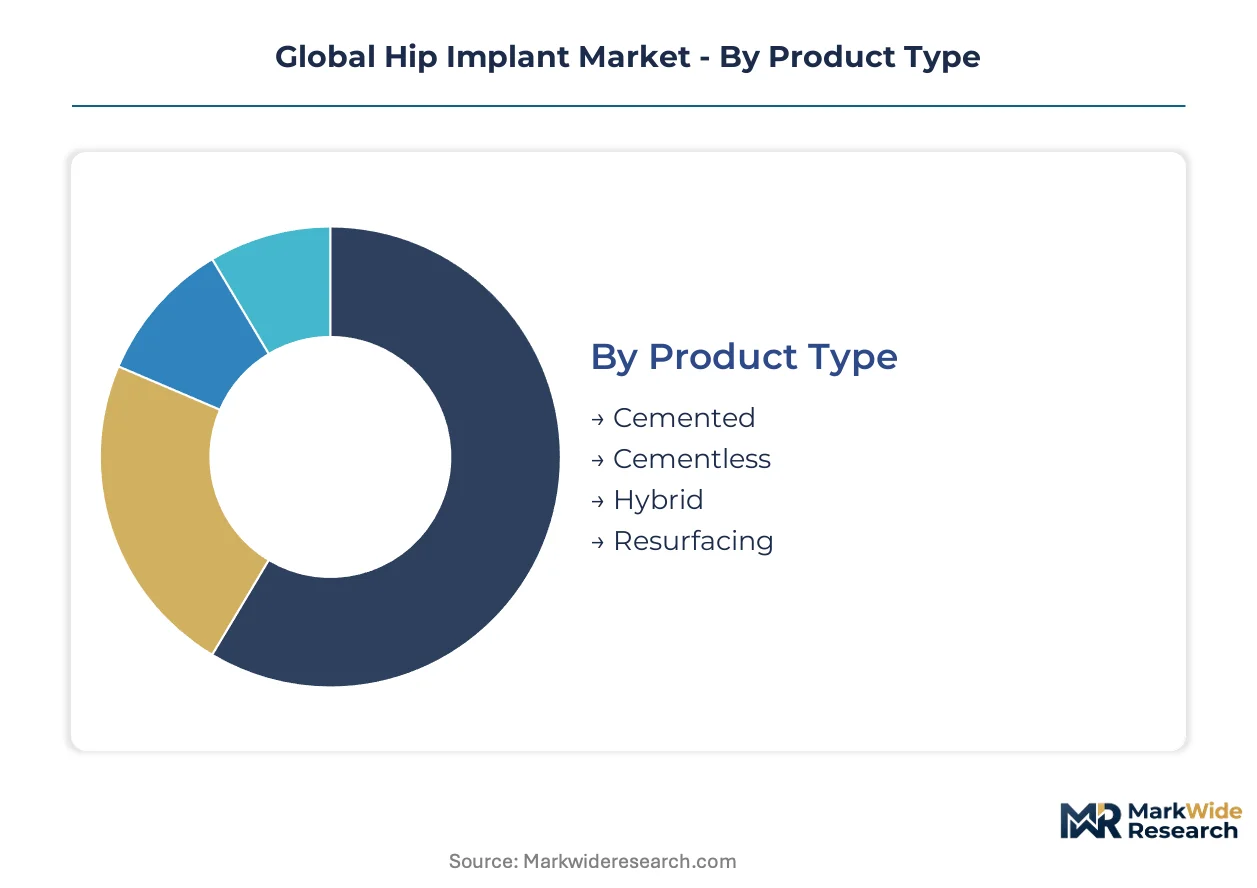
Hip implant procurement patterns diverge sharply across fixation philosophies, bearing materials, and care delivery settings. Each segmentation axis captures distinct margin structures, regulatory pathways, and competitive dynamics that reshape manufacturer resource allocation.
Product Type:
Fixation methodology determines surgical workflow, revision risk profiles, and reimbursement coding complexity across primary arthroplasty cases.
- Cementless:Porous titanium plasma spray coatings enable biological osseointegration without polymethyl methacrylate bone cement. Swiss and Australian academic medical centers prioritize this construct for younger, active patients seeking long-term implant survivorship.
- Cemented:Polymethyl methacrylate fixation delivers immediate mechanical stability in osteoporotic bone or elderly patients with compromised trabecular architecture. Demand concentrates in Japanese and German geriatric surgical corridors where rapid mobilization protocols dominate.
- Hybrid:Combines cemented femoral stem with cementless acetabular cup, optimizing fixation strategy per anatomical site. Orthopedic practices in the United Kingdom and Canada favor this approach for intermediate-risk patient profiles.
- Resurfacing:Bone-conserving femoral head replacement preserves native femoral neck and diaphysis. Niche adoption persists in select United States and United Kingdom centers for male patients under 60 with adequate bone stock.
Cementless fixation commands the established base. The steepest expansion runs through hybrid constructs as surgeons seek customizable fixation strategies.
Material:
Bearing surface selection directly impacts wear debris generation, biocompatibility testing requirements, and long-term revision rates.
- Ceramic:Alumina or zirconia-toughened alumina articulating surfaces produce minimal particulate debris and demonstrate superior scratch resistance. Japan's PMDA Sakigake designation accelerates approval for ceramic-on-ceramic systems, concentrating demand in Tokyo's orthopedic research corridors.
- Metal:Cobalt-chromium alloys dominate femoral stem substrates and acetabular shells due to fatigue strength and machinability. Supply vulnerability from German and United States specialty foundries constrains pricing flexibility.
- Plastic:Ultra-high molecular weight polyethylene liners provide cost-effective articulation in standard primary arthroplasty. Cross-linked variants dominate procurement in price-sensitive Brazilian and Indian hospital systems.
- Composites:Carbon fiber-reinforced polymers and bioactive glass hybrids enable patient-specific modulus matching. Experimental adoption at Mayo Clinic and Charité Berlin supports research protocols rather than commercial volume.
Metal substrates anchor current revenue. Ceramic bearings gain share fastest as long-term registry data validates survivorship advantages.
End User:
Care setting determines case complexity, reimbursement rates, and vendor relationship intensity.
- Hospitals:Academic medical centers and community hospitals perform high-volume primary and revision arthroplasty with comprehensive implant inventories. Procurement consortia in the Netherlands and Sweden consolidate purchasing through multi-year framework agreements.
- Clinics:Ambulatory surgical centers adopt minimally invasive approaches and same-day discharge protocols. United States Medicare reimbursement shifts accelerate channel migration toward freestanding facilities.
- Rehabilitation Centers:Post-acute facilities manage extended recovery protocols and complication surveillance. German and Swiss integrated care networks embed these centers in episode-based payment models.
- Orthopedic Practices:Private group practices maintain implant preference relationships and direct patient referral control. Direct manufacturer contracting in Brazil's São Paulo corridor bypasses traditional distributor networks.
Hospital systems retain volume concentration. Clinic-based delivery expands most quickly as enhanced recovery protocols mature.
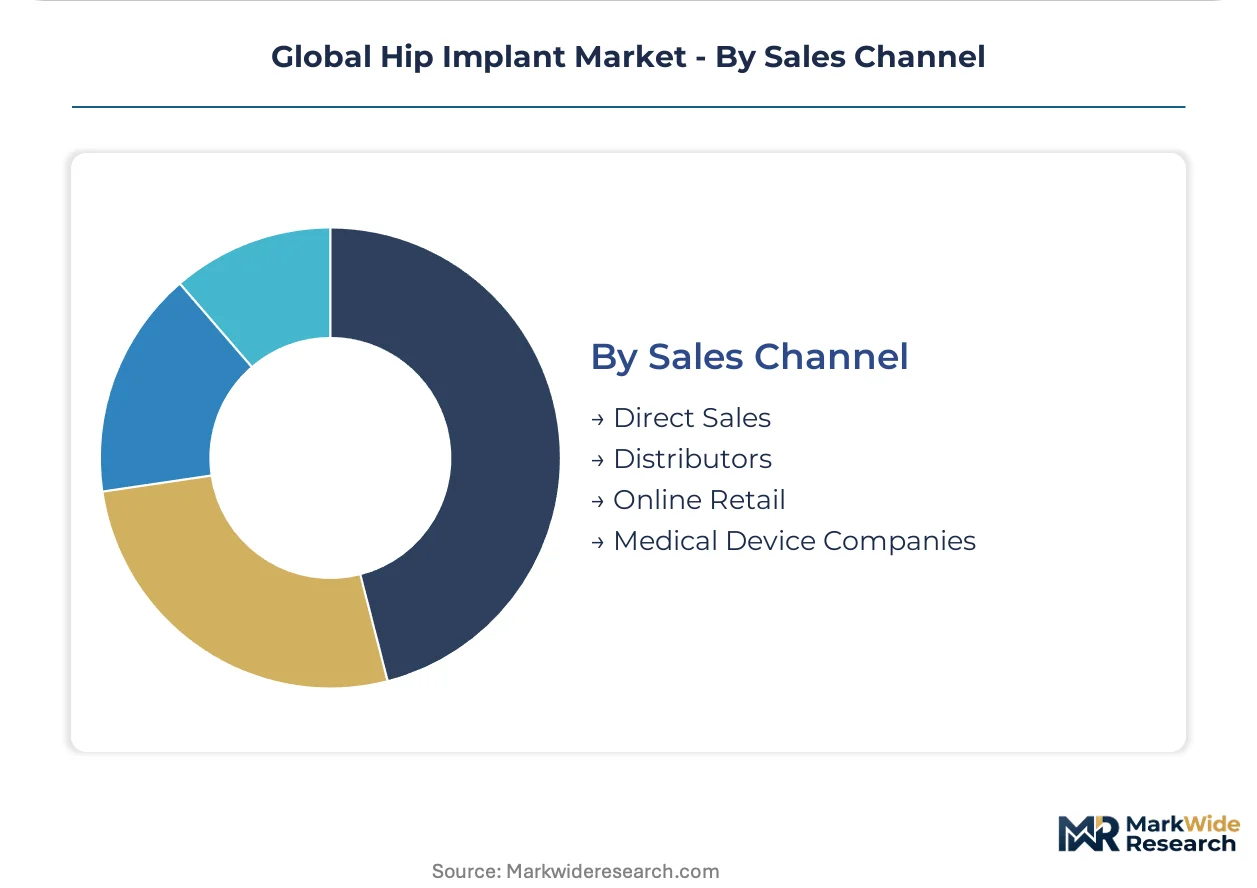
Sales Channel:
Route-to-market structure shapes working capital requirements, technical support obligations, and margin capture.
- Direct Sales:Manufacturer-employed representatives provide case coverage, inventory management, and surgeon training. Stryker and Zimmer Biomet deploy this model across United States hospital networks.
- Distributors:Independent medical device distributors aggregate multiple manufacturer portfolios and provide local logistics. Brazilian and Mexican markets rely on this channel for regulatory navigation and credit extension.
- Online Retail:Digital procurement platforms enable small clinic and international purchaser access to standardized components. ANVISA-harmonized Brazilian registrations facilitate cross-border e-commerce.
- Medical Device Companies:Integrated orthopedic conglomerates bundle hip implants with robotic platforms and patient-specific instrumentation. Tokyo and Minneapolis research clusters concentrate this vertical integration.
Direct sales forces defend the incumbent position. Digital channels climb fastest as procurement digitization penetrates mid-tier facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty foundries in Germany and the United States control high-purity cobalt-chromium vacuum-melted feedstock, concentrating critical upstream inputs for femoral stem substrates. Regulatory divergence across major jurisdictions forces manufacturers to maintain parallel compliance infrastructures. Demand clusters in aging surgical corridors where orthopedic volumes outpace replacement rates.
United States
Medicare reimbursement shifts accelerate ambulatory surgical center migration for same-day discharge protocols. FDA premarket notification pathways shape product development timelines and clinical evidence thresholds for 510(k) clearances. Minneapolis anchors titanium porous plasma spray research clusters serving academic medical center procurement networks.
Germany
Geriatric surgical corridors prioritize cemented fixation with polymethyl methacrylate for rapid mobilization in osteoporotic bone. EU MDR technical documentation requirements extend post-market surveillance obligations to legacy devices with decades of implantation history. Basel and Charité Berlin concentrate biomaterials toxicology expertise for wear debris characterization.
Japan
PMDA Sakigake designation accelerates market access for ceramic-on-ceramic bearing systems in younger patient cohorts. Japan's national health insurance reimbursement rates compress procurement budgets while maintaining quality standards. Tokyo's orthopedic research corridors pull manufacturers toward precision manufacturing partnerships.
Switzerland
Academic medical centers prioritize cementless fixation with porous titanium coatings for long-term implant survivorship. Swissmedic conformity assessment procedures align with EU MDR requirements while maintaining distinct notification pathways. Lugano hosts Medacta International's precision manufacturing campus reconfiguring European supply chains.
Australia
TGA biocompatibility testing protocols filter entrants without dedicated regulatory affairs infrastructure. Osseointegration surface engineering displaces cemented fixation in primary arthroplasty across academic medical centers. Integrated care networks embed rehabilitation centers in episode-based payment models for extended recovery protocols.
Global Hip Implant Market Vendor Landscape
Integrated orthopedic conglomerates and precision manufacturing specialists split the market between scale-driven portfolio breadth and niche technical excellence. The vendor base concentrates around robotic surgical platforms and ceramic-bearing platforms with demonstrable long-term survivorship data. Three strategic archetypes dominate: diversified medical technology conglomerates, mid-cap orthopedic specialists, and emerging additive manufacturing innovators. Consolidation through M&A activity and strategic partnerships for patient-specific instrumentation capabilities represent the dominant competitive moves reshaping positioning.
Among diversified medical technology conglomerates, Zimmer Biomet Holdings and Stryker Corporation exemplify scale-driven archetypes with integrated robotic platform offerings. DePuy Synthes occupies a position within the Johnson & Johnson medical device portfolio representing consolidated orthopedic capabilities. Mid-cap specialists including Medacta International and Exactech sit within the precision manufacturing tier, while Smith & Nephew anchors European reconstructive portfolios. Emerging competitive dynamics center on additive manufacturing convergence with patient-specific instrumentation, where MicroPort Scientific Corporation represents Chinese manufacturing scale.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings |
| Stryker Corporation |
| DePuy Synthes |
| Smith & Nephew |
| Johnson & Johnson |
| Exactech |
| B. Braun Melsungen |
| MicroPort Scientific Corporation |
| Medacta International |
| Others |
Supply Flow & Price Mechanics
German and United States specialty foundries controlling high-purity cobalt-chromium vacuum-melted feedstock concentrate upstream margin capture in femoral stem substrates, while downstream pricing power fragments across hospital procurement consortia and ambulatory surgical centers negotiating ceramic-bearing premiums.
Pricing Analysis
EU MDR dictates the pricing tier structure across the Global Hip Implant Market, separating CE-marked ceramic-on-ceramic systems with enhanced clinical evidence from standard polyethylene-bearing configurations and economy-tier cemented constructs. Price differentiation hinges on biocompatibility certification grade and volume scale through multi-year hospital framework agreements. Cost compression in standard primary arthroplasty components is intensifying because procurement consortia in the Netherlands and Sweden consolidate purchasing power. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement compression, while academic medical centers prioritize long-term survivorship data over unit cost.
Supply Chain Analysis
Extended payment terms from hospital procurement consortia are forcing supply-chain finance facilities upon mid-tier distributors serving Brazilian and Mexican markets. Manufacturing concentrates in Switzerland, Germany, and the United States for precision-machined femoral stems and acetabular shells. Raw material dependencies center on cobalt-chromium alloys, titanium porous plasma spray feedstock, and alumina ceramic blanks. Single-source vulnerability from three German and United States specialty foundries creates input concentration risk. Distribution runs through direct sales forces for United States academic medical centers and independent distributors for Latin American regulatory navigation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across the Global Hip Implant Market as ambulatory surgical center migration and patient-specific instrumentation demand create niches between scale conglomerates and precision specialists.
For Market Incumbents: Build regulatory data moats through EU MDR clinical evaluation report investments for legacy implant portfolios facing certificate renewal deadlines. Consolidate manufacturing footprints to offset 18-24 month development timeline extensions. Prioritize robotic-arm assisted surgery platform integration to defend against additive manufacturing entrants threatening revision component margins. For New Entrants and Emerging Players: Build out patient-specific instrumentation capabilities using CT-derived geometries and 3D-printed cutting guides for ambulatory surgical center channels. Brazil's ANVISA harmonization with IMDRF standards offers the most penetrable regulatory entry point for manufacturers with existing FDA dossiers. Pursue direct manufacturer contracting models in São Paulo's private orthopedic practice corridor to bypass entrenched distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward precision manufacturing specialists with ceramic-bearing platform expertise and additive manufacturing convergence capabilities. Long-term viability favors vendors capturing software licensing value from AI-driven preoperative planning algorithms displacing traditional sales representative involvement. Monitor FDA premarket notification pathway backlog clearance as inflection indicator for new entrant market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Notified body audit backlogs force portfolio triage decisions before certificate expiration deadlines. |
| Robotic Surgical Platform Integration | Computer-navigated positioning expands addressable populations to younger, active patient cohorts. |
| Additive Manufacturing Convergence | CT-derived implant geometries matched to 3D-printed cutting guides compress operative time. |
| Ambulatory Surgical Center Channel Expansion | Same-day discharge protocols enable Medicare reimbursement capture outside hospital networks. |
| Patient-Specific Instrumentation Development | Cloud-based sizing algorithms digitize traditional sales representative case preparation involvement. |
Methodological Framework
A standing panel of orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and national joint registry survival analyses. Bottom-up demand modeling triangulated against top-down manufacturer revenue aggregation.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling fixation methodology, bearing material composition, care delivery setting, and regional regulatory cluster as segmentation dimensions. CAGRs were derived from surgical volume forecasts weighted by implant mix shifts and reimbursement trajectory analysis. Forecast inputs incorporated aging demographic projections, robotic platform adoption curves, and ceramic-bearing registry survivorship data.
Practitioners should monitor EU MDR notified body capacity constraints, cobalt-chromium feedstock pricing volatility, and ambulatory surgical center reimbursement policy shifts for early signals. Forecasts reflect assumptions regarding regulatory pathway efficiency and procurement consolidation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Patellar Implant Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
India Diabetes Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Heated Humidifiers Market
Medical Devices
Global Capnography Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Air Oxygen Blender Market
Medical Devices
Global Breast Implants Market
Medical Devices
Continuous Passive Motion Devices Market