
 Australia System Integration Market | 2026-2036
Australia System Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Australia System Integration Market Insights
Enterprise-grade security certification is reorganizing competitive dynamics across the Australia System Integration Market. Accenture Australia leverages its global cybersecurity frameworks to anchor premium consulting engagements with ASX-listed enterprises. Telstra Purple competes through deep telecommunications infrastructure integration, while DXC Technology Australia sustains dominance in legacy modernization contracts for federal agencies.
System integration encompasses the architectural design, middleware deployment, and protocol harmonization required to unify disparate hardware, software, and data environments into coherent operational workflows, typically involving API orchestration, ETL pipelines, and real-time event streaming at sub-100-millisecond latency thresholds. Its primary purpose is eliminating data silos and enabling automated decision loops across multi-vendor technology estates. Implementation services command the largest revenue pool within the Service Type dimension, though Cloud Computing under Technology is accelerating fastest as hyperscale migration mandates intensify. Manufacturing under End User retains the deepest installed base of operational technology integration, while Enterprise Application within Integration Level captures the highest margin per engagement due to complexity premiums.
TGA cybersecurity guidelines for connected medical devices, APRA CPS 234 requirements for financial services data protection, and the Australian government's Essential Eight maturity model collectively elevate compliance burden and vendor qualification standards. These frameworks compel system integrators to embed security-by-design methodologies from project inception rather than retrofitting controls post-deployment. Stakeholders must monitor how forthcoming amendments to the Security of Critical Infrastructure Act expand sector coverage and mandate minimum integration standards for supply chain visibility.
Market Dynamics
Australia's Critical Infrastructure Protection Act mandates security-by-design integration standards that vendors must embed from project inception, elevating compliance costs and disqualifying uncertified system integrators from federal and state procurement pipelines.
Growth Catalysts
- Essential Eight Maturity Model:Federal agencies now require baseline cybersecurity posture verification before awarding integration contracts, expanding demand for certified implementation partners across Canberra and Sydney.
- Hyperscale Cloud Migration:ASX-listed enterprises accelerate unified operational technology platform deployments, driving API orchestration and real-time event streaming engagements.
- Mining Sector Modernization:Western Australia and Queensland resource operators consolidate disparate SCADA, ERP, and IoT estates into coherent middleware architectures.
Market Restraints
- Specialized Talent Scarcity:Shortage of engineers certified in both OT/IT convergence and APRA CPS 234 compliance extends project timelines and inflates labor rates.
- Supply Concentration Risk:Dominance of three hyperscale cloud providers in Australia creates vendor lock-in exposure and limits negotiation leverage for mid-market integrators.
- Legacy Technical Debt:Federal agencies maintain decades-old COBOL and mainframe estates that resist standard API protocols, forcing costly custom middleware development.
Strategic Opportunities
- Tasmanian Data Center Expansion:Cool climate and renewable energy access attract hyperscale facility investments, creating demand for local integration expertise in Hobart and Launceston.
- Healthcare IoT Convergence:TGA cybersecurity guidelines for connected medical devices open specialized integration verticals combining edge computing with clinical workflow automation.
- Outcome-Based Contracting:State governments pilot performance-guaranteed engagement models that reward integrators for operational uptime rather than billable hours.
Industry Challenges
- Multi-Framework Compliance Burden:Integrators must simultaneously satisfy TGA medical device rules, APRA financial data standards, and state-level critical infrastructure mandates, fragmenting project management resources.
- Interoperability Protocol Fragmentation:Absence of unified Australian standards for industrial IoT messaging forces integrators to maintain multiple proprietary gateway configurations.
- Skills Certification Pipeline Lag:University and vocational programs produce generalist IT graduates lacking operational technology domain expertise, widening the experience gap for complex manufacturing deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia System Integration Market |
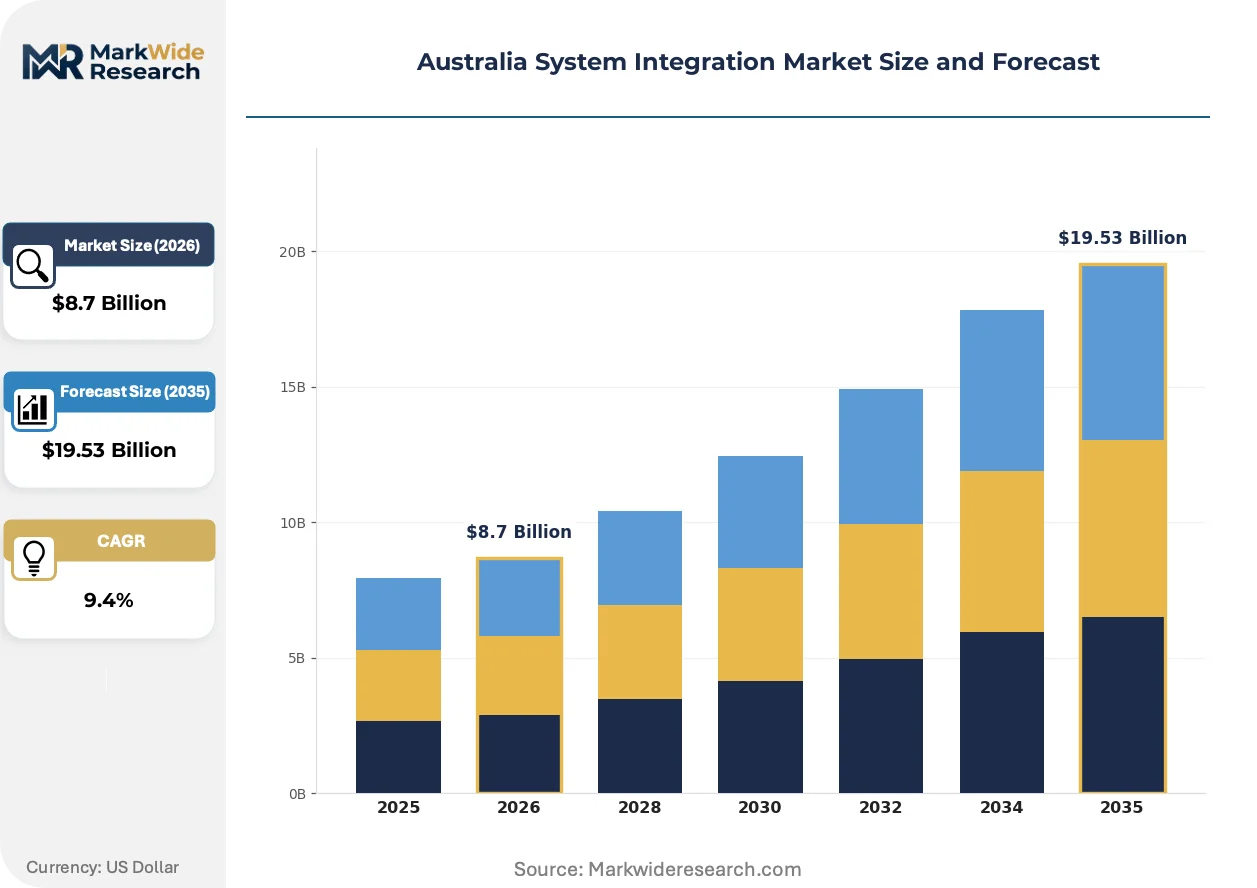
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Maintenance, Support Technology: Cloud Computing, IoT Solutions, Artificial Intelligence, Big Data End User: Manufacturing, Healthcare, Retail, Transportation Integration Level: System-to-System, Application-to-Application, Enterprise Application, Data Integration |
| Companies Covered | Accenture Australia, IBM Australia, Deloitte Australia, Capgemini Australia, TCS Australia, Telstra Purple, DXC Technology Australia, HCLTech Australia, Dialog, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia System Integration Market Trends and Innovations
Integration architecture across Australian enterprises is fragmenting into two distinct technical camps as security mandates harden and cloud-native platforms mature, reshaping vendor qualification criteria and project scoping methodologies.
Edge-native integration middleware is bifurcating the Australian market between sub-50-millisecond latency deployments for mining automation and centralized cloud orchestration for administrative workflows. Western Australia iron ore operators demand localized event streaming to maintain pit-to-port continuity during connectivity outages. This technical split is compressing vendor margins as engineering teams must maintain dual competency stacks.
The Security of Critical Infrastructure Act amendments expand sector coverage to data storage and cloud processing, compelling integrators to demonstrate supply chain visibility capabilities. Financial services institutions face APRA CPS 234 enforcement actions for inadequate third-party risk management, accelerating investment in continuous compliance monitoring tools. System integrators respond by embedding automated audit trails into every API connection from design phase.
Enterprise buyers in New South Wales and Victoria now consolidate vendor relationships around managed service partnerships rather than discrete project engagements. State government agencies lead this transition, replacing time-and-materials contracts with multi-year operational responsibility agreements. Procurement teams prioritize integrators offering 24/7 security operations center integration alongside technical implementation.
Australia System Integration Market Segmentation
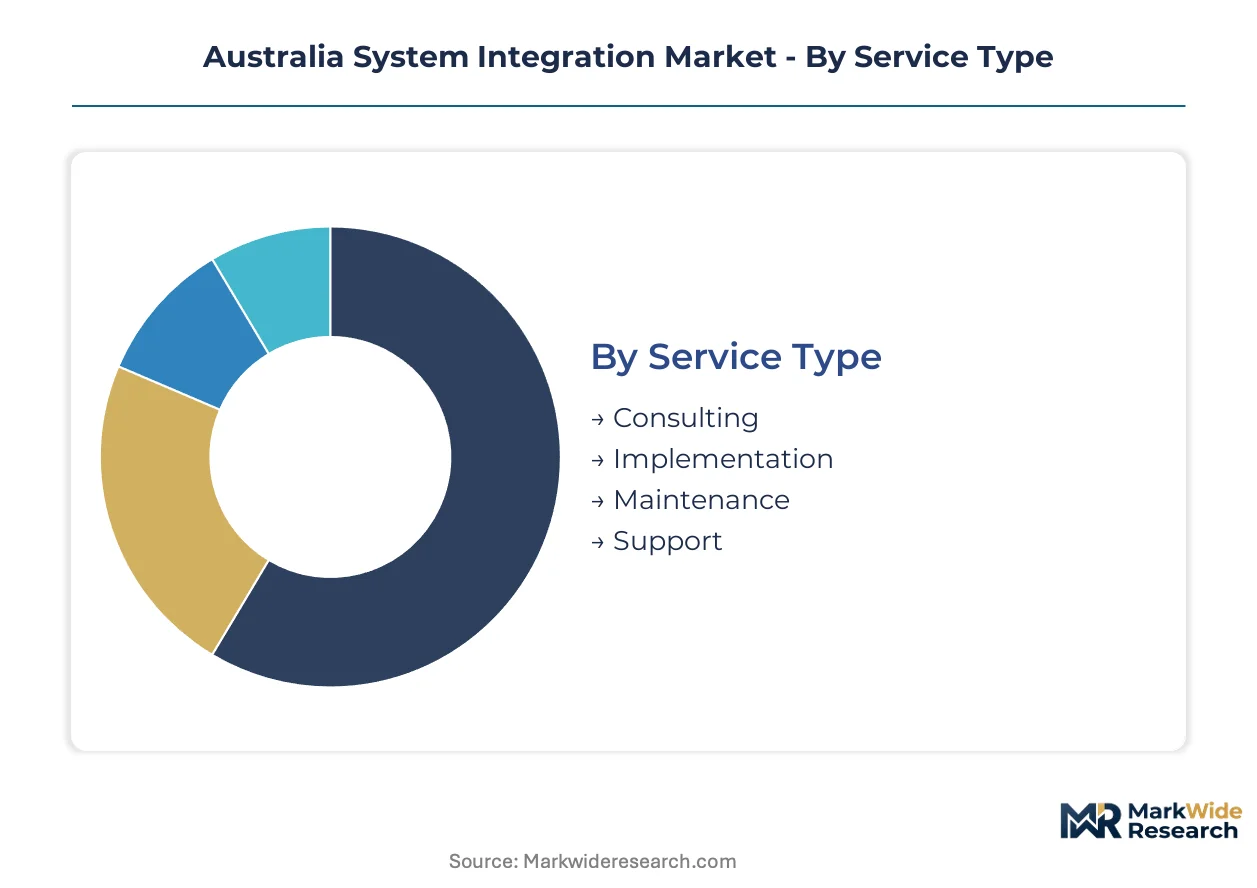
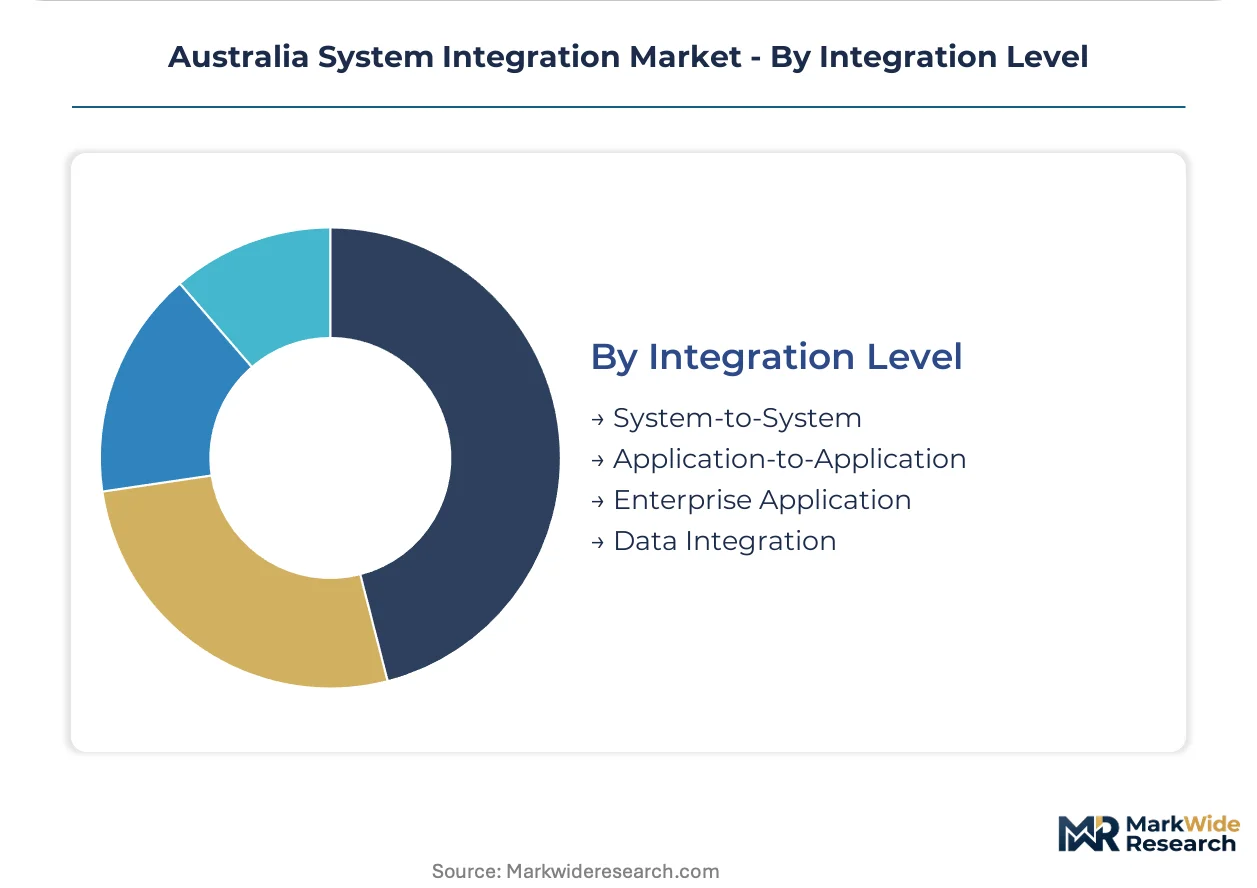
Segmentation reveals how Australia's Critical Infrastructure Protection Act and APRA CPS 234 requirements differentially impact procurement across service tiers, technology stacks, and integration complexity levels. Vendors must align certification portfolios with specific segment compliance thresholds to access federal and state contract pipelines.
Service Type:
Regulatory differentiation separates certified consulting engagements from commodity support contracts under the Essential Eight Maturity Model and state-level security frameworks.
- Consulting:Security-by-design architecture and compliance roadmap development dominate engagements, with APRA CPS 234 and TGA cybersecurity guidelines mandating certified practitioners. Demand concentrates among ASX-listed financial services firms in Sydney establishing baseline posture verification before cloud migration.
- Implementation:Middleware deployment, API orchestration, and protocol harmonization form the core technical scope. Federal agencies in Canberra and Sydney now require verified Essential Eight compliance before awarding these contracts, expanding certified partner rosters.
- Maintenance:Continuous monitoring and patch management for integrated estates.
- Support:Help desk and incident response for operational technology environments.
Established volume favors Implementation; emerging adoption favors Consulting.
Technology:
Cost tier differentiation separates hyperscale cloud migration budgets from constrained edge computing deployments across mining and healthcare verticals.
- Cloud Computing:Unified operational technology platform deployments and real-time event streaming at sub-100-millisecond latency thresholds define technical specifications. ASX-listed enterprises in New South Wales and Victoria accelerate migration mandates, driving API orchestration engagements with 24/7 security operations center integration requirements.
- IoT Solutions:SCADA consolidation and pit-to-port continuity systems for Western Australia iron ore operators demand localized event streaming during connectivity outages.
- Artificial Intelligence:Automated decision loops and predictive maintenance for manufacturing workflows.
- Big Data:ETL pipelines and analytics infrastructure for federal agency legacy modernization.
Cloud Computing captures the steepest expansion trajectory; IoT Solutions retain deepest installed base in resources sectors.
End User:
Application differentiation separates operational technology integration in resources from administrative workflow automation in services.
- Manufacturing:Operational technology convergence unifying SCADA, ERP, and IoT estates into coherent middleware architectures. Western Australia and Queensland resource operators drive demand for sub-50-millisecond latency deployments with localized redundancy.
- Healthcare:TGA cybersecurity guidelines for connected medical devices combine edge computing with clinical workflow automation, opening specialized integration verticals in Melbourne and Sydney hospital networks.
- Retail:Omnichannel platform integration and supply chain visibility systems.
- Transportation:Fleet management and logistics orchestration for interstate operators.
Manufacturing retains margin leadership through complexity premiums; Healthcare is climbing the fastest on regulatory mandate density.
Integration Level:
Margin differentiation separates high-complexity enterprise application engagements from standardized data integration projects.
- Enterprise Application:Multi-vendor technology estate unification with complexity premiums per engagement. State government agencies in New South Wales and Victoria consolidate vendor relationships around multi-year operational responsibility agreements replacing time-and-materials contracts.
- Data Integration:ETL pipeline construction and real-time streaming architecture for administrative workflows.
- System-to-System:Protocol harmonization between discrete hardware environments.
- Application-to-Application:API orchestration for software interoperability.
Enterprise Application commands highest margin per engagement; Data Integration scales most rapidly on cloud-native platform maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in New South Wales and Victoria, where Sydney and Melbourne host dense clusters of enterprise digital transformation programs. Federal procurement pipelines in Canberra and state-level security mandates across eastern seaboard states anchor vendor qualification requirements. Mining automation demand in Western Australia and Queensland creates a secondary concentration of operational technology integration expertise.
New South Wales
Sydney's financial services sector drives demand for APRA CPS 234 compliant integration architectures. The state's Critical Infrastructure Protection Act enforcement elevates security-by-design procurement standards for ASX-listed enterprises. Macquarie Park and North Sydney technology corridors concentrate certified implementation partners serving cloud migration mandates.
Victoria
Melbourne's healthcare networks and manufacturing base generate specialized IoT convergence engagements under TGA cybersecurity guidelines. The state's Essential Eight maturity model adoption compels baseline posture verification before integration contract awards. Docklands and Southbank enterprise districts anchor multi-year managed service partnerships replacing discrete project engagements.
Western Australia
Iron ore and LNG operators in the Pilbara and Karratha regions demand sub-50-millisecond latency edge deployments for pit-to-port continuity. The state's resources sector modernization consolidates disparate SCADA and ERP estates into unified middleware architectures. Perth serves as the integration coordination hub for remote operational technology deployments.
Queensland
Coal and minerals processing facilities in the Bowen Basin and Gladstone drive operational technology convergence projects. The state's critical infrastructure designation for resources supply chains mandates certified security integration from project inception. Brisbane technology precincts host specialized vendors serving both resources and emerging healthcare IoT verticals.
South Australia
Defense and advanced manufacturing programs in Adelaide create demand for high-assurance integration architectures. The state's renewable energy transition opens grid modernization and distributed energy resource management engagements. Tonsley Innovation District anchors specialized operational technology expertise for complex industrial deployments.
Australia System Integration Market Competitive Landscape
Concentration sits with global consulting networks and telecommunications-anchored integrators that have secured federal security certifications. The vendor base stratifies into three tiers: premium consulting houses commanding complexity premiums on enterprise application engagements, telecommunications-led integrators leveraging infrastructure ownership for managed service contracts, and mid-market specialists competing on legacy modernization velocity. Dominant competitive moves include security certification portfolio expansion and multi-year operational responsibility agreement pursuit.
Within the premium consulting tier, Accenture Australia and Deloitte Australia exemplify global framework localization strategies that satisfy ASX-listed enterprise procurement criteria. Telstra Purple occupies a distinct position bridging telecommunications infrastructure ownership with integration service delivery. DXC Technology Australia anchors the federal agency segment through sustained presence in legacy modernization and security-cleared personnel pools.
| Leading Market Players |
|---|
| Accenture Australia |
| IBM Australia |
| Deloitte Australia |
| Capgemini Australia |
| TCS Australia |
| Telstra Purple |
| DXC Technology Australia |
| HCLTech Australia |
| Dialog |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud infrastructure substitution for on-premises data centers simultaneously shifts supply geography toward Sydney and Melbourne technology corridors and compresses pricing premiums for mid-market integrators competing against certified global vendors. This displacement dynamic concentrates procurement leverage among three dominant cloud providers while fragmenting margin pools across dual competency requirements for edge-native and centralized architectures.
Pricing Analysis
The Essential Eight Maturity Model dictates the pricing tier structure across the Australian system integration market, separating certified security-by-design engagements from commodity implementation contracts. Three-tier pricing stratifies across premium consulting houses commanding complexity premiums on federal agency work, telecommunications-led integrators bundling infrastructure ownership with managed services, and mid-market specialists competing on legacy modernization velocity. Cost compression in the mid-tier intensifies because hyperscale migration mandates standardize technical specifications and reduce differentiation headroom. Federal agencies in Canberra demonstrate the lowest price sensitivity due to compliance-driven procurement mandates, while Queensland resources operators exhibit highest sensitivity as operational technology convergence projects face capital discipline pressures.
Supply Chain Analysis
The United States and Ireland anchor global hyperscale cloud platform provision, while Singapore and Japan supply specialized edge computing hardware for mining automation deployments. Australian system integrators draw from Taiwan-manufactured semiconductors, German industrial automation components, and domestically hosted data center infrastructure. Single-source vulnerability concentrates in hyperscale cloud provider dependency, where three vendors control the majority of federal and enterprise workload hosting. Distribution runs through direct enterprise sales teams for ASX-listed accounts, supplemented by channel partners serving state government and mid-market manufacturing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian system integration market functions as a service-attach opportunity where managed security operations and continuous compliance monitoring expand faster than discrete implementation revenue. Recurring service layers now capture multi-year operational responsibility agreements that displace time-and-materials project structures.
For Market Incumbents: Compound defensive positioning through Essential Eight certification portfolio expansion and exclusive managed service partnerships with hyperscale cloud providers. Accenture Australia and Deloitte Australia face emerging pressure from Telstra Purple's telecommunications infrastructure leverage, requiring accelerated security operations center integration investments to maintain premium consulting margins. Federal procurement pipeline access hinges on security-cleared personnel scale in Canberra. For New Entrants and Emerging Players: Lead with Tasmanian data center integration expertise and healthcare IoT convergence specializations under TGA cybersecurity guidelines as the most penetrable white-space targets. Western Australia mining automation demands localized edge computing competency that global vendors underserve due to remote deployment cost structures. A channel partnership model with Perth-based operational technology specialists enables rapid capability assembly without direct certification overhead. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors acquisition of mid-market integrators possessing Essential Eight compliance and federal security clearances. Long-term viability centers on recurring revenue ratio expansion through multi-year operational responsibility agreements replacing project-based engagements. The signal to watch is amendment timing to the Security of Critical Infrastructure Act, which would accelerate supply chain visibility mandate adoption and reshape vendor qualification economics.| Strategic Initiative | Industry Significance |
|---|---|
| Security Certification Portfolio Expansion | Essential Eight compliance unlocks federal and ASX-listed enterprise procurement pipelines in Sydney and Melbourne. |
| Managed Service Partnership Conversion | Multi-year operational responsibility agreements displace time-and-materials contracts across New South Wales and Victoria state agencies. |
| Edge Computing Competency Development | Sub-50-millisecond latency deployment capability captures Western Australia iron ore automation modernization demand. |
| Healthcare IoT Vertical Specialization | TGA cybersecurity guideline expertise opens Melbourne and Sydney hospital network integration engagements. |
| Hyperscale Cloud Alliance Deepening | Exclusive partnership tiers with dominant cloud providers secure preferential pricing and joint go-to-market access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ASX-listed enterprise procurement disclosures, federal government contract award databases, and APRA CPS 234 enforcement action records. Primary interviews engaged integration architects at tier-one consulting houses, cybersecurity leads at financial services institutions, and operational technology directors at Western Australia mining operators. Secondary validation drew from Essential Eight maturity assessment reports, TGA medical device cybersecurity guidance documents, and hyperscale cloud provider Australian capex disclosures. Bottom-up project pipeline aggregation triangulates against top-down market sizing from service type and technology segment expenditure tracking.
Segmentation dimensions modeled include service type tier, technology stack deployment model, integration complexity level, end-user vertical, and state-level regulatory jurisdiction across the projection horizon. CAGRs derive from weighted average growth rates across segment-specific demand drivers, with cross-validation against historical federal IT expenditure trends and resources sector capital allocation patterns. Industry-specific forecast inputs incorporate Security of Critical Infrastructure Act amendment probability assessments and mining automation investment cycle positioning.
Forecasts assume regulatory continuity in Australian federal critical infrastructure protection and APRA prudential standards regimes; material policy shifts expanding sector coverage or mandating supply chain visibility standards would require re-modeling. Specific risks that could revise projections include accelerated hyperscale cloud provider market concentration, prolonged operational technology certification pipeline lags, and interstate migration of enterprise digital transformation program budgets. Recalibration cycles align with material shifts in federal security framework enforcement intensity and resources sector capital commitment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Context Rich Systems Market
Digital Solutions
Digital Library Software Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
Commodity Supply Chain Management Solution Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Czech Republic ICT Market
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Container Management Software Market
Digital Solutions
Business As a Service Market