
 Physical-Digital Integration Market | 2026-2036
Physical-Digital Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Physical-Digital Integration Market Analytics
Smart manufacturing adoption is restructuring how industrial buyers evaluate physical-digital integration vendors. Siemens leverages its digital twin software stack to anchor automation contracts across European automotive plants. General Electric sustains turbine-to-cloud connectivity programs that dominate energy sector deployments. IBM competes through quantum-safe encryption layers embedded in industrial IoT gateways.
Physical-digital integration fuses sensor networks, edge computing nodes, and cloud-native platforms into unified operational systems where latency thresholds below 10 milliseconds enable real-time process control. IoT Platforms lead technology deployment as enterprises prioritize device orchestration over isolated AR or VR pilots. Smart Displays command premium positioning in retail experience applications where ambient computing replaces static signage. Wearable Tech occupies accelerating health monitoring segments despite lingering FDA clearance timelines for biometric accuracy claims.
The EU AI Act imposes conformity assessment burdens on autonomous physical-digital systems deployed in European industrial settings. The FDA regulates health monitoring wearables as Class II medical devices when diagnostic algorithms process continuous physiological streams. NIST cybersecurity frameworks shape procurement specifications for federal IoT contracts in the United States. Stakeholders must monitor how divergent regulatory timelines across jurisdictions fragment product certification roadmaps and alter go-to-market sequencing.
Market Dynamics
Smart manufacturing contracts now bundle hardware procurement with multi-year software subscriptions, compressing vendor selection cycles and locking buyers into integrated technology stacks that span sensor deployment through cloud analytics.
Growth Catalysts
- EU AI Act conformity requirements:European industrial facilities must certify autonomous physical-digital systems through notified bodies, creating sustained demand for audit-ready IoT architectures and compliance-embedded hardware.
- Automotive digital twin deployment:Vehicle manufacturers in Germany and South Korea replicate entire production lines in virtual environments to optimize throughput before physical retooling, driving sensor density requirements.
- Edge computing node proliferation:Latency-sensitive process control applications across energy and chemical plants mandate localized data processing, expanding the addressable hardware layer beyond cloud-centric models.
Market Restraints
- Semiconductor supply concentration:Advanced sensor and edge processor fabrication remains concentrated in Taiwan and South Korea, exposing deployment timelines to geopolitical disruption and capacity constraints.
- Cybersecurity certification costs:NIST framework compliance for US federal IoT contracts requires third-party penetration testing and continuous monitoring infrastructure that elevates total cost of ownership.
- Legacy system interoperability barriers:Brownfield industrial sites operate decades-old SCADA protocols that resist native integration with IP-based sensor networks without expensive protocol translation layers.
Strategic Opportunities
- India manufacturing digitization:Production-linked incentive schemes for electronics and automotive sectors are attracting contract manufacturers that require greenfield physical-digital infrastructure.
- Digital twin-as-a-service models:Mid-sized industrial operators in France and Italy lack capital for full in-house simulation platforms, creating subscription revenue potential for hosted virtual commissioning environments.
- Quantum-safe encryption retrofit:NIST post-quantum cryptographic standards will mandate hardware upgrades across critical infrastructure, opening replacement cycles for industrial gateways and edge devices.
Industry Challenges
- Cross-functional talent scarcity:Deployment teams must combine OT engineering expertise with cloud architecture skills, a combination rarely found in single labor markets and expensive to assemble.
- FDA clearance timelines for wearables:Health monitoring devices with diagnostic algorithms face 18-24 month Class II medical device review cycles that delay revenue recognition and consume regulatory capital.
- Fragmented data sovereignty requirements:German industrial operators must maintain operational data within national borders under BSI guidelines, complicating multi-national cloud architectures and increasing infrastructure duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical-Digital Integration Market |
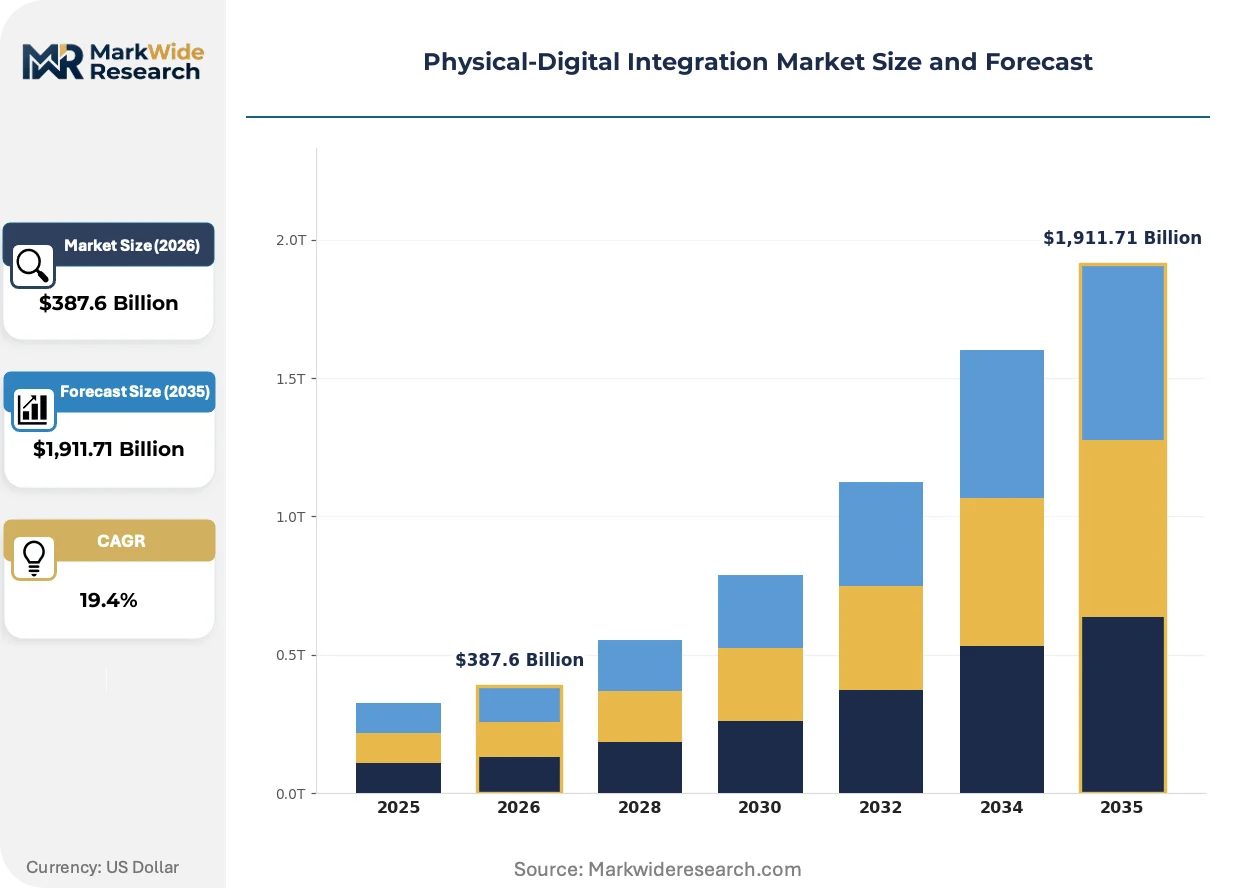
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,911.71 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor Devices, Smart Displays, Wearable Tech, Interaction Tools Technology: Augmented Reality, Virtual Reality, IoT Platforms, Cloud Solutions Application: Retail Experience, Remote Collaboration, Health Monitoring, Smart Home End User: Enterprises, Consumers, Educational Institutions, Industrial Users |
| Companies Covered | Siemens, General Electric, IBM, Honeywell, Schneider, Microsoft, Accenture, Tata Consultancy Services, Deloitte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical-Digital Integration Market Evolving Landscape
Physical-digital integration is evolving from discrete technology pilots toward unified operational platforms where sensor networks, edge intelligence, and cloud analytics operate as single orchestrated systems rather than layered add-ons.
Digital twin software is consolidating previously separate simulation, predictive maintenance, and process optimization tools into unified manufacturing execution environments. Automotive and aerospace producers in Germany and the United States now mandate that equipment suppliers deliver native digital twin compatibility as a procurement condition. This consolidation is compressing the vendor landscape by favoring full-stack providers over point-solution specialists.
The EU AI Act imposes conformity assessment obligations on autonomous physical-digital systems deployed in European industrial settings, requiring documented risk management systems and human oversight protocols. Manufacturers must redesign product architectures to embed explainability features and audit trails from the sensor layer upward. Medical device and automotive segments face the steepest compliance burdens, with notified body backlogs already extending certification timelines.
Industrial buyers are consolidating vendor relationships to reduce integration complexity and accountability fragmentation. Multi-year framework agreements now dominate capital equipment procurement in energy and chemicals, replacing transactional purchasing of isolated sensors and software modules. This concentration is most pronounced in the United States, where federal infrastructure spending mandates single-source accountability for cybersecurity incidents.
Physical-Digital Integration Market Segmentation
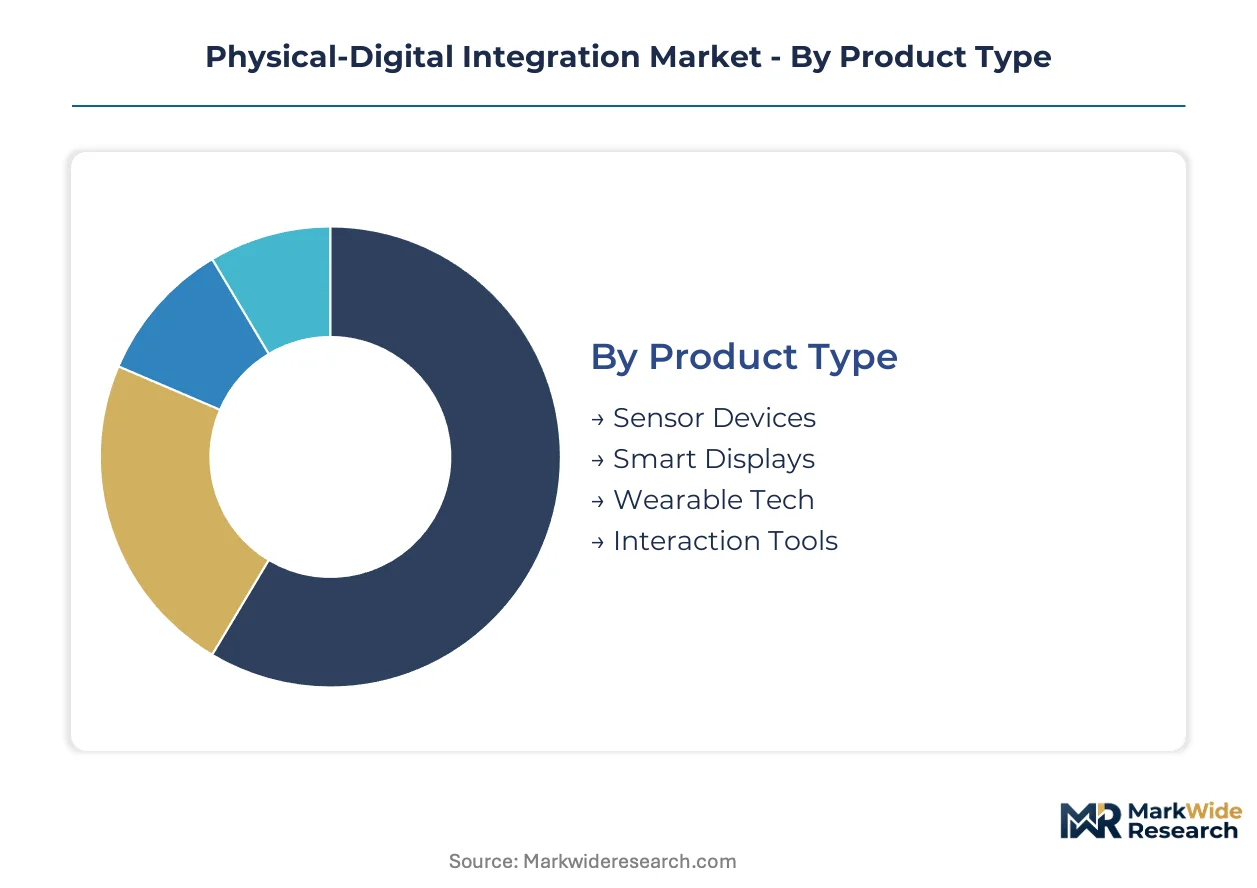
Segmentation in physical-digital integration reveals how technology stacks bundle differently across deployment contexts. Procurement patterns diverge sharply between industrial buyers seeking unified operational platforms and consumer markets prioritizing discrete device functionality.
Product Type:
Supply concentration in semiconductor fabrication concentrates competitive advantage among vendors with captive sensor production or deep component partnerships.
- Sensor Devices:Multi-modal environmental, motion, and proximity sensors form the foundational data layer for industrial IoT deployments. Automotive plants in Germany and South Korea drive demand for high-density sensor arrays capable of sub-millisecond latency in digital twin environments.
- Smart Displays:Ambient computing surfaces integrate computer vision and edge processing for contextual content delivery. Retail experience applications in the United States absorb premium positioning as static signage replacement accelerates in flagship store networks.
- Wearable Tech:Biometric monitoring bands and smartwatches process continuous physiological streams for health applications.
- Interaction Tools:Haptic controllers and gesture recognition hardware enable spatial computing interfaces for design and training environments.
Sensor Devices absorb the bulk of installed capacity; Smart Displays are expanding most quickly.
Technology:
Cost tier differentiation separates enterprise-grade orchestration platforms from consumer-facing immersive experiences.
- IoT Platforms:Device orchestration middleware manages authentication, firmware updates, and data routing across heterogeneous sensor populations. Energy sector deployments in the United States prioritize these platforms for turbine-to-cloud connectivity programs requiring NIST cybersecurity framework compliance.
- Cloud Solutions:Scalable compute and storage infrastructure hosts analytics workloads for predictive maintenance and process optimization. European industrial operators under GDPR and EU AI Act constraints increasingly demand sovereign cloud architectures with data residency guarantees.
- Augmented Reality:Spatial overlay systems project contextual information onto physical environments for maintenance and assembly guidance.
- Virtual Reality:Fully immersive simulation environments support training and virtual commissioning applications.
IoT Platforms command the largest deployment footprint; Cloud Solutions are climbing the fastest as edge-to-cloud architectures mature.
Application:
Volume concentration clusters around use cases with measurable operational efficiency returns rather than experiential enhancements.
- Health Monitoring:Continuous physiological tracking applications process heart rate variability, blood oxygen, and sleep architecture data. FDA Class II medical device clearance requirements in the United States constrain market entry for diagnostic algorithm developers.
- Remote Collaboration:Spatial presence systems replicate in-person interaction fidelity for distributed engineering and design teams. Aerospace manufacturers in France and Germany deploy these tools for virtual assembly verification across multi-site production networks.
- Retail Experience:Ambient computing deployments replace static signage with adaptive content triggered by customer proximity and behavior.
- Smart Home:Residential automation integrates climate, lighting, and security systems through unified control interfaces.
Health Monitoring captures the deepest revenue per deployment; Remote Collaboration is gaining share fastest as hybrid work models persist.
End User:
Customer type determines procurement cycle length, with industrial buyers negotiating multi-year framework agreements against consumer transactional purchasing.
- Industrial Users:Manufacturing, energy, and chemical operators deploy integrated sensor-to-cloud systems for process control and predictive maintenance. Production-linked incentive schemes in India are attracting contract manufacturers requiring greenfield physical-digital infrastructure.
- Enterprises:Corporate and institutional buyers prioritize cybersecurity certification and vendor accountability consolidation. Federal infrastructure spending mandates in the United States drive single-source procurement for IoT security incidents.
- Consumers:Individual purchasers evaluate discrete device functionality and ecosystem compatibility for personal health and home applications.
- Educational Institutions:Universities and technical colleges deploy immersive tools for vocational training and research visualization.
Industrial Users account for the majority of capital deployment; Enterprises are expanding most quickly as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of edge processors and industrial sensors concentrates in Taiwan and South Korea, while consumption of integrated physical-digital systems clusters in Germany, the United States, and Japan where automotive and energy sectors drive deployment.
United States
Federal infrastructure spending and NIST cybersecurity framework mandates accelerate procurement of sovereign IoT architectures for energy and defense applications. The Department of Defense and Department of Energy impose single-source accountability requirements on contractors deploying sensor-to-cloud systems. Texas and California host the densest concentrations of industrial IoT deployments, with Gulf Coast refineries and Silicon Valley data centers driving edge computing node installation.
Germany
Automotive digital twin initiatives at BMW, Mercedes-Benz, and Volkswagen require high-density sensor arrays and sub-millisecond latency infrastructure. The EU AI Act and BSI data sovereignty guidelines force operational data residency within national borders, complicating multi-national cloud architectures. Bavaria and Baden-Württemberg anchor industrial digitization, with Munich and Stuttgart metropolitan areas hosting advanced manufacturing clusters integrating virtual commissioning environments.
South Korea
Samsung and Hyundai Motor Group replicate entire production lines in virtual environments before physical retooling, driving sensor density requirements across electronics and automotive plants. The national digital twin initiative receives government funding under the Manufacturing Renaissance Strategy. Seoul Capital Area and Busan-Ulsan corridor concentrate deployment, with Gumi and Hwaseong industrial complexes leading smart factory adoption.
Japan
METI's Society 5.0 vision prioritizes cyber-physical systems integration for aging workforce compensation and productivity maintenance. The Ministry of Economy, Trade and Industry funds interoperability standards development for legacy SCADA protocol translation. Kanto region around Tokyo and Chubu region centered on Nagoya host the deepest concentrations, with Toyota City and Yokohama manufacturing zones deploying predictive maintenance at scale.
India
Production-linked incentive schemes for electronics and automotive sectors attract Foxconn, Tata Motors, and contract manufacturers requiring greenfield physical-digital infrastructure. The Ministry of Electronics and Information Technology mandates local data storage for critical infrastructure under the National Data Governance Framework Policy. Maharashtra and Gujarat lead deployment, with Pune automotive clusters and Sanand electronics manufacturing zones driving sensor network installation.
Physical-Digital Integration Market Competitive Landscape
Top-tier vendors anchor full-stack integration contracts, while mid-tier specialists compete on protocol translation and edge computing modules. The market structure favors consolidated procurement relationships where buyers reduce vendor count to simplify cybersecurity accountability and integration complexity. Two strategic archetypes dominate: industrial automation incumbents with captive software stacks, and IT services conglomerates embedding compliance layers into outsourced deployments. Competitive moves concentrate on multi-year framework agreements and quantum-safe encryption retrofit programs.
Within the industrial automation archetype, Siemens and General Electric exemplify full-stack providers bundling hardware procurement with software subscriptions. IBM occupies a distinct tier through quantum-safe encryption positioning in federal and critical infrastructure contracts. Among IT services conglomerates, Accenture and Deloitte sit within the compliance-embedded deployment segment, while Tata Consultancy Services represents the India-based systems integration vector serving contract manufacturers under production-linked incentive schemes.
| Leading Market Players |
|---|
| Siemens |
| General Electric |
| IBM |
| Honeywell |
| Schneider |
| Microsoft |
| Accenture |
| Tata Consultancy Services |
| Deloitte |
| Others |
Value Network & Pricing Analysis
Federal single-source accountability mandates for cybersecurity incidents are compressing vendor selection cycles and forcing suppliers to absorb compliance certification costs into bundled hardware-software contracts. This procurement consolidation eliminates spot-market purchasing flexibility and rewards integrated stack providers with pricing power over fragmented component vendors.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as automotive and energy buyers penalize delivery delays that stall digital twin deployments. Three-tier pricing structure across premium, standard, and economy levels separates NIST-compliant federal-grade systems from commercial industrial configurations and basic sensor hardware without embedded security layers. Price differentiation hinges on cybersecurity certification tier and volume scale, with hyperscale automotive contracts commanding standard-tier discounts unavailable to mid-sized chemical operators. Cost compression in economy-tier sensor hardware is intensifying because Taiwanese foundry capacity constraints force buyers toward higher-margin edge processor bundles. Industrial users in federal contracting channels exhibit lowest price sensitivity; mid-sized French and Italian manufacturers seeking digital twin-as-a-service subscriptions show highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from BMW, Samsung, and Hyundai Motor Group, while systems integrators serve fragmented mid-market demand across European automotive suppliers. Geographic supply concentration centers on Taiwan and South Korea for advanced edge processors and multi-modal sensors, with secondary sourcing from Japan for precision motion components. Raw material dependencies include silicon wafers, rare earth elements for magnet-based proximity sensors, and high-purity copper for signal transmission infrastructure. Single-source vulnerability in Taiwanese semiconductor fabrication exposes deployment timelines to geopolitical disruption and capacity allocation decisions by foundry operators. Distribution runs through authorized industrial automation distributors with certified integration capabilities, bypassing generic electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as full-stack providers capture multi-year framework agreements by controlling sensor production, edge software, and cloud analytics layers. Incumbents and entrants must secure upstream component access or downstream deployment control to defend margin position.
For Market Incumbents: Extend captive sensor manufacturing partnerships or backward integration into edge processor design to lock in supply security against Taiwanese foundry concentration risk. Bundle quantum-safe encryption modules as standard features to preempt NIST compliance-driven replacement cycles and forestall IBM's federal contracting advantage. Consolidate channel relationships with Indian contract manufacturers under PLI schemes before Tata Consultancy Services and Accenture cement systems integration control. For New Entrants and Emerging Players: Protocol translation layers for legacy SCADA integration represent the most penetrable white space, as brownfield industrial sites resist native IP-based sensor deployment without expensive interoperability solutions. Target mid-sized French and Italian automotive suppliers lacking capital for full in-house digital twin platforms but requiring EU AI Act-compliant virtual commissioning environments. Pursue hosted digital twin-as-a-service models with subscription pricing to bypass incumbent hardware procurement relationships. For Investors and Strategic Acquirers: The window for entry favors quantum-safe encryption specialists and legacy protocol translation software developers ahead of NIST post-quantum cryptographic standard enforcement. Long-term viability hinges on acquisition targets with embedded compliance architectures rather than point-solution sensor vendors facing margin compression. Watch notified body backlog extensions for EU AI Act conformity assessments as the inflection signal for compliance-embedded hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Safe Encryption Retrofit | NIST post-quantum standards will mandate hardware upgrades across critical infrastructure gateways. |
| Digital Twin-as-a-Service Launch | Hosted virtual commissioning environments capture mid-sized French and Italian manufacturers lacking capital. |
| Legacy Protocol Translation Acquisition | Brownfield SCADA interoperability unlocks brownfield industrial sites resistant to native IP sensor deployment. |
| Indian Manufacturing Digitization Partnership | PLI scheme contract manufacturers require greenfield physical-digital infrastructure at scale. |
| EU AI Act Compliance Certification Investment | Notified body relationships accelerate conformity assessment timelines for autonomous system deployments. |
Research Methodology
SEC filings, customs and trade databases, and hyperscaler capital expenditure disclosures formed the secondary backbone for supply-side capacity and demand-side procurement pattern analysis. Primary interviews with plant engineers, OEM procurement teams, industrial IoT platform architects, and aftermarket service heads validated deployment timelines and vendor selection criteria. Bottom-up sensor shipment and edge node installation data triangulated against top-down automotive and energy sector capital expenditure forecasts to establish market sizing boundaries.
Historical trendline analysis across technology deployment cycles informed projection assumptions throughout the forecast period. Segmentation modeling incorporated product type, technology stack, application use case, and end-user procurement archetype dimensions. CAGRs were derived from installed base growth rates and replacement cycle acceleration under regulatory compliance deadlines. Forecast inputs included semiconductor foundry capacity expansion announcements, EU AI Act implementation timelines, and NIST cybersecurity framework revision schedules.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruptions to Taiwanese semiconductor supply, accelerated FDA clearance pathways for diagnostic wearables, and sovereign cloud data residency requirement expansions beyond current BSI and GDPR boundaries. Forecasts reflect assumptions regarding regulatory implementation consistency and foundry capacity allocation continuity. Periodic stress-testing of base assumptions is recommended against notified body backlog fluctuations and federal infrastructure spending authorization revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mexico ICT Market
Digital Solutions
Data Integration Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
G2P Systems Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
Document Management System Market