
 Solar Vehicle Market | 2026-2036
Solar Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Vehicle Market Analysis
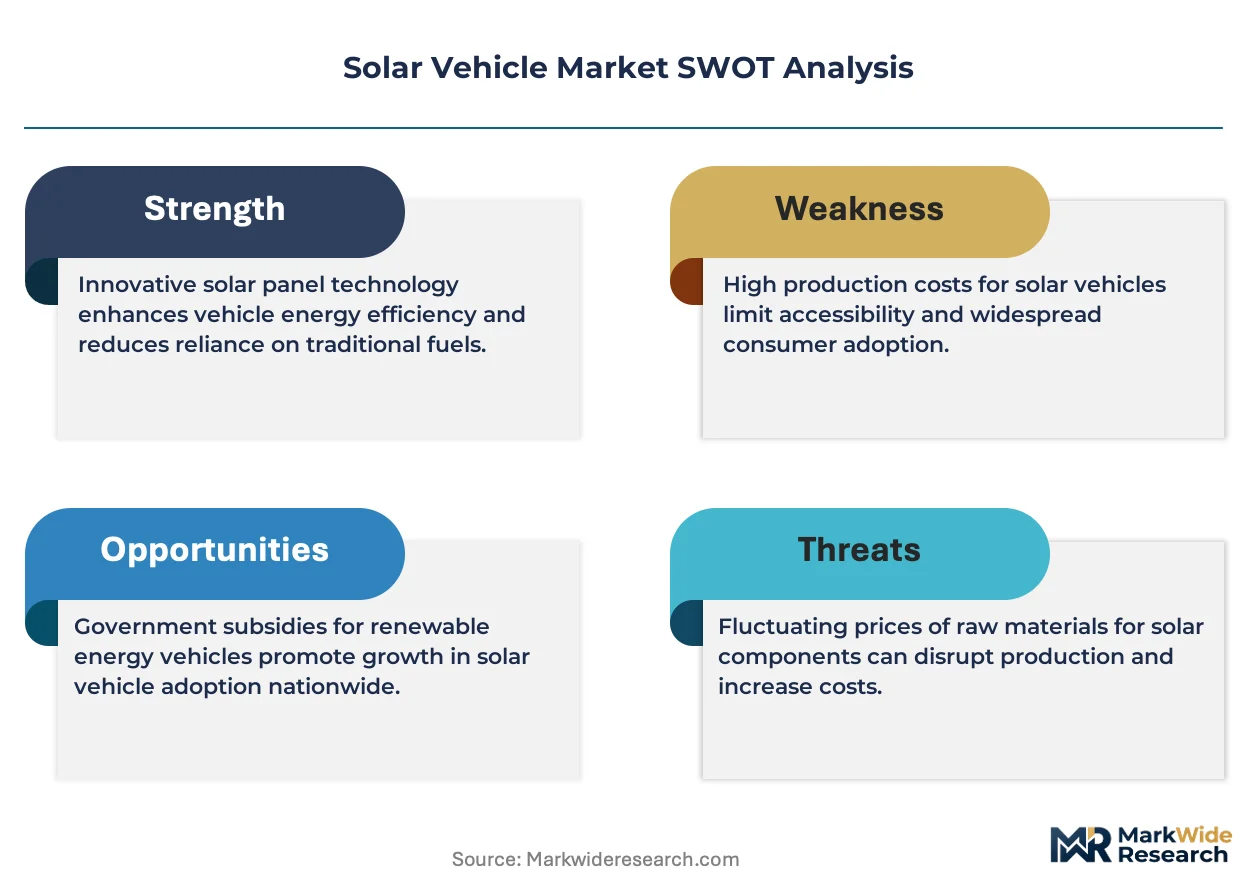
Silicon-perovskite tandem cell integration is narrowing the efficiency gap between laboratory prototypes and mass-production panels for automotive applications. Sono Motors leverages polymer-based solar body panels to embed photovoltaics directly into vehicle exteriors without compromising structural integrity. Lightyear sustains ultra-aerodynamic platform development to maximize energy yield from limited surface area. Toyota anchors its solar strategy through hybrid synergy drive systems that supplement rather than replace conventional powertrains.
A solar vehicle integrates photovoltaic cells into its body, roof, or supplemental surfaces to convert sunlight into electrical energy that charges onboard batteries or powers electric drivetrains directly, with commercial variants typically achieving 15-45 km of daily range extension from solar input alone. The primary industrial purpose centers on reducing grid dependency and operating cost exposure for electric mobility operators. Passenger vehicles currently occupy the largest addressable surface area for panel deployment, though commercial trucks command higher per-unit value given their expansive roof planes and predictable fleet utilization patterns. Photovoltaic cell technology leads investment intensity as manufacturers pursue higher conversion efficiency at automotive-grade durability standards, while energy management systems differentiate through intelligent routing of harvested power between propulsion, cabin loads, and battery conditioning.
The US EPA tailpipe emission standards and California Air Resources Board zero-emission mandates create compliance pull for solar-assisted electrification, while the EU Green Deal and F-Gas Regulation constrain refrigerant choices that affect thermal management system design. India's PLI scheme for advanced chemistry cells and solar module manufacturing builds indigenous supply capacity that reduces import dependency for domestic assemblers. Stakeholders must monitor how battery chemistry roadmaps align with solar charging profiles, as mismatched charge acceptance rates could strand capital in incompatible technology stacks regardless of panel efficiency gains.
Market Dynamics
Fleet operators in last-mile logistics are compressing procurement cycles for solar-assisted electric vehicles as thin-film photovoltaic efficiency gains and solid-state battery integration reshape total cost of ownership calculations. This buyer concentration is forcing module suppliers to certify automotive-grade durability standards faster than laboratory-to-production timelines traditionally allow.
Growth Catalysts
- California Air Resources Board zero-emission mandates:Compliance pull from CARB standards accelerates solar-assisted electrification adoption among commercial fleet operators seeking regulatory certainty.
- Last-mile logistics fuel exposure reduction:Fleet operators prioritize solar range extension to hedge against petroleum price volatility in urban delivery routes.
- Silicon-perovskite tandem cell efficiency:Laboratory breakthroughs in tandem cell architecture narrow the gap between prototype and mass-production panel performance for automotive surfaces.
Market Restraints
- Photovoltaic cell supply concentration:Crystalline silicon wafer production clusters in China create import dependency risks for Western vehicle assemblers.
- Solid-state battery capex intensity:Dry electrode manufacturing and sulfide electrolyte handling require billion-dollar fabrication facilities that strain mid-tier producer balance sheets.
- EU F-Gas Regulation thermal constraints:Refrigerant phase-down timelines force redesign of cabin cooling systems that compete with battery conditioning for harvested solar energy.
Strategic Opportunities
- India PLI scheme localization:Advanced chemistry cell and solar module manufacturing incentives build indigenous supply capacity for domestic electric vehicle assemblers.
- Commercial truck roof-plane deployment:Predictable fleet utilization patterns and expansive surface area create higher per-unit value capture than passenger vehicle applications.
- Vehicle-to-grid integration:Bidirectional charging infrastructure enables fleet operators to monetize solar-harvested energy during peak grid demand periods.
Industry Challenges
- Automotive-grade PV certification timelines:IEC 61215 and IEC 61646 testing protocols for vibration, thermal cycling, and humidity freeze extend product validation cycles beyond typical automotive development windows.
- Battery chemistry-solar charge profile mismatch:Lithium iron phosphate and nickel manganese cobalt cells exhibit divergent charge acceptance rates that strand capital in incompatible technology stacks.
- Polymer substrate integration complexity:Embedding photovoltaics into vehicle body panels without compromising structural crashworthiness requires cross-functional engineering coordination absent in tiered supplier hierarchies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Vehicle Market |
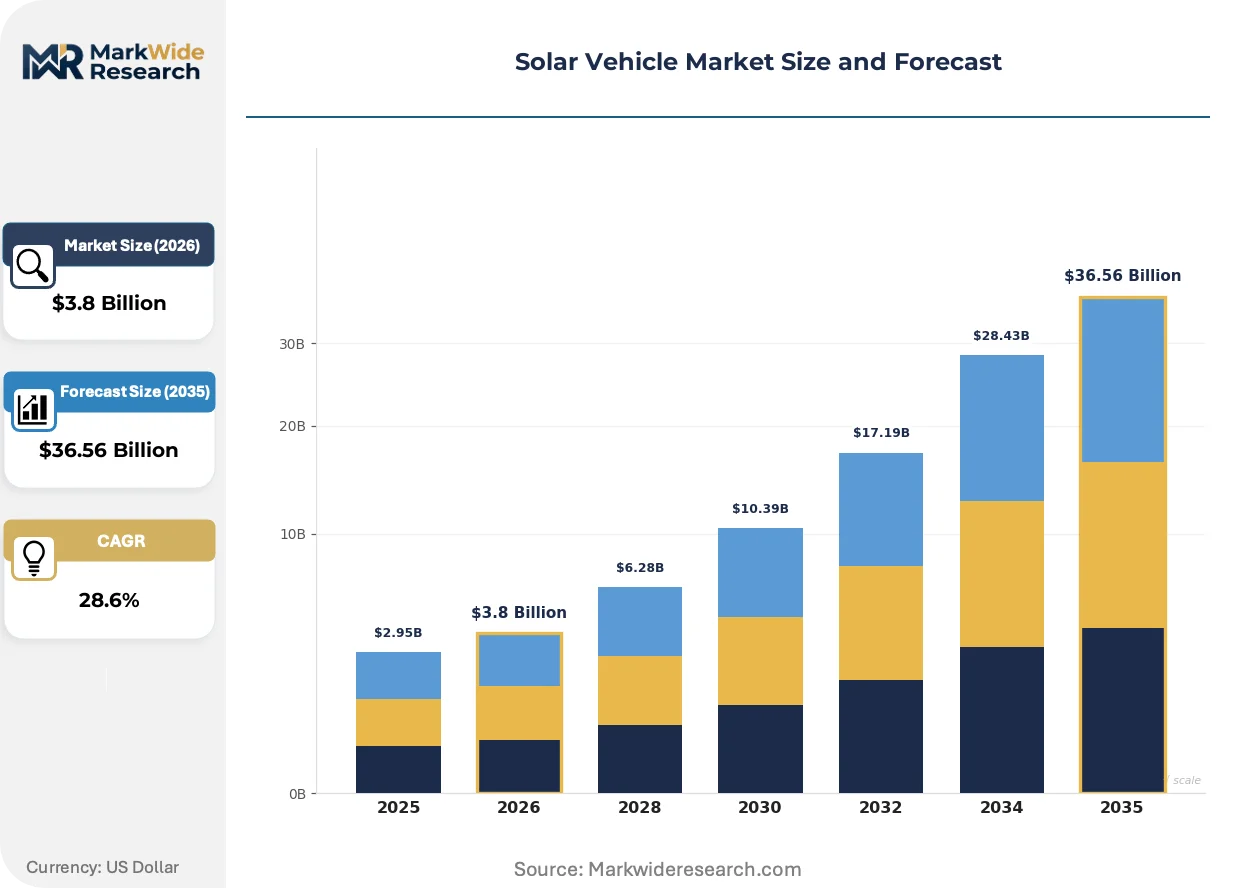
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Vehicles, Commercial Trucks, Buses, Motorcycles Technology: Photovoltaic Cells, Hybrid Systems, Battery Technology, Energy Management Systems Application: Transport, Leisure, Utility, Fleet Management End User: Consumers, Businesses, Government, Research Institutions |
| Companies Covered | Sono Motors, Lightyear, Aptera Motors, Toyota Motor Corporation, Ford Motor Company, Volkswagen, General Motors, Hyundai Motor Company, Mahindra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Vehicle Market Emerging Trajectories
Photovoltaic cell technology is commanding investment intensity as manufacturers pursue conversion efficiency gains at automotive-grade durability standards. Three distinct vectors are compressing development timelines and reshaping competitive positioning.
Silicon-perovskite tandem cell architectures are rendering obsolete conventional single-junction silicon panels for automotive applications. Sono Motors and Lightyear are embedding these cells into polymer body substrates and ultra-aerodynamic platforms respectively. The structural consequence is collapsing the efficiency premium that laboratory prototypes previously held over mass-production panels.
EU F-Gas Regulation refrigerant constraints are forcing thermal management system redesigns across German and Dutch test-bed markets. The regulation's hydrofluorocarbon phase-down timeline compresses supplier development cycles for heat pump integration. Commercial truck segments with high cabin cooling loads face disproportionate engineering resource allocation to maintain solar energy routing efficiency.
Fleet procurement committees are consolidating vendor selection authority previously dispersed across sustainability, operations, and finance functions. This concentration accelerates pilot-to-scale transitions for solar-assisted vehicles in California logistics hubs. The shift is most visible among third-party delivery contractors serving e-commerce platforms with published net-zero commitments.
Solar Vehicle Market Segmentation
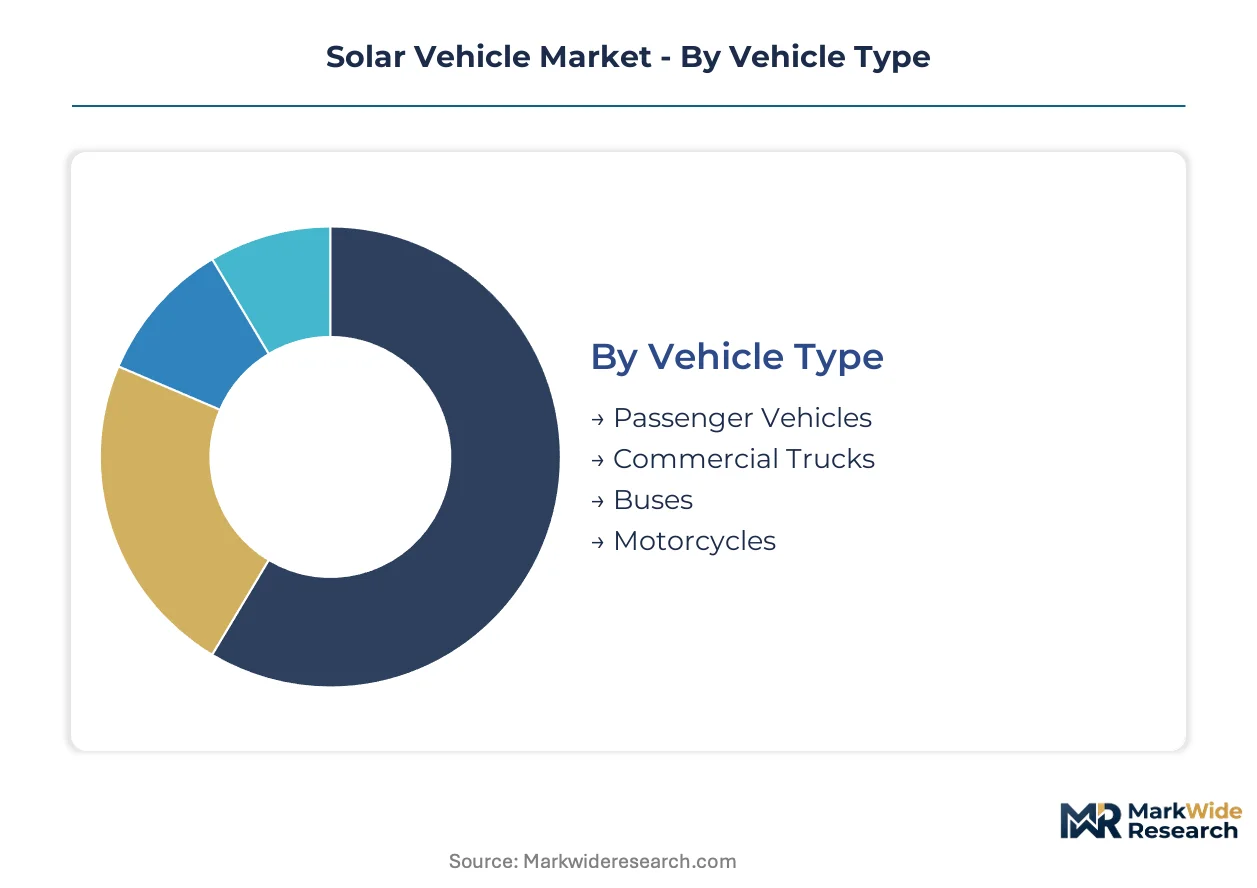
Segmentation in the solar vehicle market reveals how surface area constraints, duty cycle intensity, and procurement authority concentration allocate investment returns across radically different use cases. Understanding these divisions exposes where photovoltaic integration delivers measurable operating cost reduction versus where it remains demonstrative.
Vehicle Type:
Passenger vehicles anchor near-term deployment volumes while commercial variants concentrate value capture per installed watt.
- Passenger Vehicles:Sedans, hatchbacks, and SUVs integrate solar panels across roof, hood, and trunk surfaces, typically yielding 15-45 km of daily range extension. German and California consumers with residential solar pairing drive retail demand for Sono Motors and Lightyear configurations.
- Commercial Trucks:Expansive roof planes on delivery vans and rigid trucks accommodate 3-5x the panel area of passenger vehicles, with predictable fleet utilization patterns amortizing premium acquisition costs through fuel hedge value. Last-mile logistics operators in the Netherlands compress procurement cycles for these configurations.
- Buses:Municipal transit authorities deploy solar supplementation primarily for auxiliary loads—HVAC and onboard electronics—rather than traction power, given roof curvature constraints and high-cabin energy demand.
- Motorcycles:Two-wheeled platforms present severe surface area limitations, restricting solar integration to range-extender accessories and off-grid charging stations for adventure touring segments.
Passenger vehicles retain volume leadership; commercial trucks hold the steepest expansion curve.
Technology:
Cost tier stratification separates laboratory-proven architectures from mass-production-ready systems.
- Photovoltaic Cells:Silicon-perovskite tandem architectures are displacing conventional single-junction silicon for automotive applications, with Sono Motors embedding polymer-based cells directly into body panels without compromising structural integrity.
- Hybrid Systems:Toyota's hybrid synergy drive approach supplements rather than replaces internal combustion, reducing regulatory compliance cost for manufacturers without full electrification commitment.
- Battery Technology:Solid-state electrolyte systems promise faster solar charge acceptance and improved cold-weather performance, though dry electrode manufacturing demands billion-dollar fabrication facilities that strain mid-tier producer balance sheets.
- Energy Management Systems:Intelligent routing algorithms prioritize harvested power between propulsion, cabin conditioning, and battery thermal management, with EU F-Gas Regulation refrigerant constraints forcing redesign of competing thermal loads.
Photovoltaic cells command the deepest R&D allocation; energy management systems are climbing the fastest as software differentiation intensifies.
Application:
Customer type concentration varies sharply between scheduled fleet operations and discretionary use patterns.
- Transport:Daily commuting and intercity mobility constitute the dominant addressable hours, with solar yield directly substituting for grid charging during peak electricity rate periods.
- Leisure:Recreational vehicles and camper vans exploit off-grid parking to maximize solar harvest independence, though seasonal usage patterns limit annual kilometer accumulation.
- Utility:Agricultural and construction equipment deploy solar for auxiliary power and battery maintenance during intermittent operation cycles.
- Fleet Management:Centralized procurement authority among third-party delivery contractors serving e-commerce platforms accelerates pilot-to-scale transitions in California logistics hubs.
Transport absorbs the largest absolute deployment; fleet management is gaining share fastest through consolidated vendor selection authority.
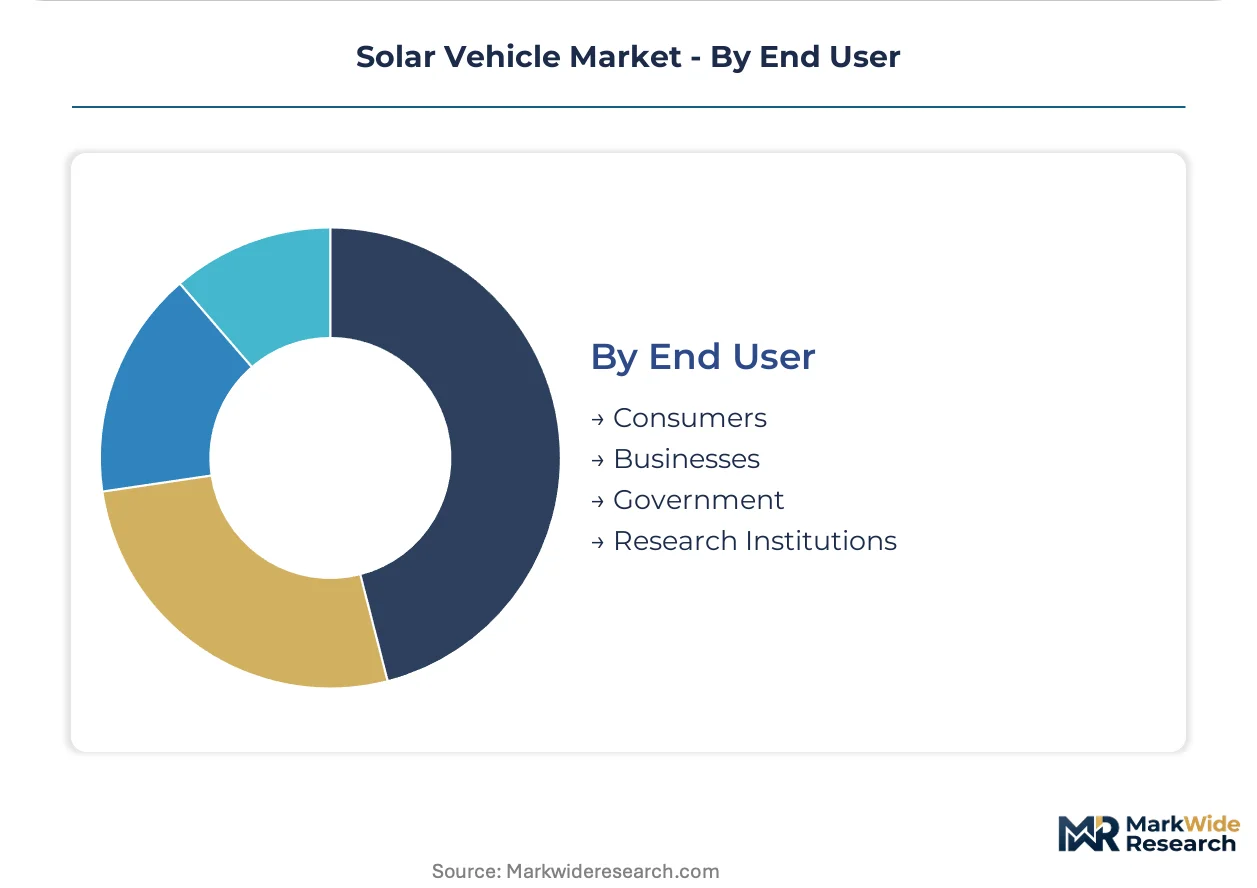
End User:
Procurement sophistication separates price-sensitive retail buyers from total-cost-of-ownership calculators.
- Consumers:Individual purchasers prioritize capital cost and aesthetic integration, with German subsidy frameworks reducing effective price premiums for early adopters.
- Businesses:Fleet operators hedge petroleum price exposure through solar range extension, with last-mile logistics compressing payback period calculations via high daily utilization.
- Government:Municipal and national procurement mandates—California Air Resources Board zero-emission standards, EU Green Deal targets—create compliance-pull demand independent of private return thresholds.
- Research Institutions:Universities and national laboratories validate field performance data, bridging the gap between laboratory efficiency claims and real-world automotive durability.
Businesses anchor revenue concentration; government procurement is expanding most quickly through regulatory mandate acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports solar vehicle components and engineering services to Dutch and Belgian fleet operators, establishing a trade corridor that channels technology westward into subsidy-rich adoption markets.
Germany
Last-mile logistics operators in Berlin and Hamburg compress procurement cycles for solar-assisted electric vans. The KBA enforces automotive-grade certification standards that accelerate IEC 61215 validation protocols for photovoltaic body panels. Bavaria's automotive engineering clusters around Munich concentrate polymer substrate integration R&D for embedded solar architectures.
Netherlands
Urban delivery contractors serving Rotterdam and Amsterdam e-commerce hubs prioritize solar range extension for diesel displacement. EU Green Deal targets mandate zero-emission logistics zones in major municipalities by 2030. Eindhoven's high-tech campus hosts field validation programs for commercial truck roof-plane deployments.
United States
California third-party delivery fleets hedge petroleum price exposure through solar-assisted vehicle acquisitions. EPA tailpipe standards and CARB zero-emission mandates create compliance-pull demand independent of private return thresholds. Los Angeles and San Francisco logistics corridors concentrate pilot-to-scale transitions for solar range extension technologies.
India
Domestic electric vehicle assemblers in Pune and Chennai source solar modules under PLI scheme incentives for advanced chemistry cell manufacturing. The CEA regulates grid interconnection standards that affect vehicle-to-grid monetization potential. Tamil Nadu's industrial belt builds indigenous supply capacity to reduce crystalline silicon import dependency from Chinese wafer producers.
Japan
Hybrid synergy drive systems dominate consumer demand in Tokyo and Osaka metropolitan areas where full electrification infrastructure remains uneven. METI coordinates national hydrogen and electrification roadmaps that include solar supplementation strategies. Nagoya's automotive supplier networks refine energy management algorithms for intelligent solar power routing.
Solar Vehicle Market Vendor Landscape
On the supply side, the industry is bifurcated between established automotive OEMs with hybrid legacy architectures and venture-backed specialists pursuing dedicated solar-native platforms. The competitive terrain separates volume-scaled manufacturers with regulatory compliance expertise from engineering-focused entrants with materials science differentiation. Two strategic archetypes dominate: polymer-embedded photovoltaic integrators and ultra-aerodynamic platform optimizers. Capacity expansion in solid-state battery fabrication and strategic partnerships for automotive-grade PV certification constitute the dominant competitive moves.
Among the solar-native specialists, Sono Motors and Lightyear occupy positions as archetype anchors for polymer substrate and aerodynamic optimization approaches respectively. Toyota Motor Corporation represents the incumbent hybrid pathway, leveraging existing manufacturing scale to supplement rather than replace conventional powertrains. These three entities exemplify the structural division between disruptive platform engineering and incremental electrification strategies.
| Leading Market Players |
|---|
| Sono Motors |
| Lightyear |
| Aptera Motors |
| Toyota Motor Corporation |
| Ford Motor Company |
| Volkswagen |
| General Motors |
| Hyundai Motor Company |
| Mahindra |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese crystalline silicon wafer fabrication is compressing module pricing and forcing Western vehicle assemblers to renegotiate long-term offtake terms or absorb tariff exposure. Thin-film photovoltaic producers in Germany and the Netherlands exploit this dislocation by positioning polymer-based automotive panels at premium tiers justified by IEC 61215 certification speed.
Pricing Analysis
Silicon-perovskite tandem cells command 40-60% premiums over conventional single-junction silicon panels while prior-generation amorphous silicon systems face accelerated obsolescence. Three-tier pricing structure across premium certified, standard automotive-grade, and economy retrofit tiers differentiates buyers by fleet scale and regulatory exposure. Cost compression in economy tiers is intensifying because Chinese wafer overcapacity floods spot markets. Last-mile logistics operators exhibit lowest price sensitivity given fuel hedge value capture, while individual consumers in subsidy-dependent markets show highest elasticity.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment and EU critical raw materials regulations constrain crystalline silicon ingot sourcing from Chinese producers. Photovoltaic cell supply concentrates in China, Vietnam, and Malaysia for wafer slicing and cell fabrication, while Germany and South Korea anchor automotive-grade module assembly. Sulfide electrolyte precursors for solid-state batteries, polymer substrates for embedded panels, and high-purity silicon feedstock constitute critical input dependencies. Single-source vulnerability in Chinese polysilicon refining creates tariff exposure risks for Western assemblers. Distribution runs through Tier 1 automotive supplier networks with direct OEM integration for polymer-embedded architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from solid-state battery capex cyclicality as fleet procurement committees consolidate vendor authority and compress pilot-to-scale timelines. Thin-film efficiency gains and subsidy framework maturation in Germany, California, and the Netherlands anchor the cyclical upswing.
For Market Incumbents: Harden supply chain resilience through backward integration into polymer substrate manufacturing or captive sulfide electrolyte refining to offset Chinese wafer concentration. Accelerate IEC 61215 automotive-grade certification investment to outpace laboratory-to-production timelines that venture-backed specialists exploit. Defensive consolidation around energy management software capabilities counters solar-native entrants' algorithmic differentiation. For New Entrants and Emerging Players: Commercial truck roof-plane deployments in Dutch and Belgian urban logistics corridors represent the most penetrable entry point given predictable fleet utilization and expansive surface area. Mid-size German automotive engineering consultancies with polymer integration expertise offer acquisition targets for rapid certification capability. Direct fleet procurement committee engagement bypasses tiered supplier hierarchies that incumbent OEMs control. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated thin-film specialists with captive automotive certification pipelines rather than pure-play solid-state battery developers facing billion-dollar fabrication facility requirements. Long-term viability hinges on charge profile alignment between solar harvesting curves and next-generation battery chemistry acceptance rates. Watch for IEC 61215 validation timeline compression as the inflection signal separating scalable platforms from laboratory-bound prototypes.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade PV Certification Acceleration | IEC 61215 validation compression enables faster pilot-to-scale transitions for fleet operators. |
| Solid-State Battery Supply Agreement | Long-term offtake contracts with sulfide electrolyte producers lock in charge acceptance compatibility. |
| Polymer Substrate Backward Integration | In-house production of embedded solar body panels reduces tiered supplier dependency and margin leakage. |
| Vehicle-to-Grid Infrastructure Partnership | Bidirectional charging deployment with California utilities monetizes solar harvest during peak demand periods. |
| Energy Management Software Acquisition | Algorithmic differentiation in power routing between propulsion and thermal loads creates switching costs. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement directors, fleet operations managers, and photovoltaic module certification specialists and refined through secondary validation. Primary fieldwork combined structured interviews with aftermarket distributors and dealership operations heads across German, Dutch, and California logistics hubs. Secondary sources included vehicle production databases, IHS Markit registration data, EPA compliance filings, and EU Green Deal implementation trackers. Bottom-up unit economics for fleet operators were triangulated against top-down market sizing from subsidy allocation disclosures.
Demand-supply balance modeling across the analysis window integrated vehicle class segmentation, propulsion architecture differentiation, and regional regulatory cluster variations. CAGRs were derived from installed base accumulation curves and replacement cycle dynamics rather than extrapolated shipment growth. Forecast inputs incorporated thin-film efficiency improvement trajectories, solid-state battery manufacturing yield assumptions, and subsidy framework sunset provisions without year-specific calibration.
Macroeconomic conditions sit as an overlay; deviation in fleet operator capital expenditure cycles, petroleum price volatility, or Chinese export license restrictions would shift the trajectory. Forecasts reflect documented assumptions regarding IEC certification timeline compression and polymer substrate manufacturing yield maturation. Material shifts in EU F-Gas Regulation enforcement severity or US IRA credit qualification thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
GCC Electric Vehicle Market
Electric Vehicles
Electric Vehicle Communication Controller Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Solar E-Bike Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Speed Pedelec E-Bike Market