
 Automotive Augmented Reality (AR) HUD System Market | 2026-2036
Automotive Augmented Reality (AR) HUD System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Augmented Reality (AR) HUD System Market Insights
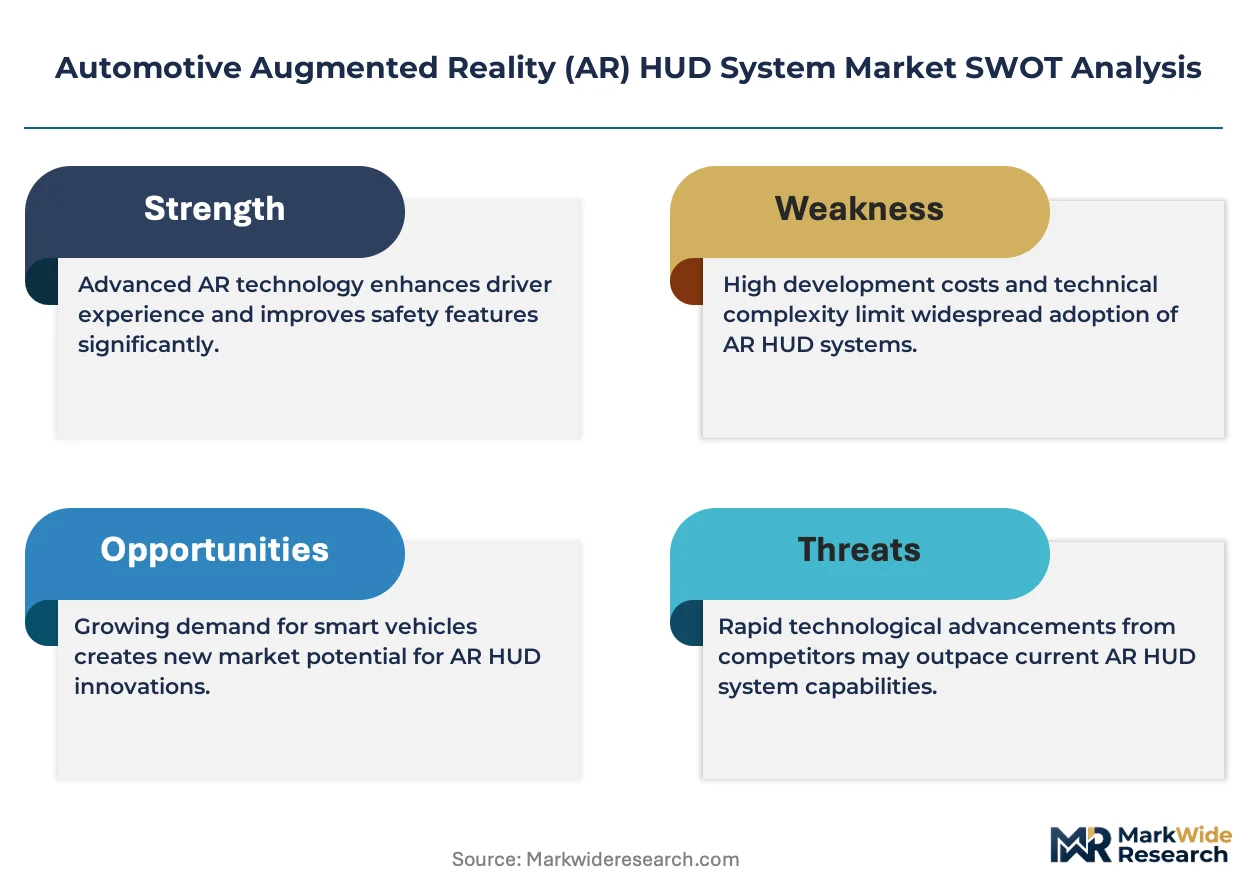
Asset-light leasing models for AR HUD projection modules are reshaping competitive entry barriers for Tier-1 suppliers. Continental AG leverages captive semiconductor partnerships to sustain display engine supply security. Panasonic Connect anchors its position through laser-based projection specialization. Robert Bosch GmbH competes across integrated sensor-fusion architectures that merge camera feeds with HUD overlays.
An automotive augmented reality head-up display system projects real-time vehicle, navigation, and environmental data onto the windshield within the driver's natural line of sight, typically employing waveguide combiners or free-form mirrors to achieve virtual image distances exceeding seven meters. The system reduces cognitive load by eliminating focal plane switching between road and instrument panel. Laser-based technology dominates premium factory installations due to superior brightness and thermal efficiency. OEM end users command the largest value pool as safety and navigation applications migrate from optional to standard fitment. LCD and OLED segments face margin compression from LED alternatives in mid-tier vehicle programs.
NHTSA guidelines on driver visual distraction govern field-of-view and luminance limits for AR HUD imagery in the United States. Euro NCAP assessment protocols reward vehicles with active safety information projection, indirectly mandating capability upgrades. Japan's METI promotes automotive electronics standardization through JIS frameworks that facilitate cross-platform HUD module interoperability. Stakeholders must monitor regulatory divergence between photometric standards and active safety credit systems when allocating R&D across regional product variants.
Market Dynamics
Factory-installed AR HUD adoption is accelerating as premium passenger vehicle OEMs migrate the technology from optional to standard equipment, compressing supplier margins while expanding addressable volume pools across Tier-1 electronics clusters.
Growth Catalysts
- Euro NCAP Assessment Protocols:Active safety information projection now contributes to vehicle safety ratings, creating indirect regulatory pull for AR HUD capability upgrades across European OEM programs.
- Laser-Based Projection Technology:Superior brightness and thermal efficiency in laser systems is displacing LCD alternatives in premium factory installations, opening volume expansion in mid-tier vehicle segments.
- Germany:Concentrated automotive electronics manufacturing clusters around Stuttgart and Munich enable rapid prototyping cycles and integrated ADAS-HUD development partnerships.
Market Restraints
- Semiconductor Supply Concentration:Display engine chipsets depend on captive foundry relationships concentrated in East Asian manufacturing zones, exposing Tier-1 suppliers to allocation volatility.
- NHTSA Visual Distraction Guidelines:Field-of-view and luminance limits for projected imagery constrain design freedom and extend validation timelines for US-bound vehicle programs.
- Waveguide Combiner Cost Structure:Precision optical component fabrication requires capital-intensive cleanroom facilities, elevating breakeven volumes for new market entrants.
Strategic Opportunities
- Japan's METI Standardization Framework:JIS interoperability protocols facilitate cross-platform HUD module design, reducing regional variant engineering costs for global OEMs.
- Asset-Light Leasing Models:Projection module leasing structures are lowering competitive entry barriers for mid-tier suppliers seeking factory-installation contracts.
- Sensor-Fusion Convergence:Integration of camera feeds with HUD overlays creates new value pools in integrated architecture supply, rewarding suppliers with software-defined capabilities.
Industry Challenges
- Photometric Calibration Expertise:Shortage of optical engineers capable of tuning virtual image distances exceeding seven meters is constraining R&D throughput at display engine specialists.
- Multi-Regulatory Certification Overhead:Divergence between NHTSA photometric standards and Euro NCAP active safety credit systems forces parallel validation tracks, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Augmented Reality (AR) HUD System Market |
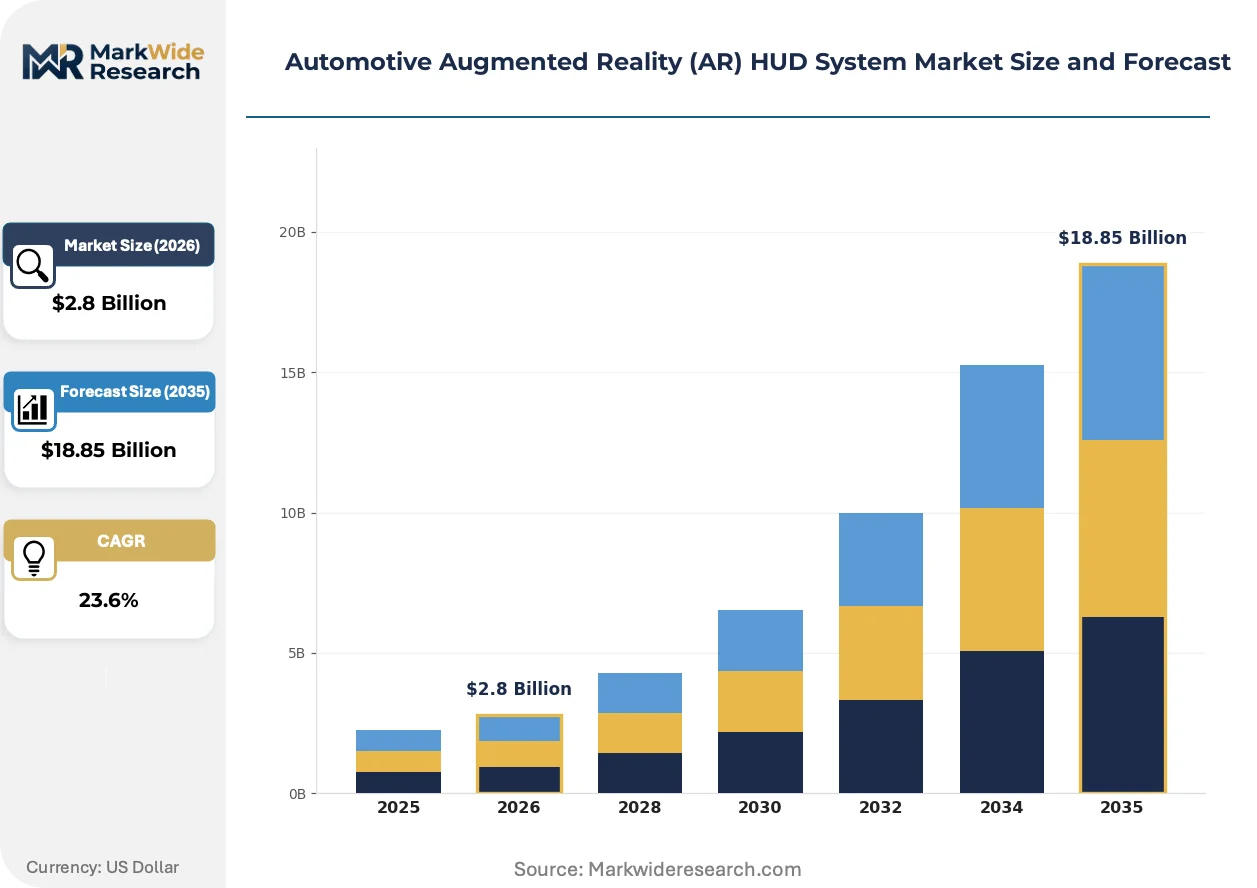
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $18.85 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Laser-Based, LED, LCD, OLED Application: Navigation, Safety, Entertainment, Driver Assistance End User: OEMs, Tier-1 Suppliers, Fleet Operators, Aftermarket Providers Installation: Factory Installed, Retrofit, Custom Installation, Integrated Solutions |
| Companies Covered | Continental AG, Panasonic Connect, Robert Bosch GmbH, Visteon Corporation, DENSO Corporation, Nippon Seiki Co. Ltd., HARMAN International, LG Electronics, WayRay AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Augmented Reality (AR) HUD System Market Trends and Innovations
Waveguide combiner architectures and laser projection engines are compressing hardware footprints while software-defined overlay pipelines enable real-time sensor fusion, fundamentally restructuring how Tier-1 suppliers compete for factory-installation contracts.
Laser-based projection systems achieve virtual image distances exceeding seven meters with superior thermal efficiency and daylight readability. Premium passenger vehicle OEMs are adopting these systems at standard-fitment pace across flagship sedans and electric vehicle platforms. Conventional LCD and OLED display engines is rendering obsolete in factory-installed applications where brightness and power budgets are non-negotiable.
Japan's METI promotes automotive electronics standardization through JIS frameworks that facilitate cross-platform HUD module interoperability. This regulatory architecture reduces engineering overhead for global OEMs operating multi-regional vehicle programs. Suppliers with JIS-certified modules capture preferred supplier status in Japanese and affiliated OEM supply chains.
Fleet procurement teams at premium OEMs now specify outcome-based performance contracts tied to active safety information projection reliability metrics. Traditional component-supply agreements with unit-price structures are losing share to service-level arrangements in North American and European fleet negotiations. Germany and Japan exhibit the fastest migration toward integrated sensor-fusion procurement models bundling HUD hardware with software maintenance.
Automotive Augmented Reality (AR) HUD System Market Segmentation
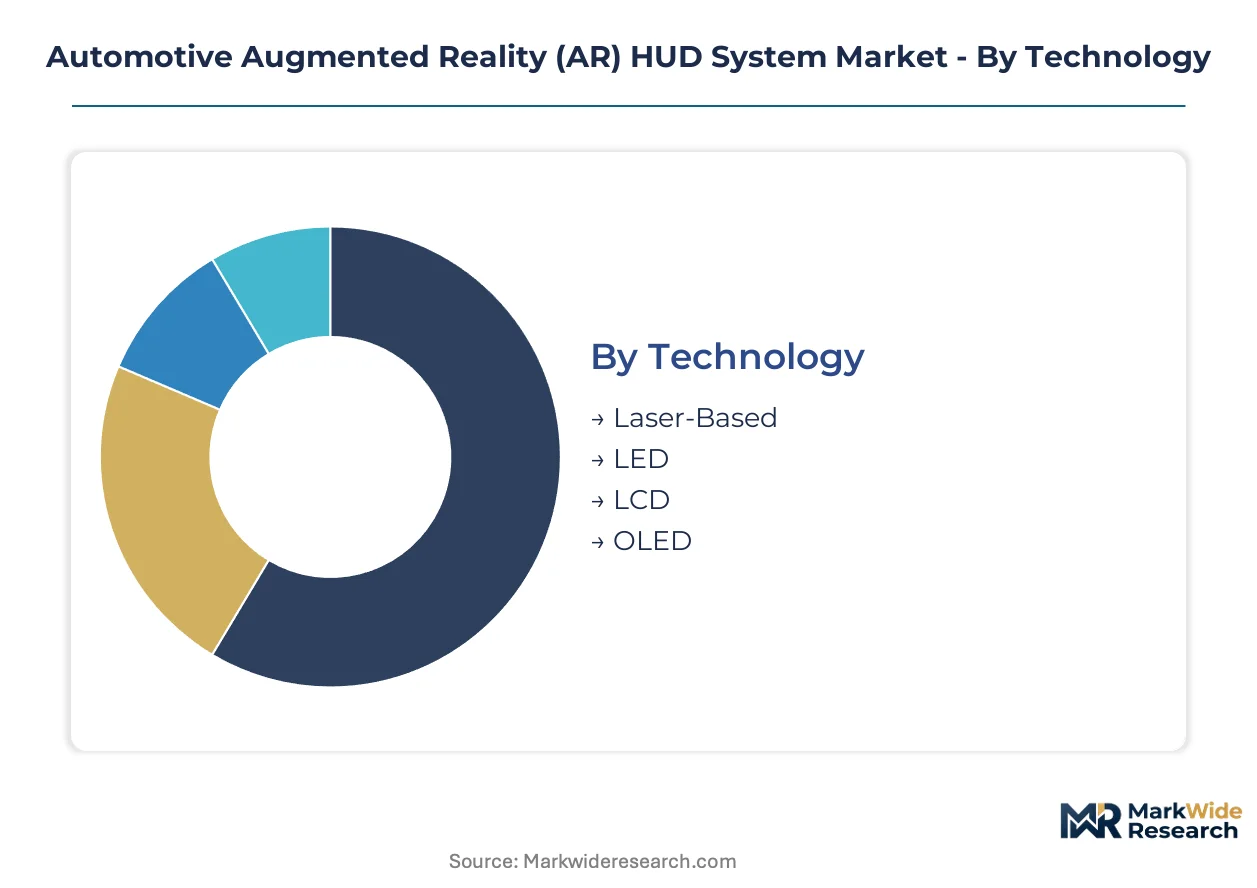
AR HUD market segmentation reveals how technology choices, installation channels, and end-user procurement patterns fragment value capture across the supply chain. Understanding these divisions exposes where pricing power concentrates and where commodification pressures emerge.
Technology:
Display engine architectures span a performance-cost spectrum from premium laser systems to legacy LCD alternatives.
- Laser-Based:Diode-pumped solid-state lasers deliver virtual image distances exceeding seven meters with superior luminance and thermal efficiency. Demand concentrates in German premium OEM programs where NHTSA photometric compliance and Euro NCAP safety ratings drive specification upgrades.
- LED:Phosphor-converted LED engines balance brightness against cost in mid-tier vehicle platforms. Volume expansion accelerates as Japanese OEMs migrate this technology from optional to standard fitment across mass-market electric vehicle lines.
- LCD:Thin-film transistor liquid crystal displays face margin compression from solid-state alternatives in factory-installed applications.
- OLED:Organic light-emitting diode panels retain niche positioning in aftermarket custom installations where contrast ratio prioritizes over daylight readability.
The dominant share belongs to laser-based systems, while LED is closing the gap fastest as mid-tier OEMs standardize AR HUD fitment.
Application:
Use-case prioritization varies by regulatory environment and OEM safety strategy.
- Safety:Collision warning overlays and pedestrian detection graphics integrate with ADAS sensor fusion. Euro NCAP assessment protocols reward active safety information projection, pulling demand toward German and Swedish OEM development centers.
- Navigation:Turn-by-turn guidance and lane-level positioning reduce cognitive load. Japanese OEMs lead integration with METI-promoted JIS standardization frameworks.
- Driver Assistance:Adaptive cruise and lane-keeping visual cues merge camera feeds with HUD imagery.
- Entertainment:Passenger-viewable content and gaming overlays occupy peripheral display zones.
Safety applications command the largest value pool, with navigation gaining share fastest as standard-fitment mandates spread.
End User:
Procurement authority shapes contract structures and margin retention.
- OEMs:Volkswagen Group, Toyota Motor, and General Motors specify outcome-based performance contracts tied to reliability metrics. Direct factory-installation negotiations compress Tier-1 margins while securing volume commitments.
- Tier-1 Suppliers:Continental AG and Robert Bosch GmbH aggregate display engine supply for multiple OEM platforms. Captive semiconductor partnerships insulate against foundry allocation volatility.
- Fleet Operators:Commercial vehicle procurement teams specify service-level arrangements bundling hardware with software maintenance.
- Aftermarket Providers:Specialty installers serve enthusiast segments with custom waveguide combiner retrofits.
OEMs retain dominant procurement authority, though Tier-1 suppliers are consolidating influence through integrated sensor-fusion architectures.
Installation:
Channel structure determines calibration requirements and warranty liability allocation.
- Factory Installed:Windshield-integrated waveguide combiners require cleanroom assembly during vehicle production. Stuttgart and Munich electronics clusters enable rapid prototyping cycles for German OEM programs.
- Integrated Solutions:ADAS-HUD bundled architectures merge camera, radar, and projection modules under single-supplier responsibility. Japanese OEMs favor this procurement model through METI-facilitated interoperability standards.
- Retrofit:Add-on projection units attach to existing windshields with reduced virtual image distance performance.
- Custom Installation:Bespoke optical path engineering serves limited-production vehicle programs.
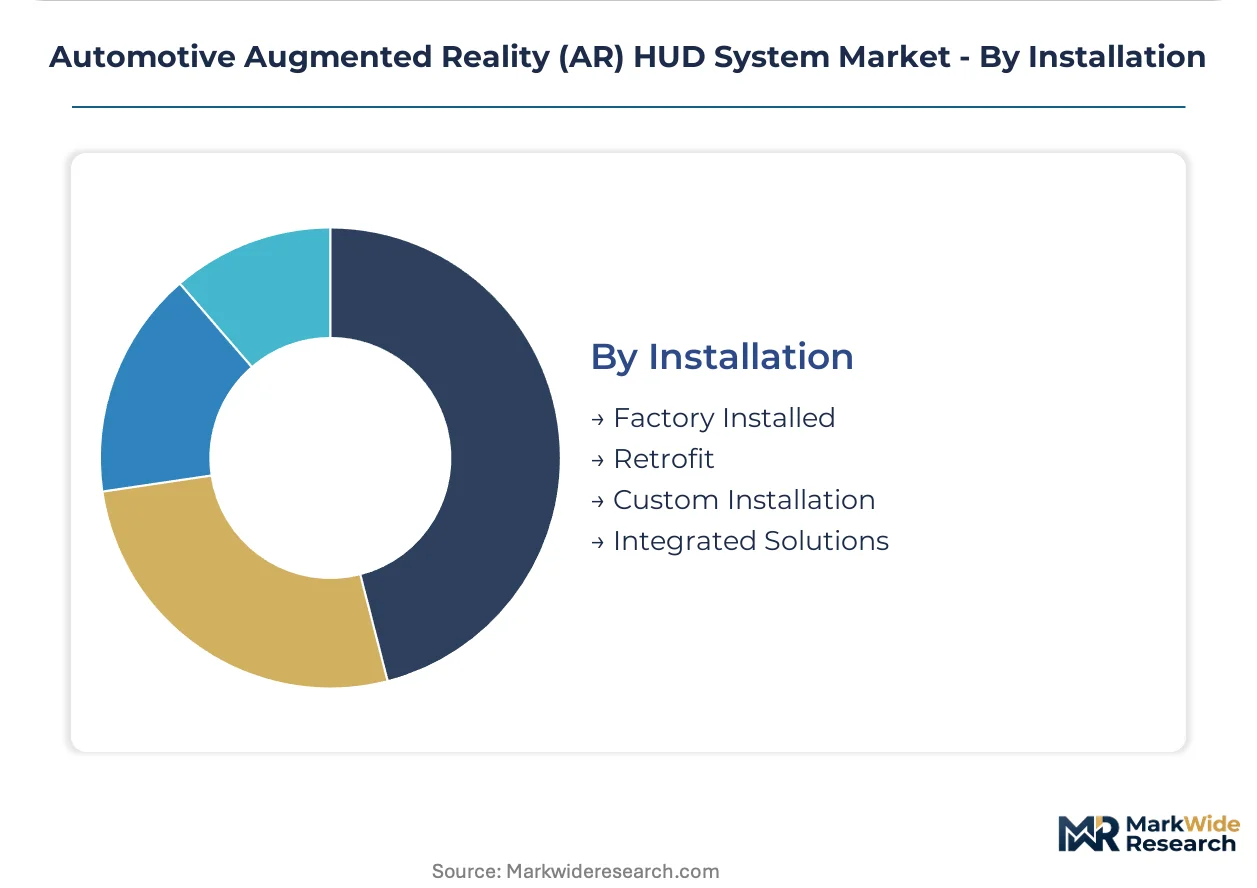
Factory installed dominates volume, while integrated solutions are expanding most quickly as OEMs consolidate electronics procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium passenger vehicle OEMs in Germany, Japan, and the United States command the dominant procurement positions for AR HUD systems, with factory-installation contracts concentrating around established automotive electronics clusters and ADAS integration capabilities.
Germany
Volkswagen Group and BMW specify laser-based AR HUD systems as standard equipment across flagship electric vehicle platforms. KBA vehicle type approval processes enforce stringent photometric compliance for projected imagery. Stuttgart and Munich electronics clusters enable rapid prototyping cycles for integrated sensor-fusion architectures.
United States
General Motors and Ford Motor Company negotiate outcome-based performance contracts tied to active safety projection reliability metrics. NHTSA visual distraction guidelines constrain field-of-view and luminance limits for HUD imagery. Michigan and California development centers anchor Tier-1 supplier engineering partnerships for ADAS-HUD convergence.
Japan
Toyota Motor and Honda Motor accelerate LED-based AR HUD standardization across mass-market electric vehicle lines. METI promotes JIS interoperability frameworks that facilitate cross-platform module design. Nagoya and Tokyo automotive electronics corridors concentrate display engine manufacturing and calibration expertise.
South Korea
Hyundai Motor Group and Kia Corporation integrate AR HUD systems with camera-based driver assistance architectures. The country's national automotive safety regulator aligns photometric standards with international harmonization initiatives. Seoul and Ulsan manufacturing zones host captive semiconductor partnerships for display engine supply security.
Automotive Augmented Reality (AR) HUD System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where factory-installation procurement authority concentrates among integrated electronics suppliers. The vendor base spans three strategic archetypes: semiconductor-captive display engine specialists, laser projection technology pure-plays, and sensor-fusion architecture integrators. Dominant competitive moves include strategic partnerships for foundry allocation security and portfolio diversification into software-defined overlay pipelines.
Among Germany-based automotive electronics suppliers, Continental AG and Robert Bosch GmbH exemplify the integrated architecture archetype. Panasonic Connect represents the laser projection specialization vector within Japanese industrial electronics. These three entities anchor the premium-tier supply position through captive technology control and OEM direct contracting relationships.
| Leading Market Players |
|---|
| Continental AG |
| Panasonic Connect |
| Robert Bosch GmbH |
| Visteon Corporation |
| DENSO Corporation |
| Nippon Seiki Co. Ltd. |
| HARMAN International |
| LG Electronics |
| WayRay AG |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor carries waveguide combiner assemblies and laser diode modules from East Asian foundries to German automotive electronics clusters, with freight cost volatility amplifying margin compression for mid-tier suppliers while OEM procurement teams exploit volume concentration to extract price concessions across factory-installation contracts.
Pricing Analysis
Cost-plus contracts with semiconductor raw material indexation dominate Tier-1 supplier agreements with German and Japanese OEMs. Three-tier pricing structure across premium laser systems, standard LED configurations, and economy LCD alternatives reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from OEM migration toward outcome-based performance contracts bundling hardware with software maintenance. Fleet operators exhibit highest price sensitivity, while premium passenger vehicle OEMs prioritize photometric compliance and active safety reliability over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessments for display engine chipsets and precision optical components. Manufacturing concentrates in Taiwan, South Korea, and Japan for semiconductor foundry capacity and laser diode fabrication. Waveguide combiner substrates and free-form mirror assemblies draw from German and Japanese precision optics specialists. Single-source vulnerability in captive foundry relationships for high-brightness laser engines constrains allocation security. Distribution runs through integrated Tier-1 supplier architectures bundling HUD hardware with ADAS sensor fusion modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from software-defined overlay pipelines that could displace dedicated projection hardware, requiring defensive positioning around integrated sensor-fusion architectures.
For Market Incumbents: Entrench market position through backward integration into laser diode foundry partnerships and JIS certification investment for cross-platform module interoperability. Defend against emerging pure-play software overlay specialists by controlling camera-feed fusion pipelines. Prioritize Stuttgart and Nagoya electronics cluster proximity for rapid prototyping cycles. For New Entrants and Emerging Players: Mid-tier LED-based AR HUD configurations for Japanese mass-market electric vehicle platforms represent the most penetrable entry point. Aftermarket custom installation channels for enthusiast vehicle segments offer lower capital barriers than factory-installation procurement. Pursue asset-light leasing models for projection module hardware to bypass cleanroom fabrication capital requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with undermonetized automotive optics divisions. Long-term viability hinges on software-defined capability integration rather than pure hardware manufacturing scale. Monitor Euro NCAP protocol revisions for active safety information projection as inflection indicator for regulatory pull intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | JIS-certified module interoperability reduces engineering overhead for Toyota and Honda multi-regional programs. |
| Semiconductor Supply Agreement | Captive foundry partnerships insulate Continental and Bosch against Taiwan and South Korea allocation volatility. |
| Software-Defined Vehicle Investment | Real-time sensor fusion pipelines merge camera feeds with HUD overlays for integrated architecture supply. |
| Geographic Manufacturing Footprint | Stuttgart and Munich electronics clusters enable KBA-compliant rapid prototyping for Volkswagen and BMW. |
| Charging Infrastructure Partnership | AR HUD integration with electric vehicle platform displays extends battery range visualization for German OEMs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers; and secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from automotive electronics suppliers, and NHTSA photometric compliance records. Bottom-up unit economics triangulated against top-down market sizing across technology, application, and installation segmentation dimensions.
Forecast inputs incorporated propulsion architecture evolution, content per vehicle trajectories, OEM tier procurement patterns, and regional production cluster concentration across the analysis window. CAGRs derived from modeled adoption curves for laser versus LED display engine penetration, standard-fitment migration timelines, and ADAS-HUD convergence rates. Segmentation modeling captured vehicle class, technology performance tier, and end-user procurement authority splits.
Practitioners should monitor semiconductor foundry allocation volatility, Euro NCAP protocol revisions, and NHTSA photometric standard updates for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality (XR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market