
 Drone Camera Market | 2026-2036
Drone Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Camera Market Intelligence
China's Shenzhen-Guangdong manufacturing corridor is reshaping global supply dynamics for drone imaging systems. DJI leverages its vertically integrated component ecosystem to sustain cost leadership across consumer and commercial tiers. Autel Robotics anchors its competitive stance through R&D intensity in autonomous flight algorithms. Sony competes by dominating the CMOS sensor layer that defines image quality thresholds for Tier-1 platform builders.
A drone camera integrates stabilized gimbal mechanisms with CMOS or CCD sensors, typically ranging from 12 to 200 megapixels, to capture aerial imagery from unmanned aerial vehicles for commercial, military, or recreational purposes. Multirotor platforms occupy the highest volume tier due to maneuverability advantages in close-range cinematography and inspection workflows. Thermal imaging technology is recording the fastest adoption velocity as energy utilities and emergency response agencies replace manual inspection regimes with remote sensing protocols. The commercial end-user segment controls the dominant margin pool, driven by recurring software subscriptions and fleet management contracts layered atop hardware sales.
The FAA enforces Remote ID compliance and Part 107 certification pathways that dictate product design and operator training investments across the United States. EASA's drone regulation framework and CE marking requirements govern market access throughout European member states, while China's MIIT and CAAC coordinate airspace classification and manufacturing standards for domestic producers. Stakeholders must monitor the divergence between permissive recreational frameworks and restrictive beyond-visual-line-of-sight commercial rules, as this regulatory gap will determine which technology architectures achieve scalable deployment.
Market Dynamics
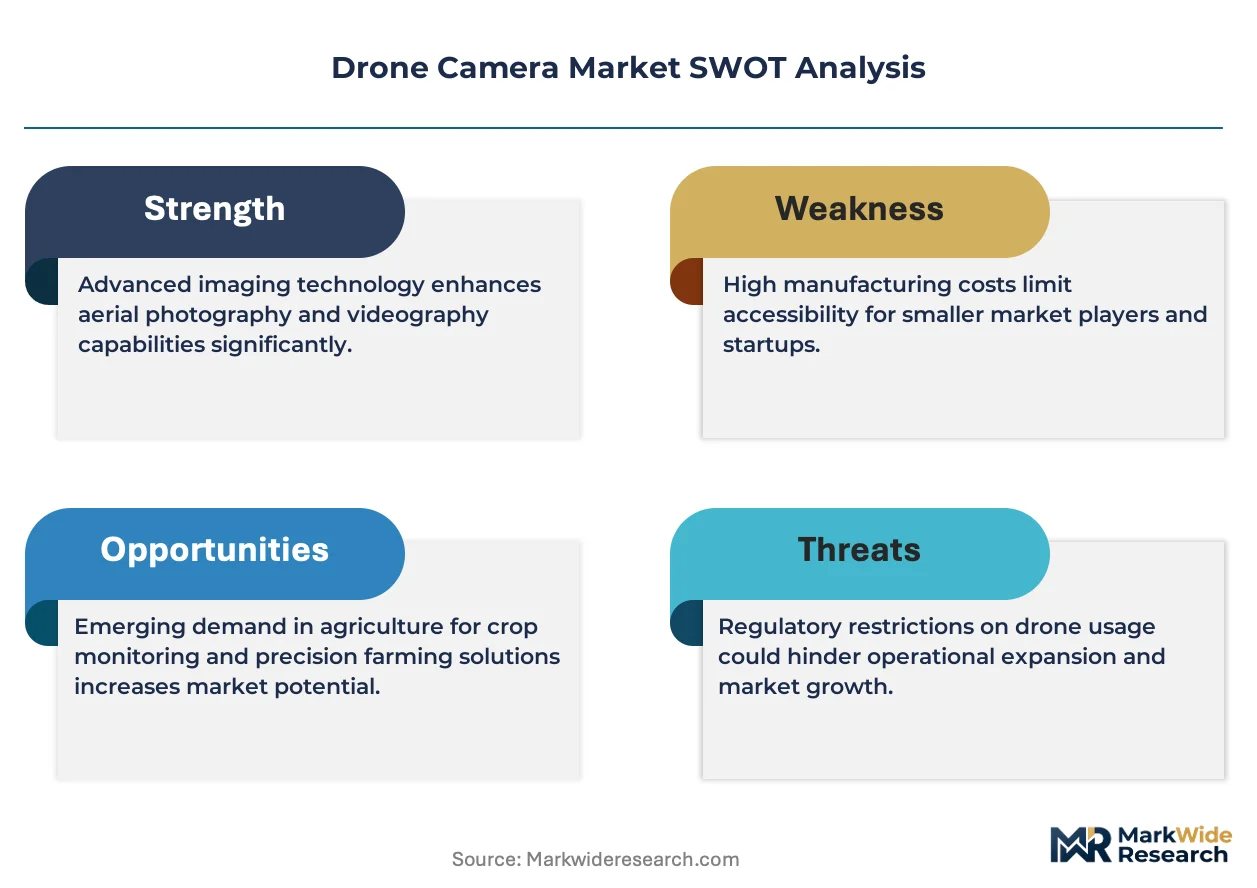
The FAA's Remote ID mandate and EASA's equivalent airspace compliance frameworks are forcing hardware redesigns and operator certification investments across commercial fleets, compressing margins for non-compliant assemblers while advantaging vertically integrated platform builders.
Growth Catalysts
- Agricultural automation:Crop monitoring and precision spraying operations across Brazil and Australia are expanding commercial UAV deployments. Farmers substitute manual inspection with thermal and multispectral imaging for yield optimization.
- Remote ID mandates:FAA regulations and EASA frameworks create standardized compliance pathways that legitimize commercial BVLOS operations. Certified operators gain access to previously restricted airspace corridors.
- Thermal sensor integration:Energy utilities and emergency response agencies replace manual infrastructure inspection with remote thermal sensing protocols. Fault detection speed improves while labor exposure to hazardous environments drops.
Market Restraints
- CMOS sensor supply concentration:Critical imaging components concentrate among Japanese and Korean semiconductor foundries. Geopolitical friction or fabrication capacity constraints propagate through Shenzhen-based assembly lines.
- BVLOS regulatory fragmentation:Divergence between permissive recreational frameworks and restrictive beyond-visual-line-of-sight commercial rules delays scalable deployment architectures in multiple jurisdictions.
- Li-ion battery chemistry limitations:Energy density constraints cap flight endurance for multirotor platforms. Payload-weight tradeoffs restrict simultaneous high-resolution imaging and extended range operations.
Strategic Opportunities
- Indian agricultural digitization:India's PLI scheme for drone manufacturing and BIS certification streamlining creates localized assembly incentives. Domestic production escapes import duty structures that inflate hardware costs.
- AI-powered autonomous flight:Convergence of computer vision algorithms with real-time obstacle avoidance enables single-operator management of multi-drone fleets. Labor productivity per pilot multiplies across inspection and mapping workflows.
- Subscription software layering:Fleet management platforms and image analytics tools generate recurring revenue atop hardware sales. Commercial end-users lock into vendor ecosystems through data processing dependencies.
Industry Challenges
- Remote pilot certification throughput:FAA Part 107 and EASA equivalent training pipelines face instructor capacity constraints. Commercial fleet expansion outpaces certified operator supply, delaying contract execution.
- Cross-border component classification:Dual-use export controls on gyro-stabilized gimbals and thermal sensors complicate procurement for non-domestic assemblers. Customs clearance timelines extend production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Camera Market |
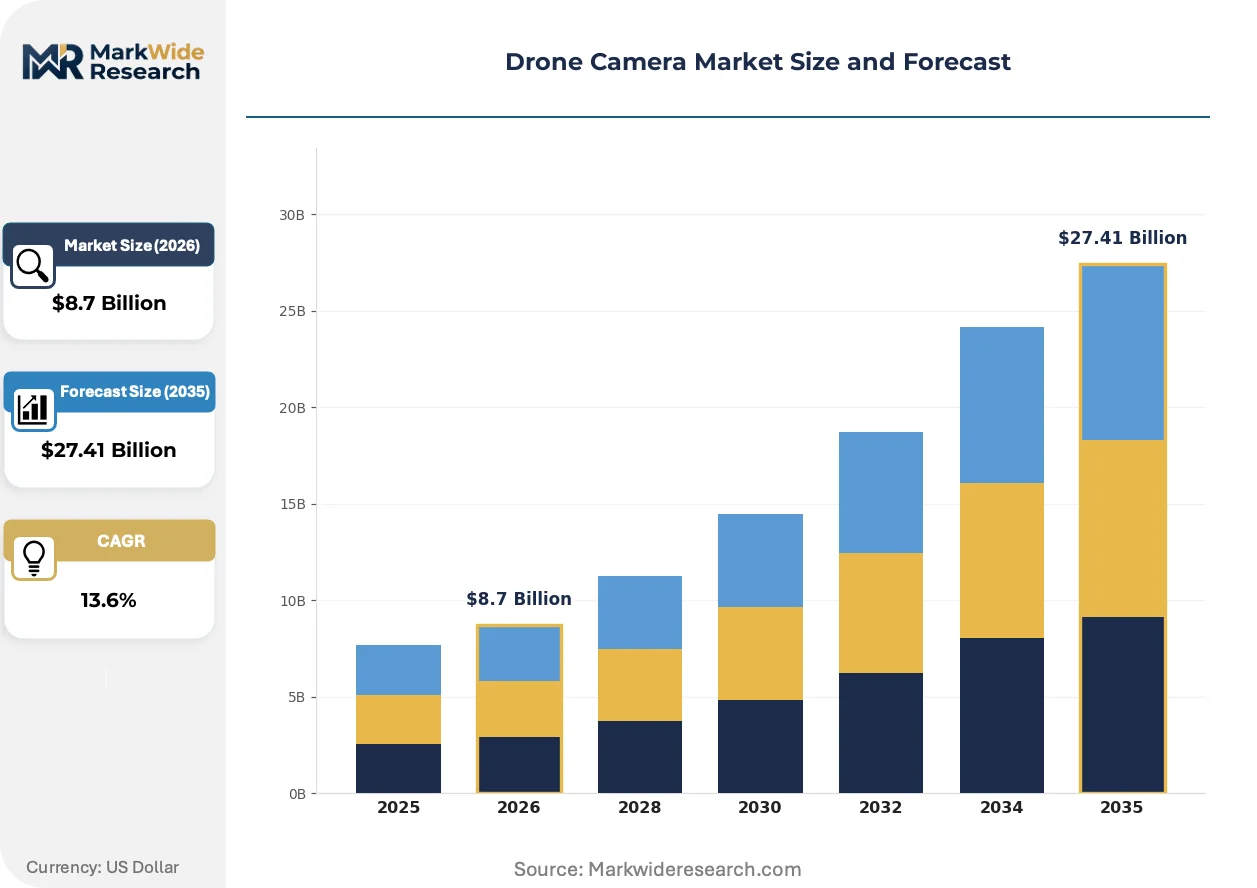
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor, Fixed-Wing, Hybrid, Single-Rotor Application: Aerial Photography, Surveillance, Mapping, Agriculture End User: Commercial, Military, Environmental, Recreational Technology: GPS, LiDAR, Optical, Thermal Imaging |
| Companies Covered | Parrot, JOUAV, DJI, Inspired Flight, Draganfly, Autel Robotics, Sony, Vantage Robotics, Skydio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Camera Market Strategic Shifts & Innovations
Computational imaging and edge AI processing are compressing the hardware-software boundary in aerial platforms, enabling real-time analytics that previously required ground-station processing. This shift reconfigures value capture toward software-centric vendors.
Hyperspectral imaging arrays are digitizing agricultural decision-making. Crop health monitoring services deploy these sensors across Brazilian soybean operations and Australian wheat belts. Agronomists receive nitrogen stress and irrigation deficit alerts within minutes of overflight, compressing response cycles that previously spanned days.
EASA's drone regulation framework and CE marking requirements are tightening conformity assessment procedures for European market entry. Hardware manufacturers must demonstrate electromagnetic compatibility and operational safety through notified body certification. Commercial operators in Germany and France prioritize pre-certified platforms to avoid airspace authorization delays.
Energy utilities are consolidating vendor relationships around integrated inspection service contracts rather than discrete hardware procurement. Transmission line operators in the United States and Spain contract outcome-based deliverables—fault detection reports, not drone units—shifting capital expenditure to operational expenditure and locking suppliers into performance-guarantee structures.
Drone Camera Market Segmentation
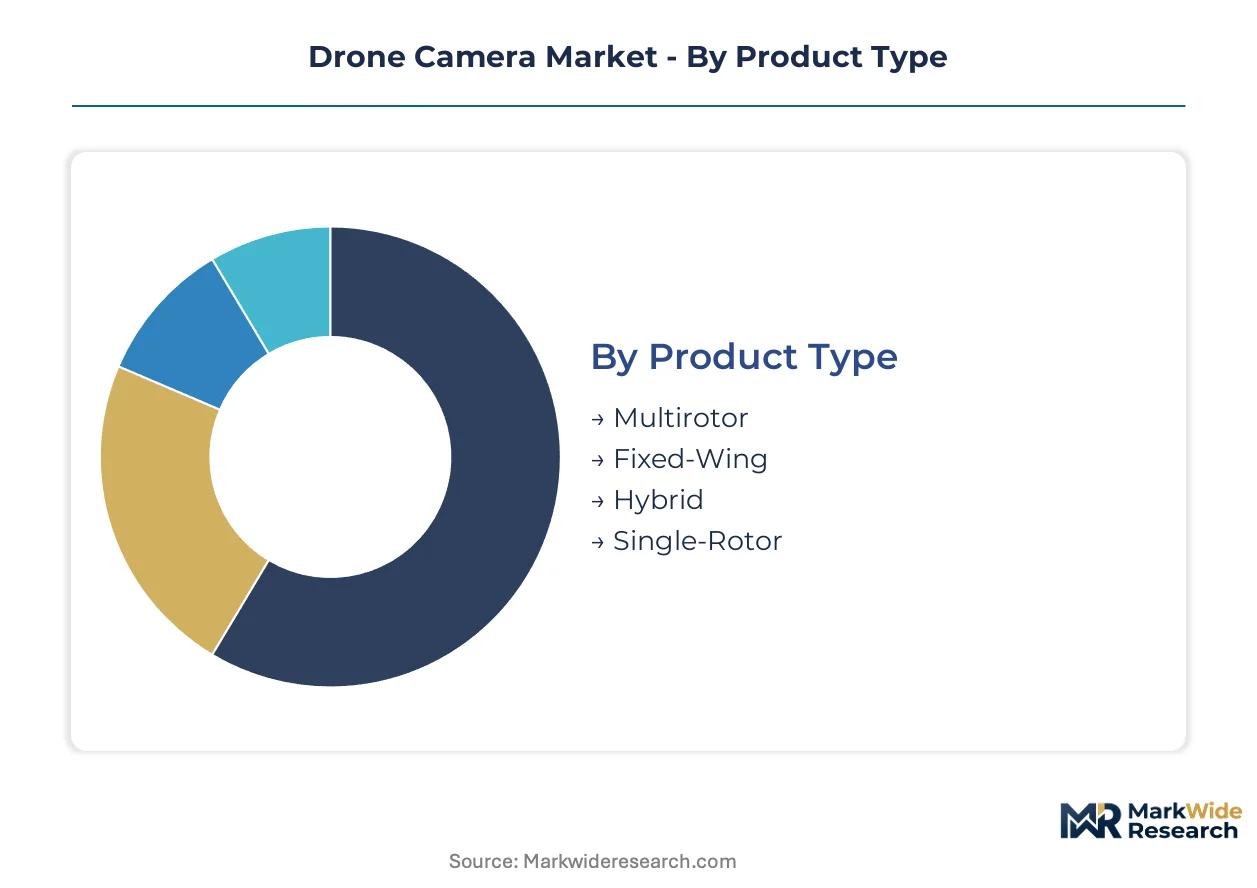
Drone camera segmentation reveals how platform architecture, imaging payload, and end-use economics split procurement decisions across radically different operational contexts. Understanding these fault lines exposes where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Mature multirotor designs dominate volume, while emerging hybrid architectures promise endurance breakthroughs that could redraw competitive maps.
- Multirotor:Four-to-eight rotor configurations deliver vertical takeoff and precision hovering for cinematography and close-range inspection. Energy utilities in Spain and media production houses in Los Angeles standardize procurement around DJI's Matrice and Inspire series for maneuverability in confined airspace.
- Fixed-Wing:Aerodynamic airframes achieve 90-minute flight durations on single battery cycles, enabling hundred-acre agricultural surveys without landing. Brazilian soybean cooperatives and Australian wheat belt operators deploy these platforms for crop health mapping across vast holdings.
- Hybrid:Tilt-rotor mechanisms combine VTOL convenience with fixed-wing efficiency, though mechanical complexity elevates unit costs and maintenance intervals.
- Single-Rotor:Helicopter-style designs carry heavier cinematography payloads and withstand wind gusts that destabilize multirotor alternatives, limiting adoption to high-budget film productions.
Multirotor retains volume leadership; hybrid holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity inspection contracts from premium creative services, with software subscription intensity varying dramatically across the divide.
- Aerial Photography:High-resolution CMOS sensors paired with three-axis gimbal stabilization capture cinematic footage for advertising agencies and streaming content producers. Los Angeles production studios and London post-production houses drive refresh cycles as 8K acquisition becomes standard.
- Surveillance:Persistent overwatch missions for border security and critical infrastructure protection demand encrypted datalinks and thermal-night vision fusion. U.S. Customs and Border Protection and Saudi perimeter security contractors specify ruggedized platforms with 30x optical zoom.
- Mapping:Photogrammetry pipelines generate centimeter-accurate elevation models for construction site planning and mining volume calculations.
- Agriculture:NDVI index mapping and targeted pesticide application reduce input costs for Brazilian cane growers and Indian cotton farmers.
Aerial photography commands premium pricing; agriculture shows the fastest software attachment rates.
End User:
Customer type determines procurement modality, with military buyers demanding hardened supply chains and recreational purchasers prioritizing retail accessibility.
- Commercial:Enterprise fleet operators bundle hardware with SaaS analytics platforms, locking customers into recurring revenue structures. German industrial inspection firms and Japanese construction conglomerates negotiate multi-year service contracts with guaranteed uptime SLAs.
- Military:ISR missions and tactical resupply require encrypted communications, jam-resistant navigation, and ITAR-compliant component sourcing. U.S. Special Operations Command and Israeli Defense Forces procurement offices vet supply chains for foreign component exposure.
- Environmental:Conservation NGOs and forestry departments track wildlife migration and illegal logging with low-acoustic-signature electric platforms.
- Recreational:Consumer hobbyists purchase through retail channels with minimal training requirements, though FAA Part 107 compliance increasingly filters casual buyers toward certified instruction pathways.
Commercial captures dominant margin pools; environmental applications are expanding most quickly as carbon credit verification demands aerial monitoring.
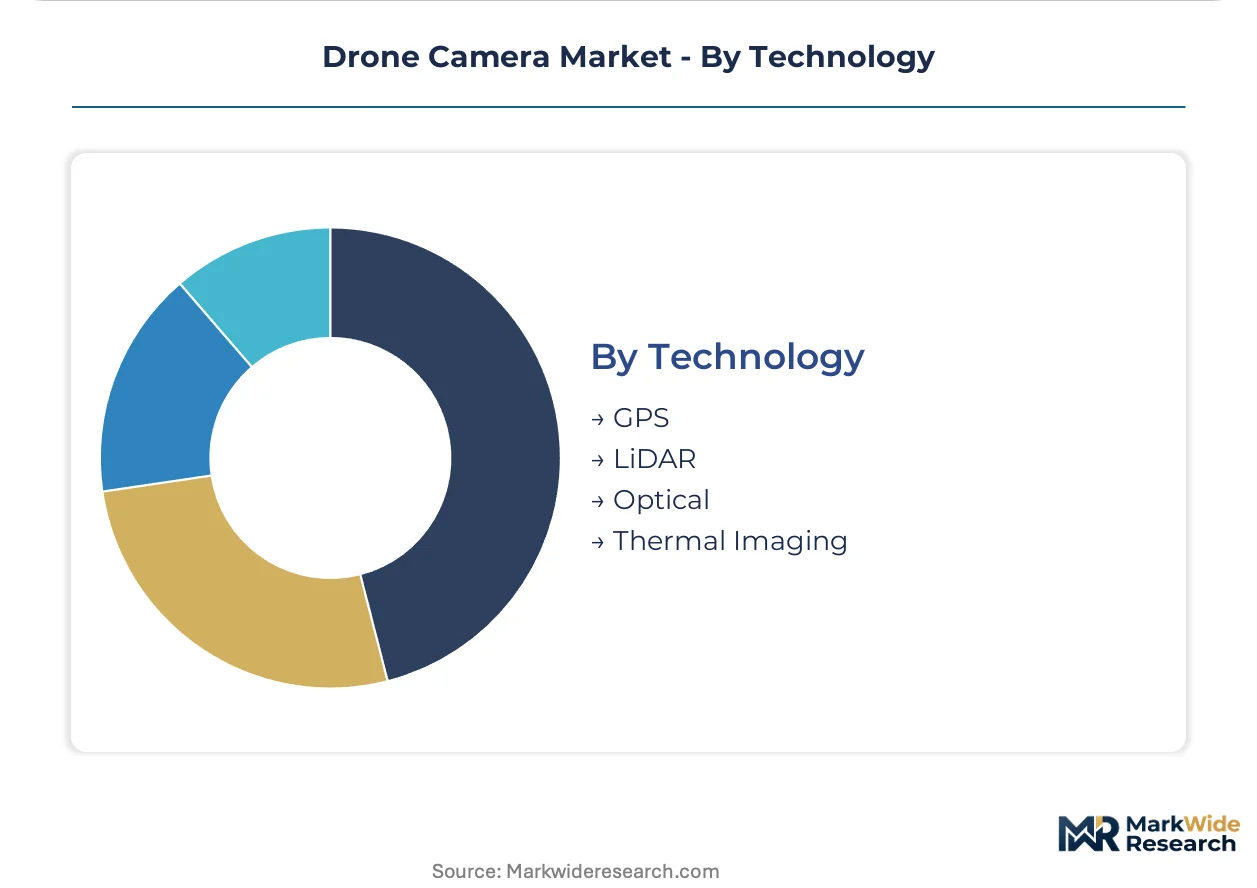
Technology:
Supply concentration in sensor layers creates divergent margin structures, with semiconductor-dependent modalities facing cost volatility.
- GPS:Multi-constellation receivers integrating GPS, GLONASS, and BeiDou signals enable centimeter-level positioning for surveying grids. South Korean cadastral authorities and Dutch land registry offices mandate redundant satellite coverage for legal boundary documentation.
- LiDAR:Pulsed laser arrays penetrate forest canopy to generate bare-earth elevation models, though solid-state sensor costs constrain adoption outside mining and utility corridor planning.
- Optical:Visible-spectrum CMOS and CCD sensors dominate unit economics, with Sony's Exmor R stack defining image quality benchmarks for Tier-1 assemblers.
- Thermal Imaging:Uncooled microbolometer arrays detect heat signatures for electrical fault diagnosis and search-and-rescue operations, with FLIR and BAE Systems controlling critical detector supply.
Optical retains volume leadership; thermal imaging gains share fastest as utility inspection automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication clusters in Shenzhen and Guangzhou control imaging supply chains for platform assemblers worldwide. Demand fragmentation across operational use cases—agriculture, energy inspection, cinematography—pulls finished systems toward distinct regional deployment patterns. Regulatory divergence between permissive recreational frameworks and restrictive commercial BVLOS rules shapes where scalable architectures achieve market penetration.
United States
Energy utilities in Texas and California consolidate vendor relationships around integrated inspection service contracts rather than discrete hardware procurement. The FAA enforces Remote ID compliance and Part 107 certification pathways that dictate product design and operator training investments. Transmission line operators in the Southwest contract outcome-based deliverables—fault detection reports, not drone units—shifting capital expenditure to operational expenditure.
China
Domestic demand concentrates in the Guangdong manufacturing corridor where Shenzhen-based assemblers control critical portions of the imaging supply chain. MIIT and CAAC coordinate airspace classification and manufacturing standards for domestic producers. Guangzhou and Shenzhen clusters leverage vertically integrated component ecosystems to sustain cost leadership across consumer and commercial tiers.
Germany
Industrial inspection firms and construction conglomerates negotiate multi-year service contracts with guaranteed uptime SLAs. EASA's drone regulation framework and CE marking requirements govern market access throughout European member states. Bavaria-based operators prioritize pre-certified platforms to avoid airspace authorization delays.
Brazil
Soybean cooperatives and cane growers deploy fixed-wing platforms for crop health mapping across vast holdings. ANVISA and the national civil aviation authority coordinate airspace access for agricultural spraying operations. São Paulo state anchors fleet expansion as farmers substitute manual inspection with thermal and multispectral imaging for yield optimization.
Australia
Wheat belt operators expand commercial UAV deployments for precision spraying and crop monitoring. The Civil Aviation Safety Authority mandates operator certification and airspace compliance for beyond-visual-line-of-sight operations. Queensland and New South Wales agricultural zones drive thermal sensor integration as energy utilities replace manual infrastructure inspection with remote sensing protocols.
Drone Camera Market Key Industry Players
Vertically integrated platform builders and specialized component suppliers split the market into contrasting value-capture models. Consolidation pressure favors assemblers with captive supply of stabilized gimbals and imaging sensors, while fragmentation persists among software analytics vendors and regional service contractors. Two archetypes dominate: Shenzhen-based hardware integrators leveraging component ecosystem control, and Tier-1 sensor houses dominating the CMOS layer that defines image quality thresholds. Competitive moves concentrate on backward integration into semiconductor supply and geographic expansion through localized assembly incentives.
Among Chinese hardware integrators, DJI and Autel Robotics exemplify the vertically integrated archetype, with Shenzhen headquarters signaling proximity to component clusters. Parrot represents the European specialist tier, its Paris-based structure reflecting a regional alternative to Asia-Pacific supply concentration. Sony anchors the sensor-layer segment, with Japanese corporate form indicating dominance in CMOS technology that Tier-1 platform builders require.
| Leading Market Players |
|---|
| Parrot |
| JOUAV |
| DJI |
| Inspired Flight |
| Draganfly |
| Autel Robotics |
| Sony |
| Vantage Robotics |
| Skydio |
| Others |
Cost & Logistics Intelligence
Japan's Sony and South Korean semiconductor foundries control CMOS sensor supply, anchoring margin capture at the imaging layer while Shenzhen-based assemblers compete on integration efficiency downstream.
Pricing Analysis
FAA Remote ID mandates and EASA CE marking requirements dictate the pricing tier structure across commercial drone camera procurement. Certification-grade platforms command premium positioning against uncertified recreational alternatives. Pricing stratifies across FAA Part 107-compliant systems, industrial-grade units with thermal fusion, and consumer hobbyist tiers. Cost compression in recreational segments intensifies as Shenzhen manufacturers exploit component ecosystem density. Agricultural cooperatives in Brazil exhibit highest price sensitivity; military ISR contractors show lowest.
Supply Chain Analysis
Dual-use export controls on gyro-stabilized gimbals and thermal microbolometers restrict component flows to non-domestic assemblers, complicating procurement timelines. Critical imaging inputs concentrate in Japan, South Korea, and China's Guangdong corridor. Raw material dependencies span rare-earth magnets for gimbal motors, lithium-ion cells for power systems, and germanium substrates for thermal detectors. Single-source vulnerability in uncooled detector supply elevates risk exposure. Distribution runs through OEM direct channels for enterprise fleets and retail electronics chains for consumer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified pilot throughput bottlenecks and ITAR-compliant component sourcing constraints create acute capability scarcity, favoring operators with captive training pipelines and hardened supply chains.
For Market Incumbents: Entrench market position by deepening backward integration into sensor semiconductor supply and expanding FAA-certified training academy capacity. Autonomous flight algorithm R&D investments defend against software-centric challengers. Lock enterprise customers through multi-year fleet management contracts with guaranteed uptime SLAs.
For New Entrants and Emerging Players: India's agricultural digitization under PLI scheme incentives offers the most penetrable white-space opportunity. Localized assembly escapes import duty structures inflating hardware costs for Brazilian and Australian farmers. Target state-level drone procurement programs with BIS-certified platforms and bundled agronomy analytics subscriptions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European inspection service contractors consolidating around outcome-based deliverables. Five-to-ten year viability hinges on software attachment rates and recurring revenue conversion. Monitor EASA beyond-visual-line-of-sight rule harmonization as the critical inflection signal for scalable deployment architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Semiconductor Backward Integration | Captive CMOS supply insulates margin pools from Japanese and Korean foundry concentration. |
| FAA Part 107 Training Academy Expansion | Certified pilot throughput alleviates commercial fleet scaling constraints across Texas and California utilities. |
| AI-Powered Autonomous Flight Development | Single-operator multi-drone management multiplies labor productivity in German industrial inspection workflows. |
| Indian Localized Assembly Investment | Domestic production under PLI scheme escapes import duties inflating hardware costs for agrarian buyers. |
| Subscription Software Platform Layering | Recurring analytics revenue locks German construction conglomerates into vendor ecosystems through data dependencies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial fleet managers, FAA-certified training instructors, agricultural cooperative procurement officers, and thermal sensor engineering leads. Secondary validation drew from FAA Remote ID implementation filings, EASA drone regulation updates, Brazilian ANVISA agricultural spraying registrations, and Australian Civil Aviation Safety Authority operator certification databases. Bottom-up platform shipment estimates triangulated against top-down imaging component demand forecasts.
Calibration against historical price trajectories and regulatory implementation timelines anchored projections across the analysis window. Segmentation dimensions spanned platform architecture, imaging payload technology, end-user procurement modality, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating fleet replacement cycles and software attachment rate assumptions. Thermal sensor integration velocity and BVLOS authorization expansion served as primary forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-subsidized assemblers or accelerated FAA waiver approvals would shift outcomes. Material shifts in dual-use export control enforcement or EASA commercial airspace harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Identification System Market
UAV
Global Drone Services Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Commercial Drone Market
UAV
Ultra Micro Drone Market
UAV
Europe Drones Market
UAV
Bubble Drone Market
UAV
Commercial Drone-Enabled Services Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Europe Tactical UAV Market
UAV
Enterprise Drone Management Solutions Market
UAV
Fuel Cell UAV Market
UAV
UAV Battery Market