
 Utility Drone Market | 2026-2036
Utility Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Drone Market Outlook
The gap between premium enterprise systems and commodity inspection platforms is broadening, with thermal imaging payloads and AI-powered defect detection now separating tiers. SZ DJI Technology Co Ltd leverages its manufacturing scale to dominate consumer-adjacent segments, while Lockheed Martin Corporation anchors defense-utility crossover contracts through ruggedized platforms. Parrot Drones SAS specializes in lightweight agricultural scouting units that compete on software integration rather than hardware specs.
Utility drones are unmanned aerial systems engineered for industrial infrastructure tasks, typically featuring Beyond Visual Line of Sight (BVLOS) capability, IP-rated weather sealing, and interchangeable payloads including LiDAR, thermal cameras, and gas sensors. Their primary purpose is to replace manned helicopter and ground crew inspections of power lines, pipelines, and telecommunications towers with faster, safer data collection. Fixed-wing platforms lead in corridor-mapping missions for energy utilities due to endurance advantages, while multi-rotor systems capture the maintenance segment where hovering precision matters. Autonomous technology represents the fastest-growing category as utilities seek to eliminate pilot costs and enable scheduled repeat surveys without human scheduling constraints.
FAA Part 107 and BVLOS waiver frameworks shape United States market access by dictating where and how utilities can operate, while EASA drone regulations in Europe mandate specific safety management systems for critical infrastructure flights. ISO 21384-3 provides international baseline standards for commercial drone operations that insurers and procurement departments reference when qualifying vendors. Stakeholders must monitor which regulatory bodies approve fully autonomous flights without ground observers, as this permission will determine where capital shifts first.
Market Dynamics
The transition from pilot-dependent operations to fully autonomous Beyond Visual Line of Sight (BVLOS) flight is compressing labor costs and expanding inspection frequency for power utilities. This shift is redistributing value from service providers to equipment vendors capable of certifying self-navigating platforms.
Growth Catalysts
- FAA Part 107 waivers:United States utilities secure expanded operational airspace for transmission corridor surveys, accelerating fleet deployment timelines without full pilot certification requirements.
- Storm recovery operations:Post-disaster infrastructure assessment creates surge demand for rapid-deployment drone units capable of accessing damaged terrain before ground crews.
- AI-powered defect detection:Machine learning algorithms trained on thermal and visual datasets reduce false-positive rates in corrosion identification, improving maintenance scheduling precision.
Market Restraints
- LiDAR sensor cost volatility:Premium navigation payloads remain concentrated among Japanese and German component suppliers, creating input price instability for mid-tier platform manufacturers.
- Battery energy density limitations:Lithium-polymer chemistry constraints cap multi-rotor flight endurance below forty-five minutes, forcing frequent swap cycles that erode labor savings.
- EASA safety management mandates:European critical infrastructure operators must document operational risk assessments for each flight category, extending procurement approval timelines.
Strategic Opportunities
- Rural electrification corridors:India's grid expansion programs under CEA guidelines create demand for cost-effective inspection platforms suited to low-density transmission networks.
- Pipeline methane detection:Converging gas sensor miniaturization with BVLOS autonomy enables continuous emissions monitoring contracts previously requiring manned aircraft.
- Subscription-based fleet services:Utilities in Texas and California shift from capital procurement to per-mile inspection pricing, opening recurring revenue models for equipment-as-a-service providers.
Industry Challenges
- Autonomous systems engineering talent:Shortage of flight control software developers with FAA certification experience delays product roadmaps for domestic platform vendors.
- ISO 21384-3 compliance timelines:Commercial operators face twelve-to-eighteen-month validation periods for international insurance qualification, restricting cross-border contract mobility.
- Legacy SCADA integration:Drone data streams require middleware development to interface with decades-old utility asset management databases, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Drone Market |
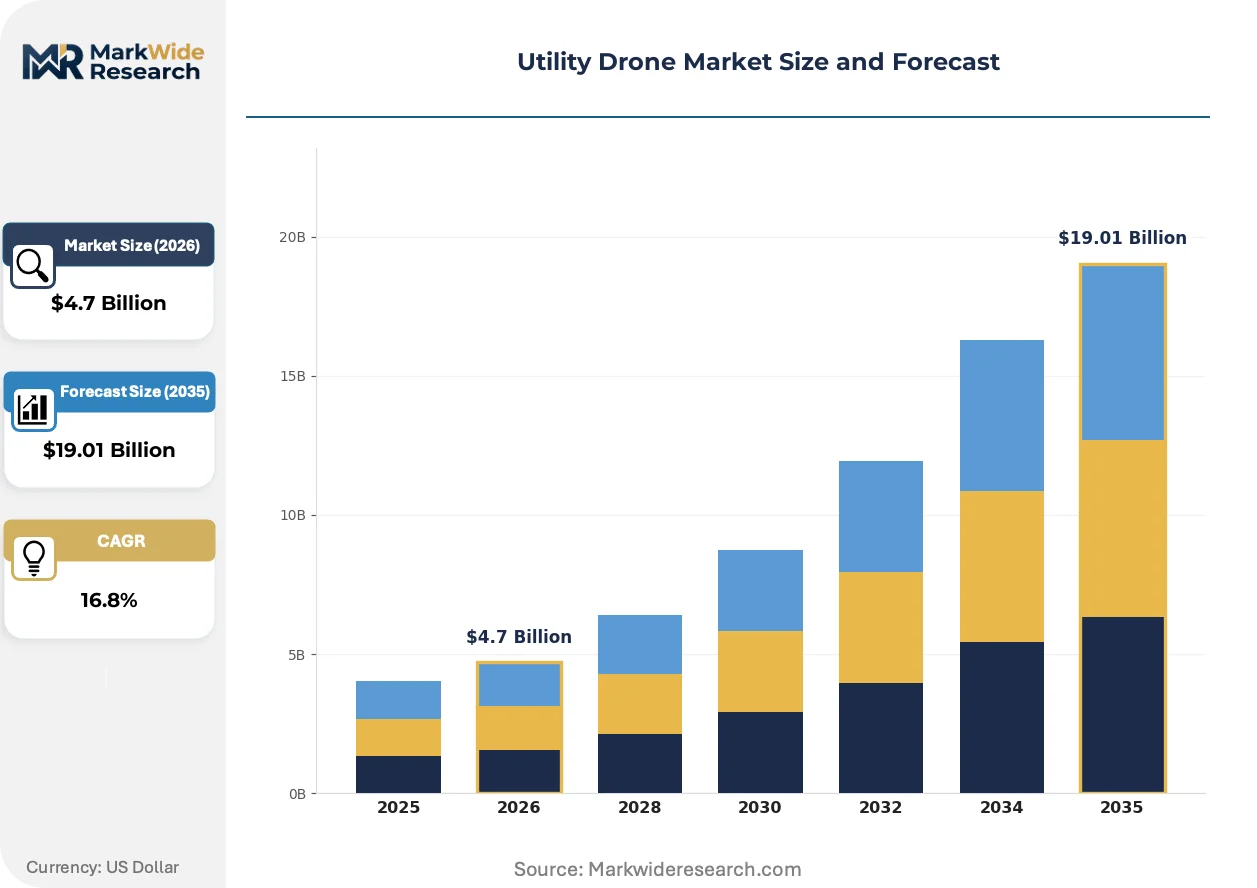
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Inspection, Surveillance, Delivery, Maintenance End User: Agriculture, Energy, Construction, Telecommunications Technology: Fixed-Wing, Multi-Rotor, Hybrid, Autonomous Payload Capacity: Lightweight, Medium, Heavyweight, Others |
| Companies Covered | SZ DJI Technology Co Ltd, Lockheed Martin Corporation, Parrot Drones SAS, Yuneec International Co Ltd, Delair SAS, Terra Drone Corp, PrecisionHawk Inc, Kespry Inc, Power Drone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Drone Market Strategic Shifts
Edge computing architectures are relocating processing power from ground stations to airborne payloads, enabling real-time decision-making without persistent datalinks. This architectural shift is altering hardware specifications and vendor competitive positioning across inspection service tiers.
Computer vision chipsets are integrating directly into gimbal-stabilized camera modules, allowing onboard classification of conductor anomalies without transmitting raw footage to cloud servers. Utilities in Arizona and Florida deploy these units for wildfire-risk vegetation encroachment surveys where bandwidth constraints limit satellite relay dependency. The technology is integrating thermal and RGB pipelines into unified threat-scoring algorithms that prioritize maintenance dispatch.
EU AI Act risk classification rules are mandating human oversight documentation for autonomous systems operating near critical infrastructure. German and French grid operators now require explainability logs for defect detection algorithms, forcing software vendors to retrofit black-box neural networks with interpretable decision trees. This regulatory pressure is segmenting the vendor base between compliance-ready enterprise platforms and stripped-down regional alternatives.
Consolidated procurement by multi-state utility holding companies is displacing fragmented regional purchasing. Duke Energy and Southern California Edison now mandate interoperable data formats across subsidiary fleets, pressuring smaller drone service providers toward standardized reporting platforms. This concentration is visible most acutely in the southeastern United States, where parent-company IT integration teams override local operations preferences.
Utility Drone Market Segmentation
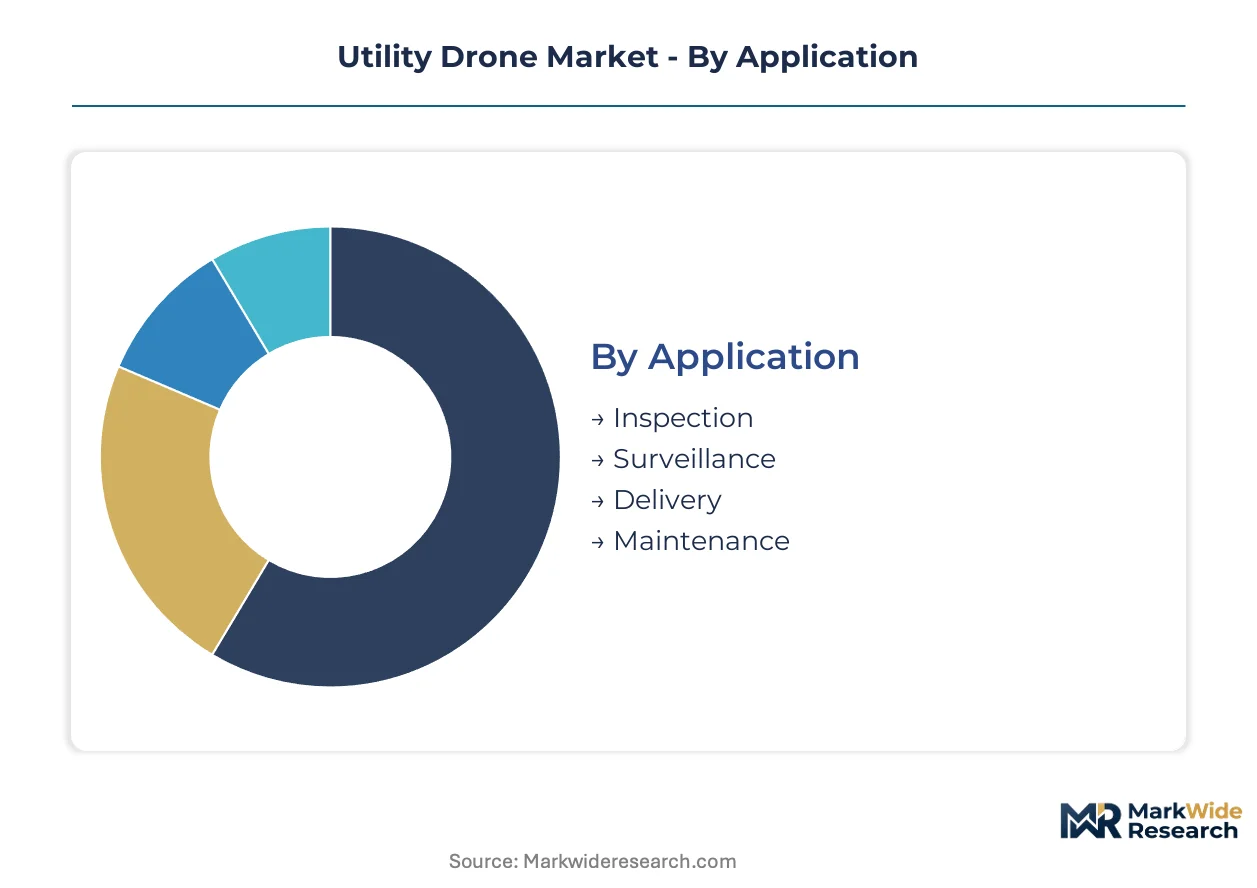
Utility drone procurement patterns diverge sharply between capital-intensive energy utilities seeking BVLOS-certified platforms and agricultural operators prioritizing payload flexibility over endurance. Understanding these segment boundaries clarifies where technology investments concentrate and which certification pathways unlock scalable deployment.
Application:
Operational mission type dictates payload configuration, flight duration requirements, and regulatory complexity for buyers.
- Inspection:Thermal imaging and LiDAR-equipped platforms dominate transmission line and pipeline surveys. United States power utilities under FAA Part 107 waivers drive fleet standardization around automated defect detection workflows.
- Surveillance:Perimeter monitoring and security overwatch applications favor multi-rotor systems with persistent loiter capability. Critical infrastructure operators in Texas and California prioritize encrypted datalinks and real-time video streaming over sensor diversity.
- Delivery:Spare parts transport to remote substations and offshore platforms remains nascent, constrained by payload-weight regulations and battery range limitations.
- Maintenance:Contact-based tasks including conductor cleaning and vegetation trimming require precision hovering and robotic arm integration, limiting adoption to specialized service providers.
Inspection leads volumes today; surveillance is gaining share fastest.
End User:
Industry verticals separate buyers by inspection frequency, terrain complexity, and tolerance for autonomous operation.
- Energy:Electric utilities and oil & gas operators deploy fixed-wing corridors for transmission mapping and methane detection. Storm recovery mandates in the southeastern United States accelerate replacement of manned helicopter surveys.
- Agriculture:Crop scouting and irrigation monitoring favor lightweight multi-rotor units with multispectral cameras. Large-scale farming cooperatives in the Midwest integrate drone data with precision agriculture platforms.
- Construction:Site progress monitoring and earthworks volume calculation demand photogrammetry-grade imaging. Heavy civil contractors specify dust-resistant IP ratings for active construction environments.
- Telecommunications:Tower climbing replacement drives demand for compact units capable of close-proximity antenna inspection. Cell tower operators in mountainous terrain prioritize wind resistance and GPS-denied navigation.
Energy commands the largest installed base; agriculture shows the steepest expansion trajectory.
Technology:
Platform architecture determines range, payload flexibility, and pilot certification requirements for mission planners.
- Fixed-Wing:Extended endurance platforms with 90-minute-plus flight times dominate linear infrastructure mapping. Energy utilities favor these for BVLOS corridor surveys where landing site access is predictable.
- Multi-Rotor:Vertical takeoff and precision hovering capability capture maintenance and close-inspection segments. Telecommunications tower work and confined-space operations depend on this architecture.
- Hybrid:Convertiplane designs combining fixed-wing efficiency with multi-rotor flexibility remain limited by mechanical complexity and maintenance intervals.
- Autonomous:Self-navigating systems eliminating ground observer requirements represent the frontier of regulatory approval. Utilities in Arizona and Florida pilot these for scheduled repeat surveys.
Multi-Rotor systems anchor current procurement; Autonomous platforms are climbing the fastest.
Payload Capacity:
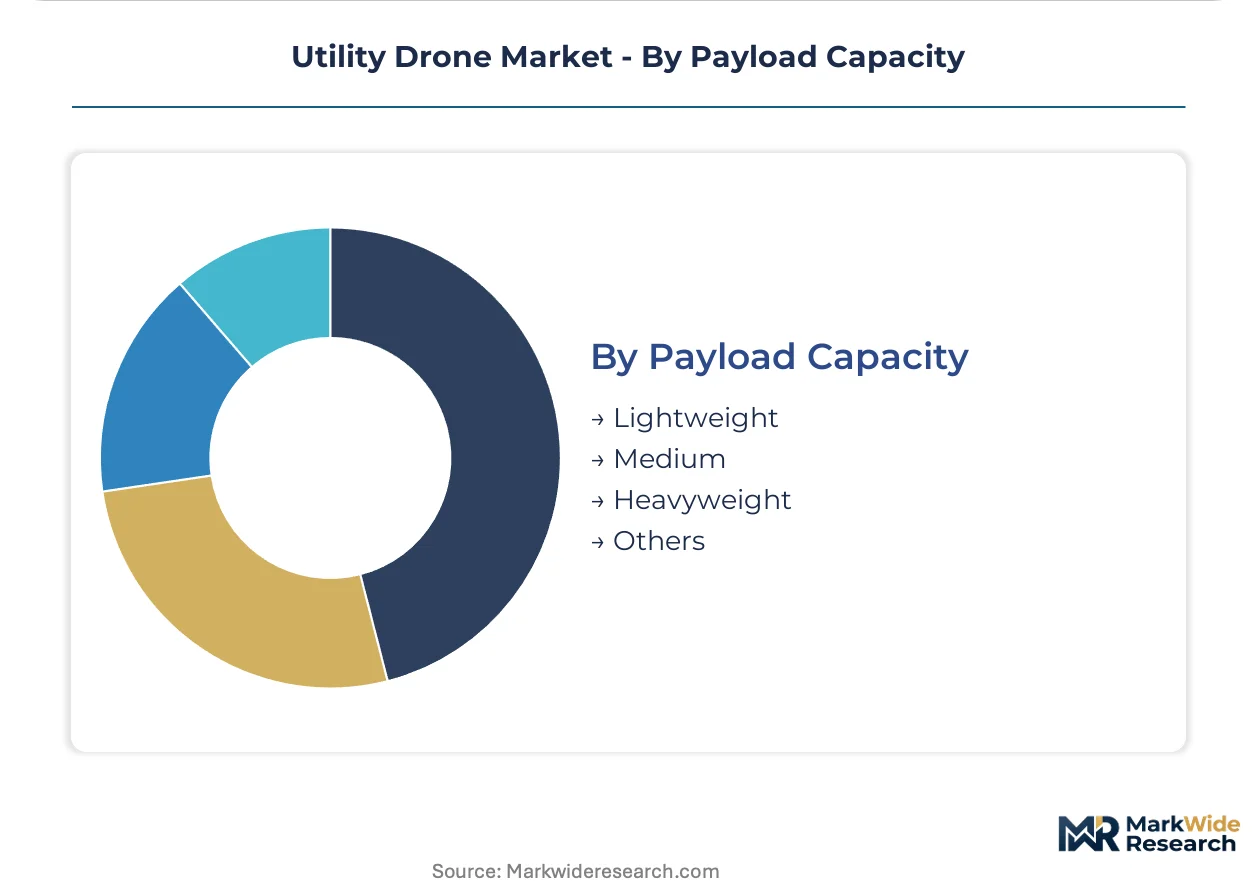
Weight class segmentation aligns with sensor sophistication, flight duration trade-offs, and transport logistics for field crews.
- Lightweight:Sub-2kg platforms with compact RGB and basic thermal sensors serve agricultural scouting and small-scale inspection. These units maximize flight time and minimize regulatory friction under FAA Part 107.
- Medium:2-10kg capacity accommodates LiDAR, dual thermal-RGB gimbals, and gas detection sensors. Energy utilities standardize on this tier for transmission line integrity assessments.
- Heavyweight:Above-10kg platforms carry multiple sensor payloads or maintenance tools including robotic arms. Offshore oil platform logistics and specialized construction tasks drive limited deployment.
- Others:Custom payload configurations for research, military-utility crossover, and experimental sensor integration occupy niche procurement channels.
Medium capacity dominates utility budgets; Lightweight units are expanding most quickly in agricultural adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilot training clusters in Phoenix and Dallas anchor North American operational expertise, while European engineering talent concentrates around Toulouse and Munich autonomy research centers.
United States
Storm recovery operations across the Gulf Coast and rural electrification programs in the Mountain West drive fleet procurement. FAA Part 107 waivers enable transmission corridor surveys without full pilot certification. Arizona utilities deploy autonomous platforms for wildfire-risk vegetation surveys where bandwidth constraints limit satellite dependency.
Germany
Grid modernization under the Energiewende program and offshore wind expansion in the North Sea create inspection demand. EU AI Act risk classification rules mandate human oversight documentation for autonomous systems near critical infrastructure. Bavarian research clusters around Munich develop explainable AI for defect detection algorithms.
China
Ultra-high voltage transmission buildout and smart grid investments accelerate platform deployment. GB standards for commercial drone operations provide baseline certification frameworks that insurers reference. Shenzhen manufacturing ecosystems supply thermal imaging payloads to domestic and export markets.
India
Rural electrification corridors under CEA guidelines and renewable energy park surveys generate cost-sensitive procurement. Central Electricity Authority mandates shape inspection protocols for low-density transmission networks. Karnataka drone service providers cluster around Bangalore software development hubs.
Japan
Aging infrastructure maintenance and typhoon damage assessment prioritize precision hovering platforms. METI guidelines for industrial drone operations influence procurement qualification timelines. Nagoya engineering centers advance LiDAR integration for corridor mapping missions.
Utility Drone Market Competitive Environment
Top-tier vendors anchor defense-utility crossover contracts, while mid-tier specialists compete on software integration and payload flexibility. The market structure reflects tiered certification requirements that separate BVLOS-capable platforms from consumer-adjacent units. Strategic archetypes include aerospace conglomerates with ruggedized military heritage, consumer electronics scale players, and lightweight agricultural specialists. Dominant competitive moves involve portfolio diversification into subscription-based fleet services and strategic partnerships for methane detection sensor integration.
Within the defense-utility crossover tier, Lockheed Martin Corporation exemplifies ruggedized platform certification for critical infrastructure missions. SZ DJI Technology Co Ltd occupies a scale-driven position leveraging manufacturing ecosystems for cost-advantaged thermal imaging deployments. Parrot Drones SAS represents the agricultural-specialist archetype competing on software integration rather than hardware specifications.
| Leading Market Players |
|---|
| SZ DJI Technology Co Ltd |
| Lockheed Martin Corporation |
| Parrot Drones SAS |
| Yuneec International Co Ltd |
| Delair SAS |
| Terra Drone Corp |
| PrecisionHawk Inc |
| Kespry Inc |
| Power Drone |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon-border adjustments and domestic-content mandates in India and the United States are gating qualified thermal imaging sensor supply and reserving premium-tier pricing access for vendors with certified regional manufacturing footprints.
Pricing Analysis
The bundled-vs-unbundled service split separates capital procurement from per-mile inspection subscriptions. Three-tier pricing structure across premium, standard, and economy levels tracks BVLOS certification grade and AI-powered defect detection integration. Cost compression in the economy tier is intensifying because SZ DJI Technology Co Ltd manufacturing scale erodes hardware margins. Agricultural cooperatives in the Midwest exhibit highest price sensitivity, while Gulf Coast utilities facing storm recovery mandates accept premium service bundles.
Supply Chain Analysis
Domestic-content mandates in India under CEA guidelines and proposed U.S. Buy American provisions for critical infrastructure equipment are reshaping sourcing toward Shenzhen, Nagoya, and Bavarian manufacturing clusters. LiDAR navigation modules and thermal imaging chipsets draw from Japanese and German component suppliers, creating single-source vulnerability for mid-tier platform assemblers. Distribution runs through utility holding company procurement consortia and specialized drone service provider networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Utility Drone Market functions as a stable compounder where regulatory ratification of fully autonomous BVLOS flight creates predictable inspection demand replacement cycles.
For Market Incumbents: Deploy backward integration into thermal imaging sensor production to capture margin from Japanese and German component suppliers. Consolidate software integration capabilities to defend against agricultural-specialist entrants. Lockheed Martin Corporation's defense-utility crossover positioning demonstrates how ruggedized platform certification creates switching costs. For New Entrants and Emerging Players: Launch via subscription-based fleet services targeting Texas and California utilities shifting from capital procurement. Penetrate India's rural electrification corridors where CEA-mandated inspection protocols outpace domestic platform supply. White-space exists in methane detection sensor integration for pipeline operators. For Investors and Strategic Acquirers: Roll-up economics work for regional drone service providers because utility holding company procurement consolidation demands interoperable data formats and standardized reporting platforms. Five-to-ten year viability hinges on FAA and EASA autonomous flight approval timelines. Watch for BVLOS waiver expansion velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Certification Investment | FAA waiver expansion unlocks autonomous corridor surveys without ground observers. |
| AI Defect Detection Integration | Explainable algorithms satisfy EU AI Act risk classification for critical infrastructure. |
| Subscription Fleet Services | Per-mile pricing models align with Duke Energy and Southern California Edison procurement shifts. |
| Methane Sensor Partnership | Gas detection miniaturization enables continuous emissions monitoring contracts. |
| Regional Manufacturing Localization | Domestic-content compliance secures Indian CEA and U.S. infrastructure procurement access. |
Study Parameters
Direct dialogue with utility planning officers, FAA certification specialists, drone fleet operations managers, and thermal imaging sensor procurement leads grounded qualitative findings. Secondary validation drew from FAA Part 107 waiver databases, EASA safety management system filings, SEC 10-K disclosures of utility holding companies, and ISO 21384-3 certification registries. Bottom-up segment sizing and top-down macroeconomic anchoring triangulated volume estimates.
Bottom-up modeling built from individual application segments—inspection, surveillance, delivery, maintenance—cross-referenced against technology architecture and payload capacity tiers. Top-down validation checked aggregate figures against utility capital expenditure disclosures and drone service provider revenue proxies. The projection horizon spans the analysis window with CAGRs derived from historical replacement cycles and regulatory approval velocity. Forecast inputs incorporated battery energy density improvement curves and LiDAR cost decline trajectories.
Several conditions sit outside the modeled scope, including military-utility crossover contract classifications, consumer drone market spillover effects, and hypothetical breakthroughs in solid-state battery chemistry. Forecasts reflect documented assumptions about FAA and EASA regulatory timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Asia-Pacific Drones Market
UAV
Counter Drone System Market
UAV
UAV Payload and Subsystems Market
UAV
GCC Drone Pilot Training Market
UAV
Europe Tactical UAV Market
UAV
Drone Telematics Market
UAV
Drone-Based Consulting Services Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Drone Flight Controller System Market
UAV
Rc Helicopter Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Commercial UAV Market
UAV
Tactical UAV Market
UAV
Fixed Wing Military Drones Market
UAV
Global Inspection Drones Market
UAV
North America Fuel Cell UAV Market