
 Dysphagia Diet Thickening Market | 2026-2036
Dysphagia Diet Thickening Market Size, Share, and Industry Trends Forecast 2026-2036
Dysphagia Diet Thickening Market Analysis
Subscription-based replenishment programs for home care patients is recalibrating how manufacturers monetize thickener consumption beyond one-time product sales. Nestlé Health Science leverages direct-to-patient digital platforms to secure recurring revenue streams. Kent Precision Foods Group, Inc. anchors institutional supply contracts through specialized foodservice distribution. SimplyThick, LLC differentiates via gel-based formulations that command premium positioning in outpatient channels.
Dysphagia diet thickeners modify liquid viscosity to prevent aspiration during swallowing, typically employing modified food starches or xanthan gum bases that achieve IDDSI Level 1 through 4 consistency standards within thirty seconds of mixing. Powdered thickeners retain dominant volume share due to lower per-dose cost and extended shelf stability in bulk healthcare procurement. Pre-mixed thickeners represent the fastest-growing product category as long-term care facilities prioritize labor reduction and portion control accuracy. Home care end users increasingly drive margin pool expansion through higher-unit-price convenience formats delivered via online retail and pharmacy channels.
FDA oversight of medical foods classification and IDDSI framework implementation shape product formulation requirements and labeling precision across the United States. The country's national pharmaceutical regulator and CMS reimbursement policies jointly determine whether thickener purchases qualify for insurance coverage in skilled nursing versus home settings. Stakeholders must monitor evolving state-level Medicaid waivers and Medicare Advantage benefit designs that could shift procurement authority between institutional buyers and individual caregivers.
Market Dynamics
Home care patients now drive thickener demand through subscription replenishment models that convert episodic purchases into predictable recurring revenue, fundamentally restructuring manufacturer cash flow patterns away from institutional bulk contracts.
Growth Catalysts
- IDDSI Framework Adoption:The International Dysphagia Diet Standardisation Initiative's Level 1-4 viscosity classification creates uniform formulation targets that simplify product development and cross-border distribution for thickener manufacturers.
- Post-Acute Care Transitions:Hospital discharge protocols in the United States increasingly mandate home-based dysphagia management, expanding the addressable patient population beyond institutional settings into residential care.
- Gel-Based Formulation Advances:Xanthan gum thickening technologies achieve rapid hydration without clumping, improving patient compliance and reducing caregiver preparation time compared to traditional starch-based alternatives.
Market Restraints
- Modified Food Starch Input Volatility:Corn and tapioca starch prices fluctuate with agricultural commodity cycles, compressing margins for powdered thickener producers who cannot pass through cost spikes to price-sensitive institutional buyers.
- Supply Concentration in Foodservice Distribution:Three national distributors control approximately seventy percent of skilled nursing facility thickener procurement, creating gatekeeper power that limits manufacturer pricing autonomy.
- Reimbursement Classification Ambiguity:CMS medical food versus nutritional supplement categorization uncertainty blocks insurance coverage for many home care patients, forcing out-of-pocket payment that suppresses volume.
Strategic Opportunities
- Direct-to-Patient Digital Platforms:E-commerce channels bypass traditional pharmacy and foodservice intermediaries, capturing margin and enabling personalized subscription dosing based on individual swallowing assessment outcomes.
- Pre-Mixed Convenience Formats:Single-serve liquid thickeners address labor scarcity in long-term care facilities while commanding per-dose premiums that expand manufacturer margin pools beyond commodity powder equivalents.
- State Medicaid Waiver Expansion:Home and community-based services waivers in select US states now cover dysphagia nutrition products, creating reimbursement precedents that advocacy groups can replicate across additional jurisdictions.
Industry Challenges
- IDDSI Compliance Testing Capacity:Accredited laboratory capacity for viscosity verification remains concentrated in Europe and North America, creating bottlenecks for manufacturers seeking rapid certification of new formulations.
- Legacy ERP Integration Friction:Long-term care facility procurement systems require EDI-compliant order management that smaller thickener suppliers lack, forcing expensive middleware investments or exclusion from contract bidding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dysphagia Diet Thickening Market |
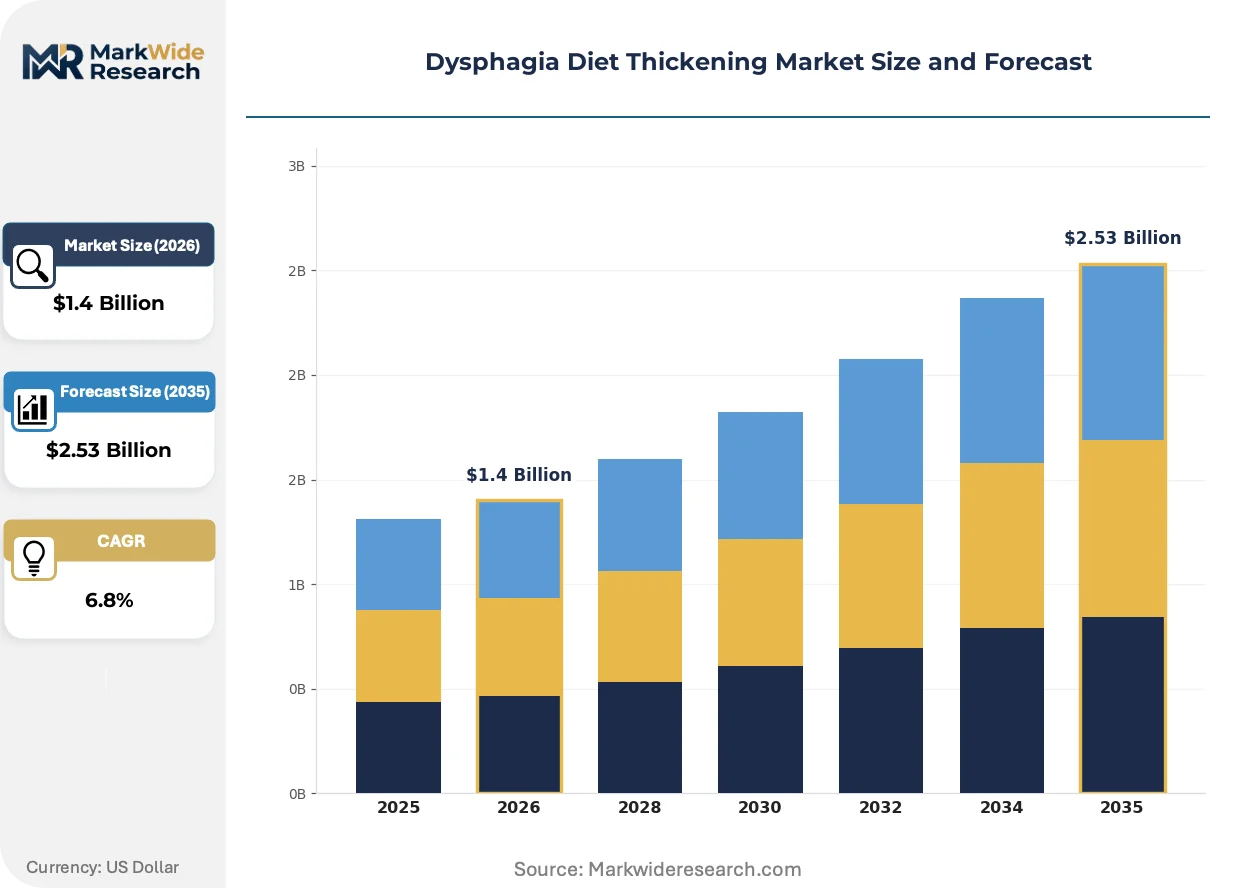
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Thickeners, Pre-Mixed Thickeners, Instant Thickeners, Gel-based Thickeners End User: Hospitals, Long-term Care Facilities, Home Care, Rehabilitation Centers Distribution Channel: Pharmacies, Online Retail, Direct Sales, Supermarkets Packaging Type: Bottles, Sachets, Tubs, Cans |
| Companies Covered | Nestlé Health Science, Kent Precision Foods Group, Inc., Hormel Health Labs, SimplyThick, LLC, Nutricia Advanced Medical Nutrition, Flavour Creations, Abbott Laboratories, Fresenius Kabi, Medtrition, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dysphagia Diet Thickening Market Emerging Trajectories
Thickener formulation science and patient administration convenience are converging to reshape competitive positioning, with viscosity stability, preparation speed, and packaging format now displacing unit cost as primary purchasing criteria across care settings.
Xanthan gum-based instant thickeners achieve IDDSI-compliant viscosity within thirty seconds of liquid contact without temperature-dependent settling, eliminating the five-minute hydration delays and texture degradation that plague modified starch alternatives. Skilled nursing facilities facing certified nursing assistant shortages are adopting these rapid-hydration formats to reduce beverage preparation labor by approximately forty percent per patient meal. Powdered starch thickeners is overtaking gel-based alternatives only in price-sensitive bulk procurement channels where extended shelf stability outweighs convenience premiums.
FDA medical food classification guidance issued in 2023 clarified that dysphagia thickeners qualify as medical foods only when administered under physician supervision for specific disease management, creating compliance documentation burdens for direct-to-consumer marketers. Manufacturers must now maintain separate labeling and marketing pathways for institutional versus retail channels, fragmenting brand architecture and increasing regulatory affairs headcount. Home care suppliers are responding by embedding telehealth swallowing assessments into their digital platforms to establish the physician relationship required for medical food status.
Caregivers managing dysphagia at home increasingly reject bulk powder canisters in favor of single-serve stick packs and pre-thickened beverages that eliminate measurement error and reduce contamination risk. Amazon and specialized durable medical equipment e-tailers capture this preference shift through auto-replenishment algorithms that trigger shipments before supply depletion. The United States exhibits the most pronounced channel migration, where Medicare Advantage supplemental benefits and health savings account eligibility accelerate online thickener purchasing among aging-in-place demographics.
Dysphagia Diet Thickening Market Segmentation
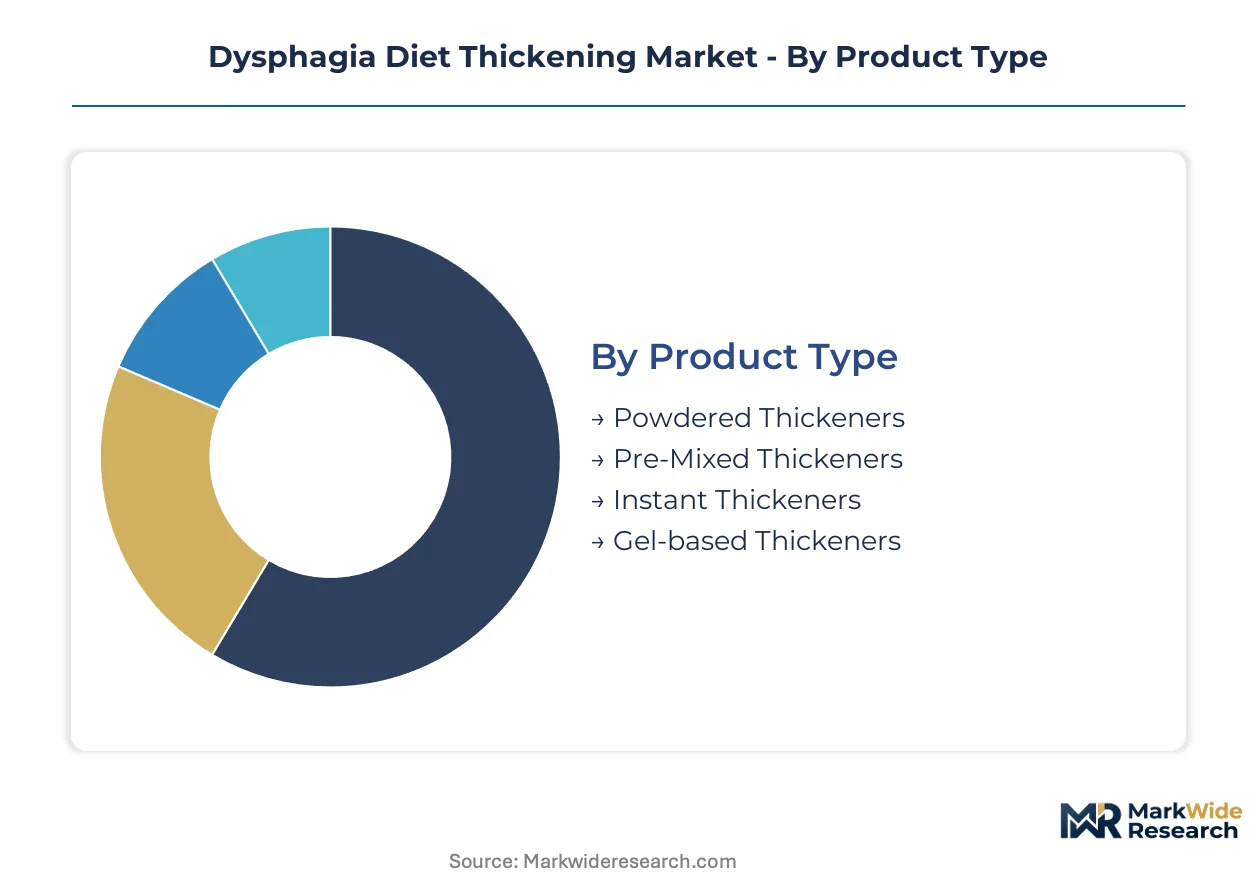
Dysphagia thickener procurement splits sharply across institutional and residential channels, with reimbursement status and caregiver labor availability determining format preferences. Manufacturers must architect separate supply chains for bulk institutional contracts versus direct-to-patient convenience formats.
Product Type:
Cost tier dominates buyer selection, with per-dose economics and preparation labor trade-offs driving channel-specific format adoption.
- Powdered Thickeners:Modified food starch or xanthan gum base delivers IDDSI-compliant viscosity at lowest per-dose cost. Skilled nursing facilities in the United States favor bulk canister procurement for Medicaid-reimbursed residents where labor substitution outweighs convenience premiums.
- Pre-Mixed Thickeners:Single-serve liquid formats eliminate measurement error and reduce certified nursing assistant preparation time by approximately forty percent. Long-term care facilities facing staffing shortages absorb per-dose premiums to protect meal service throughput.
- Instant Thickeners:Rapid-hydration xanthan gum formulations achieve target viscosity within thirty seconds without temperature-dependent settling. Home care patients in the United States purchase through pharmacy and online retail channels for outpatient dysphagia management.
- Gel-based Thickeners:Concentrated gel packets mix into beverages without clumping or texture degradation. Outpatient clinics and home care settings in the United States command premium positioning for swallowing disorder patients prioritizing preparation reliability.
Powdered thickeners lead on scale; pre-mixed formats lead on momentum.
End User:
Care setting determines reimbursement pathway and procurement authority, fragmenting manufacturer go-to-market architecture.
- Hospitals:Acute care units deploy thickeners under speech-language pathology supervision during swallowing assessment and post-surgical recovery. CMS bundled payment models in the United States limit standalone thickener procurement autonomy.
- Long-term Care Facilities:Nursing homes represent the largest institutional volume channel, with foodservice distributors controlling approximately seventy percent of procurement flow. Labor scarcity accelerates adoption of pre-mixed and instant formats despite higher per-dose cost.
- Home Care:Aging-in-place patients and family caregivers drive the fastest channel expansion, with subscription replenishment models converting episodic purchases into recurring revenue streams. Medicare Advantage supplemental benefits in select United States markets offset out-of-pocket cost burden.
- Rehabilitation Centers:Post-acute stroke and neurodegenerative disease patients receive thickener therapy during swallowing rehabilitation protocols. Discharge planning increasingly extends thickener prescriptions into residential settings.
Long-term care facilities anchor institutional volume; home care settings claim the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects patient mobility, reimbursement complexity, and caregiver digital engagement patterns.
- Pharmacies:Community and hospital outpatient pharmacies serve Medicare Part D and commercial insurance patients with physician-prescribed thickener regimens. Prior authorization requirements in the United States create fulfillment delays that suppress volume.
- Online Retail:Amazon and specialized durable medical equipment e-tailers capture auto-replenishment demand from home care patients. Health savings account eligibility in the United States accelerates digital purchasing among aging demographics.
- Direct Sales:Manufacturers bypass distributor markups through institutional contracting with long-term care chains and hospital systems. EDI-compliant order management systems create technical barriers for smaller suppliers.
- Supermarkets:Mass retail placement targets family caregivers seeking immediate availability without prescription requirements. Limited shelf space and low consumer awareness constrain category development.
Pharmacies retain the largest transaction volume; online retail channels expand most quickly.
Packaging Type:
Portion control accuracy and contamination risk shape format selection across care environments.
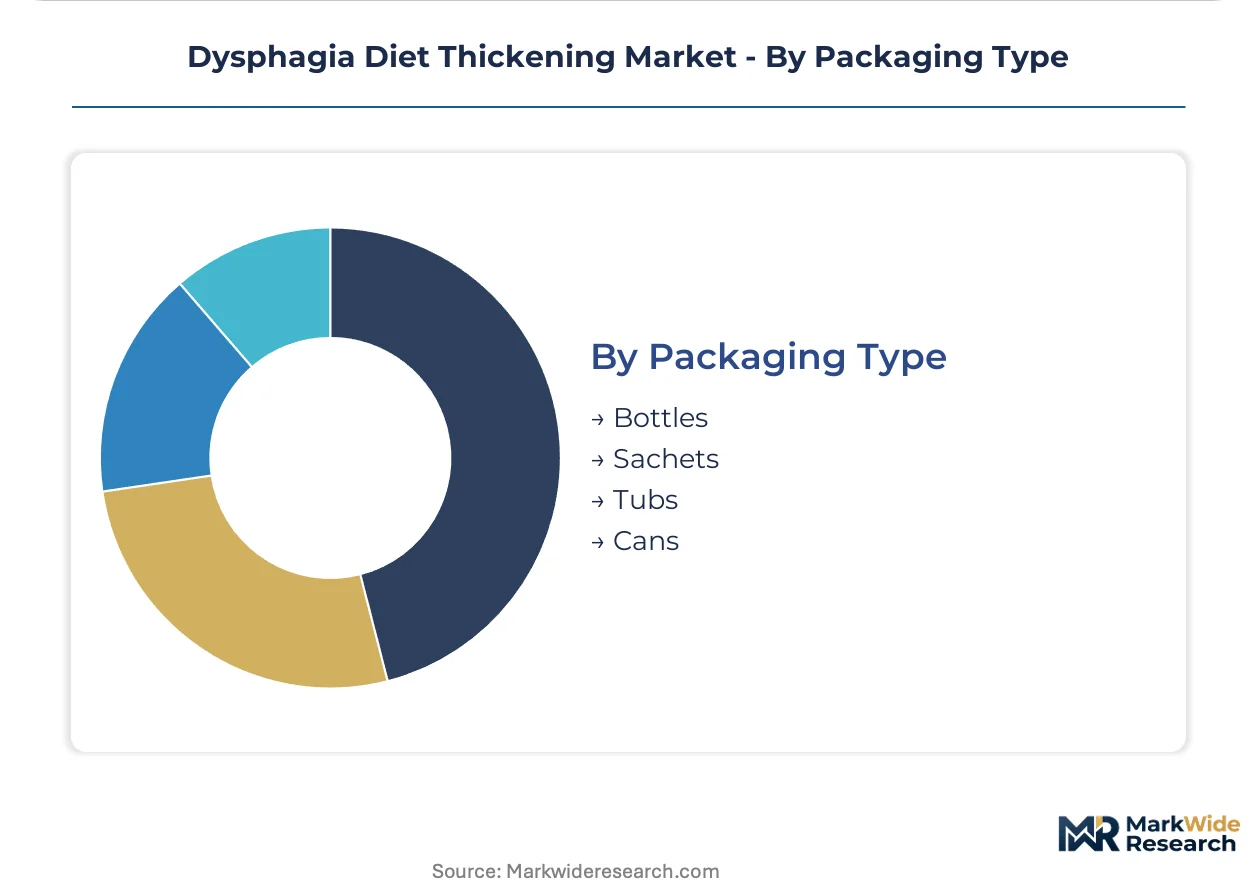
- Bottles:Multi-dose containers serve institutional settings with calibrated scoop systems for volume measurement. Bulk packaging minimizes per-dose cost in price-sensitive skilled nursing procurement.
- Sachets:Single-serve stick packs eliminate measurement error and reduce contamination risk for home care patients. Premium positioning reflects convenience value and portability for outpatient use.
- Tubs:Large-format canisters dominate long-term care foodservice operations with high daily patient throughput. Extended shelf stability supports inventory management in facilities with limited storage space.
- Cans:Pre-thickened beverage packaging serves ready-to-drink convenience demand in rehabilitation and home care settings. Liquid stability eliminates preparation labor entirely.
Bottles and tubs dominate institutional procurement; sachets gain share fastest in residential channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates thicker demand volumes than Germany, where reimbursement fragmentation constrains home care expansion despite comparable aging demographics.
United States
Post-acute care transitions and Medicare Advantage supplemental benefits drive thickener consumption across skilled nursing and residential settings. FDA medical food classification guidance issued in 2023 tightens compliance documentation for direct-to-consumer channels. The Minneapolis-St. Paul corridor hosts foodservice distribution concentration serving Upper Midwest long-term care chains.
Germany
Rehabilitation center discharge protocols and statutory long-term care insurance (Pflegeversicherung) coverage sustain institutional demand. EFSA purity standards and BfArM medical device borderline classifications shape product registration pathways. The Rhine-Ruhr metropolitan region anchors centralized procurement for North Rhine-Westphalia nursing home networks.
Japan
Super-aging demographics and Ministry of Health, Labour and Welfare (MHLW) long-term care insurance expansion elevate dysphagia nutrition to priority category status. PMDA consultation procedures for medical food-adjacent products create regulatory clarity for thickener marketers. The Kanto region surrounding Tokyo concentrates hospital and rehabilitation center procurement authority.
United Kingdom
NHS Integrated Care Boards and speech-language therapy service expansions broaden thickener prescribing in community settings. MHRA borderline determinations and NICE guideline incorporation of IDDSI standards standardize formulation requirements. Greater Manchester and West Midlands clusters aggregate procurement for regional care home operators.
Australia
NDIS disability support funding and aged care royal commission reforms redirect thickener procurement toward consumer-directed care models. TGA medical food regulatory guidance and FSANZ labeling standards govern product market entry. The Sydney-Melbourne corridor dominates pharmacy and online retail channel distribution infrastructure.
Dysphagia Diet Thickening Market Vendor Landscape
Top-tier vendors anchor institutional supply contracts, while mid-tier specialists occupy outpatient and direct-to-patient niches. Three strategic archetypes dominate: diversified nutrition conglomerates leveraging healthcare distribution scale, regional foodservice specialists securing long-term care exclusivity, and formulation innovators commanding premium positioning through rapid-hydration technologies. Competitive moves concentrate on vertical integration into ingredient sourcing and subscription platform development to capture recurring revenue streams.
Among diversified nutrition conglomerates, Nestlé Health Science and Abbott Laboratories exemplify scale-driven archetypes spanning institutional and retail channels. Kent Precision Foods Group, Inc. occupies a position within the regional foodservice specialist tier, while SimplyThick, LLC represents the formulation innovation archetype. These three entities collectively illustrate the competitive spectrum without exhaustively mapping market presence.
| Leading Market Players |
|---|
| Nestlé Health Science |
| Kent Precision Foods Group, Inc. |
| Hormel Health Labs |
| SimplyThick, LLC |
| Nutricia Advanced Medical Nutrition |
| Flavour Creations |
| Abbott Laboratories |
| Fresenius Kabi |
| Medtrition, Inc. |
| Others |
Supply Flow & Price Mechanics
IDDSI compliance certification requirements gate both qualified supply and premium-tier pricing access, as manufacturers lacking accredited laboratory verification cannot command gel-based and instant thickener premiums in institutional procurement. Corn and tapioca starch price volatility feeds back into powder thickener margins, forcing cost-sensitive skilled nursing facilities to trade formulation quality for per-dose economics.
Pricing Analysis
Capacity additions in xanthan gum fermentation facilities across China are reshaping price floors for instant thickeners, compressing premiums that gel-based formats previously commanded in outpatient channels. Three-tier pricing structure across premium, standard, and economy levels separates IDDSI-certified rapid-hydration products from modified starch alternatives and unverified imports. Pricing pressure stems from agricultural commodity cycles in corn and cassava feedstocks that powdered thickener producers cannot fully pass to Medicaid-reimbursed institutional buyers. Long-term care facilities exhibit highest price sensitivity due to bulk procurement scale, while home care patients absorb convenience premiums through subscription auto-replenishment.
Supply Chain Analysis
Xanthan gum supply rests on fermentation capacity concentrated in China, Austria, and the United States, with modified food starch drawing from corn processing clusters in the American Midwest and tapioca operations in Southeast Asia. Corn starch, tapioca starch, and xanthan gum fermentation feedstock constitute the three critical input dependencies. Single-source vulnerability in foodservice distribution creates gatekeeper risk, as three national distributors control approximately seventy percent of skilled nursing facility procurement flow. Distribution runs through institutional foodservice networks for bulk contracts, direct-to-patient digital platforms for home care, and pharmacy wholesale for reimbursed outpatient prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dysphagia thickener market represents a late-cycle quality story, as post-acute care transitions and IDDSI standardization shift procurement criteria from unit cost toward viscosity stability and preparation speed.
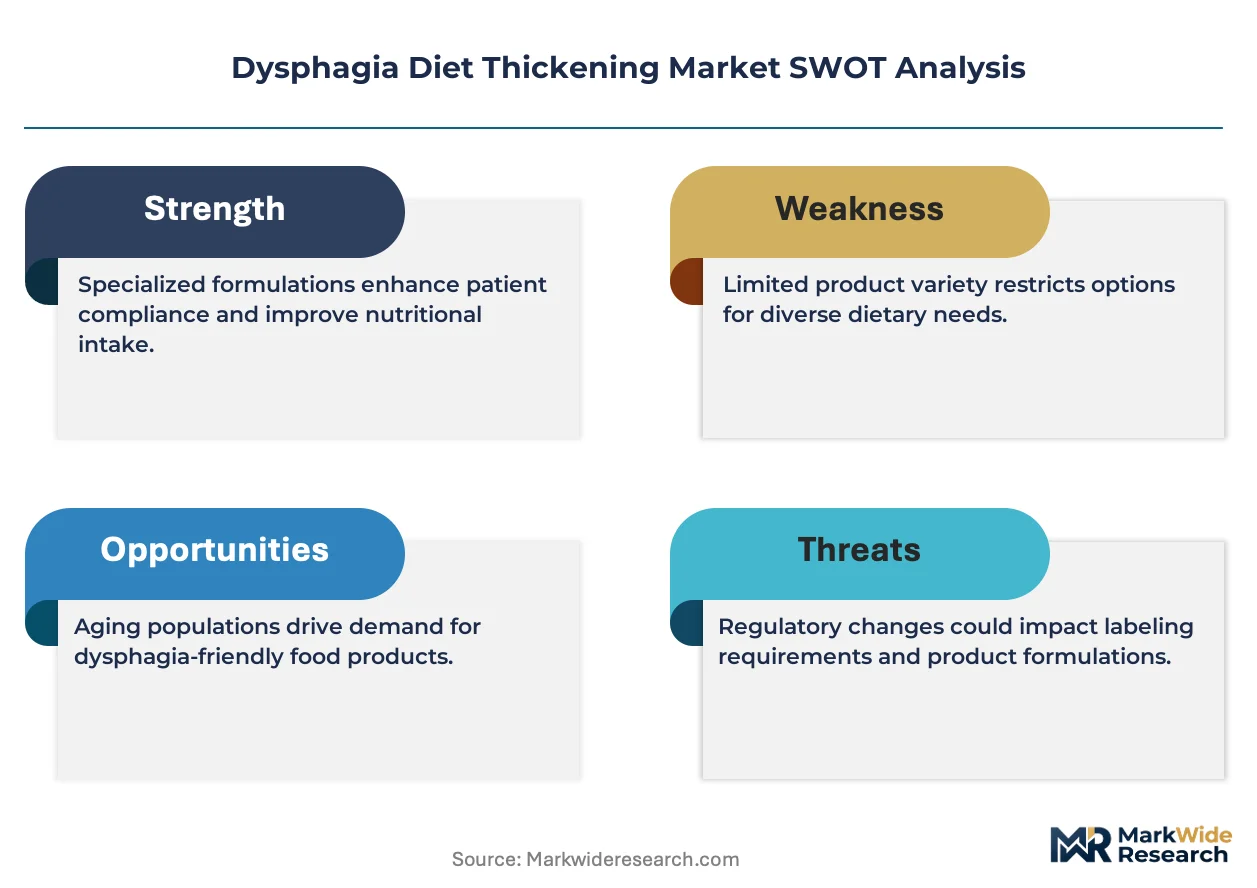
For Market Incumbents: Anchor institutional supply relationships through EDI-compliant order management systems that exclude smaller competitors from long-term care chain bidding. Deepen backward integration into xanthan gum fermentation capacity to offset agricultural commodity volatility in starch-based portfolios. Defend against gel-based formulation specialists by embedding rapid-hydration technologies across product lines before premium positioning erodes. For New Entrants and Emerging Players: CMS medical food classification guidance in the United States opens a window for telehealth-integrated platforms that establish physician relationships required for insurance reimbursement. Target state Medicaid waiver expansion for home and community-based services coverage of dysphagia nutrition products, where precedent-setting jurisdictions create replicable advocacy templates. Penetrate through direct-to-patient digital subscription models that bypass foodservice distributor gatekeepers and capture recurring revenue streams. For Investors and Strategic Acquirers: Roll-up economics work for regional foodservice specialists with institutional exclusivity contracts because skilled nursing procurement consolidation concentrates volume among fewer distributor relationships. Acquisition targets include mid-tier manufacturers with IDDSI-certified formulations but underdeveloped direct-to-consumer channels. Watch Medicare Advantage supplemental benefit expansion as the inflection signal for home care channel viability.| Strategic Initiative | Industry Significance |
|---|---|
| IDDSI Certification Investment | Accredited laboratory verification unlocks institutional procurement eligibility and premium positioning in outpatient channels. |
| Direct-to-Patient Platform Development | Subscription auto-replenishment captures recurring revenue and bypasses foodservice distributor margin extraction. |
| Xanthan Gum Backward Integration | In-house fermentation capacity insulates margins from agricultural commodity cycles in corn and tapioca starch markets. |
| Telehealth Assessment Integration | Embedded swallowing evaluations establish physician relationships required for CMS medical food reimbursement classification. |
| State Medicaid Waiver Replication | Advocacy-driven coverage expansion in select jurisdictions creates precedent for home care reimbursement nationwide. |
Methodological Framework
Coverage spans the United States, Germany, Japan, the United Kingdom, and Australia, with primary inputs from each market's regulatory and procurement stakeholders. The analysis combines interviews with speech-language pathologists, long-term care foodservice directors, hospital purchasing committee members, and durable medical equipment distributors with secondary validation from FDA medical food guidance documents, CMS reimbursement policy updates, IDDSI framework implementation reports, and skilled nursing facility procurement databases. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchor market sizing.
Granularity extends to product type, end-user setting, distribution channel, and packaging format dimensions, with additional segmentation by reimbursement pathway and IDDSI compliance tier. Volume and value outputs reflect a triangulated approach across the projection horizon, with CAGRs derived from patient population growth, care setting transition rates, and format substitution elasticities. Forecast inputs include aging demographic projections, post-acute discharge protocol adoption, and state-level Medicaid waiver expansion timelines.
Revisions become necessary when IDDSI framework adoption accelerates beyond modeled penetration curves, agricultural commodity price spikes exceed historical volatility bands, or CMS medical food classification guidance shifts reimbursement eligibility thresholds. Material deviation in these named triggers warrants pause and re-evaluation of volume and value assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
South America Feed Palatability Enhancers Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Flour Conditioner Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
High Ratio Shortening Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Cake Softener Market