
 Europe Water Enhancer Market | 2026-2036
Europe Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Water Enhancer Market Foresight
The capital-intensity gap between spray-dry infrastructure and liquid-concentrate blending is reorganizing competitive tiers across the Europe Water Enhancer Market. Britvic PLC sustains broad retail penetration through its established beverage distribution network. The Coca-Cola Company leverages its fountain-equipment footprint to place enhancer dispensers in foodservice channels. Pure Flavour GmbH specializes in artisanal fruit-infusion formulations that command premium positioning in German health stores.
Europe water enhancers comprise concentrated liquid or powdered additives that deliver flavor, electrolytes, or functional ingredients to plain water, typically dosed at 1-5 milliliters per 500 milliliters serving and manufactured through cold-fill aseptic processing to preserve volatile aromatic compounds. Their primary purpose is converting commodity bottled or tap water into differentiated, low-calorie beverages without carbonation infrastructure. Flavor Drops and Electrolyte Mixes together capture the dominant volume share, with Electrolyte Mixes recording the fastest trajectory as athletic hydration protocols migrate from ready-to-drink formats toward customizable dosing. Spray Enhancers occupy a narrower but higher-margin niche in culinary and mixology applications where precise aromatic control commands price premiums.
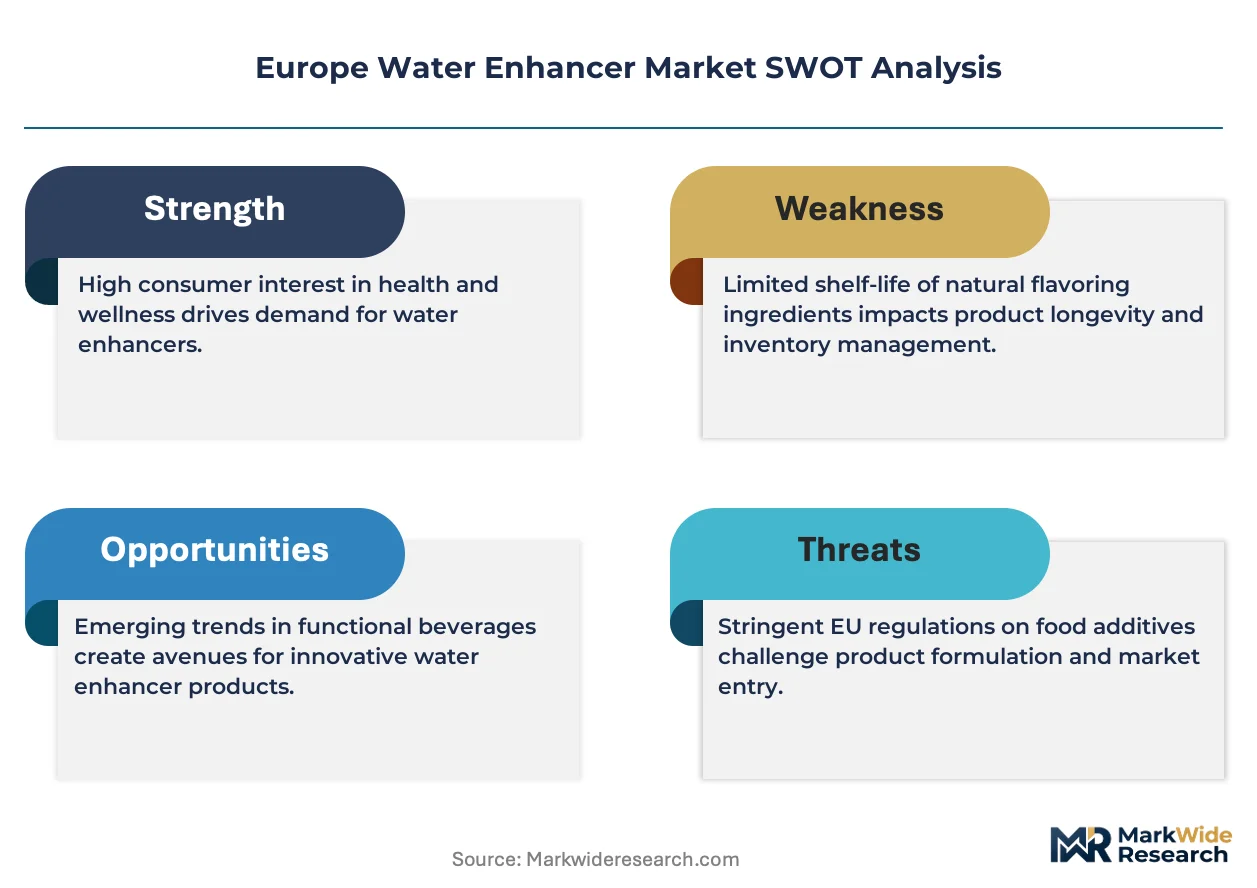
EFSA nutritional-claim substantiation rules and EU Food Information to Consumers Regulation constrain how enhancers market functional benefits, forcing reformulation toward demonstrable mineral content or botanical extracts with established safety dossiers. REACH compliance for flavor compound imports adds testing overhead that favors larger suppliers with dedicated regulatory affairs capacity. Stakeholders must monitor pending EU packaging-waste directives that could mandate concentrated formats over single-serve sachets, reshaping format strategy and channel economics before implementation timelines crystallize.
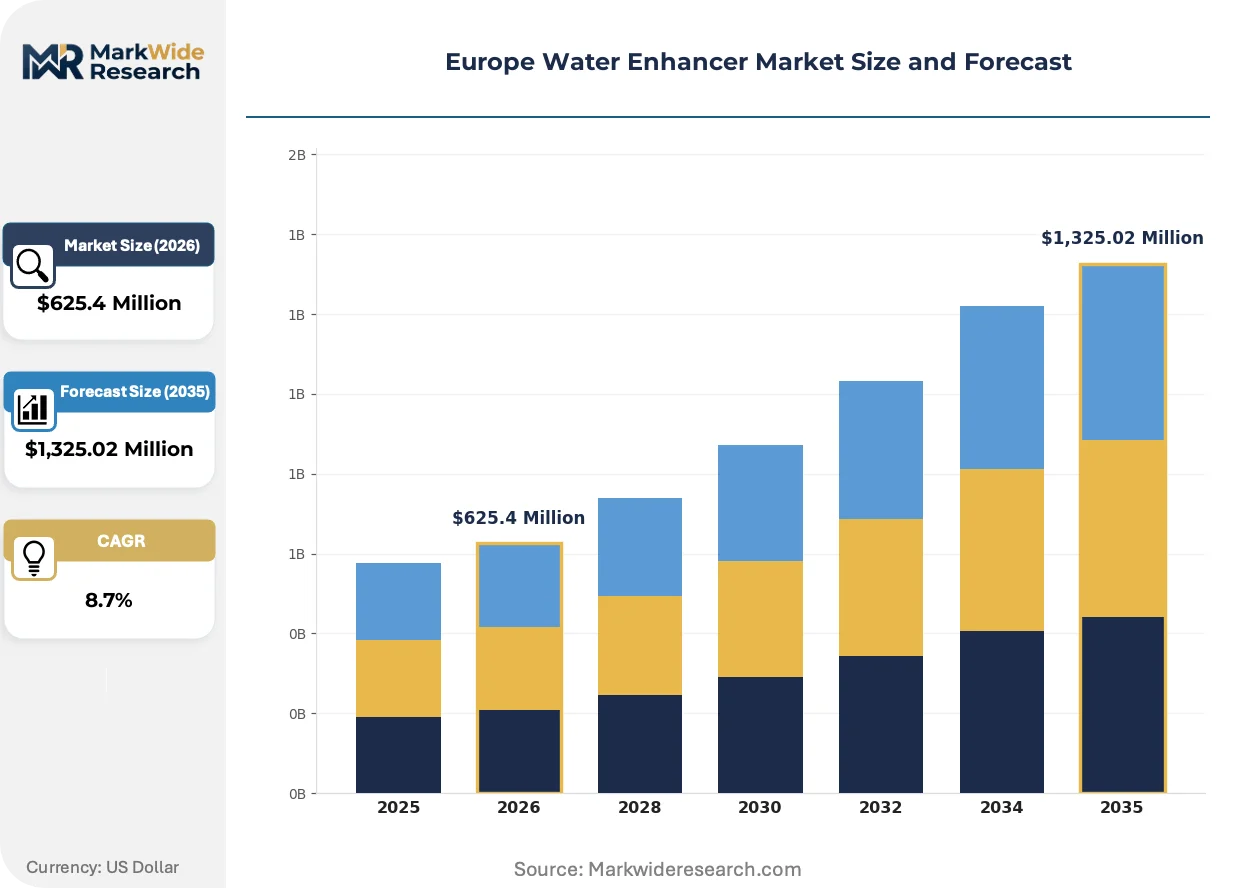
Market Dynamics
EFSA nutritional-claim substantiation rules are forcing reformulation toward demonstrable mineral content or botanical extracts with established safety dossiers, compressing marketing flexibility while elevating R&D thresholds for competitive entry.
Growth Catalysts
- REACH compliance for flavor compound imports:Larger suppliers with dedicated regulatory affairs capacity capture share from fragmented importers, consolidating supply-side power.
- Athletic hydration protocol migration:Electrolyte mixes displace ready-to-drink formats as customizable dosing gains traction among German and French fitness consumers.
- Urban convenience retail maturation:Western European city centers with mature cold-chain infrastructure enable impulse purchase velocity for liquid-concentrate formats.
Market Restraints
- Testing overhead concentration:REACH compliance costs favor suppliers with captive laboratory capacity, excluding mid-tier entrants from premium flavor sourcing.
- Single-serve sachet dependency:Pending EU packaging-waste directives threaten format economics before concentrated alternatives achieve scale.
- Volatile natural extract supply:Botanical ingredient sourcing from Mediterranean and Baltic suppliers faces climate-driven harvest inconsistency.
Strategic Opportunities
- Foodservice fountain integration:Dispensers in workplace and hospitality channels bypass retail slotting-fee structures entirely.
- Eastern European underpenetration:Polish and Romanian convenience retail expansion offers first-mover positioning before category saturation.
- CSRD-aligned carbon disclosure:Concentrated formats with reduced transport emissions attract ESG-mandated procurement from institutional buyers.
Industry Challenges
- Cold-fill aseptic technician scarcity:Preserving volatile aromatic compounds requires specialized operators absent from standard beverage training pipelines.
- EFSA dossier timeline compression:Novel botanical submissions face multi-year safety evaluation windows that outpace product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Water Enhancer Market |
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,325.02 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavor Drops, Electrolyte Mixes, Fruit Infusions, Spray Enhancers Application: Fitness, Hydration, Health Supplements, Culinary Use Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Customer Type: Individuals, Athletes, Health-Conscious Consumers, Families |
| Companies Covered | Dyla LLC, Pure Flavour GmbH, The Kraft Heinz Company, Wisdom Natural Brands, Britvic PLC, The Coca-Cola Company, Eau Exquise, The Hut.com Ltd., PepsiCo Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Water Enhancer Market Shifts & Advancements
Formulation science and regulatory disclosure requirements are compressing traditional competitive advantages while elevating transparency and customization as primary differentiators across European hydration markets.
Microencapsulation of heat-sensitive flavor compounds is decomposing the trade-off between shelf stability and aromatic fidelity that previously favored synthetic alternatives. German health-store chains and Nordic direct-to-consumer platforms are adopting these formats at accelerating velocity. The technology is decomposing premium pricing power for established spray-dry infrastructure holders by enabling smaller blenders to match sensory performance without capital-intensive equipment.
EFSA's evolving guidance on botanical health claims is tightening evidentiary standards for functional positioning. Manufacturers must now commission human intervention studies or withdraw immunity and cognitive benefit assertions from packaging. Electrolyte mixes with mineral content claims face heightened scrutiny in France and Italy, driving reformulation toward magnesium and potassium concentrations that satisfy quantitative thresholds.
Subscription-based replenishment models are displacing supermarket replenishment cycles among urban professionals in Amsterdam, Copenhagen, and Berlin. Direct-to-consumer platforms capture recurring revenue while bypassing slotting-fee structures that concentrate retail power. This channel rotation is most visible among German consumers aged 25-40 who prioritize flavor variety rotation over single-SKU loyalty.
Europe Water Enhancer Market Segmentation
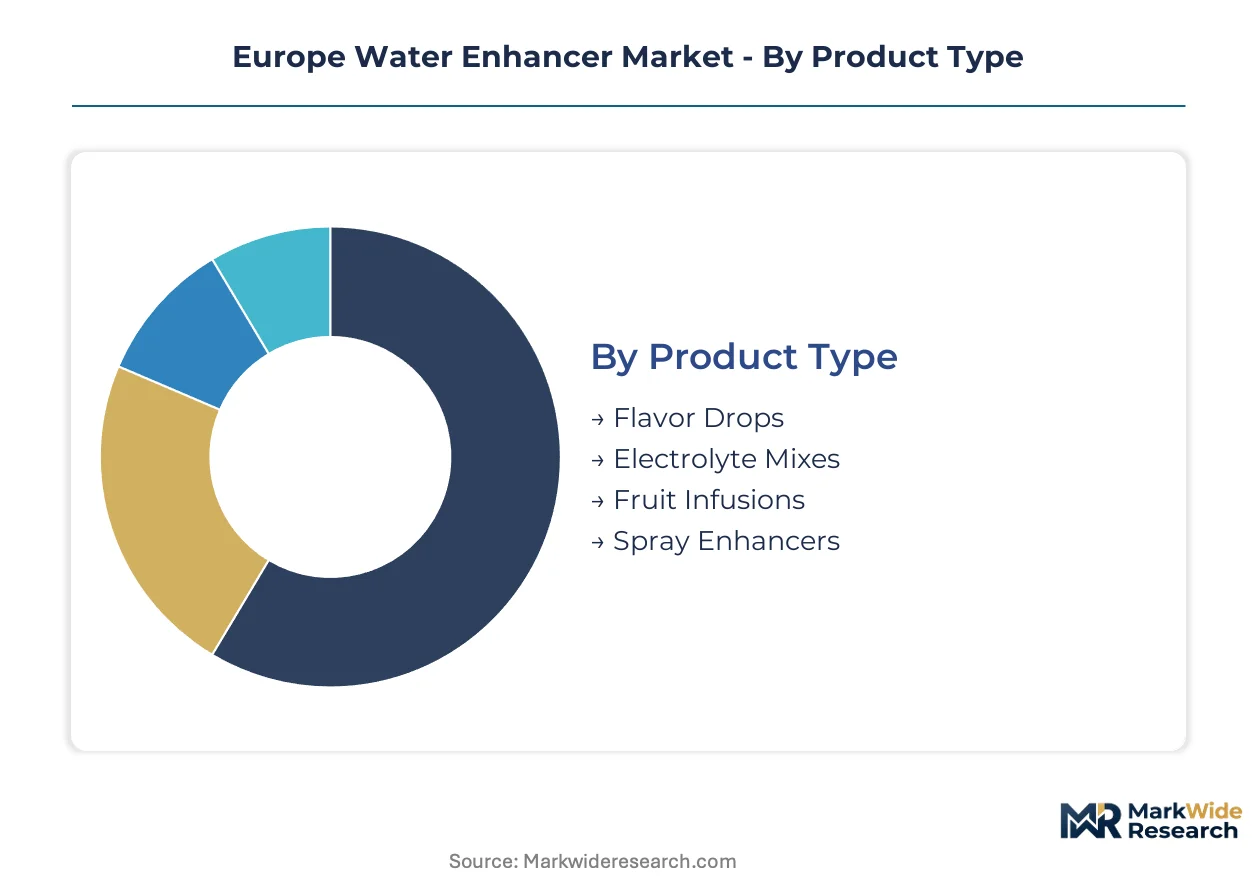
Water enhancer segmentation in Europe reflects divergent channel economics and dosing preferences. Product formats, end-use applications, and retail pathways each impose distinct manufacturing and margin requirements on suppliers.
Product Type:
Channel-mix dynamics concentrate Electrolyte Mixes in health stores and online subscriptions, while Flavor Drops dominate supermarket impulse aisles and foodservice dispensers.
- Flavor Drops:Concentrated liquid formulations dosed at 1-2 milliliters per serving, manufactured through cold-fill aseptic processing. German and French supermarket chains capture the highest velocity for single-serve trial formats, though EFSA sugar-reduction labeling pressures are compressing synthetic sweetener formulations.
- Electrolyte Mixes:Powdered mineral concentrates with customizable sodium, magnesium, and potassium ratios. Athletic clubs in Munich and Lyon drive recurring bulk purchases, with subscription platforms displacing retail replenishment among triathletes and CrossFit participants.
- Fruit Infusions:Botanical extract blends emphasizing natural aromatic profiles. Nordic direct-to-consumer channels favor these formats for their clean-label positioning.
- Spray Enhancers:Precision-dispensed aromatic mists for culinary and mixology applications. Premium hospitality channels in Barcelona and Milan absorb limited volumes at elevated price points.
By volume, Flavor Drops leads. By growth pace, Electrolyte Mixes is climbing the fastest.
Application:
Cost tiers separate commodity hydration from premium functional positioning, with Fitness commanding the highest per-serving price and Culinary Use absorbing the lowest volume at maximum margin.
- Fitness:Performance-oriented electrolyte replenishment with mineral content substantiated for EFSA claims. German cycling clubs and French running associations drive institutional procurement.
- Hydration:Everyday flavor enhancement for plain water consumption. Supermarket chains in the Netherlands and Belgium move the highest unit volumes through promotional bundling.
- Health Supplements:Functional botanical extracts targeting immunity and cognitive positioning. EFSA dossier requirements are constraining permissible claims.
- Culinary Use:Precision flavor control for beverage preparation in hospitality settings. Michelin-rated establishments in Copenhagen and Stockholm generate concentrated demand.
Fitness captures the steepest expansion trajectory as athletic protocols migrate from ready-to-drink formats.
Distribution Channel:
Volume concentration favors Supermarkets, while margin capture concentrates in Health Stores and Online Retail where slotting fees are absent.
- Online Retail:Subscription-based replenishment platforms bypass retail intermediaries entirely. Berlin and Amsterdam professionals aged 25-40 drive recurring revenue through flavor-variety rotations.
- Supermarkets:Impulse-purchase placement in beverage aisles and checkout zones. Carrefour and REWE chains dominate volume throughput across France and Germany.
- Health Stores:Specialist retail with trained staff consultation. dm-drogerie markt and Rossmann locations in German urban centers command premium positioning.
- Specialty Shops:Curated selection for culinary and mixology enthusiasts. Limited footprint in Milan, Barcelona, and Paris gastronomy districts.
Supermarkets move the most units. Online Retail is gaining share fastest among urban professionals.
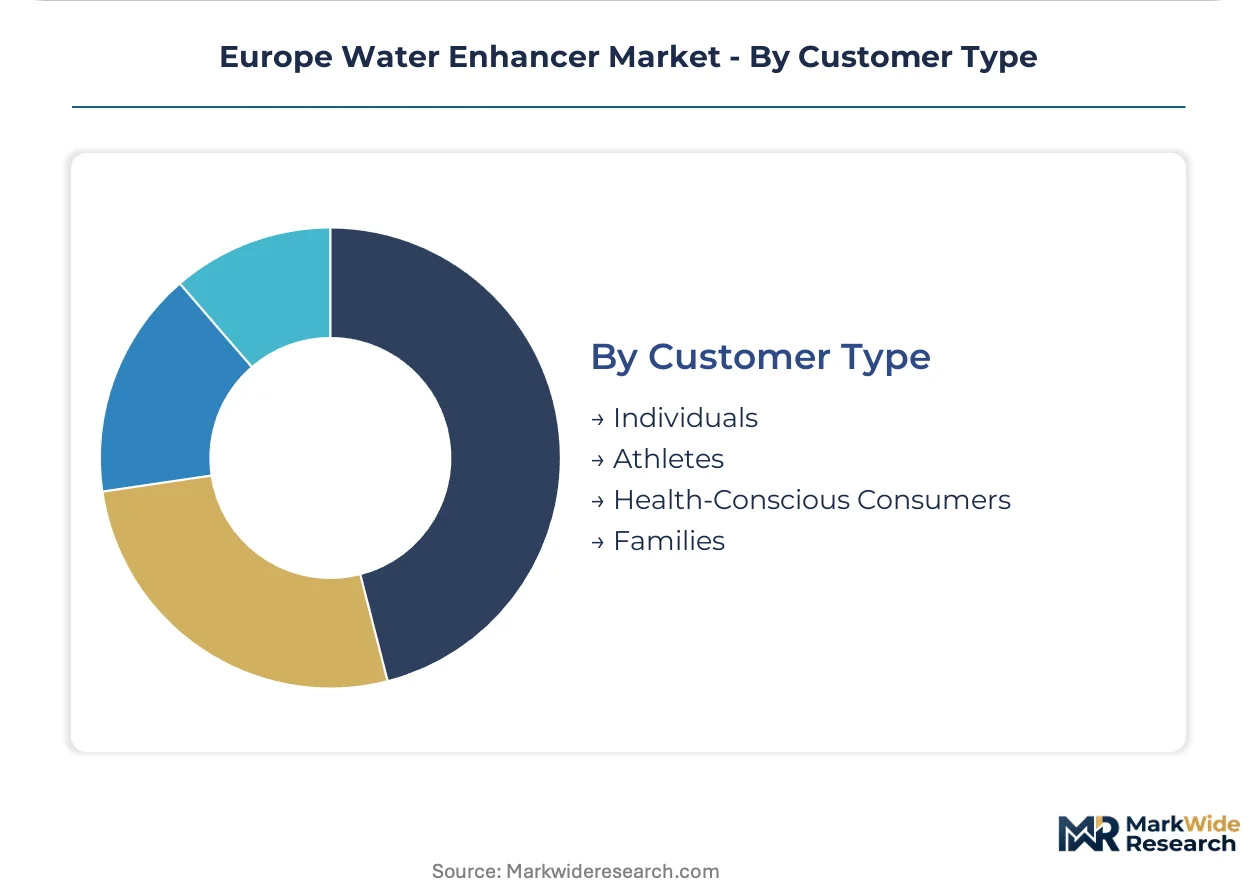
Customer Type:
Application maturity separates established Hydration users from emerging Health-Conscious segments with divergent price sensitivity and loyalty patterns.
- Individuals:Single-person households seeking flavor variety without commitment to large formats. Convenience retail in Western European capitals serves this base.
- Athletes:Structured training regimens demanding precise electrolyte dosing. Triathlon and marathon communities in Germany and France drive bulk purchasing.
- Health-Conscious Consumers:Clean-label prioritization with botanical and mineral content scrutiny. EFSA-compliant claims are table stakes for this segment.
- Families:Multi-person households balancing adult preferences with child-friendly formulations. Sugar-reduction pressures are intensifying across this base.
Individuals constitute the largest addressable base. Athletes exhibit the highest per-capita consumption intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for botanical extracts and natural flavor compounds shapes competitive positioning across European markets, with Mediterranean suppliers dominating aromatic ingredient sourcing while Nordic and German blenders capture formulation value-add.
Germany
Fitness-oriented electrolyte consumption and health-store retail density drive category penetration. EFSA labeling requirements for nutritional claims enforce reformulation toward demonstrable mineral content. Munich and Berlin anchor demand concentration, with dm-drogerie markt and Rossmann chains moving premium liquid-concentrate formats through trained staff consultation.
France
Culinary applications in hospitality and sugar-reduction mandates in retail channels expand addressable occasions. ANSM oversight of botanical health claims tightens evidentiary standards for functional positioning. Lyon and Paris gastronomy districts absorb precision-dispensed spray enhancers at elevated price points, while Carrefour dominates supermarket volume throughput.
United Kingdom
Subscription-based replenishment models and workplace fountain integration reshape channel economics. REACH compliance costs for flavor compound imports favor suppliers with captive regulatory affairs capacity. London and Southeast England concentrate urban professional demand aged 25-40 who prioritize flavor variety rotation.
Netherlands
Impulse-purchase velocity in mature convenience retail and cold-chain infrastructure enable liquid-concentrate distribution. CSRD-aligned carbon disclosure requirements attract ESG-mandated procurement from institutional buyers. Amsterdam anchors direct-to-consumer platform adoption, with promotional bundling driving highest unit volumes in supermarket channels.
Poland
Underpenetrated convenience retail expansion and price-sensitive consumer segments offer first-mover positioning before category saturation. EU packaging-waste directive implementation timelines threaten single-serve sachet economics. Warsaw and Kraków concentrate emerging demand as modern trade formats expand beyond Western European saturation levels.
Europe Water Enhancer Market Competitive Landscape
Concentration sits with diversified beverage conglomerates and specialized flavor houses, creating a tiered structure where scale-driven distribution networks coexist with artisanal positioning. The vendor base spans multinational liquid-concentrate blenders, spray-dry infrastructure holders, and botanical extract specialists. Strategic archetypes include fountain-equipment integrators, health-store premium-positioned formulators, and direct-to-consumer subscription platforms. Dominant competitive moves encompass foodservice dispenser placement bypassing retail slotting fees and microencapsulation technology licensing eroding capital-intensity barriers.
Within the diversified beverage conglomerate tier, The Coca-Cola Company and PepsiCo Inc. exemplify scale-driven distribution anchoring, while Britvic PLC occupies a position bridging retail penetration and foodservice integration. Pure Flavour GmbH represents the specialized artisanal archetype concentrated in German health-store channels. These three entities illustrate the competitive spectrum from mass-market liquid-concentrate velocity to premium botanical positioning.
| Leading Market Players |
|---|
| Dyla LLC |
| Pure Flavour GmbH |
| The Kraft Heinz Company |
| Wisdom Natural Brands |
| Britvic PLC |
| The Coca-Cola Company |
| Eau Exquise |
| The Hut.com Ltd. |
| PepsiCo Inc. |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for Mediterranean botanical extracts concentrate margin pressure on smaller blenders lacking captive sourcing relationships, while German and French buyers with consolidated procurement power extract volume discounts that compress standard-format pricing tiers.
Pricing Analysis
The customization-premium spread between configured-to-order electrolyte ratios and standard Flavor Drops spans approximately three-to-one, with subscription-based replenishment models capturing recurring revenue at mid-tier price points. Price differentiation rests on EFSA-compliant mineral certification and cold-chain delivery reliability. Pricing pressure stems from REACH compliance costs elevating fixed overhead for flavor compound imports. Health-Conscious Consumers exhibit lowest price sensitivity due to clean-label prioritization, while Polish and Romanian mass-market segments drive aggressive standard-format discounting.
Supply Chain Analysis
Inventory holdings of 45-60 days for natural extracts from Spain, Italy, and Morocco expose formulators to climate-driven harvest volatility. Raw material dependencies center on Mediterranean citrus terpenes, Baltic botanicals, and South American stevia extracts. Single-source vulnerability concentrates in artisanal fruit-infusion supply where small-batch producers lack redundancy. Distribution runs through REWE and Carrefour centralized warehouses for liquid-concentrate formats, with direct-to-consumer platforms bypassing traditional wholesale tiers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and French supermarket chains with consolidated category management functions, fragmenting supplier pricing autonomy and elevating slotting-fee leverage as the dominant commercial tension.
For Market Incumbents: Fortify health-store consultation channels against dm-drogerie markt and Rossmann private-label encroachment by embedding trained staff at point-of-sale. Deepen backward integration into spray-dry infrastructure to capture margin from microencapsulation technology licensing. Prioritize EFSA dossier completion for novel botanical claims before submission windows compress further.
For New Entrants and Emerging Players: Differentiate on CSRD-aligned carbon disclosure to capture ESG-mandated institutional procurement in Netherlands and Nordic markets. Target Polish convenience retail expansion before modern trade saturation replicates Western European slotting-fee structures. Pursue foodservice fountain placement in workplace channels to bypass retail intermediary power entirely.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified beverage conglomerates seeking to divest non-core flavor-house assets with stranded spray-dry capacity. Long-term viability favors concentrated-format specialists with regulatory affairs capacity over single-serve sachet-dependent operations. Watch pending EU packaging-waste directive implementation timelines as inflection indicator for format economics restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA-Compliant Botanical Dossier Investment | Human intervention studies for immunity claims satisfy France and Italy regulatory thresholds. |
| Foodservice Fountain Equipment Placement | The Coca-Cola Company leverages existing dispenser infrastructure to bypass retail slotting fees. |
| Microencapsulation Technology Licensing | German health-store chains adopt heat-sensitive flavor formats at accelerating velocity. |
| Eastern European Distribution Expansion | Polish and Romanian modern trade formats offer first-mover positioning before saturation. |
| Subscription-Based Replenishment Platform | Berlin and Amsterdam professionals aged 25-40 drive recurring revenue through flavor rotations. |
Research Methodology
Initial hypotheses were tested against primary input from beverage R&D directors, regulatory affairs specialists at EFSA-notified bodies, health-store category managers, and cold-chain logistics coordinators, then refined through secondary validation against EFSA guidance documents, REACH registration databases, EU packaging-waste directive drafts, and Nielsen retail audit data for France and Germany. Bottom-up volume modeling triangulated with top-down value estimates across the analysis window.
Variance decomposition across product type, application, distribution channel, and customer archetype segments shaped the analytical framework, with CAGRs derived from segment-level growth rate reconciliation. Electrolyte mix customization intensity and EFSA claim substantiation timelines served as industry-specific forecast inputs throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside EFSA regulatory stability or REACH compliance cost trajectories would require recalibration. Forecasts reflect documented assumptions regarding urban convenience retail maturation and botanical extract supply consistency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
High Ratio Shortening Market
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
UK Food Flavor and Enhancer Market
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Charcoal-Infused Food Market