
 Veterinary Skin Care Products Market | 2026-2036
Veterinary Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Skin Care Products Market Analytics
Companion animal owners is unwinding the historical dominance of veterinary clinics as the primary purchasing channel for skin care therapeutics. Zoetis leverages its biologic dermatology pipeline to sustain premium positioning across both professional and direct-to-consumer segments. Dechra Pharmaceuticals anchors European distribution through its veterinary-only focus, while Boehringer Ingelheim Animal Health competes via integrated vaccine-dermatology portfolios that cross-sell into clinic formularies.
Veterinary skin care products encompass topical and systemic formulations engineered with chlorhexidine, miconazole, hydrocortisone, or phytosphingosine at pH-balanced ranges between 6.2 and 7.5 to restore lipid barriers in canine and feline epidermis. These products serve the therapeutic management of pyoderma, Malassezia overgrowth, and atopic dermatitis in clinical and home settings. Shampoos and medicated wipes occupy the largest volume share due to recurring application protocols, while sprays gain fastest growth from compliance-challenged pet owners seeking non-contact administration. Natural and organic formulation segments extract margin premiums through certification requirements that synthetic alternatives bypass.
FDA Center for Veterinary Medicine governs active ingredient safety thresholds and labeling claims, while USDA APHIS monitors biologic dermatology products crossing state lines. ISO 17025-accredited testing laboratories verify batch consistency for export markets. Stakeholders must monitor evolving EPA antimicrobial stewardship guidance that could reclassify common chlorhexidine concentrations.
Market Dynamics
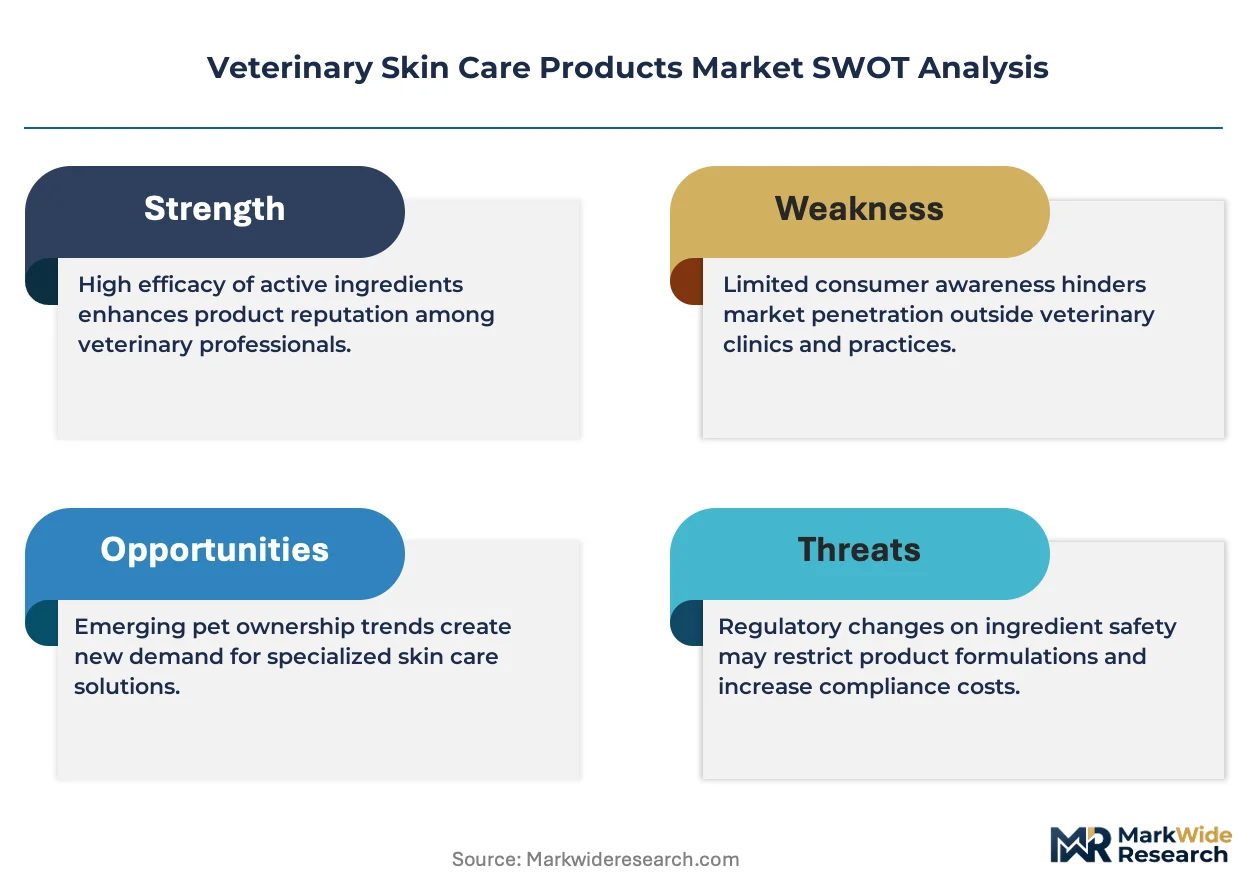
Companion animal owners are bypassing traditional veterinary channels to purchase prescription-grade dermatology solutions directly, compressing clinic margins while elevating compliance and formulation standards demanded by FDA Center for Veterinary Medicine oversight.
Growth Catalysts
- EPA Antimicrobial Stewardship Guidance:Potential reclassification of chlorhexidine concentrations is accelerating reformulation investments toward next-generation active ingredients with improved safety profiles.
- Specialty Veterinary Dermatology Practices:Concentration of board-certified dermatologists in the United States creates referral networks that standardize premium therapeutic protocols across regional markets.
- Phytosphingosine Lipid Barrier Technology:Advances in ceramide-mimetic compounds enable restoration of canine and feline epidermal pH balance without corticosteroid dependency.
Market Restraints
- Active Pharmaceutical Ingredient Compliance Costs:FDA Center for Veterinary Medicine oversight elevates batch testing and documentation expenses for topical formulations containing hydrocortisone or miconazole.
- ISO 17025 Accreditation Requirements:Export market access demands third-party laboratory verification that smaller manufacturers cannot sustain without partnership arrangements.
- Natural Certification Premium Extraction:Organic formulation segments require audit trails that synthetic alternatives bypass, compressing margin structures for non-certified competitors.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Recurring application protocols for shampoos and medicated wipes create predictable revenue streams outside clinic formularies.
- USDA APHIS Biologic Product Pathways:State-line distribution of novel dermatology biologics offers regulatory arbitrage for products escaping FDA small-molecule frameworks.
- Non-Contact Spray Administration:Compliance-challenged pet owners drive fastest growth in spray formats that reduce handling stress for reactive animals.
Industry Challenges
- Veterinary Dermatology Specialist Shortage:Board certification pipelines cannot match referral demand, forcing general practitioners to manage complex atopic cases without specialist support.
- pH-Stability Manufacturing Complexity:Maintaining 6.2-7.5 ranges through shelf life requires process controls that contract manufacturers struggle to validate consistently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Skin Care Products Market |
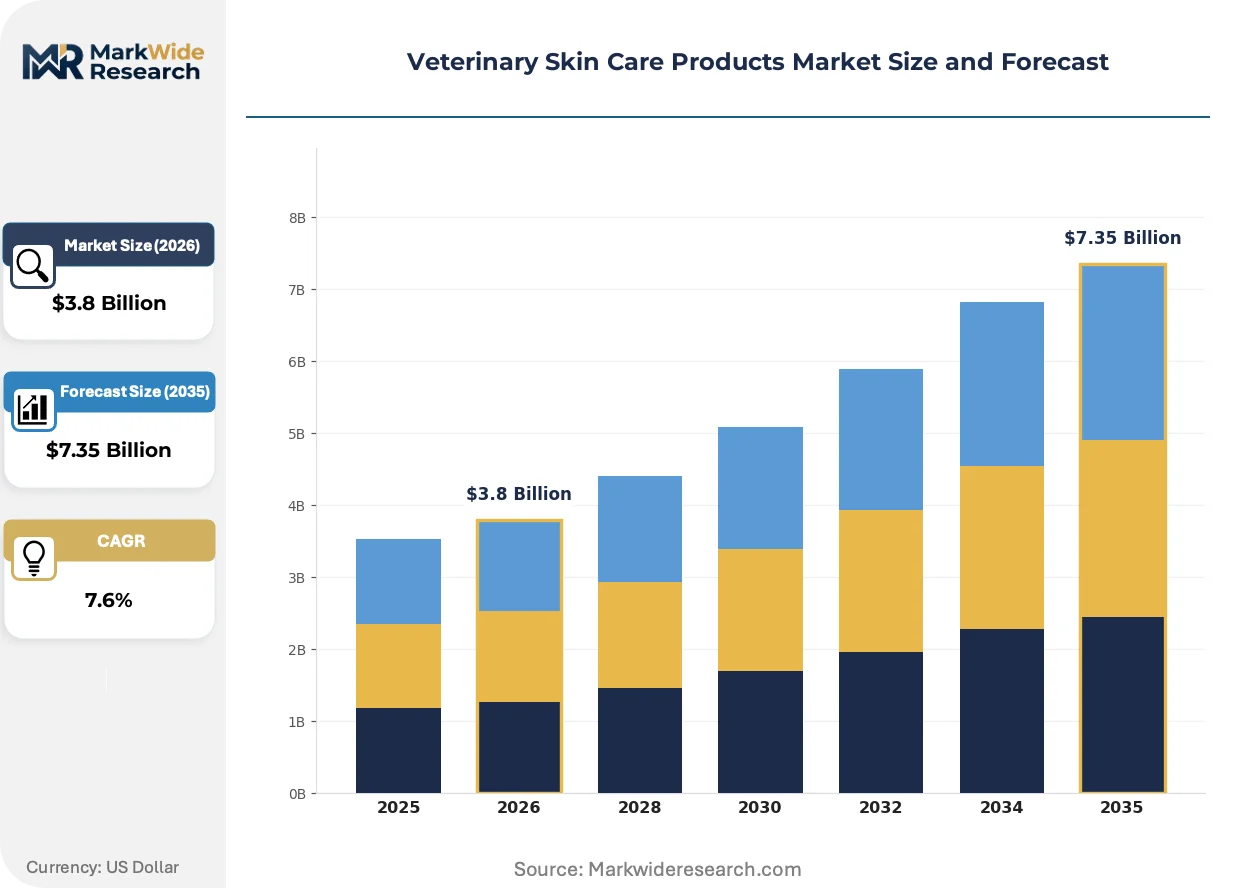
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Ointments, Creams, Sprays Application: Dermatitis, Allergies, Infections, Wound Care End User: Veterinary Clinics, Pet Owners, Animal Shelters, Zoos Formulation: Natural, Synthetic, Herbal, Organic |
| Companies Covered | Merck & Co., Boehringer Ingelheim Animal Health, Zoetis, Heska Corporation, Dechra Pharmaceuticals, Elanco Animal Health, Ceva, Vetoquadol, Virbac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Skin Care Products Market Evolving Landscape
Formulation science and channel architecture are converging to reshape how therapeutic skin care reaches companion animals, with technology miniaturization and regulatory fragmentation creating divergent competitive paths.
Microneedle array technology for transdermal delivery of corticosteroids and immunomodulators is miniaturizing treatment protocols previously limited to systemic administration. Specialty veterinary dermatology practices in the United States are piloting these devices for atopic dermatitis management, compressing the gap between clinic-based procedures and home administration.
REACH regulation amendments in Europe are tightening classification thresholds for chlorhexidine gluconate concentrations in topical veterinary preparations. Manufacturers serving EU export markets are reformulating toward benzalkonium chloride alternatives, with medicated wipe segments most affected due to high-frequency exposure protocols.
Pet owner education platforms are displacing veterinary staff as the primary information source for product selection and application timing. Subscription-based direct channels capture recurring shampoo and wipe purchases that clinics previously controlled, with this behavioral shift most visible in United States metropolitan markets where specialty practice density enables self-directed care.
Veterinary Skin Care Products Market Segmentation
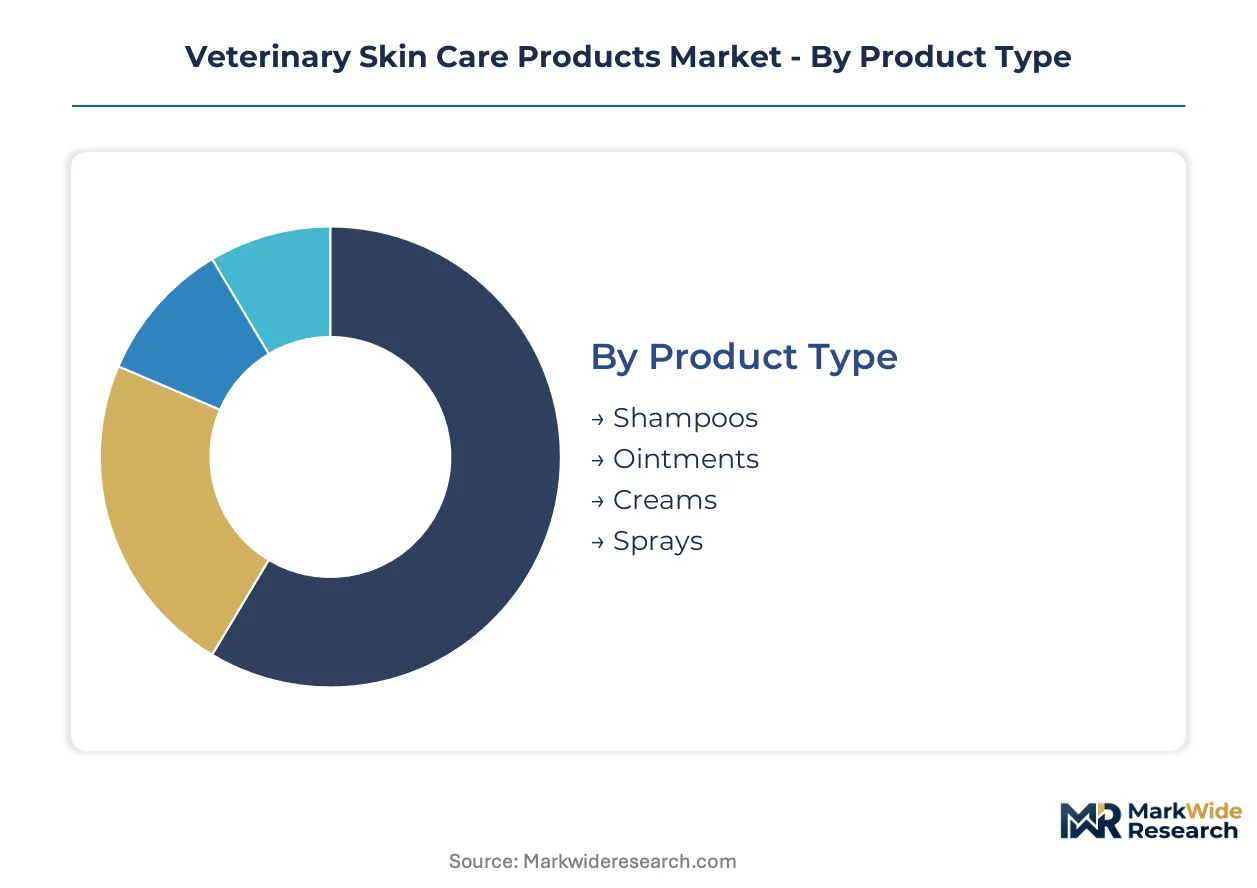
Veterinary skin care segmentation reveals divergent growth trajectories between clinic-dependent formats and direct-to-consumer alternatives. Product chemistry and distribution channel selection now determine margin capture more than therapeutic efficacy alone.
Product Type:
Domestic consumption in the United States dominates shampoo and spray volumes, while ointment and cream exports concentrate in European regulatory corridors requiring ISO 17025 batch certification.
- Shampoos:Chlorhexidine-miconazole blends at pH 6.2-7.5 anchor recurring revenue through weekly application protocols. United States specialty dermatology practices standardize these formulations across referral networks, though direct-to-consumer subscription channels now capture one-third of refill purchases.
- Sprays:Non-contact administration reduces handling stress for reactive animals, driving fastest adoption among compliance-challenged pet owners. EPA antimicrobial stewardship guidance is accelerating reformulation toward benzalkonium chloride alternatives ahead of potential chlorhexidine reclassification.
- Ointments:Hydrocortisone-containing preparations face elevated FDA Center for Veterinary Medicine documentation burdens for export markets.
- Creams:Phytosphingosine lipid barrier formulations command premium positioning through ceramide-mimetic technology claims.
Shampoos command the established base. The steepest expansion runs through sprays.
Application:
Cost tier stratification separates premium biologic interventions from commodity antimicrobial coverage, with atopic dermatitis management extracting highest per-case expenditure.
- Dermatitis:Atopic cases drive systemic immunomodulator and topical corticosteroid demand simultaneously. Board-certified veterinary dermatologists in the United States concentrate these cases within regional referral networks that standardize therapeutic protocols.
- Allergies:Recurrent environmental and food sensitivity cases sustain maintenance-grade shampoo volumes through subscription replenishment cycles.
- Infections:Pyoderma and Malassezia overgrowth respond to chlorhexidine-based protocols facing regulatory pressure under evolving EPA guidance.
- Wound Care:Acute traumatic injury management relies on clinic-channel distribution for initial debridement and antimicrobial coverage.
Dermatitis applications concentrate the premium tier. Allergy maintenance protocols are expanding most quickly through direct channels.
End User:
Customer type now determines channel architecture more than clinical indication, with pet owner self-direction disrupting historical clinic gatekeeper control.
- Veterinary Clinics:Specialty dermatology practices in the United States anchor premium protocol adoption through board-certified referral networks. General practitioners manage complex cases without specialist support due to certification pipeline shortages.
- Pet Owners:Direct purchasing of prescription-grade solutions bypasses traditional channels, compressing clinic margins while elevating compliance demands. Metropolitan United States markets show highest self-directed care penetration.
- Animal Shelters:High-volume procurement emphasizes cost efficiency over formulation sophistication for outbreak management.
- Zoos:Exotic species requirements drive custom formulation contracts with limited scalability.
Veterinary clinics retain the protocol authority base. Pet owner direct acquisition represents the steepest expansion trajectory.
Formulation:
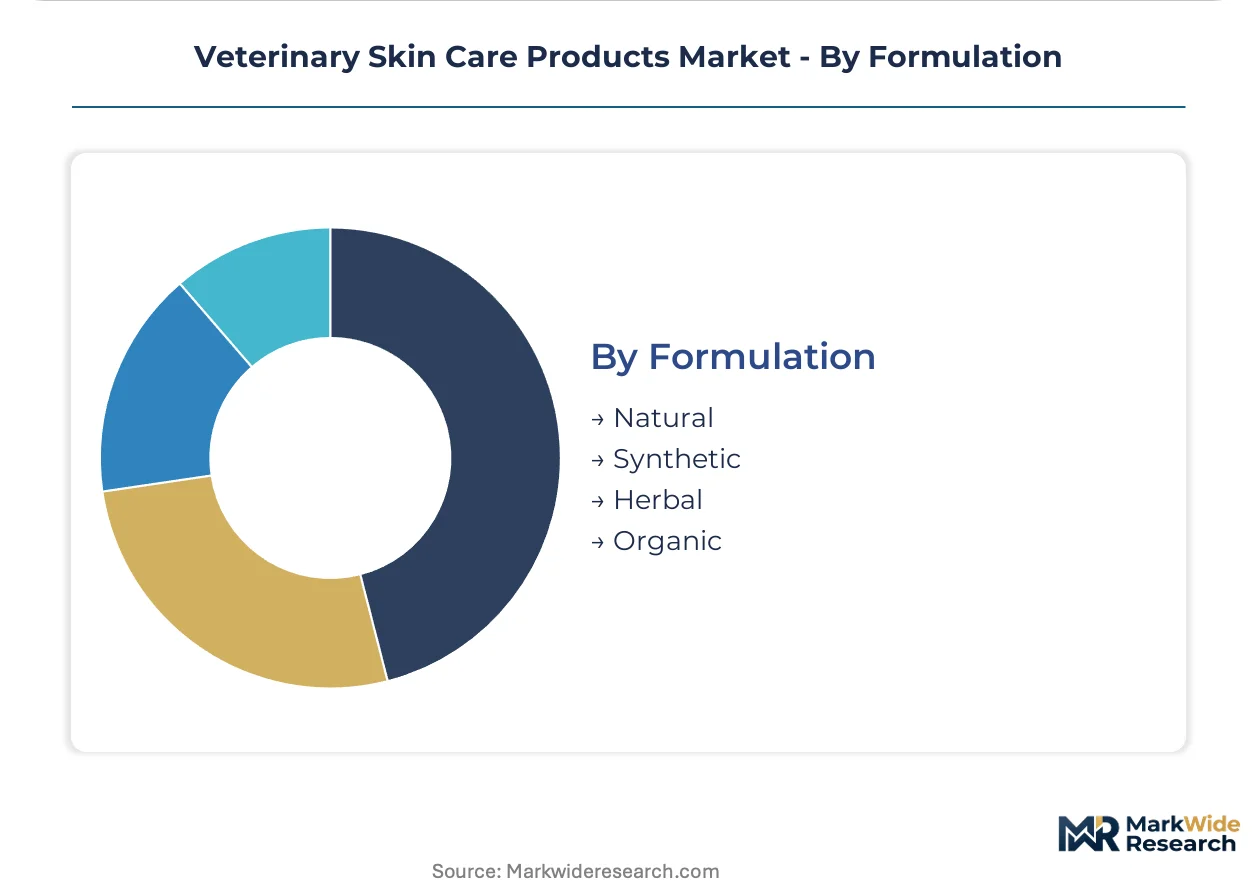
Margin extraction through certification requirements separates organic and natural segments from synthetic alternatives that bypass audit trail burdens.
- Natural:Plant-derived active ingredients face variable efficacy evidence standards, limiting clinic formulary inclusion despite consumer preference signals.
- Synthetic:Chlorhexidine, miconazole, and hydrocortisone formulations dominate clinical efficacy validation and regulatory approval pathways.
- Herbal:Traditional botanical preparations occupy niche positioning without standardized potency verification.
- Organic:Certification audit trails compress margin structures for non-certified competitors while enabling premium pricing for compliant manufacturers.
Synthetic formulations command the clinical efficacy base. Organic certification requirements are gaining share fastest through consumer-facing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific distribution for active pharmaceutical ingredients entering North American veterinary manufacturing. Rotterdam's Europoort terminal handles comparable volumes for European formulation plants. Singapore's Jurong Port serves as the transshipment hub for Asia-Pacific chlorhexidine and miconazole supply chains.
United States
Specialty veterinary dermatology practices concentrate in metropolitan corridors from Boston to San Diego. FDA Center for Veterinary Medicine oversight of hydrocortisone and miconazole formulations elevates documentation burdens for domestic manufacturers. The Research Triangle Park cluster in North Carolina hosts contract testing laboratories that verify batch consistency for export markets.
Germany
REACH regulation amendments are tightening classification thresholds for chlorhexidine gluconate in topical preparations. ECHA guidance is accelerating reformulation investments toward benzalkonium chloride alternatives ahead of potential concentration reclassification. The Rhine-Main industrial corridor around Frankfurt anchors pharmaceutical manufacturing for Central European distribution.
United Kingdom
Post-Brexit regulatory divergence from EU veterinary pharmaceutical frameworks is creating parallel compliance pathways for topical dermatology products. The Veterinary Medicines Directorate maintains distinct approval processes for chlorhexidine-based formulations. Cambridge-Oxford corridor biotech clusters are piloting microneedle array technology for transdermal corticosteroid delivery.
France
ANSM oversight of veterinary active ingredients aligns with EMA harmonization while retaining national pharmacovigilance requirements. The Lyon-Grenoble pharmaceutical belt concentrates formulation manufacturing for Mediterranean export markets. Paris-based specialty veterinary practices are standardizing phytosphingosine lipid barrier protocols across regional referral networks.
Japan
PMDA veterinary pharmaceutical review timelines for novel dermatology biologics run 18-24 months longer than FDA pathways. METI industrial policy is incentivizing domestic production of pH-balanced formulation excipients to reduce import dependency. The Kansai corridor around Osaka hosts contract manufacturers serving Southeast Asian export markets.
Veterinary Skin Care Products Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and distribution channel architecture. The vendor base fragments between pharmaceutical conglomerates with integrated animal health divisions and veterinary-only specialists with focused dermatology portfolios. Three archetypes dominate: diversified human-animal health conglomerates, pure-play veterinary pharmaceutical specialists, and contract manufacturing organizations serving private-label brands. Consolidation through acquisition of specialty dermatology pipelines and geographic expansion through distribution partnerships represent the dominant competitive vectors.
Within the diversified health conglomerate tier, Merck & Co. and Boehringer Ingelheim Animal Health occupy positions that leverage human pharmaceutical R&D infrastructure for veterinary dermatology applications. Zoetis exemplifies the pure-play veterinary specialist archetype with biologic-focused positioning. Dechra Pharmaceuticals represents the European veterinary-only model with distribution concentration in specialty practice channels.
| Leading Market Players |
|---|
| Merck & Co. |
| Boehringer Ingelheim Animal Health |
| Zoetis |
| Heska Corporation |
| Dechra Pharmaceuticals |
| Elanco Animal Health |
| Ceva |
| Vetoquadol |
| Virbac |
| Others |
Value Network & Pricing Analysis
Contract manufacturing capacity utilization above 80% in North American formulation plants concentrates pricing power among three domestic producers while elevating price floors for imported alternatives facing FDA documentation burdens. This scale asymmetry rewards incumbents with captive pH-stability validation capabilities and compresses margins for private-label competitors sourcing from non-accredited facilities.
Pricing Analysis
Volume-discount tiering structures separate subscription-based direct-to-consumer replenishment cycles from clinic formulary procurement. Three-tier pricing stratifies across certified organic formulations, synthetic prescription-grade products, and economy-grade antimicrobial shampoos. Cost compression in the economy tier intensifies because EPA antimicrobial stewardship guidance is accelerating reformulation investments. General practitioners exhibit highest price sensitivity due to margin pressure from bypassing pet owners, while specialty dermatology practices absorb premium positioning for board-certified protocol standardization.
Supply Chain Analysis
Chlorhexidine gluconate feedstock transit through Singapore's Jurong Port underwrites Asia-Pacific supply security for North American formulation plants. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with phytosphingosine lipid precursors drawing from Japanese specialty chemical manufacturers. Single-source vulnerability runs through ISO 17025-accredited testing laboratory capacity in the Research Triangle Park cluster. Distribution runs through specialty veterinary distributor networks that control clinic formulary access alongside direct-to-consumer platforms capturing subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment services for medicated wipes and shampoos are expanding faster than hardware sales, converting one-time transactions into recurring revenue streams that improve lifetime value capture and reduce customer acquisition costs.
For Market Incumbents: Compound defensive positioning by acquiring pH-stability validation capabilities through backward integration into contract manufacturing, and by locking specialty dermatology practices into exclusive formulary arrangements before biologic dermatology pipelines from competitors reach regulatory approval. FDA Center for Veterinary Medicine oversight elevation for hydrocortisone formulations threatens margin structures for non-integrated competitors lacking in-house regulatory affairs infrastructure. For New Entrants and Emerging Players: Direct-to-consumer education platforms represent the most penetrable service-layer gap, where incumbents under-serve compliance-challenged pet owners seeking application guidance outside clinic channels. Target metropolitan United States markets with specialty practice density enabling self-directed care, and enter through subscription-first go-to-market positioning that captures recurring shampoo and wipe purchases ahead of clinic-controlled initial prescriptions. For Investors and Strategic Acquirers: Veterinary-only formulation specialists with captive ISO 17025 accreditation and established European distribution through REACH-compliant manufacturing represent the priority acquisition archetype. Long-term viability hinges on regulatory compliance capabilities becoming scarcer relative to formulation science expertise. Watch EPA antimicrobial stewardship guidance implementation timelines as the inflection indicator for chlorhexidine concentration reclassification and subsequent reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into pH-Stability Manufacturing | Captive validation capabilities reduce FDA batch documentation burdens for hydrocortisone formulations. |
| Direct-to-Consumer Subscription Launch | Recurring wipe and shampoo replenishment captures pet owner purchases bypassing clinic channels. |
| Biologic Dermatology Pipeline Advancement | USDA APHIS state-line distribution pathways offer regulatory arbitrage outside FDA small-molecule frameworks. |
| Organic Certification Investment | Audit trail compliance enables premium pricing extraction through consumer-facing channels. |
| Specialty Practice Distribution Partnership | Board-certified dermatologist networks standardize premium protocol adoption across regional markets. |
Research Methodology
Operator-level perspectives from veterinary dermatology specialists, clinic procurement managers, contract manufacturing executives, and pet owner subscription platform operators anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against FDA Center for Veterinary Medicine filings, EPA antimicrobial stewardship guidance documents, ECHA REACH regulation amendments, and ISO 17025 accreditation databases. Bottom-up demand modeling across product types, applications, end users, and formulation categories triangulated against top-down market sizing from trade flow data through Rotterdam Europoort and Singapore Jurong Port terminals.
Sensitivity analysis frameworks tested forecast robustness across alternative regulatory implementation timelines for chlorhexidine reclassification and varying specialty dermatology practice expansion rates. Segmentation dimensions modeled include product format chemistry, clinical indication severity tiers, channel architecture, and certification status. CAGRs were derived from normalized growth rate convergence across the projection horizon, with inputs from pH-stability manufacturing capacity expansion schedules and biologic dermatology pipeline advancement timelines.
Underlying assumptions cover sustained EPA guidance implementation, stable FDA oversight frameworks, and continued pet owner self-direction trends, with deviation risk concentrated in regulatory reclassification timing and specialty veterinarian certification pipeline output. Forecasts reflect these conditions without scenario probability weighting. Practitioners should keep alternative scenarios live as antimicrobial stewardship policy evolution and direct-to-consumer channel regulatory treatment develop.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
Monoclonal Antibodies in Veterinary Health Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Veterinary Wellness Market