
 China Real Time Payments Market | 2026-2036
China Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
China Real Time Payments Market Outlook
Payment engineering talent scarcity is bifurcating platform development timelines across China's real time payments landscape. Ant Group Co., Ltd. (Alipay) leverages its merchant ecosystem density to dominate QR-code transaction routing at physical retail points. Tencent Holdings Ltd. (WeChat Pay) anchors social-commerce payment flows through mini-program integration. Huawei Technologies Co., Ltd. (Huawei Pay) differentiates via NFC hardware-software stack control across its device installed base.
Real time payments constitute funds transfer systems that clear and settle transactions within seconds through continuous processing architectures, typically operating on ISO 20022 messaging standards with sub-10-second confirmation loops. Merchant Payments within Transaction Type segments sustains the largest volume pool as street-level vendors adopt QR-code acceptance. Mobile Payment within Payment Method segments leads consumer-facing interfaces, while Digital Wallet competes for cross-platform loyalty consolidation. NFC within Technology segments occupies premium device-authenticated use cases despite QR dominance in mass-market penetration.
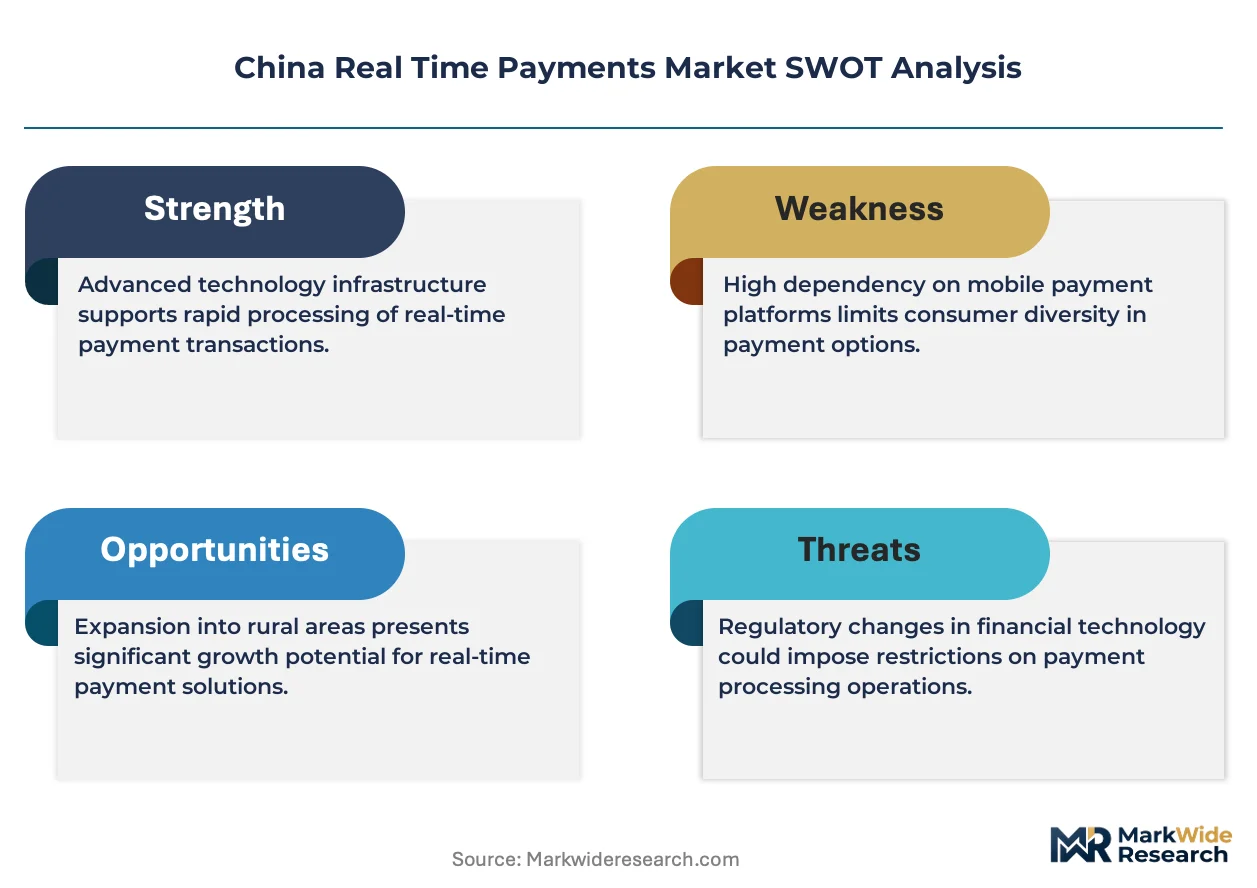
PBoC licensing frameworks and SAMR antitrust oversight constrain platform interoperability mandates and data localization requirements. NMPA fintech regulations shape capital reserve ratios for non-bank payment institutions, directly affecting market access thresholds. Stakeholders must monitor PBoC digital yuan expansion timelines against commercial wallet profit model compression.
Market Dynamics
PBoC digital yuan trials are compressing commercial wallet profit margins while forcing infrastructure upgrades across China's real time payments stack. Merchant acquirers face margin compression as interchange fee ceilings tighten under SAMR antitrust oversight.
Growth Catalysts
- MIIT 5G Infrastructure:Sub-10 millisecond latency enables sub-second payment confirmation loops at physical retail points. Dense base station deployment in Guangdong province accelerates edge-computing transaction processing.
- Tier-three City Penetration:Mobile wallet adoption deepens in inland provincial capitals as QR-code acceptance hardware costs fall below merchant threshold prices. Street-level vendor digitization concentrates transaction volume growth.
- Dual Carbon Goals:PBoC green finance mandates steer capital toward low-energy payment clearing architectures. Carbon-neutral data center requirements accelerate cloud migration for payment processors.
Market Restraints
- Capital Reserve Requirements:NMPA fintech regulations mandate 100% reserve ratios for non-bank payment institutions, compressing net interest margin income and raising entry barriers for new licensees.
- Data Localization Mandates:SAMR cross-border data transfer restrictions fragment technical architectures, forcing redundant domestic infrastructure investment that duplicates global cloud footprints.
- QR-code Saturation:Ubiquitous low-cost acceptance hardware eliminates premium pricing for basic transaction routing, commoditizing mass-market payment processing.
Strategic Opportunities
- Sichuan-Chongqing Corridor:Underpenetrated western manufacturing hubs present whitespace for B2B real time settlement networks serving supplier financing workflows.
- IoT Payment Convergence:Connected vehicle and smart appliance integrations create autonomous transaction channels beyond smartphone dependence.
- PBoC Wholesale CBDC:Central bank digital currency infrastructure for interbank settlement opens API monetization opportunities for licensed technical service providers.
Industry Challenges
- ISO 20022 Migration:Legacy message format conversion demands scarce payment engineering talent, extending platform modernization timelines for mid-tier institutions.
- Antitrust Compliance Complexity:SAMR market concentration reviews impose operational uncertainty on ecosystem lock-in strategies, requiring legal architecture redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Real Time Payments Market |
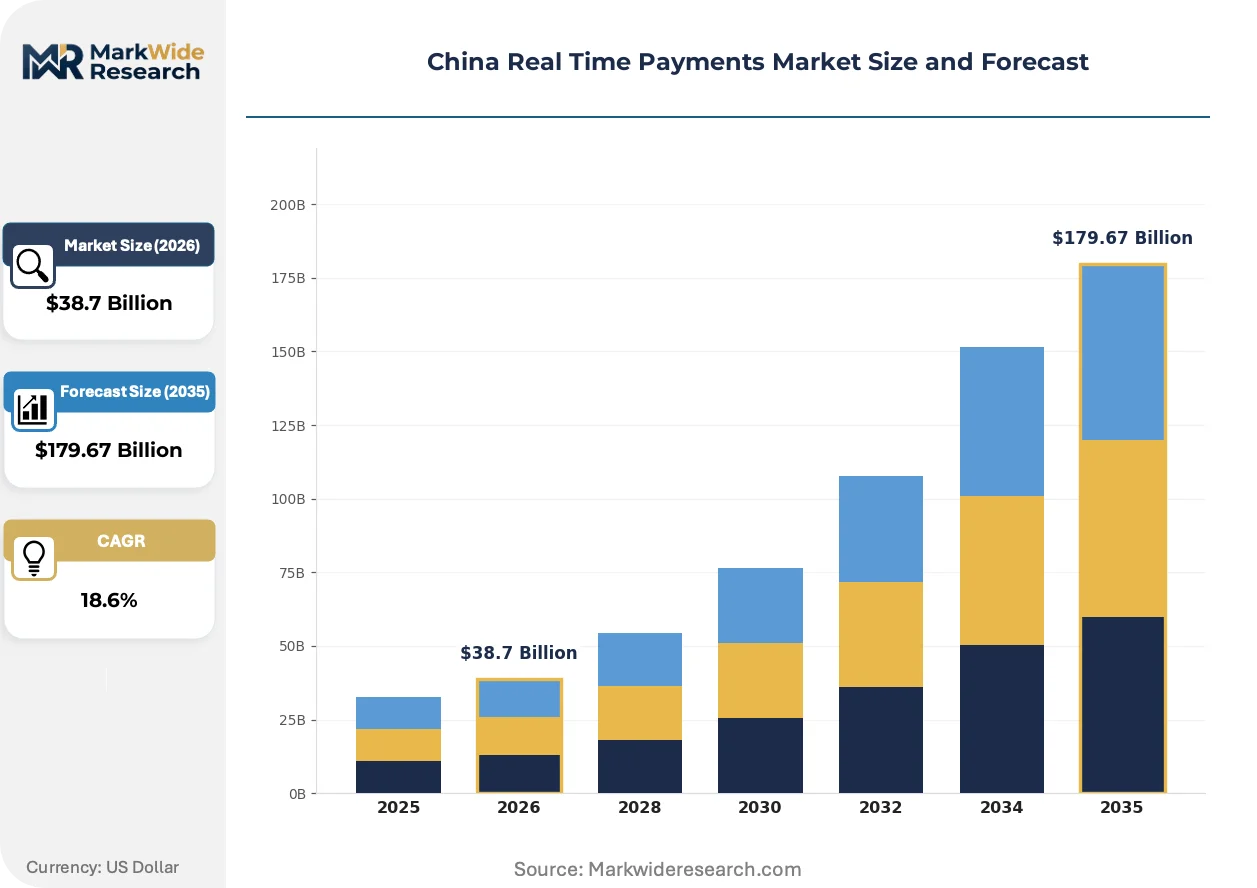
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $179.67 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Mobile Payment, Online Banking, Card Payment, Digital Wallet Transaction Type: P2P Transfers, Merchant Payments, Utility Payments, International Remittances End User: Retailers, E-commerce Platforms, Financial Institutions, Government Technology: QR Code, NFC, Blockchain, POS Systems |
| Companies Covered | JD.com, Inc. (JD Pay), NetsUnion Clearing Corp., Ant Group Co., Ltd. (Alipay), 99Bill Corporation, Lakala Payment Co., Ltd., Tencent Holdings Ltd. (WeChat Pay), Apple Inc. (Apple Pay China), Huawei Technologies Co., Ltd. (Huawei Pay), China UnionPay Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Real Time Payments Market Strategic Shifts
Hardware-software co-design is compressing authentication latency while biometric integration displaces password-dependent verification workflows. Payment interfaces embed deeper into contextual commerce moments.
Near-field communication modules embedded in wearable devices are miniaturizing to sub-2mm form factors while maintaining EMVCo security certification. Premium smartphone manufacturers embed these chips across mid-tier device lines. Physical retail checkout friction is compressing as tap-to-pay displaces QR-code scanning in high-throughput environments.
NMPA fintech licensing reforms are streamlining capital adequacy verification through risk-based supervision frameworks. Non-bank payment institutions face reduced compliance documentation burdens for low-risk transaction categories. Tier-two city fintech startups accelerate license applications under expedited review pathways.
Merchant procurement of payment acceptance hardware is fragmenting from bundled acquirer contracts toward direct OEM relationships. Street-level vendors source QR-code terminals through e-commerce platforms rather than bank distribution networks. Zhejiang province manufacturing clusters exhibit the most pronounced channel disintermediation as merchant sophistication rises.
China Real Time Payments Market Segmentation
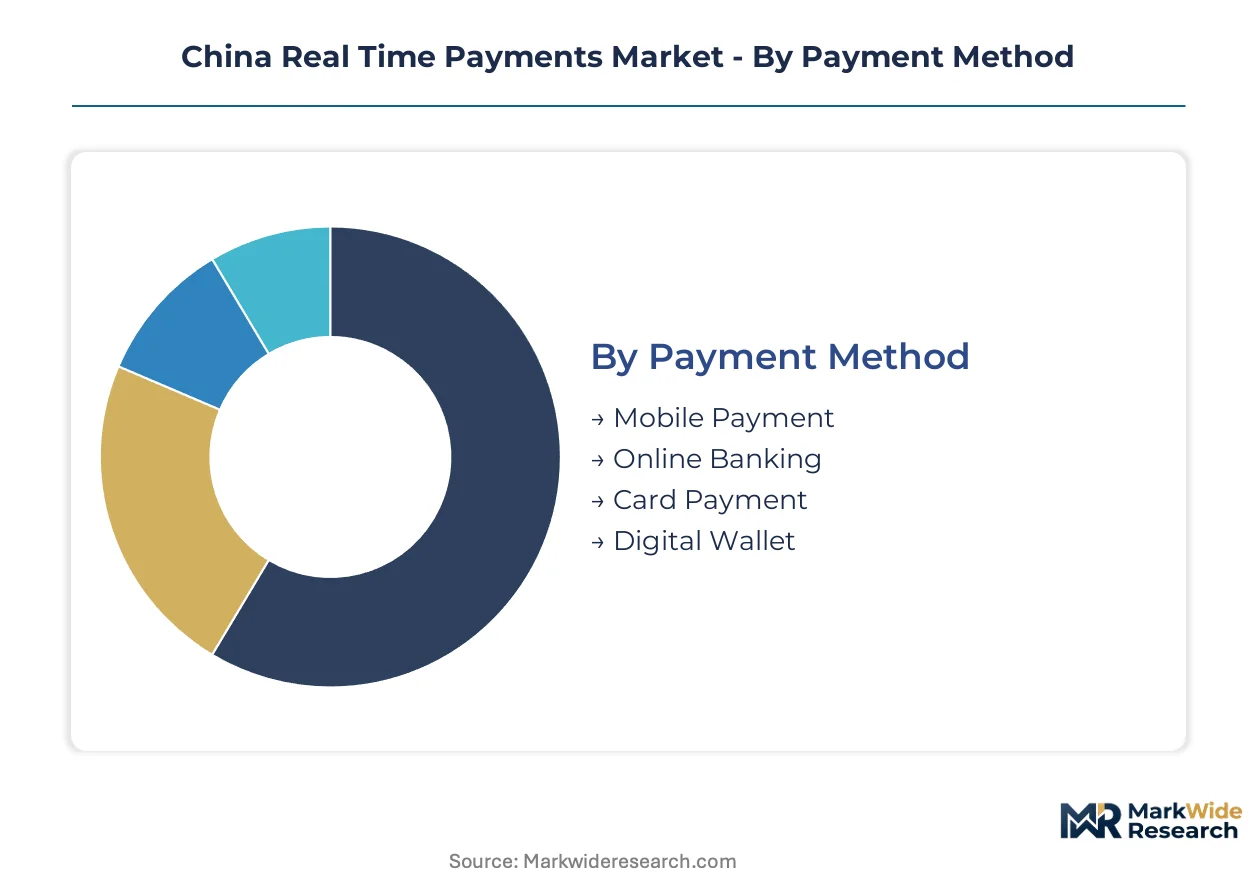
Segmentation in China's real time payments landscape reveals how infrastructure investment, regulatory licensing, and merchant digitization priorities distribute value across distinct operational layers. Each category reflects divergent margin structures and capital intensity requirements.
Payment Method:
Domestic consumption patterns anchor Mobile Payment and Digital Wallet demand, while Card Payment retains export-corridor relevance for cross-border settlement workflows.
- Mobile Payment:Smartphone-native transaction interfaces leverage 5G latency reduction for sub-second confirmation loops. Guangdong province's manufacturing corridor concentrates merchant adoption as QR-code hardware costs fall below threshold pricing for street-level vendors.
- Digital Wallet:Cross-platform loyalty consolidation architectures embed payment credentials within super-app ecosystems. Tier-three and tier-four city penetration deepens as NMPA licensing reforms streamline capital adequacy verification for non-bank institutions.
- Online Banking:Direct bank-channel interfaces serve B2B settlement workflows with higher value-per-transction profiles.
- Card Payment:EMV-compliant plastic persists in premium retail and hospitality segments requiring chargeback dispute frameworks.
Mobile Payment commands the established base. The steepest expansion runs through Digital Wallet.
Transaction Type:
Merchant-facing segments absorb the bulk of PBoC digital yuan infrastructure investment, while P2P flows face margin compression from 100% reserve ratio mandates.
- Merchant Payments:Physical retail transaction routing dominates volume pools as QR-code acceptance hardware penetrates inland provincial capitals. SAMR antitrust oversight on interchange fee ceilings compresses acquirer margins while forcing operational efficiency gains.
- P2P Transfers:Social-commerce payment flows anchor consumer retention within messaging-app ecosystems. Mini-program integration in Zhejiang province manufacturing clusters accelerates supplier financing digitization.
- Utility Payments:Recurring bill settlement interfaces aggregate fragmented municipal service providers under unified payment gateways.
- International Remittances:Cross-border corridors face SAMR data localization mandates fragmenting technical architectures away from global cloud footprints.
Merchant Payments command the established base. P2P Transfers show the steepest volume climb.
End User:
Retail merchant networks drive hardware procurement fragmentation, while government adoption channels PBoC CBDC trial expansion.
- Retailers:Street-level vendor digitization concentrates in Sichuan-Chongqing corridor whitespace as direct OEM terminal procurement displaces bundled acquirer contracts.
- E-commerce Platforms:Online marketplace settlement engines require ISO 20022 message format compatibility for cross-border transaction routing.
- Financial Institutions:Licensed banks and payment institutions face NMPA capital reserve requirements compressing net interest margin income.
- Government:Public sector procurement channels accelerate PBoC wholesale CBDC infrastructure deployment for interbank settlement modernization.
Retailers anchor the established base. Government end-use shows the steepest policy-driven expansion.
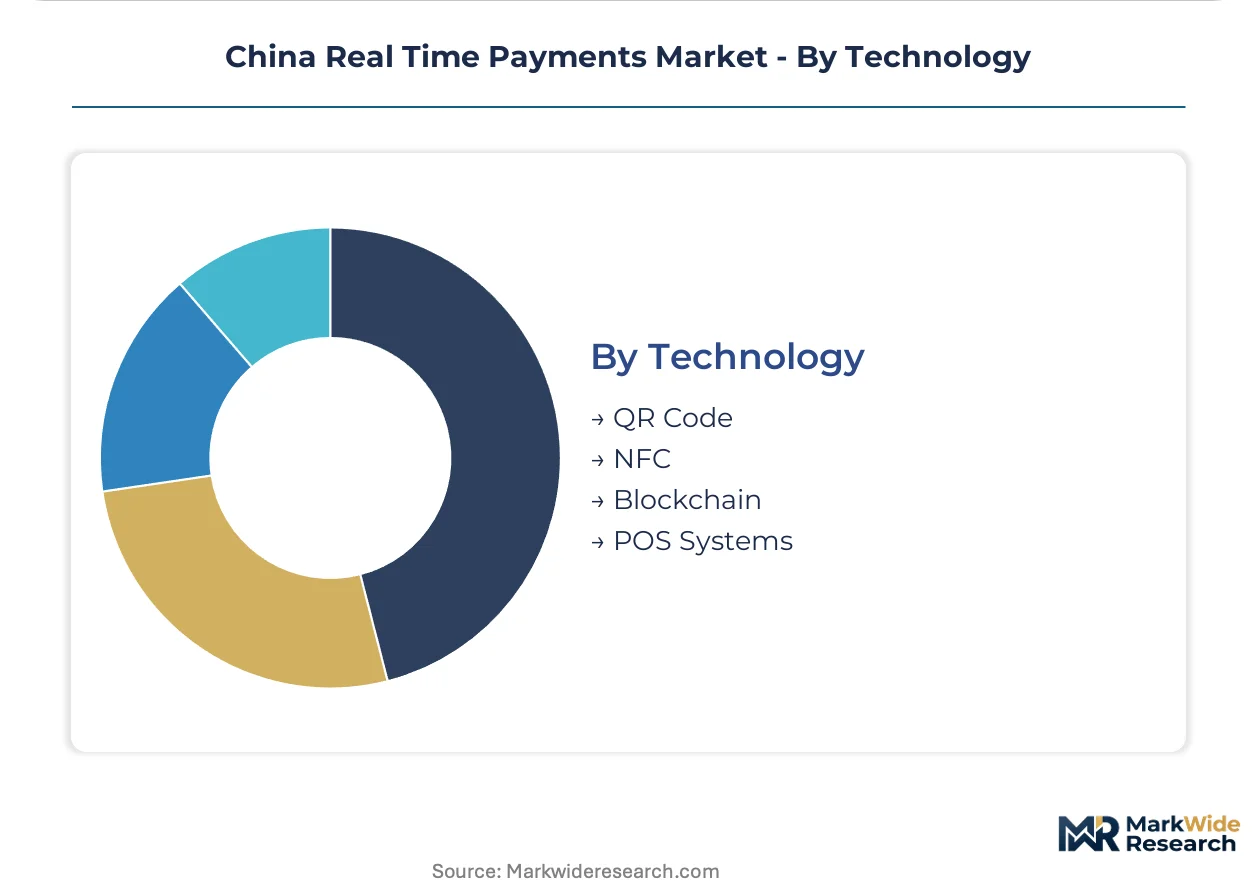
Technology:
Authentication latency reduction differentiates premium hardware-software stacks from commoditized mass-market acceptance infrastructure.
- QR Code:Ubiquitous low-cost acceptance hardware eliminates premium pricing for basic transaction routing. Commoditization pressures intensify as Zhejiang province manufacturing clusters source terminals through e-commerce platforms.
- NFC:Near-field communication modules embedded in wearable devices miniaturize to sub-2mm form factors while maintaining EMVCo security certification. Premium smartphone manufacturers deploy these chips across mid-tier device lines.
- Blockchain:Distributed ledger architectures pilot in select cross-border settlement corridors under PBoC technical supervision.
- POS Systems:Legacy terminal estates face ISO 20022 migration timelines extending modernization roadmaps for mid-tier institutions.
QR Code commands the established base. NFC gains share fastest through device authentication premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PBoC digital yuan trials and SAMR antitrust frameworks anchor infrastructure investment across China's provincial economies. Guangdong province's Pearl River Delta manufacturing corridor concentrates merchant payment digitization as MIIT 5G base station density enables sub-second transaction confirmation.
Guangdong Province
Guangdong's manufacturing corridor drives QR-code terminal penetration as street-level vendors digitize procurement workflows. SAMR interchange fee ceilings compress acquirer margins while forcing operational efficiency investments. Shenzhen and Guangzhou anchor hardware-software co-design clusters where NFC module miniaturization accelerates.
Zhejiang Province
Zhejiang's e-commerce manufacturing clusters exhibit pronounced channel disintermediation as merchants source QR-code terminals directly through e-commerce platforms. NMPA fintech licensing reforms streamline capital adequacy verification for Hangzhou-based payment startups. Ningbo port logistics corridors pilot blockchain-anchored cross-border settlement architectures.
Sichuan-Chongqing Corridor
The western manufacturing hub presents whitespace for B2B real time settlement networks serving supplier financing workflows. Dual carbon goals steer PBoC green finance mandates toward low-energy clearing architectures in Chongqing's automotive supply chain. Chengdu's fintech accelerates license applications under expedited NMPA review pathways.
Beijing-Tianjin-Hebei
The capital region channels PBoC wholesale CBDC infrastructure deployment for interbank settlement modernization. SAMR data localization mandates fragment technical architectures, forcing redundant domestic cloud investment. Zhongguancun technology corridor concentrates payment engineering talent scarcity that extends ISO 20022 migration timelines.
Jiangsu Province
Jiangsu's precision manufacturing base demands high-value B2B settlement interfaces with ISO 20022 message compatibility. MIIT 5G infrastructure sub-10 millisecond latency enables edge-computing transaction processing in Suzhou industrial parks. Nanjing's financial regulatory sandbox pilots NMPA risk-based supervision frameworks for non-bank institutions.
China Real Time Payments Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in China's real time payments architecture. Ant Group and Tencent Holdings anchor the upper tier through merchant ecosystem density and social-commerce integration respectively. Mid-tier specialists concentrate on hardware-software co-design or regional acquirer networks. Competitive positioning depends on backward integration into NFC chip supply and API monetization for CBDC infrastructure services.
Within the integrated platform tier, Ant Group Co., Ltd. and Tencent Holdings Ltd. exemplify divergent ecosystem lock-in strategies—merchant density versus social graph anchoring. Huawei Technologies Co., Ltd. occupies a position at the hardware-software boundary through device-authenticated payment stacks. China UnionPay Co., Ltd. represents the incumbent card network archetype navigating QR-code commoditization and wholesale CBDC displacement risks.
| Leading Market Players |
|---|
| JD.com, Inc. (JD Pay) |
| NetsUnion Clearing Corp. |
| Ant Group Co., Ltd. (Alipay) |
| 99Bill Corporation |
| Lakala Payment Co., Ltd. |
| Tencent Holdings Ltd. (WeChat Pay) |
| Apple Inc. (Apple Pay China) |
| Huawei Technologies Co., Ltd. (Huawei Pay) |
| China UnionPay Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sub-14-day hardware procurement cycles for QR-code terminals compress working capital requirements for street-level vendors while amplifying price transparency across Guangdong and Zhejiang manufacturing clusters. This inventory velocity concentrates bargaining power with direct OEM relationships, eroding traditional acquirer markup structures and forcing bundled service unbundling.
Pricing Analysis
Guangdong province commands a 15-20% premium over inland provincial capitals for NFC-enabled acceptance hardware, reflecting MIIT 5G infrastructure density and Shenzhen component manufacturing proximity. Pricing stratifies across premium authentication stacks, standard QR-code terminals, and economy-grade basic readers, with tier-three city procurement gravitating toward economy tiers. Cost compression in mass-market QR hardware stems from Zhejiang manufacturing cluster oversupply and direct e-commerce platform sourcing. Street-level vendors exhibit highest price sensitivity, while tier-one retail chains prioritize latency performance over unit economics.
Supply Chain Analysis
Thirty-to-forty-day component lead times for EMVCo-certified NFC modules tether payment hardware production to Taiwan semiconductor foundries and South Korea memory suppliers. China dominates final assembly and QR-code terminal manufacturing, drawing from domestic PCB fabrication and injection molding capacity. Single-source vulnerability concentrates in secure element chip supply, where global certification requirements limit qualified vendors. Distribution runs through direct OEM e-commerce channels and bank-acquirer bundled networks, with channel disintermediation accelerating in Zhejiang and Sichuan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payment engineering talent scarcity—particularly ISO 20022 migration specialists and EMVCo certification engineers—constrains platform modernization timelines and creates acquisition premiums for technical teams. This capability gap shapes competitive positioning across infrastructure tiers.
For Market Incumbents: Consolidate backward integration into NFC chip supply and captive cloud infrastructure to offset SAMR data localization compliance costs. Lock in tier-three city merchant density through subsidized terminal deployment before NMPA licensing reforms enable new entrant scale. The priority defensive lever rests on QR-code ecosystem lock-in against Huawei Pay device-authenticated displacement. For New Entrants and Emerging Players: Lead with Sichuan-Chongqing corridor B2B settlement whitespace, where supplier financing digitization lags Pearl River Delta penetration by several infrastructure investment cycles. Target underpenetrated western manufacturing hubs with API-first integration for ERP-connected payment workflows. The most viable go-to-market angle embeds into existing logistics software rather than competing for merchant acquisition head-to-head. For Investors and Strategic Acquirers: Carve-out targets emerge from state-affiliated fintech incubators seeking to monetize non-core payment processing units outside their geographic home markets. Long-term viability hinges on PBoC wholesale CBDC infrastructure service contracts rather than consumer wallet transaction economics. Watch NMPA risk-based supervision framework expansion as the signal for expedited licensing pathways that compress new entrant capitalization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secure Element Supply | Captive chip sourcing bypasses Taiwan foundry bottlenecks and SAMR data localization mandates. |
| ISO 20022 Platform Modernization | Message format conversion enables PBoC wholesale CBDC API monetization for licensed technical providers. |
| Tier-Three City Terminal Subsidization | Preemptive hardware deployment locks merchant density ahead of NMPA licensing reform acceleration. |
| IoT Payment Channel Development | Connected vehicle and smart appliance integrations create autonomous transaction channels beyond smartphone dependence. |
| Dual Carbon Data Center Migration | Carbon-neutral cloud infrastructure satisfies PBoC green finance mandates and secures state procurement eligibility. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of PBoC policy circulars, MIIT 5G deployment disclosures, and SAMR antitrust enforcement records. Primary inputs drew from payment platform engineering directors, NMPA licensing officers, merchant acquirer operations heads, and fintech startup CTOs across Guangdong, Zhejiang, and Sichuan corridors. Secondary validation incorporated PBoC digital yuan trial progress reports, MIIT base station deployment databases, and non-bank payment institution capital adequacy filings. Bottom-up transaction volume modeling triangulated against top-down infrastructure investment forecasts.
Segmentation dimensions modeled span payment method, transaction type, end user archetype, and authentication technology across the projection horizon. Value projections incorporate hardware procurement cost curves, interchange fee ceiling trajectories under SAMR oversight, and PBoC CBDC infrastructure deployment timelines. CAGRs derive from installed base penetration rates, merchant acceptance hardware replacement cycles, and 5G latency-enabled transaction throughput assumptions.
The analysis sits within stated boundaries; outcomes outside sustained MIIT infrastructure investment, NMPA regulatory stability, or PBoC digital yuan commercialization timelines would require recalibration. Forecasts embed assumptions regarding merchant digitization velocity and talent pool expansion that may shift with macroeconomic or policy discontinuities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
North America POS Terminal Market
Payments
Mobile POS Market
Payments
Indonesia Mobile Payments Market
Payments
APAC Mobile Payments Market
Payments
Dual Interface Payment Card Market
Payments
Bus Card Reader Market
Payments
Digital Transaction Management Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Vietnam Payments Market
Payments
Mobile Wallet Market
Payments
Online Charging System (OCS) Market
Payments
GCC Mobile Payment Market
Payments
Indonesia Prepaid Cards Market
Payments
Digital Payment Market
Payments
Europe Clearing Houses and Settlements Market
Payments
United States Payments Market