
 Vietnam Payments Market | 2026-2036
Vietnam Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Payments Market Analytics
Real-time payment infrastructure is fragmenting legacy banking architectures across Vietnam. VNPAY leverages its merchant-acquiring network to dominate QR-code acceptance in urban centers. Vietcombank sustains institutional trust through its correspondent banking relationships and government-linked deposit base. MoMo competes aggressively on user acquisition costs in the peer-to-peer transfer segment, anchoring its position through telco partnerships.
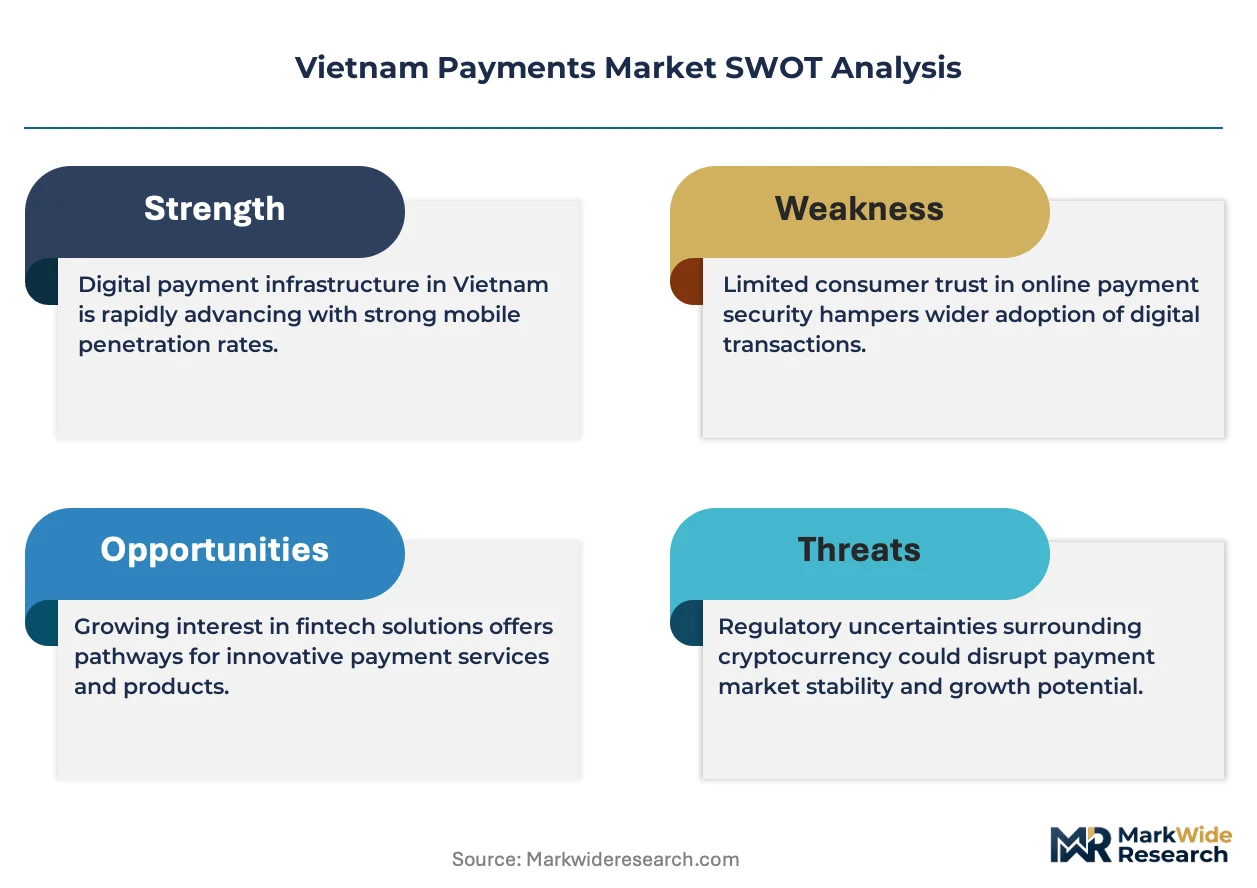
Payments systems encompass the technical protocols, clearing mechanisms, and settlement infrastructure that enable value exchange between transacting parties, typically operating on ISO 20022 messaging standards with sub-second authorization windows. Their primary commercial purpose is to reduce friction in economic exchange while managing counterparty risk through centralized or distributed ledger reconciliation. Mobile wallet adoption outpaces credit card penetration among retail consumers, reflecting Vietnam's smartphone-first consumer base and underdeveloped physical card infrastructure. Peer-to-peer transfers command disproportionate user engagement minutes relative to revenue yield, while recurring payments tied to subscription services generate superior margin pools through lower churn and predictable interchange economics.
The State Bank of Vietnam governs payment system stability through Circulars 19 and 23, mandating capital adequacy buffers for licensed e-wallet operators and prescribing interoperability standards between non-bank payment institutions and commercial banks. The National Payment Corporation of Vietnam operates the centralized switching infrastructure that binds these regulatory mandates to technical execution, controlling settlement finality across domestic rails. Stakeholders must monitor how forthcoming data localization requirements and open banking directives reshape competitive access to customer transaction histories.
Market Dynamics
Real-time payment rails are compressing settlement windows and fragmenting legacy banking architectures across Vietnam's urban centers, forcing incumbent institutions to re-platform or cede merchant relationships to agile e-wallet operators.
Growth Catalysts
- State Bank of Vietnam Circular 23:Mandated interoperability standards between non-bank payment institutions and commercial banks are accelerating merchant onboarding velocity and reducing switching friction for retail consumers.
- Smartphone-first consumer base:Vietnam's mobile penetration rate supports QR-code payment adoption without requiring physical card infrastructure investment, bypassing legacy developed-market payment evolution paths.
- Ho Chi Minh City merchant density:Concentrated digital infrastructure and real-time switching capabilities in Vietnam's commercial capital enable scalable payment rail deployment and network effect accumulation.
Market Restraints
- Capital adequacy buffers:Circular 19 mandates impose minimum reserve requirements on licensed e-wallet operators, constraining working capital flexibility for emerging fintech entrants.
- Data localization requirements:Forthcoming mandates on domestic transaction data storage will increase infrastructure capex for foreign-invested payment platforms operating in Vietnam.
- Physical cash infrastructure:Persistent rural reliance on banknotes and informal remittance channels limits digital payment penetration outside Hanoi and Ho Chi Minh City metropolitan zones.
Strategic Opportunities
- Da Nang and Can Tho secondary cities:Underpenetrated merchant-acquiring markets in Vietnam's third and fourth largest urban centers offer first-mover advantages for QR-code network expansion.
- Subscription service recurring payments:Predictable interchange economics and lower churn characteristics of utility and streaming bill payments create superior margin pools relative to peer-to-peer transfers.
- Open banking directives:Anticipated regulatory frameworks enabling consented customer transaction data sharing will reshape competitive access to credit underwriting and personalized financial services.
Industry Challenges
- ISO 20022 migration complexity:Technical protocol standardization across Vietnam's fragmented banking core systems requires substantial integration investment and coordination with the National Payment Corporation of Vietnam.
- Interoperability testing timelines:Certification delays between non-bank payment institutions and commercial bank switching infrastructure compress product launch windows and strain engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Payments Market |
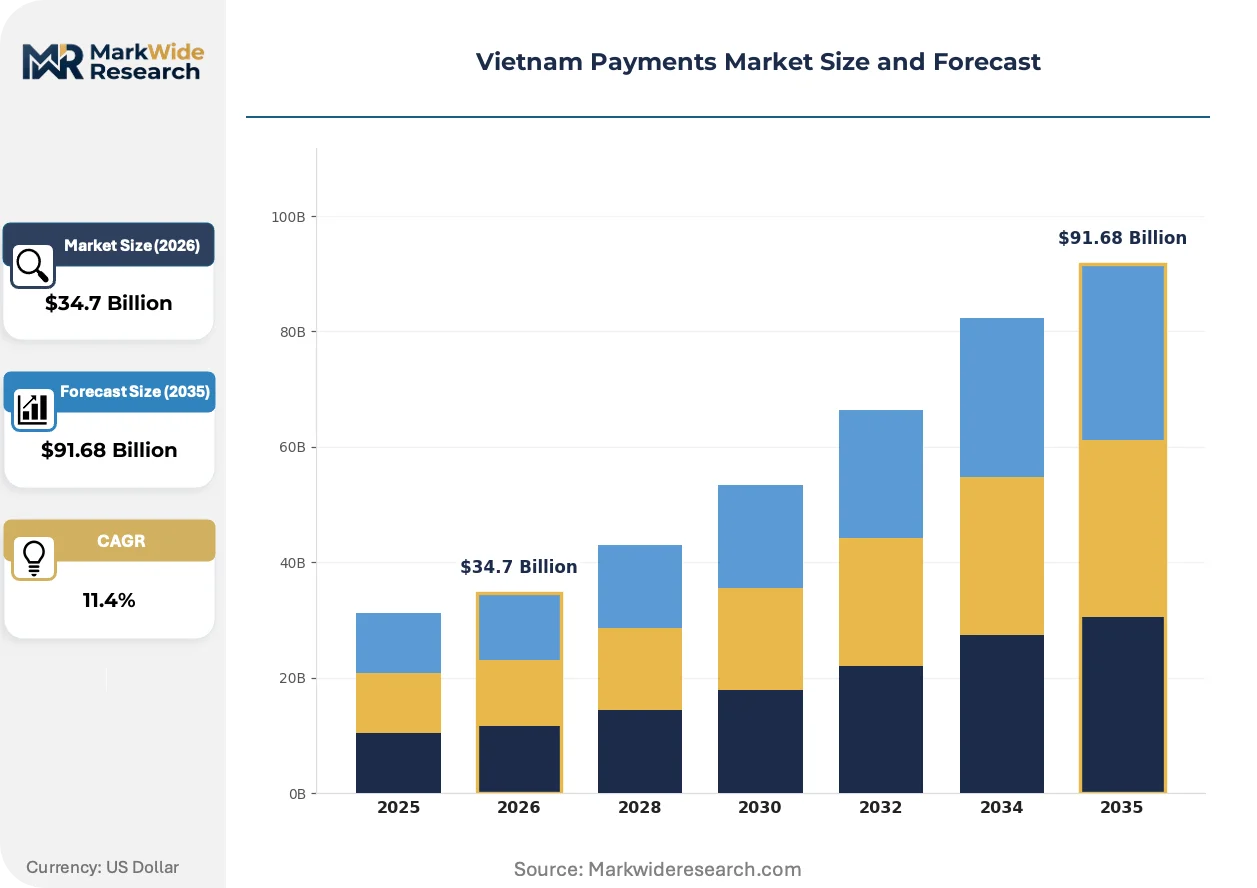
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Mobile Wallet, Bank Transfer, Cash Transaction Type: Online Payments, In-store Payments, Peer-to-Peer Transfers, Recurring Payments Customer Segment: Retail Consumers, Small Businesses, Large Enterprises, Corporates E-commerce Platform: Marketplaces, Brand Websites, Social Commerce, Subscription Services |
| Companies Covered | ZaloPay, Bank for Investment and Development of Vietnam, Vietcombank, Asia Commercial JSB, Vietnam Bank for Agriculture and Rural Development, VNPAY, VietinBank Group, 9Pay, MoMo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Payments Market Evolving Landscape
Biometric authentication and tokenized credentialing are restructuring trust architectures in Vietnam's payment ecosystem, displacing static password verification and manual KYC documentation workflows.
Biometric facial recognition integrated with national identity databases is rendering obsolete card-present verification and signature-based authentication at Vietnam's merchant points of sale. Retail banking applications in Hanoi are deploying liveness detection protocols at scale. This compression of authentication friction is accelerating checkout velocity while reducing chargeback dispute volumes for merchant acquirers.
The State Bank of Vietnam's forthcoming data localization mandates are compelling payment operators to establish domestic cloud infrastructure and encryption key custody within national borders. Foreign platform providers face infrastructure duplication costs and vendor requalification timelines. E-wallet operators with existing domestic server deployments are consolidating technical architecture ahead of enforcement deadlines.
Merchant procurement of payment acceptance hardware is shifting from perpetual license purchases toward subscription-based terminal-as-a-service models with bundled software updates. Small and medium retail enterprises in Ho Chi Minh City prefer operational expenditure structures that include automatic compliance patching and feature releases. This financing rotation is compressing sales cycles for device manufacturers while extending customer lifetime value metrics for managed service providers.
Vietnam Payments Market Segmentation
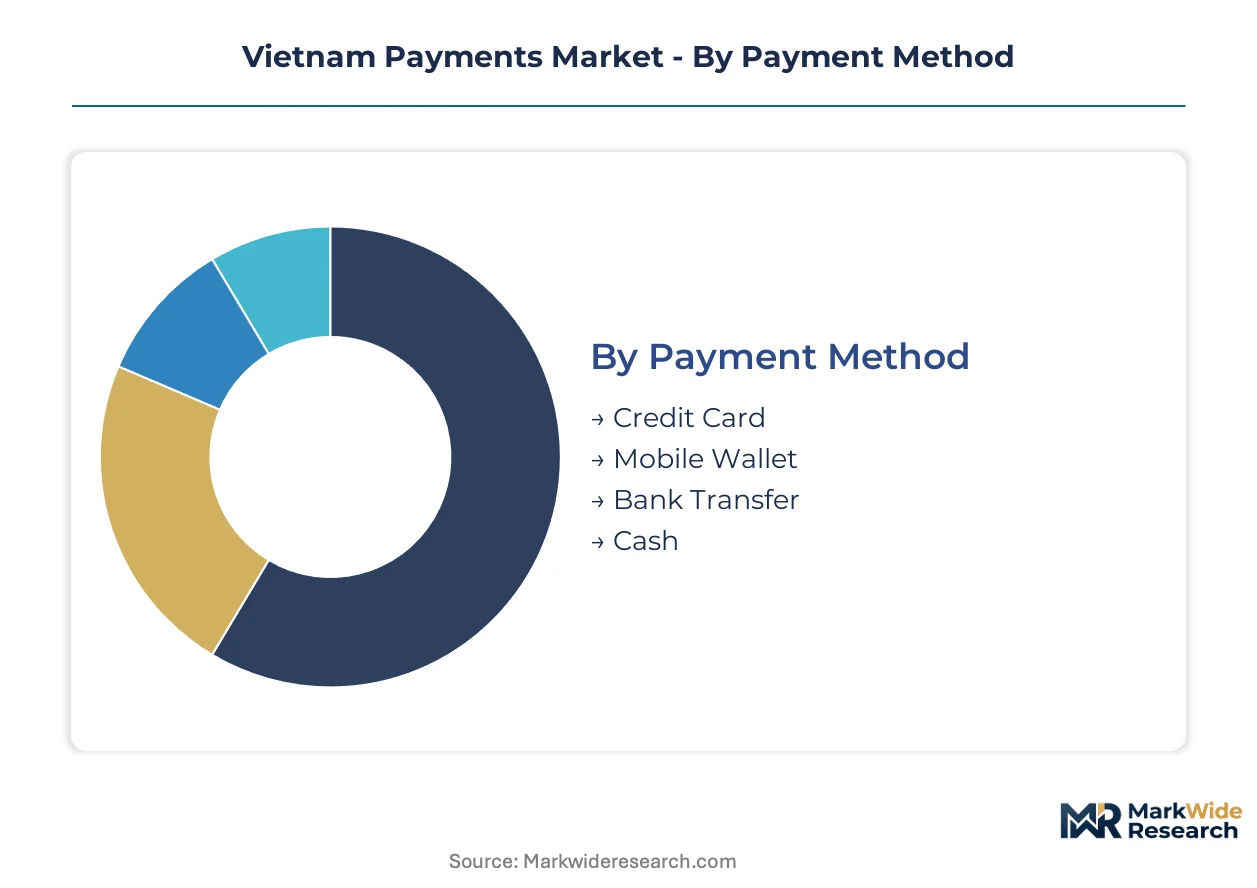
Payment method fragmentation in Vietnam reflects divergent infrastructure maturity across consumer segments. Transaction type preferences correlate with urban density and merchant digital readiness. Understanding these divides enables targeted rail deployment and interoperability investment prioritization.
Payment Method:
Cost tier differentiation separates infrastructure-light instruments from capital-intensive alternatives in Vietnam's payment stack.
- Credit Card:Physical card issuance requires correspondent banking relationships and POS terminal networks. Demand concentrates among Ho Chi Minh City corporates with cross-border procurement needs, constrained by interchange rate caps and merchant resistance to transaction fees.
- Mobile Wallet:QR-code credentialing operates on smartphone-native architectures without dedicated hardware. Hanoi retail corridors and food courts drive volume, propelled by State Bank of Vietnam licensing acceleration and telco distribution partnerships.
- Bank Transfer:Real-time account-to-account rails leverage NAPAS switching infrastructure. Corporate payroll and B2B settlements dominate usage.
- Cash:Banknote circulation persists in rural provinces beyond real-time rail coverage. Informal remittance channels sustain liquidity.
Mobile wallet commands the established base. The steepest expansion runs through bank transfer rails.
Transaction Type:
Application context determines authorization velocity requirements and fraud architecture design.
- Online Payments:Card-not-present protocols with 3D Secure authentication guard e-commerce checkouts. Ho Chi Minh City marketplace merchants absorb chargeback risk concentration.
- In-store Payments:Contactless NFC and QR-code scanning compress checkout latency at physical retail. Urban convenience stores deploy dual-rail acceptance.
- Peer-to-Peer Transfers:E-wallet address linking enables instant settlement between individual accounts. Youth demographic engagement minutes exceed revenue yield per transaction.
- Recurring Payments:Tokenized credential vaulting supports utility and streaming subscription billing. Predictable interchange economics attract processor investment.
In-store payments command the established base. Recurring payments are climbing the fastest.
Customer Segment:
Customer sophistication tier dictates service bundle complexity and support cost structures.
- Retail Consumers:Individual account holders transacting through mobile interfaces. Smartphone penetration enables wallet-first onboarding without branch dependency.
- Small Businesses:Micro-merchants requiring simplified settlement and working capital access. QR-code acceptance dominates their payment acceptance profile.
- Large Enterprises:Multi-entity corporates with treasury management and cross-border remittance requirements. API-integrated ERP connectivity is essential.
- Corporates:Multinational subsidiaries navigating Vietnam's foreign exchange controls. Compliance documentation burdens concentrate in this tier.
Retail consumers command the established base. Small businesses are gaining share fastest.
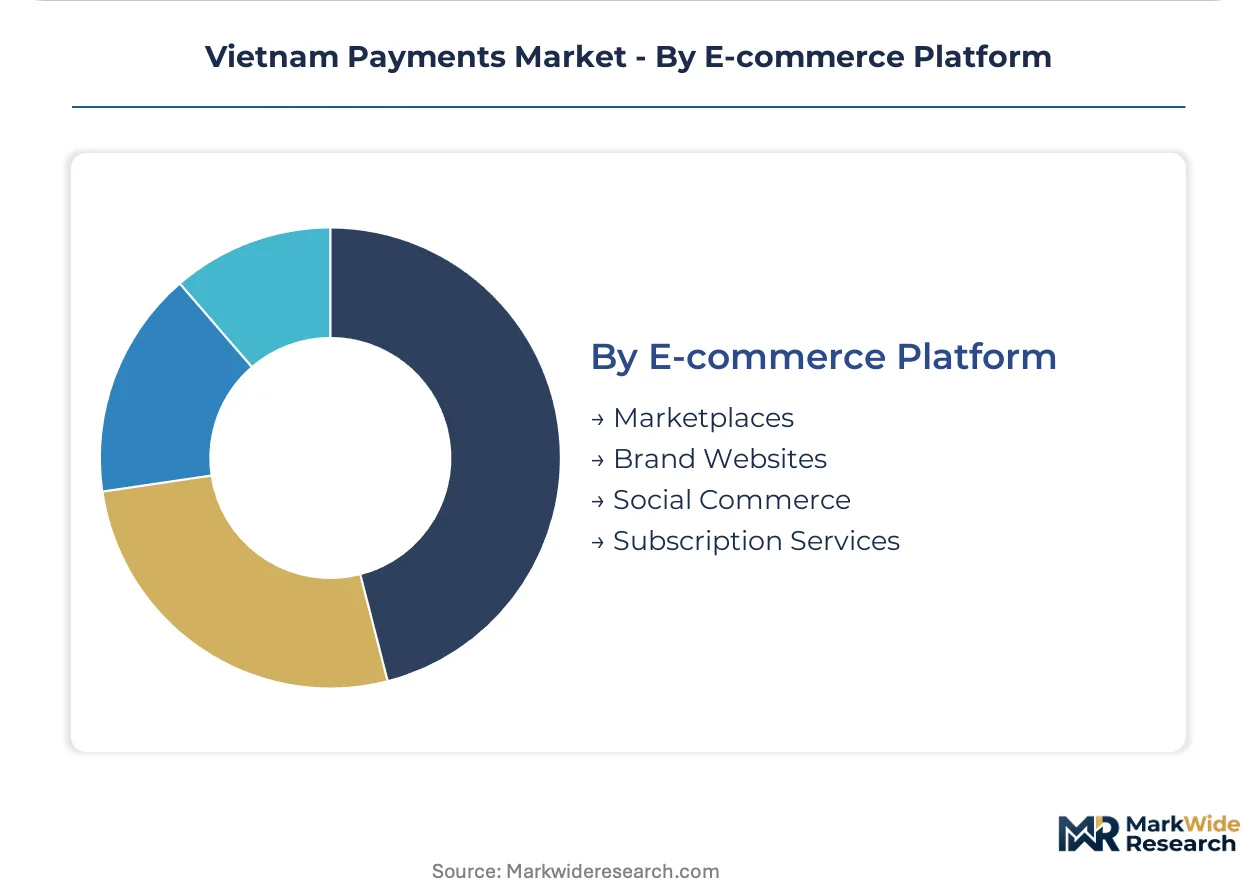
E-commerce Platform:
Platform architecture shapes payment integration depth and checkout abandonment risk.
- Marketplaces:Aggregator models with escrow settlement and seller disbursement workflows. Tiki and Shopee Vietnam anchor transaction volume.
- Brand Websites:Direct-to-consumer merchants controlling end-to-end checkout experience. Loyalty program integration drives wallet preference.
- Social Commerce:Informal selling through Facebook and Zalo livestreams with manual payment confirmation. Trust friction limits scale.
- Subscription Services:Recurring billing platforms for streaming and software access. Churn reduction through seamless credential updating.
Marketplaces command the established base. Subscription services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate treasury departments and retail consumers in Vietnam's major urban centers drive differentiated payment infrastructure requirements across sub-national markets.
Ho Chi Minh City
Foreign-invested manufacturers and export traders generate cross-border settlement demand through correspondent banking relationships. State Bank of Vietnam foreign exchange controls shape transaction documentation requirements for multinational subsidiaries. District 1 and District 7 financial corridors concentrate merchant-acquiring infrastructure and real-time switching capabilities.
Hanoi
Government procurement and state-owned enterprise payroll disbursements sustain high-value bank transfer volumes. Circular 23 interoperability mandates accelerate technical integration between municipal banks and e-wallet operators. Cau Giay and Hoan Kiem districts anchor retail QR-code payment density alongside administrative district banking clusters.
Da Nang
Tourism sector merchants seek streamlined foreign card acceptance and multi-currency settlement rails. The city's central bank branch enforces capital adequacy inspections on emerging fintech entrants. Hai Chau and Son Tra districts exhibit underpenetrated merchant-acquiring potential relative to southern metropolitan benchmarks.
Can Tho
Agricultural commodity traders and Mekong Delta logistics operators require rural-tailored payment solutions beyond urban rail coverage. Provincial banking regulations prioritize financial inclusion targets for unbanked farming households. Ninh Kieu district commercial zones represent the primary concentration of digital payment infrastructure in the region.
Hai Phong
Port logistics operators and shipping agents generate documentary trade finance and escrow payment demand. Customs modernization programs integrate electronic payment confirmation into cargo clearance workflows. Hong Bang and Ngo Quyen districts concentrate corporate banking relationships serving import-export enterprises.
Vietnam Payments Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Vietnam's payment stack, yielding a tiered structure where state-linked banks retain deposit dominance while agile fintechs capture transaction velocity. The market separates into three archetypes: legacy institutions with correspondent banking networks, telco-integrated e-wallet operators, and merchant-acquiring specialists with QR-code density. Competitive moves concentrate on interoperability certification timelines and secondary city merchant network expansion.
Among Vietnam-based payment operators, Vietcombank, VNPAY, and MoMo occupy distinct strategic positions within this architecture. Vietcombank exemplifies the institutional trust archetype through its government-linked deposit base and cross-border settlement capabilities. VNPAY anchors the merchant-acquiring specialist tier with urban QR-code network density. MoMo represents the consumer-facing e-wallet model competing on peer-to-peer transfer engagement and telco distribution partnerships.
| Leading Market Players |
|---|
| ZaloPay |
| Bank for Investment and Development of Vietnam |
| Vietcombank |
| Asia Commercial JSB |
| Vietnam Bank for Agriculture and Rural Development |
| VNPAY |
| VietinBank Group |
| 9Pay |
| MoMo |
| Others |
Value Network & Pricing Analysis
State Bank of Vietnam capital adequacy buffers function as a regulatory chokepoint that compresses working capital flexibility for emerging e-wallet entrants while simultaneously widening pricing tier spreads between bank-backed and non-bank payment operators. This single-source dependency on NAPAS switching infrastructure shapes supply chain configuration and determines which merchant segments absorb interchange cost premiums.
Pricing Analysis
Cost-plus contracts with interchange rate indexation dominate merchant-acquiring agreements, particularly for QR-code payment rails deployed through VNPAY and MoMo networks. Price differentiation hinges on transaction volume scale and NAPAS certification tier, with large Ho Chi Minh City corporates commanding sub-baseline rates while rural micro-merchants face standard-plus spreads. Cost compression in the peer-to-peer transfer tier is intensifying because MoMo and ZaloPay subsidize user acquisition through promotional cashback programs. Small businesses exhibit highest price sensitivity due to thin retail margins, whereas foreign-invested manufacturers demonstrate lowest sensitivity given cross-border settlement requirements.
Supply Chain Analysis
Supplier-financing through extended payment terms anchors hardware procurement for terminal-as-a-service models, with device manufacturers offering 90-120 day receivables to capture managed service provider contracts. Payment terminal assembly draws from China, South Korea, and Taiwan for secure element chipsets, NFC antenna modules, and biometric sensor arrays. Single-source vulnerability concentrates in NAPAS switching infrastructure, where domestic settlement finality rests on centralized technical architecture. Distribution runs through telco retail channels and direct merchant sales teams, with the latter controlling enterprise-grade API integration deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's payments market represents a service-attach opportunity where terminal-as-a-service subscription layers and merchant analytics bundles expand faster than point-of-sale hardware sales, rewarding operators that embed software revenue into physical acceptance infrastructure.
For Market Incumbents: Insulate correspondent banking relationships by deepening ISO 20022 integration with NAPAS ahead of interoperability deadlines, while acquiring QR-code density in Da Nang and Can Tho before fintech entrants achieve merchant network scale. State Bank of Vietnam data localization mandates threaten foreign platform operators, creating defensive runway for domestic server deployments. For New Entrants and Emerging Players: Agricultural commodity trading corridors in Can Tho and Mekong Delta logistics nodes offer white-space penetration where banknote reliance persists and digital merchant onboarding remains underdeveloped. Subscription service recurring payments for utility and streaming platforms present the most penetrable segment given predictable interchange economics and lower churn profiles. A telco-partnered go-to-market angle accelerates user acquisition through prepaid mobile distribution. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors merchant-acquiring specialists with dense QR-code networks and established NAPAS certification timelines. Long-term viability across the analysis window hinges on open banking readiness and data localization compliance infrastructure. The signal to watch is State Bank of Vietnam licensing velocity for e-money providers, as regulatory chokepoints determine competitive access to deposit-taking adjacent services.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant-Acquiring Network Expansion | QR-code density in Da Nang and Can Tho unlocks first-mover network effects before competitors achieve scale. |
| Terminal-as-a-Service Transition | Subscription hardware financing aligns SME procurement preferences with recurring revenue capture for managed service providers. |
| Biometric Authentication Deployment | Facial recognition integration with national identity databases compresses checkout latency and reduces chargeback dispute volumes. |
| ISO 20022 Migration Investment | Technical protocol standardization secures NAPAS interoperability certification and accelerates product launch timelines. |
| Open Banking Infrastructure Buildout | Consented transaction data sharing enables credit underwriting and personalized financial services ahead of regulatory enforcement. |
Research Methodology
The analysis maps mobile wallet operators, merchant-acquiring specialists, and correspondent banking networks, each validated through payment technology executives, State Bank of Vietnam regulatory affairs leads, merchant procurement managers, and telco partnership directors. Primary interviews with industry stakeholders combined with secondary validation from NAPAS technical specifications, State Bank of Vietnam circulars, and commercial bank annual disclosures. Bottom-up transaction volume modeling and top-down macroeconomic triangulation anchored market sizing across the projection horizon.
Assumptions held fixed include State Bank of Vietnam licensing frameworks and NAPAS switching infrastructure dominance, while smartphone penetration curves and open banking directive timing were varied across sensitivity scenarios. Segmentation dimensions modeled encompass payment method, transaction type, customer segment, and e-commerce platform architecture, with CAGRs derived from trend extrapolation and regulatory impact assessment. Interchange rate trajectories and merchant onboarding velocity served as industry-specific forecast inputs.
Practitioners should monitor State Bank of Vietnam data localization enforcement timelines and open banking directive publication for early signals of competitive access shifts. Forecasts reflect documented assumptions about regulatory stability and infrastructure investment continuity. Macroeconomic volatility, foreign exchange control tightening, or biometric authentication technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Saudi Arabia Gift Card and Incentive Card Market
Payments
E-Commerce Payments Market
Payments
Smart Home Payments Market
Payments
Japan Payments Market
Payments
Portugal Mobile Payments Market
Payments
Global Accounts Payable Software Market
Payments
Electronic Cash Register Market
Payments
Europe Fuel Cards Market
Payments
Digital Payment in Healthcare Market
Payments
Indonesia Mobile Payments Market
Payments
Biometric Payment Cards Market
Payments
Cash Management Software Market
Payments
North America Payment Analytics Software Market
Payments
Wearable Payments Market
Payments
Vehicle Toll Collection and Access System Market
Payments
New Zealand Payments Market