
 Europe Payment Analytics Software Market | 2026-2036
Europe Payment Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Payment Analytics Software Market Analytics
Real-time streaming analytics is rewriting how payment infrastructure processes transaction data across European financial networks. ACI Worldwide leverages deep integration with legacy core banking systems to sustain its position among tier-one institutions. Adyen anchors its competitive stance through unified commerce data pipelines that merge online and in-store payment intelligence. Worldpay competes on geographic coverage, operating dense acquiring networks that feed localized analytics dashboards.
Payment analytics software encompasses platforms that ingest, process, and visualize transaction data to detect anomalies, optimize routing, and generate regulatory reports, typically handling throughput exceeding 10,000 transactions per second with sub-100-millisecond latency thresholds. Cloud-based deployment leads structural growth as European banks migrate from on-premise hardware to elastic infrastructure managed by Amazon Web Services, Microsoft Azure, and Google Cloud regions in Frankfurt, Dublin, and Amsterdam. Fraud detection solutions command the strongest margin pools within the solution layer, while transaction monitoring segments expand fastest under pressure from instant payment schemes like the European Payments Initiative.
The European Banking Authority enforces DORA mandates that require financial institutions to maintain continuous monitoring of payment system resilience, directly expanding software procurement budgets. EBA guidelines on strong customer authentication under PSD2 compel banks to deploy behavioral analytics engines that score transaction risk in real time. GDPR constraints shape how payment data traverses analytics pipelines, limiting cross-border aggregation without explicit consent frameworks. Stakeholders must weigh cloud provider concentration against regulatory demands for data sovereignty as instant payment volumes scale.
Market Dynamics
Instant payment schemes across European financial networks are forcing banks to rebuild analytics infrastructure from batch-processing architectures to continuous streaming pipelines capable of sub-second anomaly detection.
Growth Catalysts
- DORA compliance mandates:The EU's Digital Operational Resilience Act requires continuous payment system monitoring, compelling institutions to expand software procurement budgets for real-time analytics platforms.
- Instant payment scheme proliferation:The European Payments Initiative and national instant payment rails generate transaction volumes that legacy batch systems cannot process, accelerating demand for streaming analytics engines.
- Frankfurt banking cluster concentration:Germany's dense concentration of systemically important banks creates procurement gravity that pulls enterprise analytics deployments across neighboring jurisdictions.
Market Restraints
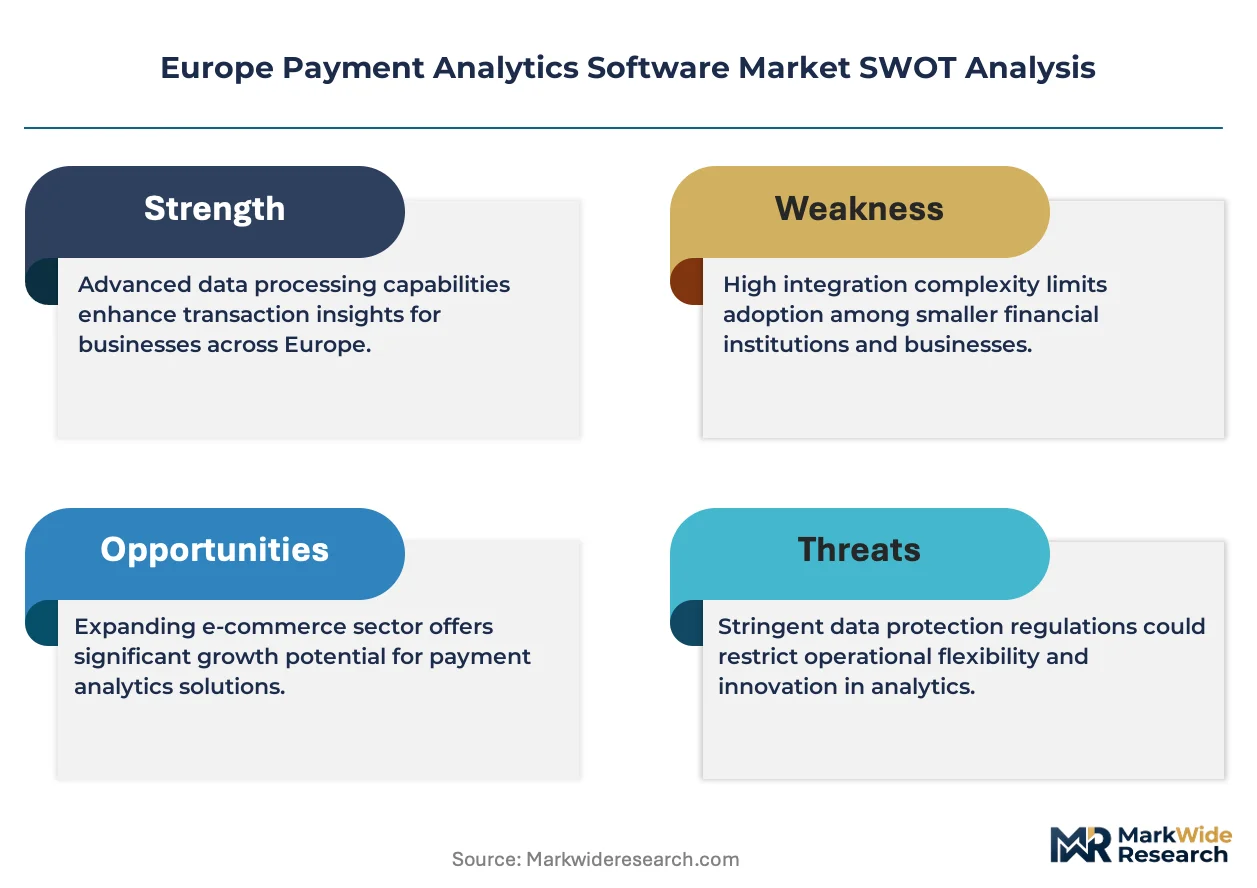
- Cloud provider concentration risk:European banks face regulatory scrutiny over dependence on Amazon Web Services, Microsoft Azure, and Google Cloud for payment data processing, creating friction with data sovereignty requirements.
- GDPR cross-border aggregation limits:Data protection constraints block seamless pooling of transaction intelligence across national boundaries without explicit consent frameworks, fragmenting analytics datasets.
- Core banking integration complexity:Decades-old mainframe architectures in tier-one institutions resist API-based connectivity, extending deployment timelines and inflating professional services costs.
Strategic Opportunities
- Behavioral analytics engine deployment:PSD2 strong customer authentication guidelines compel banks to score transaction risk using machine learning models trained on device fingerprinting and biometric patterns.
- Eastern European market penetration:Polish and Romanian banking sectors lag Western counterparts in real-time analytics adoption, creating whitespace for vendors with modular cloud-native architectures.
- Open banking data monetization:Regulatory frameworks mandating account information service provider access enable new revenue streams from aggregated payment intelligence products sold to non-bank fintechs.
Industry Challenges
- Streaming analytics talent scarcity:European financial institutions compete for engineers proficient in Apache Kafka and Flink stream processing at salaries inflated by technology sector demand.
- Legacy system API modernization:Cobol-maintained core banking platforms require expensive middleware layers to expose transaction data to contemporary analytics engines, compressing project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Payment Analytics Software Market |
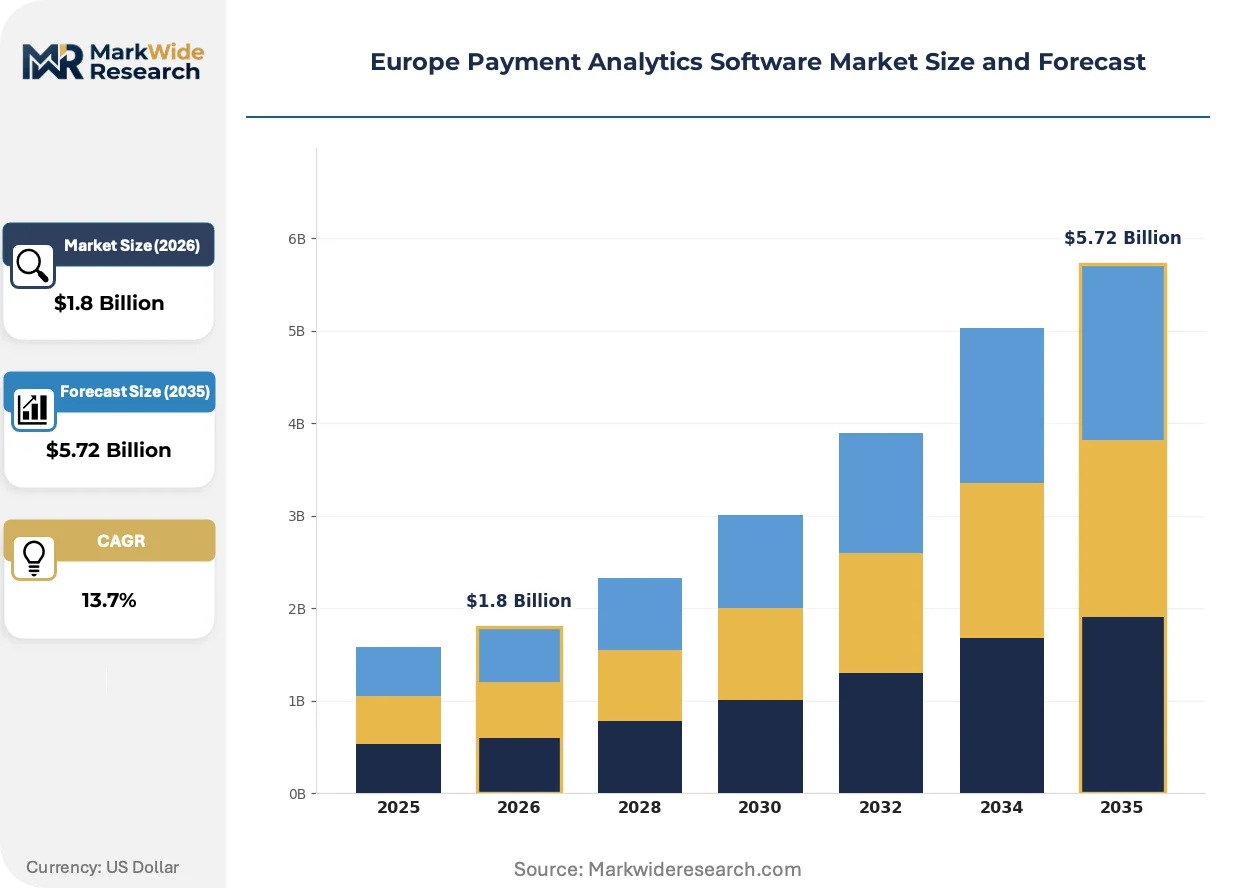
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Service End User: Retailers, Banks, Payment Processors, E-Commerce Platforms Solution: Fraud Detection, Transaction Monitoring, Data Analytics, Risk Management Application: Digital Payments, Invoice Handling, Compliance Reporting, Customer Insights |
| Companies Covered | ACI Worldwide, Adyen, Worldpay, ProfitWell, Databox, BlueSnap, HiPay, ChartMogul, Mollie, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Payment Analytics Software Market Evolving Landscape
Payment analytics infrastructure is pivoting from retrospective reporting to predictive intervention, with three concurrent shifts reshaping vendor roadmaps and bank procurement criteria across European markets.
Containerized microservices architectures are virtualizing how transaction processing pipelines deploy across hybrid cloud environments. Mid-tier banks in the Netherlands and Belgium are adopting Kubernetes-orchestrated analytics modules faster than their larger competitors, compressing time-to-value for fraud detection implementations from eighteen months to under six.
GDPR Article 25 data protection by design requirements are mandating privacy-preserving computation techniques in analytics software architecture. European regulators now expect payment intelligence platforms to embed differential privacy and federated learning capabilities, with German supervisory authorities conducting the most rigorous technical audits of vendor compliance.
Merchant acquirers are unbundling analytics capabilities from core processing contracts, creating standalone procurement decisions for payment intelligence. Large retail chains in France and Spain now separately evaluate visualization dashboards, anomaly detection engines, and regulatory reporting modules, forcing vendors to compete on component-level performance rather than bundled suite value.
Europe Payment Analytics Software Market Segmentation
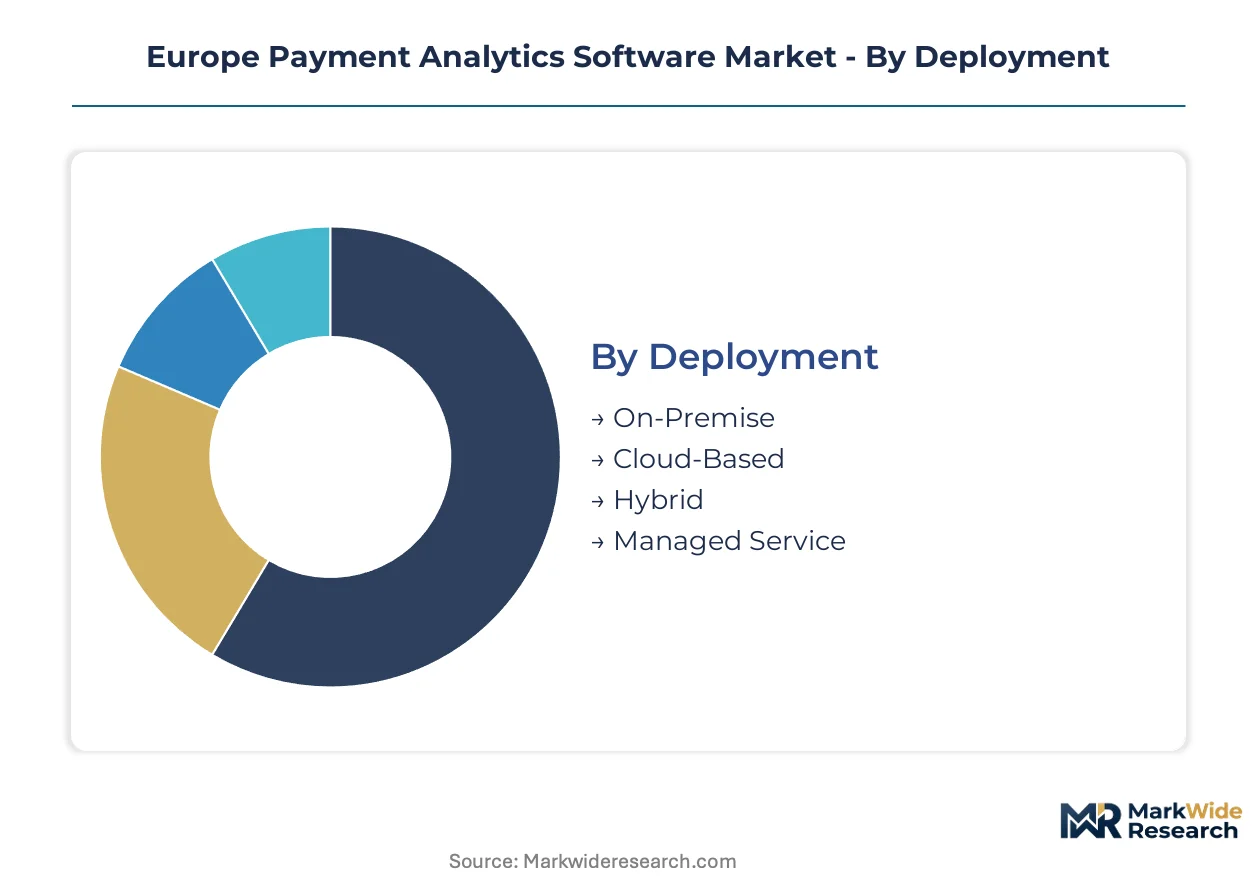
Payment analytics software procurement patterns diverge sharply across deployment models and end-user profiles. European banks prioritize resilience-certified solutions while retailers chase sub-second latency thresholds. Solution architecture choices directly determine integration complexity with legacy core banking infrastructure.
Deployment:
After-sales service intensity escalates dramatically for on-premise installations requiring dedicated field engineering teams, while cloud deployments shift support burden toward API reliability and uptime guarantees.
- On-Premise:Hardware-resident software stacks running within bank data centers demand continuous vendor presence for patch management and capacity scaling. German systemically important banks favor this model to satisfy BaFin data sovereignty audits, though professional services costs inflate total cost of ownership.
- Cloud-Based:Elastic infrastructure provisioned through AWS, Azure, and Google Cloud regions in Frankfurt, Dublin, and Amsterdam enables burst capacity for instant payment volume spikes. Dutch mid-tier banks are migrating fastest to this model to compress fraud detection deployment timelines.
- Hybrid:Split architectures keep sensitive transaction data on-premise while routing analytics workloads to cloud environments. Polish banks adopt this compromise to balance DORA resilience mandates against GDPR cross-border transfer restrictions.
- Managed Service:Fully outsourced operations where vendors assume infrastructure ownership and operational responsibility. Romanian banking sectors show rising appetite as talent scarcity for Apache Kafka and Flink engineering constrains in-house capabilities.
By volume, Cloud-Based leads. By growth pace, Managed Service is ahead.
End User:
Procurement authority concentrates with institutions bearing direct regulatory examination risk, tilting vendor R&D toward compliance automation features.
- Banks:Universal and retail banks command the largest analytics budgets driven by DORA continuous monitoring mandates and PSD2 strong customer authentication requirements. Frankfurt's banking cluster generates procurement gravity that pulls enterprise deployments across neighboring jurisdictions.
- Payment Processors:Acquiring networks and clearing houses require throughput exceeding 10,000 transactions per second with sub-100-millisecond latency. Their demand centers on real-time routing optimization to minimize interchange fee leakage across European payment rails.
- Retailers:Large retail chains in France and Spain separately evaluate visualization dashboards, anomaly detection engines, and regulatory reporting modules. Their procurement unbundles analytics from core processing contracts.
- E-Commerce Platforms:Digital-native merchants prioritize behavioral analytics engines scoring transaction risk through device fingerprinting and biometric pattern recognition.
Banks dominate absolute spending. E-Commerce Platforms are climbing the fastest.
Solution:
Margin pools vary substantially across functional modules, with detection solutions commanding premium pricing against reporting-centric offerings.
- Fraud Detection:Machine learning models trained on historical transaction patterns identify anomalous behavior in real time. GDPR Article 25 mandates differential privacy and federated learning capabilities, with German supervisory authorities conducting the most rigorous technical audits.
- Transaction Monitoring:Continuous surveillance of payment flows to satisfy anti-money laundering and sanctions screening obligations. European Payments Initiative instant payment volumes are forcing rebuilds from batch to streaming architectures.
- Data Analytics:Retrospective and predictive intelligence products aggregating payment intelligence for non-bank fintechs under open banking frameworks.
- Risk Management:Portfolio-level exposure quantification and stress testing against operational resilience scenarios.
Fraud Detection captures the steepest expansion trajectory as instant payment schemes eliminate chargeback recovery windows.
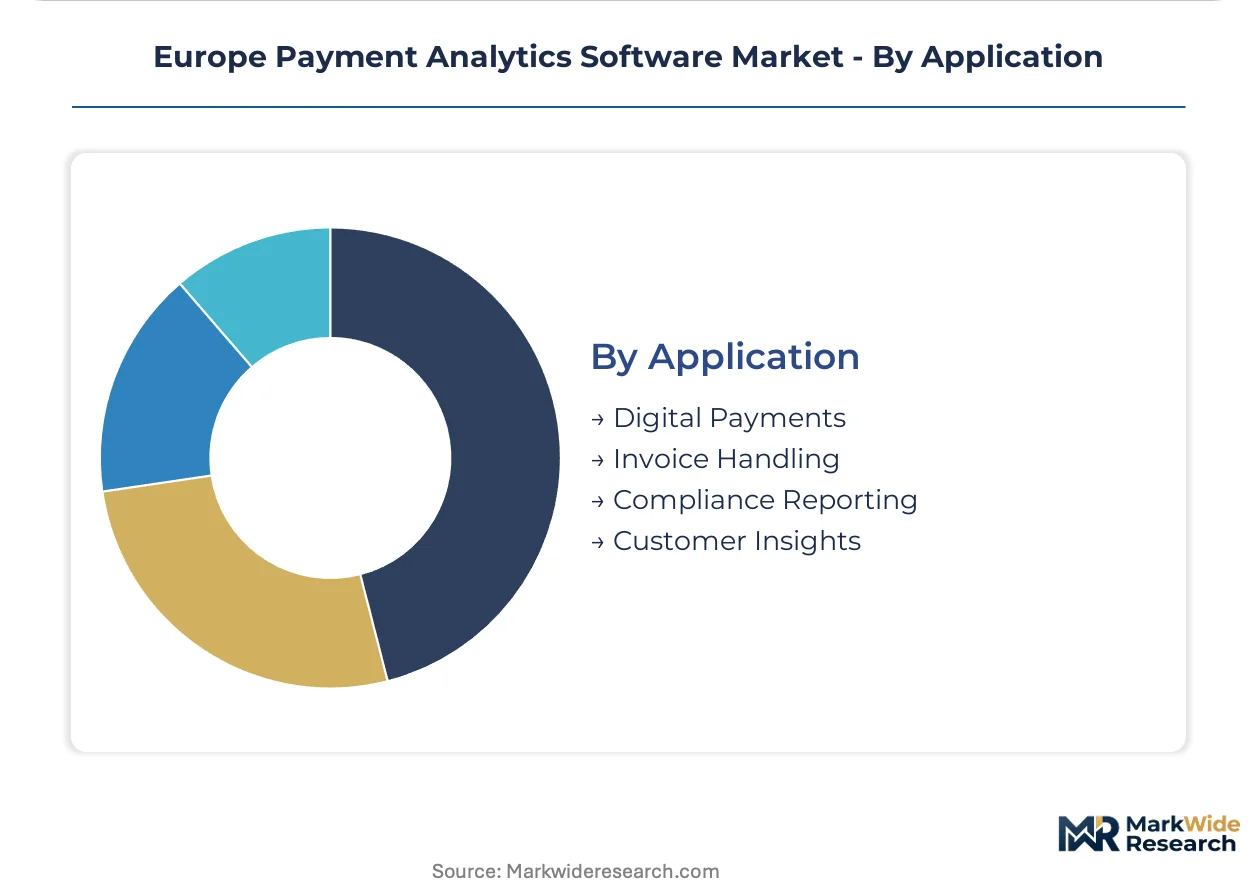
Application:
Use case specificity determines whether deployments prioritize throughput, interpretability, or audit trail completeness.
- Digital Payments:Real-time authorization scoring for card-not-present and account-to-account transfers. Belgian banks are adopting Kubernetes-orchestrated analytics modules faster than larger competitors.
- Compliance Reporting:Automated generation of regulatory submissions to the European Banking Authority and national competent authorities. DORA mandates directly expand software procurement budgets for this function.
- Invoice Handling:Accounts payable automation and supply chain financing analytics.
- Customer Insights:Merchant-facing products monetizing aggregated transaction intelligence for loyalty program optimization and location analytics.
Digital Payments leads by deployment count. Compliance Reporting is gaining share fastest under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German payment analytics vendors export enterprise software stacks to banking clusters in Switzerland and Austria, creating a Central European trade corridor that concentrates procurement gravity around Frankfurt's financial infrastructure.
Germany
Frankfurt's dense concentration of systemically important banks drives enterprise analytics procurement across neighboring jurisdictions. BaFin enforces data sovereignty audits that compel institutions toward on-premise or hybrid deployment models. The Rhine-Main metropolitan area anchors the region's highest concentration of real-time payment infrastructure investments.
Netherlands
Dutch mid-tier banks are migrating fastest to cloud-based fraud detection architectures to compress deployment timelines from eighteen months to under six. The Dutch Central Bank supervises instant payment scheme compliance under PSD2 implementation guidelines. Amsterdam's fintech corridor hosts dense clusters of Kubernetes-orchestrated analytics module adopters.
France
Large retail chains in Paris and Lyon now unbundle analytics procurement from core processing contracts, creating standalone vendor selection for visualization dashboards. The Autorité de Contrôle Prudentiel et de Résolution enforces DORA continuous monitoring mandates for systemically important institutions. The Île-de-France region concentrates merchant acquirer demand for sub-second latency payment intelligence.
Poland
Polish banking sectors show rising appetite for managed service deployments as talent scarcity for Apache Kafka and Flink engineering constrains in-house capabilities. The Polish Financial Supervision Authority aligns local regulations with EU DORA resilience requirements. Warsaw's emerging fintech hub attracts modular cloud-native architecture vendors targeting whitespace adoption gaps.
Romania
Romanian banking sectors lag Western European counterparts in real-time analytics adoption, creating procurement opportunities for vendors with elastic infrastructure offerings. The National Bank of Romania implements PSD2 strong customer authentication guidelines through technical standards on behavioral analytics. Bucharest's IT services cluster supplies engineering talent for stream processing platform implementations.
Europe Payment Analytics Software Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: legacy core banking integrators with deep mainframe connectivity, unified commerce platform operators merging online and in-store intelligence, and cloud-native specialists offering modular microservices architectures. Competitive positioning depends on geographic coverage density, legacy system integration speed, and regulatory compliance automation depth. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and vertical integration into managed service operations.
Within the legacy integration tier, ACI Worldwide exemplifies vendors sustaining position through deep core banking system connectivity. Adyen and Worldpay occupy positions among commerce platform operators competing on unified data pipeline architectures. These three companies represent distinct archetypes: the mainframe-integrated incumbent, the unified commerce native, and the geographic coverage-focused acquirer network operator.
| Leading Market Players |
|---|
| ACI Worldwide |
| Adyen |
| Worldpay |
| ProfitWell |
| Databox |
| BlueSnap |
| HiPay |
| ChartMogul |
| Mollie |
| Others |
Value Network & Pricing Analysis
Overcapacity in cloud infrastructure regions across Frankfurt, Dublin, and Amsterdam is compressing compute pricing for payment analytics workloads while simultaneously enabling vendor margin expansion through managed service bundling. This utilization dynamic rewards hyperscale-aligned software vendors with procurement leverage over mid-tier banks seeking elastic deployment economics.
Pricing Analysis
Current-generation streaming analytics engines command subscription premiums against prior-generation batch-processing architectures, while next-generation federated learning capabilities remain pre-commercial with project-based pricing. SaaS-tiered structures dominate, separating fraud detection modules from compliance reporting bundles. Price differentiation centers on DORA certification depth and real-time latency guarantees, with German systemically important banks showing lowest price sensitivity due to regulatory audit stakes. Cost compression in mid-tier cloud deployments intensifies as Dutch and Belgian banks negotiate Kubernetes-orchestrated analytics modules against eighteen-month legacy timelines.
Supply Chain Analysis
Contract manufacturing for payment analytics hardware concentrates with Flex, Jabil, and Foxconn holding server assembly capacity across Germany, Ireland, and the Netherlands. Software supply chains draw from Apache Kafka and Flink open-source distributions, commercial cloud regions, and specialized stream-processing engineering talent pools concentrated in Bucharest and Warsaw. Single-source vulnerability sits with hyperscale cloud provider concentration as AWS, Azure, and Google Cloud dominate Frankfurt-region data sovereignty zones. Distribution runs through direct enterprise sales teams serving Frankfurt's banking cluster, supplemented by systems integrators penetrating Eastern European whitespace.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payment analytics infrastructure is approaching a platform-economics inflection as open banking APIs and instant payment scheme interoperability force vendor consolidation around data pipeline standards. The European Payments Initiative's technical specifications are reshaping competitive boundaries.
For Market Incumbents: Pre-empt modular disaggregation by unbundling analytics components before merchant acquirers force the issue. Acquire Kubernetes-native specialists in Amsterdam and Brussels to compress deployment timelines below six months. Defend against cloud-native entrants by embedding differential privacy capabilities ahead of GDPR Article 25 enforcement waves from German supervisory authorities.
For New Entrants and Emerging Players: Pursue managed service penetration in Poland and Romania where Apache Kafka engineering talent scarcity constrains incumbent response speed. Target Polish banking sectors with hybrid deployment architectures balancing DORA resilience mandates against GDPR cross-border restrictions. Lead with behavioral analytics engines scoring PSD2 strong customer authentication compliance as the entry wedge.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native vendors with Kubernetes-orchestrated modules serving mid-tier Dutch and Belgian banks. Long-term viability favors platforms integrating fraud detection with open banking data monetization pipelines. Watch European Banking Authority DORA enforcement calendars as the signal for enterprise procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies online and in-store payment intelligence pipelines for merchant acquirers. |
| Strategic Partnership | Aligns analytics vendors with AWS, Azure, and Google Cloud Frankfurt regions for data sovereignty. |
| Acquisition of Specialist Firm | Absorbs Kubernetes-native modules from Amsterdam fintech corridor to compress deployment timelines. |
| Geographic Expansion | Penetrates Polish and Romanian banking sectors lagging in real-time analytics adoption. |
| Product Launch | Introduces behavioral analytics engines embedding differential privacy for GDPR Article 25 compliance. |
Research Methodology
A standing panel of payment infrastructure CTOs, fraud detection engineering leads, regulatory compliance officers at systemically important banks, and merchant acquirer procurement directors provided ongoing calibration across the study. Primary fieldwork combined structured interviews with secondary validation against European Banking Authority DORA guidance documents, PSD2 technical standards publications, and cloud provider Frankfurt-region infrastructure disclosures. Bottom-up deployment sizing across German, Dutch, French, Polish, and Romanian banking sectors triangulated against top-down software procurement budget aggregates from national competent authority filings.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling deployment mode adoption curves, end-user segment penetration rates, solution module margin trajectories, and application-specific latency requirements. Segmentation dimensions included deployment architecture elasticity, organization size tier, vertical regulatory intensity, core banking integration complexity, and regional instant payment scheme maturity. CAGRs derived from elasticity-adjusted adoption curves incorporating DORA compliance deadline effects and GDPR Article 25 technical audit timelines.
Sensitivities concentrate around European Banking Authority enforcement intensity for DORA continuous monitoring mandates and hyperscale cloud provider data sovereignty negotiations with German BaFin. Forecasts reflect assumptions on open banking API standardization velocity and instant payment scheme transaction volume scaling. Quarterly review of EBA regulatory guidance releases and Frankfurt-region cloud capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Payments As a Service Market
Payments
Online Charging System (OCS) Market
Payments
Cash Management System Market
Payments
Buy Now Pay Later Market
Payments
Netherlands Mobile Payments Market
Payments
Germany Payment Gateway Market
Payments
Fuel Cards Market
Payments
Ireland POS Terminals Market
Payments
Cyprus POS Terminals Market
Payments
China Mobile Payments Market
Payments
South Africa Gift Card and Incentive Card Market
Payments
Indonesia Payments Infrastructure Market
Payments
China Payments Market
Payments
Ghana Mobile Money Market
Payments
Greece POS Terminals Market
Payments
Japan POS Terminals Market