
 Augmented Shopping Market | 2026-2036
Augmented Shopping Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Shopping Market Intelligence
Buyer concentration in augmented shopping is decoupling from traditional retail chains toward direct-to-consumer brands and marketplace platforms. Amazon leverages its logistics-data flywheel to embed AR try-on tools throughout its e-commerce platform. Meta sustains heavy R&D spending on computer vision and spatial computing hardware that feeds downstream retail applications. Apple differentiates through tightly controlled AR software ecosystems that limit third-party commerce integration.
Augmented shopping overlays digital product visualizations onto physical environments through camera-enabled devices, typically requiring sub-50 millisecond latency for real-time rendering and millimeter-scale spatial anchoring to prevent visual drift during product placement. Its primary commercial purpose is reducing return rates and shortening purchase decision cycles by letting consumers preview fit, scale, and finish before transaction. Virtual fitting rooms now capture disproportionate investment from fashion retailers seeking to cut reverse-logistics costs, while AR glasses remain supply-constrained due to micro-display manufacturing bottlenecks and thermal management challenges. Interactive displays in physical showrooms generate higher per-foot traffic conversion than static merchandising, though deployment costs limit rollout beyond premium retail locations.
The Federal Trade Commission scrutinizes AR advertising disclosures to ensure virtual product representations do not mislead consumers on material attributes, while the EU AI Act imposes conformity assessments on biometric identification systems used in retail computer vision applications. China's SAMR enforces GB standards on data collection through AR-enabled consumer devices, creating compliance friction for cross-border platform operators. Stakeholders must monitor whether fragmented national AI governance crystallizes into de facto technology barriers that force region-specific product architectures.
Market Dynamics
Computer vision latency requirements below 50 milliseconds are forcing infrastructure rebuilds across retail technology stacks, while biometric data regulations in the European Union compel architectural redesigns of virtual fitting room deployments.
Growth Catalysts
- EU AI Act Conformity Pathways:Retailers investing early in biometric system compliance gain first-mover certification advantages for computer vision deployments across European stores.
- Reverse Logistics Cost Compression:Fashion brands deploy spatial anchoring technology to reduce fit-related returns, cutting processing and restocking expenditures in high-volume apparel categories.
- Micro-Display Supply Expansion:Asian semiconductor foundries are scaling OLEDoS manufacturing capacity, easing AR glass bottlenecks that previously constrained hardware rollout timelines.
Market Restraints
- Thermal Management Physics:AR glasses face hard power dissipation limits from compact form factors, preventing all-day battery life in consumer-grade hardware despite silicon efficiency gains.
- Cross-Border Data Friction:China's SAMR enforcement of GB standards on AR device data collection creates compliance architecture costs for platforms operating across multiple national jurisdictions.
- Spatial Computing Talent Scarcity:The shallow pool of engineers proficient in simultaneous localization and mapping (SLAM) algorithms restricts development velocity for mid-tier retailers.
Strategic Opportunities
- India PLI Scheme Alignment:Electronics manufacturing incentives under India's production-linked incentive framework attract AR hardware assembly investments serving South Asian consumer markets.
- Automotive Showroom Integration:Vehicle configurators using real-time environmental overlay technology capture premium automotive buyers seeking personalized exterior finish visualization before dealership visits.
- Furniture Scale-Accuracy Mandates:E-commerce platforms implementing millimeter-precise spatial measurement tools address consumer distrust of dimensional representations in bulky goods categories.
Industry Challenges
- FTC Disclosure Enforcement:The Federal Trade Commission's scrutiny of AR advertising representations requires legal review cycles that slow campaign deployment timelines for virtual product previews.
- Legacy POS Integration Complexity:Physical retailers embedding AR-enabled interactive displays face middleware development costs to synchronize with decades-old inventory management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Shopping Market |
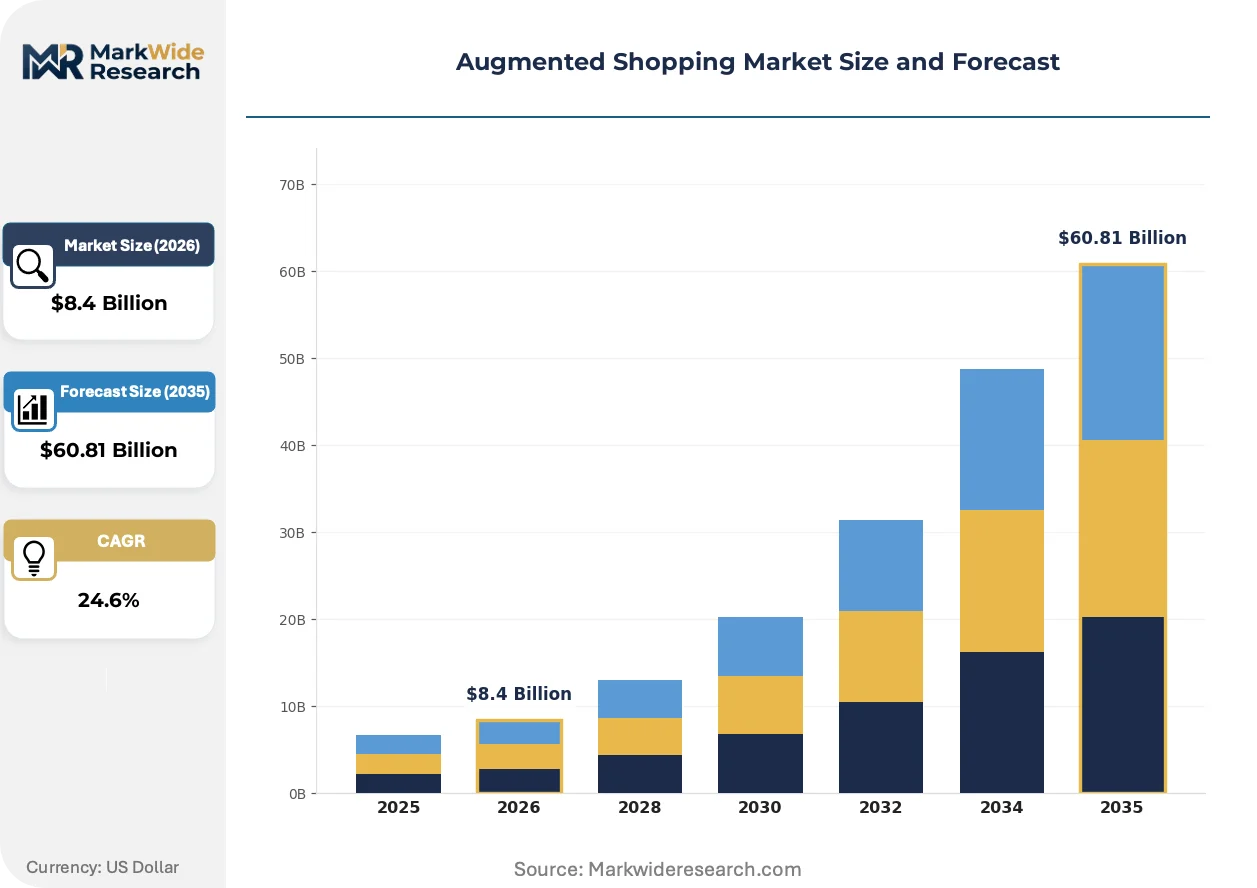
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Mirrors, AR Glasses, Virtual Fitting Rooms, Interactive Displays Application: Retail Stores, E-Commerce Platforms, Showrooms, Trade Shows End User: Fashion Retailers, Home Improvement Stores, Electronics Retailers, Automotive Dealerships Technology: Computer Vision, 3D Modeling, Gesture Recognition, AR Software |
| Companies Covered | Meta, Apple, Google, Amazon, Microsoft, Shopify, IKEA, Snap, Warby Parker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Shopping Market Strategic Shifts & Innovations
Generative AI is compressing 3D asset production pipelines for retail applications, while regulatory fragmentation forces multi-jurisdictional compliance architectures. Consumer behavior around virtual try-on is shifting from novelty to utility expectation.
Neural radiance fields (NeRF) are unifying photorealistic product visualization with real-time rendering constraints. Furniture and home décor retailers adopt NeRF-based pipelines to generate immersive previews from sparse image inputs without manual 3D modeling. This compression of asset production timelines is unifying previously separate creative and technical workflows inside retail marketing organizations.
The EU AI Act's risk classification framework for biometric identification systems imposes conformity assessment obligations on European retail computer vision deployments. Fashion retailers operating virtual fitting rooms must document algorithmic decision pathways and maintain human oversight protocols. German and French regulators are interpreting biometric scope most expansively, forcing architectural separations between identity verification and fit simulation functions.
Buyers now treat virtual try-on as a standard pre-purchase filter rather than an experimental feature. Apparel and cosmetics segments observe completion rate drops when AR tools fail to load within two seconds. South Korean and United States markets show the strongest behavioral normalization, with consumers abandoning retailers that lack spatial preview capabilities for fit-critical categories.
Augmented Shopping Market Segmentation
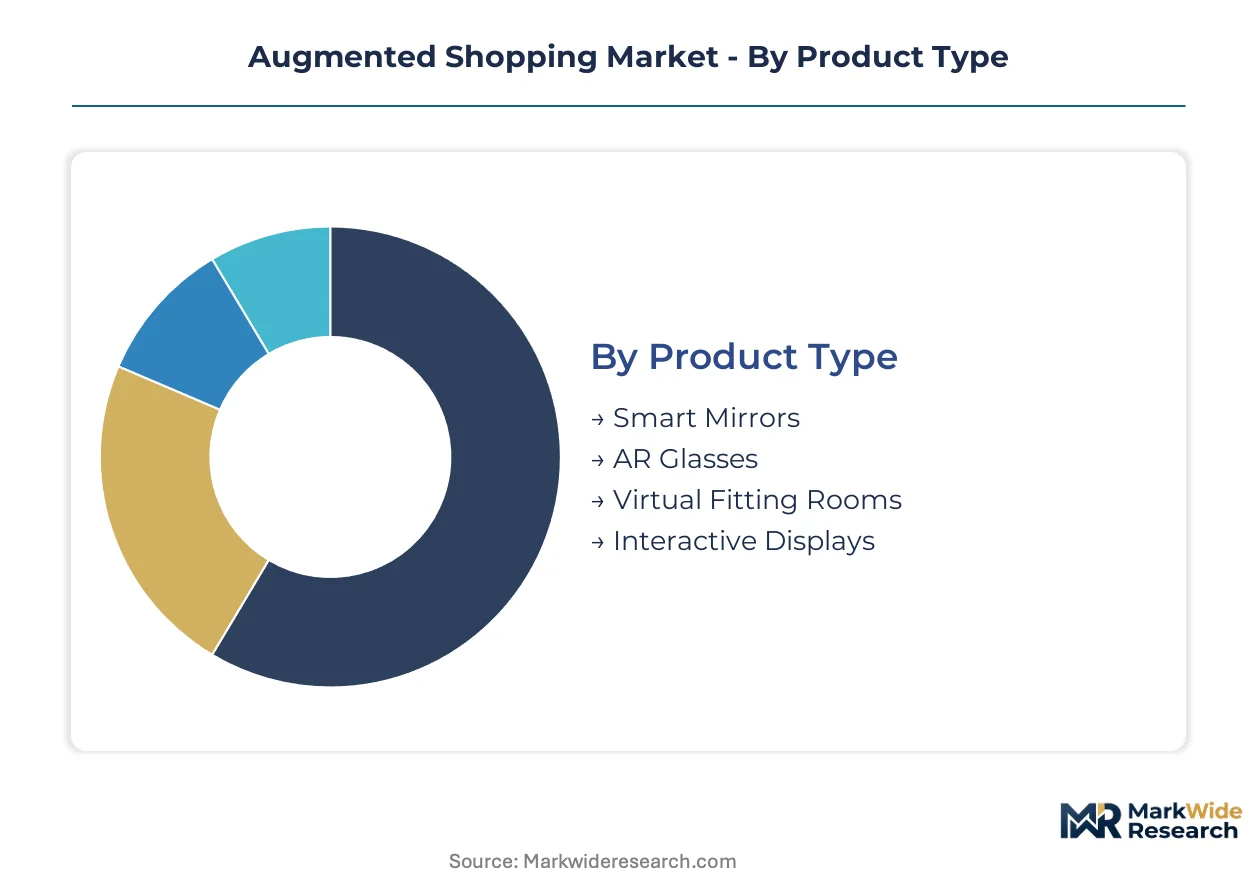
Augmented shopping deployments fragment sharply by integration depth, with standalone hardware systems commanding premium pricing while embedded software layers penetrate faster through existing device ecosystems. Segmentation choices determine capital intensity, update cycles, and regulatory exposure for technology vendors and retail adopters alike.
Product Type:
Standalone hardware segments require dedicated infrastructure investment and face longer replacement cycles, while software-embedded solutions leverage consumer-owned devices for faster scaling.
- Smart Mirrors:Wall-mounted reflective displays with integrated depth sensors and edge-computing modules process real-time body mapping for apparel visualization. Demand concentrates in flagship fashion retail locations across Germany and France, where premium positioning justifies per-unit costs exceeding traditional digital signage.
- AR Glasses:Wearable headsets with waveguide optics and spatial computing processors enable hands-free product overlay in physical environments. Supply constraints from micro-display manufacturing bottlenecks limit rollout velocity despite strong interest from automotive configurators in the United States.
- Virtual Fitting Rooms:Camera-based systems using smartphone or kiosk inputs to simulate garment fit without physical try-on.
- Interactive Displays:Touch-enabled screens with depth sensing for product exploration and environmental visualization.
Virtual fitting rooms lead volumes today; AR glasses are gaining share fastest as OLEDoS manufacturing capacity expands.
Application:
Deployment setting dictates latency tolerance, with in-store systems requiring sub-50 millisecond response while e-commerce platforms buffer through cloud rendering pipelines.
- E-Commerce Platforms:Browser and app-embedded AR tools leverage consumer device cameras for product preview without dedicated hardware investment. Amazon's logistics-data integration anchors demand concentration in the United States, where return-rate reduction drives merchant adoption.
- Retail Stores:Fixed installations of mirrors, kiosks, and display systems requiring spatial calibration and maintenance protocols. EU AI Act conformity assessments for biometric processing reshape architectural requirements in French and German deployments.
- Showrooms:Premium physical spaces using environmental overlay for high-consideration purchases.
- Trade Shows:Temporary installations for product launch visualization and buyer engagement.
E-commerce platforms anchor current deployment scale; retail stores are expanding most quickly as legacy POS integration costs decline.
End User:
Return-rate economics vary dramatically by merchandise category, with fit-critical apparel commanding the strongest business case for spatial preview investment.
- Fashion Retailers:Apparel and accessories merchants deploying virtual fitting rooms to compress reverse-logistics expenditure. Zara and H&M parent companies in Spain and Sweden drive European adoption, while South Korean fast-fashion platforms normalize consumer expectation.
- Home Improvement Stores:Paint, flooring, and fixture merchants using environmental overlay for finish visualization. Lowe's and Home Depot in the United States anchor demand as consumers preview renovation outcomes before purchase commitment.
- Electronics Retailers:Device and accessory merchants using scale-accurate product preview.
- Automotive Dealerships:Vehicle configurators using real-time finish and feature visualization.
Fashion retailers dominate current procurement volumes; automotive dealerships show the steepest expansion trajectory as exterior configuration tools mature.
Technology:
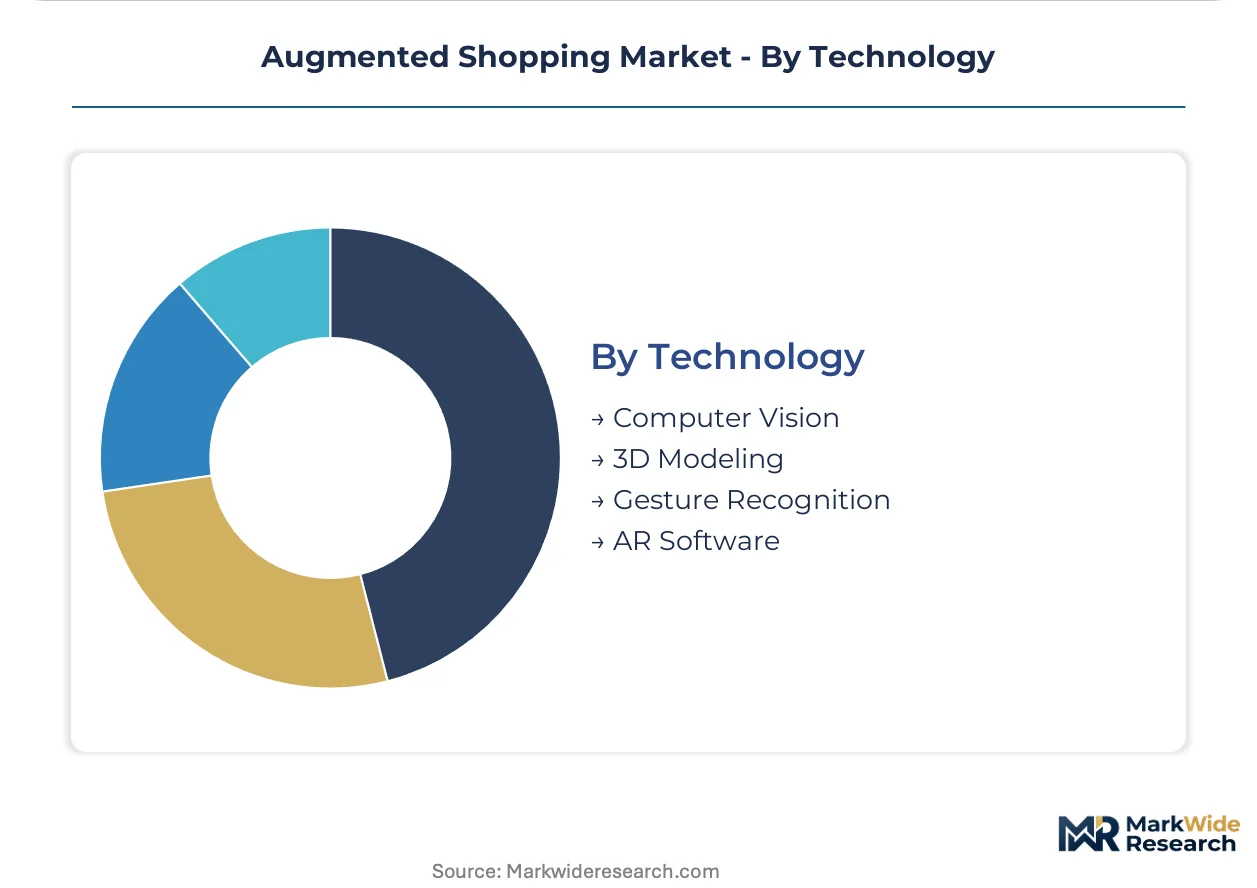
Underlying technical layers determine development talent requirements and regulatory classification, with computer vision systems facing stricter biometric oversight than pure rendering pipelines.
- Computer Vision:Algorithms for real-time object recognition, depth estimation, and spatial mapping using camera inputs. GDPR and EU AI Act compliance obligations in France and Germany force architectural separations between identity verification and fit simulation functions.
- 3D Modeling:Asset pipelines generating product representations from photogrammetry, CAD files, or NeRF-based sparse input reconstruction. Generative AI compression is unifying creative and technical workflows inside retail marketing organizations.
- Gesture Recognition:Input systems translating hand and body movement into navigation commands.
- AR Software:Development platforms and runtime engines enabling cross-device deployment.
Computer vision commands the largest development investment today; 3D modeling is climbing the fastest as NeRF pipelines reduce asset production timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates platform-level AR commerce infrastructure while South Korea normalizes consumer expectation for virtual try-on capabilities. France and Germany impose the strictest biometric data interpretations under EU frameworks. China's manufacturing scale shapes hardware supply trajectories for the broader Asian market.
United States
Amazon anchors e-commerce AR deployment through logistics-data integration that reduces merchant return rates. The FTC enforces advertising disclosure requirements on virtual product representations to prevent consumer deception. Silicon Valley clusters computer vision talent for spatial computing development while New York hosts fashion retail flagship installations.
Germany
Automotive configurators drive demand for environmental overlay technology among premium vehicle buyers. The KBA and federal data protection authorities interpret EU AI Act biometric scope expansively for retail computer vision. Berlin and Munich concentrate AR software development for European market compliance.
France
Luxury fashion houses deploy smart mirrors in flagship Paris locations to compress purchase decision cycles. The CNIL enforces GDPR biometric processing restrictions that force architectural separations in virtual fitting room systems. Lyon hosts specialized computer vision research clusters serving retail applications.
China
Fast-fashion platforms normalize consumer expectation for spatial preview capabilities across apparel categories. SAMR enforces GB standards on AR device data collection that create compliance architecture costs for cross-border operators. Shenzhen and Shanghai concentrate micro-display manufacturing capacity easing hardware supply constraints.
South Korea
Cosmetics retailers observe the strongest behavioral normalization of virtual try-on as standard pre-purchase filtering. The MFDS oversees consumer protection frameworks for AR-enabled beauty applications. Seoul anchors regional demand concentration with completion rate sensitivity below two-second load thresholds.
Augmented Shopping Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the augmented shopping value chain. Platform operators leverage existing consumer data ecosystems to embed AR tools at scale, while dedicated spatial computing vendors concentrate on rendering fidelity and latency optimization. Three strategic archetypes dominate: logistics-integrated e-commerce platforms, hardware-software ecosystem controllers, and vertical retail technology providers. Competitive positioning hardens through strategic partnerships with semiconductor foundries and portfolio diversification into adjacent spatial computing applications.
Within the platform operator tier, Amazon and Meta exemplify divergent ecosystem strategies, with the former integrating AR tools throughout existing commerce infrastructure and the latter sustaining heavy R&D investment in computer vision hardware that feeds downstream retail deployment. Apple occupies a position as ecosystem controller through tightly managed AR software layers that limit third-party commerce integration depth.
| Leading Market Players |
|---|
| Meta |
| Apple |
| Amazon |
| Microsoft |
| Shopify |
| IKEA |
| Snap |
| Warby Parker |
| Others |
Cost & Logistics Intelligence
OLEDoS wafer pricing indices from Taiwanese foundries cascade through AR hardware tiers, compressing margins on consumer-grade headsets while sustaining premium positioning for enterprise showroom deployments.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for micro-display components, enabling three-tier pricing structure across premium, standard, and economy levels. Certification under EU AI Act conformity pathways differentiates German and French retail deployments from lower-compliance jurisdictions. Cost compression in embedded software layers intensifies as generative AI pipelines reduce 3D asset production overhead. Fashion retailers show highest price sensitivity for per-unit hardware, while automotive configurators absorb premium tiering for environmental overlay fidelity.
Supply Chain Analysis
SLAM algorithm engineering talent scarcity in Shenzhen and Seoul constrains module assembly velocity for spatial computing hardware. China, Taiwan, and South Korea anchor micro-display and sensor component manufacturing. Supply chains draw from specialized semiconductor foundries, waveguide optics fabricators, and depth-sensor module integrators. Single-source vulnerability concentrates in OLEDoS manufacturing equipment. Distribution runs through direct OEM relationships for flagship retail installations and platform-embedded SDK licensing for e-commerce scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in augmented shopping hinges on reverse logistics cost capture in apparel, where virtual fitting room deployment compresses return processing expenditure faster than hardware amortization.
For Market Incumbents: Deepen vertical integration into micro-display supply through foundry partnerships in Taiwan and South Korea, insulating against OLEDoS bottlenecks. Secure EU AI Act pre-certification for biometric computer vision systems ahead of German and French enforcement waves. Prioritize SLAM engineering retention against poaching from automotive and robotics competitors. For New Entrants and Emerging Players: Capture white-space in mid-tier furniture retail, where millimeter-scale spatial measurement tools remain underdeployed relative to fashion and cosmetics saturation. Target Indian consumer markets through PLI-aligned hardware assembly partnerships. Lead with browser-based AR SDKs avoiding dedicated hardware capital intensity. For Investors and Strategic Acquirers: Consolidation pressure builds where SLAM talent scarcity intersects with fragmented vertical retail technology vendors lacking platform scale. Five-to-ten year viability favors computer vision specialists with pre-certified EU biometric pipelines over pure-play 3D asset studios. Monitor OLEDoS manufacturing yield reports as inflection signal for hardware margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Establishes compliance moat for biometric computer vision deployments in France and Germany. |
| Foundry Partnership for OLEDoS Supply | Secures micro-display allocation ahead of automotive and consumer hardware competition. |
| NeRF-Based Asset Pipeline Integration | Unifies creative and technical workflows inside retail marketing organizations. |
| SLAM Engineering Talent Acquisition | Addresses scarcity constraining development velocity for spatial anchoring features. |
| India PLI Scheme Manufacturing Alignment | Captures production-linked incentives for South Asian consumer market supply. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged spatial computing CTOs, fashion retail digital transformation leads, AR hardware procurement officers at automotive OEMs, and EU regulatory compliance specialists. Secondary validation drew from SEC filings of platform operators, hyperscaler capex disclosures, SAMR GB standard publications, and EU AI Act implementation guidance. Bottom-up deployment counts triangulated against top-down platform revenue attribution.
Historical reference periods anchored growth trajectory modeling across the projection horizon. Segmentation dimensions included hardware form factor, application setting latency requirements, end-user return-rate economics, and underlying technical layer regulatory classification. CAGRs derived from fitted curve analysis of adoption S-curves, adjusted for OLEDoS supply constraints and biometric compliance timeline uncertainty. NeRF pipeline adoption rates and virtual fitting room completion thresholds informed demand-side elasticity parameters.
Underlying measurement precision varies by segment; e-commerce platform deployment counts carry tighter precision than provisional automotive showroom installations. Forecasts embed assumptions on micro-display yield recovery and EU AI Act enforcement consistency. Material deviation in OLEDoS manufacturing expansion timelines or German biometric scope interpretation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Indoor LBS Market
Others
Gas Holders Market
Others
Molecular Spectroscopy Market
Others
Industrial Wearable Devices Market
Others
Global Laser Defense Eyewear Market
Others
Aerospace Tester Market
Others
Retail Digital Signage Market
Others
Agitator Bead Mill Market
Others
Billet Market
Others
Europe Astrology Market
Others
Exosome Technologies Market
Others
Software Synthesizers Market
Others
Heat Treatment Furnace Market
Others
France Location-Based Services Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Depth Gauge Market