
 Global Printed Signage Market | 2026-2036
Global Printed Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Printed Signage Market Outlook
China is rewriting capacity dynamics across substrate supply as domestic vinyl and composite panel output scales to serve both local installers and export channels. Avery Dennison Corporation leverages its pressure-sensitive materials portfolio to dominate premium fleet and retail graphics segments. ORAFOL Europe GmbH sustains leadership in reflective and specialty films through tight control over German manufacturing and distribution hubs. Mimaki Engineering Co. Ltd. competes on inkjet system versatility, targeting short-run signage workflows with UV-curable and solvent platforms.
Printed signage encompasses rigid and flexible substrates bearing pigmented or dyed graphics for commercial communication, typically produced through ink deposition processes achieving resolutions from 360 to 1440 dpi for viewing distances under one meter to over fifty meters. Banners and window graphics absorb the bulk of event-driven and retail refresh cycles, while billboards command higher absolute spend per unit but slower replacement frequencies tied to municipal lease structures. Digital printing displaces analog methods in runs below five hundred square meters, though screen printing retains margin pools in long-duration outdoor applications requiring weathering resistance beyond seven years.
FDA guidelines on indirect food-contact adhesives constrain retail signage deployed near grocery sections in US-based chains, while REACH and RoHS frameworks in Europe restrict phthalate plasticizers and heavy-metal pigments in vinyl formulations. China's GB standards on outdoor advertising structures mandate fire-retardant ratings for substrates above specified installation heights. Stakeholders must track how fragmented municipal permitting across India, Brazil, and Indonesia shapes speed-to-install for out-of-home campaigns.
Market Dynamics
Digital inkjet systems are compressing minimum viable run lengths below fifty square meters, fragmenting demand across thousands of micro-installers while eroding the scale advantages that once protected regional screen-printing networks.
Growth Catalysts
- EU Green Deal packaging mandates:The EU's packaging sustainability framework is forcing converters toward recyclable paper-based substrates and bio-inks, opening retrofit demand across existing retail estates.
- India modern trade expansion:Organized retail penetration in tier-two cities such as Lucknow and Indore is generating recurring refresh cycles for point-of-sale graphics.
- UV-curable ink chemistry:Low-VOC formulations are unlocking indoor applications previously closed to solvent platforms, expanding addressable square footage in healthcare and hospitality.
Market Restraints
- Petrochemical substrate volatility:PVC and PET film prices track ethylene and propylene feedstock swings, compressing converter margins on fixed-price annual contracts.
- Chinese capacity concentration:Domestic vinyl and composite panel output now supplies sixty percent of Asian installer demand, creating single-source vulnerability for regional distributors.
- Seven-year weathering threshold:Screen printing retains its cost advantage in long-duration outdoor applications, capping digital penetration in highway billboard networks.
Strategic Opportunities
- Brazil municipal permitting fragmentation:São Paulo and Rio de Janeiro operate divergent out-of-home advertising codes, creating first-mover advantage for compliance-capable installation networks.
- Food-contact adhesive certification:FDA-compliant pressure-sensitive materials for grocery-aisle deployments remain underdeveloped, offering premium positioning for qualified suppliers.
- Short-run event signage:Hybrid UV-solvent inkjet platforms are collapsing turnaround times for trade-show and festival graphics, capturing spend from traditional offset-laminate workflows.
Industry Challenges
- Color management specialization:ICC profile calibration for textile, rigid, and translucent substrates demands trained technicians that installer networks struggle to retain.
- Fire-retardant certification timelines:China's GB standards for elevated outdoor structures require third-party testing cycles that delay campaign launches by eight to twelve weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Printed Signage Market |
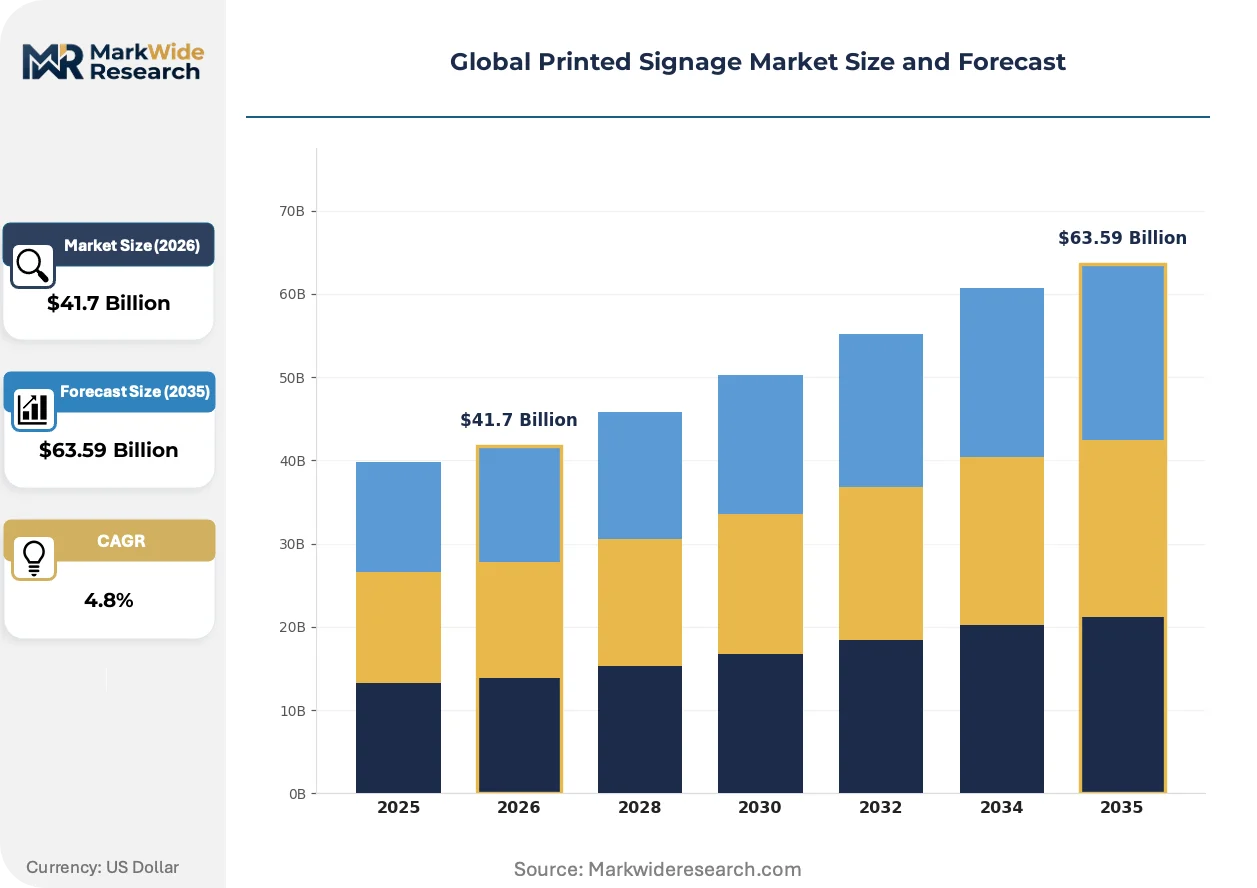
| Market Size in 2026 | $41.7 Billion |
| Market Size in 2035 | $63.59 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Banners, Posters, Billboards, Window Graphics Material: Vinyl, Fabric, Paper, Composite End User: Retail, Corporate, Events, Hospitality Technology: Digital Printing, Screen Printing, Lithography, Offset Printing |
| Companies Covered | Avery Dennison Corporation, ORAFOL Europe GmbH, 3M Company, Spandex Ltd., LINTEC Corporation, Canon Inc., Mimaki Engineering Co. Ltd., EFI, 3A Composites GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Printed Signage Market Strategic Shifts
Active reshaping in printed signage stems from three converging pressures: substrate chemistry reformulation, printhead resolution advancement, and procurement model compression toward same-day fulfillment.
Water-based latex ink systems are rendering obsolete the solvent-ventilation infrastructure that previously confined wide-format printing to industrial zones. Retail chains in Germany and the Netherlands are adopting latex platforms for in-store production cells, eliminating logistics coordination with centralized print houses. This distributed production model is compressing campaign launch windows from two weeks to forty-eight hours.
REACH restrictions on phthalate plasticizers and heavy-metal pigments are forcing vinyl formulation changes across European converter networks. Suppliers must recertify color consistency under reformulated chemistries, raising qualification costs for mid-tier producers. Fleet graphics and outdoor banner segments face the steepest reformulation timelines as brand owners enforce color-matching protocols.
Buyer concentration among multinational retail chains is consolidating procurement through centralized facility-management platforms. Independent installers in Indonesia and Vietnam are losing direct brand relationships to approved-vendor lists managed by global procurement teams. This channel rationalization favors converters with ISO 9001 certification and multi-country logistics capability.
Global Printed Signage Market Segmentation
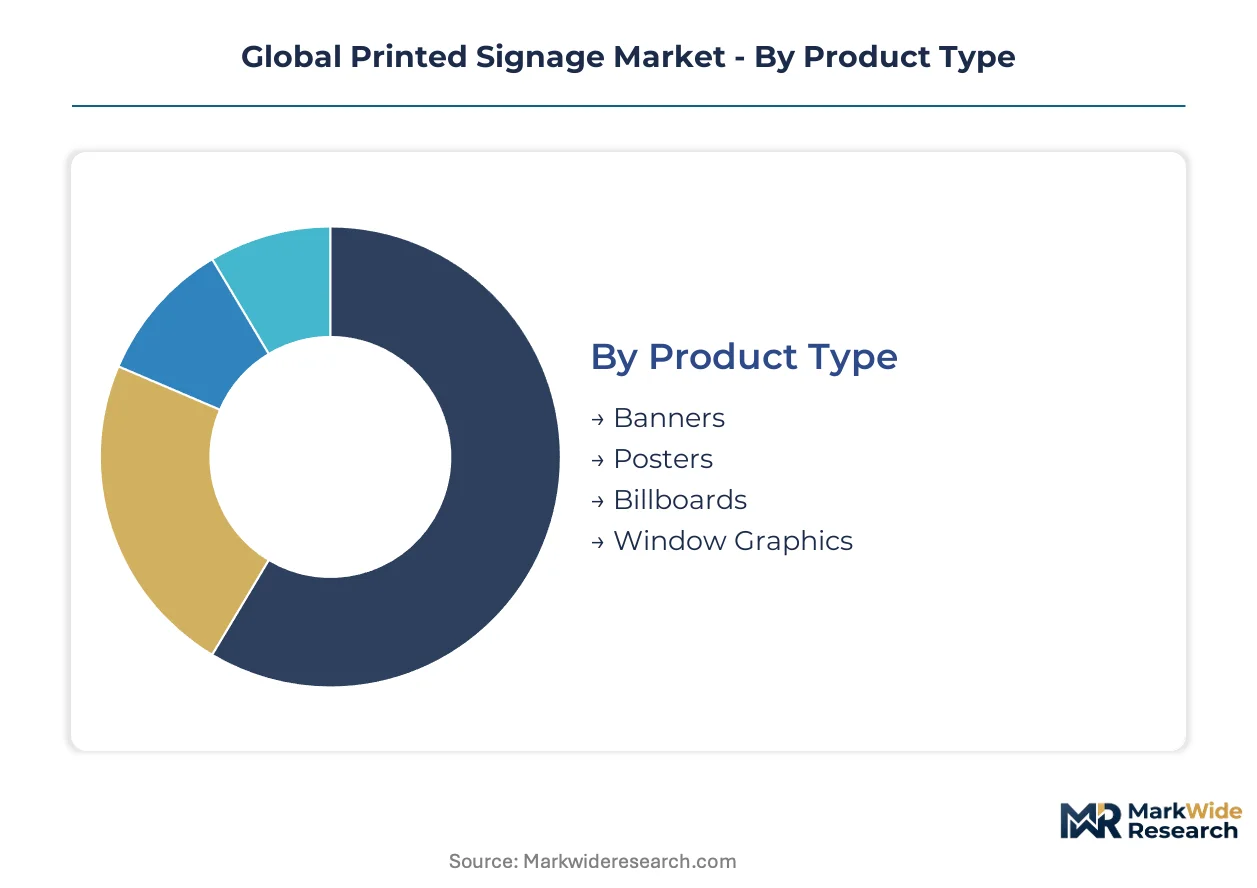
Segmentation in printed signage reveals how substrate durability, print resolution requirements, and installation logistics fragment procurement decisions across installer networks. Each dimension carries distinct margin profiles and regulatory exposure that shape converter specialization strategies.
Product Type:
After-sales intensity varies sharply across formats, with billboards demanding structural inspection cycles and banners requiring seasonal replacement coordination.
- Banners:Flexible vinyl or fabric substrates suspended from grommeted edges, typically produced in widths up to five meters for event and retail refresh applications. Demand clusters in India's tier-two cities where modern trade formats multiply promotional cycles, though monsoon seasonality compresses effective campaign windows.
- Billboards:Rigid substrates or stretched flex faces mounted on steel structures, engineered for seven-plus year weathering resistance in highway and urban premium locations. Screen printing retains cost advantage here, capping digital penetration where municipal lease structures slow replacement frequencies.
- Posters:Paper-based or synthetic prints for indoor point-of-sale and transit shelter applications, governed by shorter replacement cycles tied to promotional calendars.
- Window Graphics:Perforated films and clear static clings for retail facade branding, subject to visibility regulations in EU member states and fire-retardant mandates in China's GB standards for elevated installations.
By volume, banners lead. By growth pace, window graphics are gaining share fastest as retail chains prioritize facade personalization.
Material:
Cost tier stratification separates commodity substrates from certified specialty grades, with REACH-compliant vinyl commanding premium positioning.
- Vinyl:PVC-based films and banners dominate outdoor durability requirements, though phthalate plasticizer restrictions under REACH and RoHS are forcing European reformulation. Chinese domestic output now supplies sixty percent of Asian installer demand, creating single-source vulnerability.
- Composite:Aluminum or foam-core rigid panels for long-term architectural signage, favored where fire-retardant certification under China's GB standards is mandatory for structures above specified heights.
- Fabric:Polyester and dye-sublimation textiles for lightweight, recyclable event graphics, expanding as EU Green Deal packaging rules push converters toward paper-based alternatives.
- Paper:Coated stocks for short-run indoor posters and retail applications, limited by moisture sensitivity but advantaged in sustainability scoring for corporate procurement.
By installed square meters, vinyl dominates. By margin expansion, composites are climbing the fastest as certification requirements filter out mid-tier competitors.
End User:
Application context determines substrate specification, with food-contact proximity triggering FDA adhesive constraints in US grocery retail.
- Retail:Point-of-sale graphics, window films, and in-store banners with refresh cycles tied to promotional calendars. Organized retail penetration in India and Southeast Asia is generating recurring demand for standardized formats.
- Events:Temporary banners and stage backdrops requiring rapid turnaround, where hybrid UV-solvent inkjet platforms are collapsing production timelines from weeks to forty-eight hours.
- Corporate:Fleet graphics and facility branding with strict color-matching protocols, facing extended reformulation timelines as REACH restrictions force vinyl chemistry changes.
- Hospitality:Interior wayfinding and decorative graphics, where low-VOC UV-curable inks are unlocking applications previously closed to solvent platforms.
By absolute spend, retail leads. By contract renewal frequency, events are expanding most quickly as festival and trade-show formats proliferate.
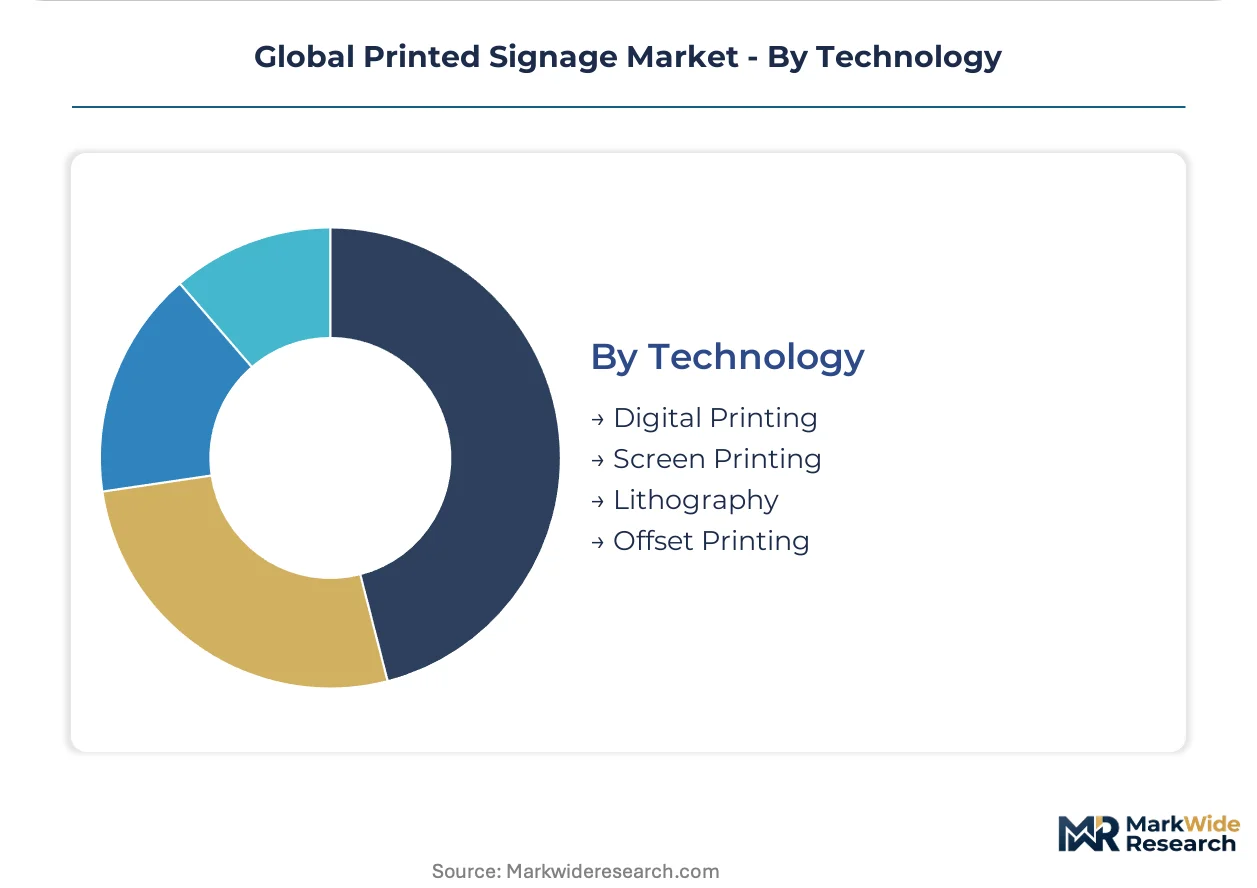
Technology:
Volume threshold economics separate digital inkjet's short-run dominance from screen printing's hold on weathering-critical outdoor applications.
- Digital Printing:Inkjet systems achieving 360 to 1440 dpi resolution, displacing analog methods in runs below five hundred square meters and fragmenting demand across micro-installer networks.
- Screen Printing:Mesh-based ink deposition for seven-plus year outdoor durability, retaining margin pools in highway billboard networks where weathering resistance exceeds digital capabilities.
- Lithography:Planographic offset for high-volume poster and point-of-sale runs, losing share to digital as minimum viable quantities compress.
- Offset Printing:Sheet-fed and web processes for standardized retail formats, constrained by longer setup times that disadvantage rapid refresh cycles.
By job count, digital printing leads. By revenue per square meter, screen printing maintains the steepest premium trajectory in long-duration outdoor contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese vinyl and composite panel output now supplies sixty percent of Asian installer demand, creating supply-side concentration that reshapes procurement patterns across neighboring markets. This capacity dominance filters through to pricing volatility and single-source vulnerability for regional distributors.
United States
Modern trade expansion in Texas and Florida drives recurring refresh cycles for retail graphics and fleet branding. FDA guidelines on indirect food-contact adhesives constrain signage deployed near grocery sections in national chains. Chicago and Los Angeles host dense installer networks serving out-of-home advertising campaigns with compressed turnaround requirements.
Germany
REACH restrictions on phthalate plasticizers force vinyl reformulation across converter networks serving premium fleet graphics. The EU Green Deal packaging mandates push substrate producers toward recyclable paper-based alternatives. ORAFOL Europe GmbH anchors reflective film production from its German manufacturing and distribution hubs.
China
Domestic output of vinyl and composite panels scales to serve both local installers and export channels across Southeast Asia. GB standards on outdoor advertising structures mandate fire-retardant ratings for substrates above specified installation heights. Shenzhen and Shanghai clusters concentrate inkjet system manufacturing and wide-format print service capacity.
India
Organized retail penetration in Lucknow and Indore generates recurring demand for point-of-sale graphics and promotional banners. Municipal permitting fragmentation across tier-two cities shapes speed-to-install for out-of-home campaigns. Maharashtra and Karnataka host the largest concentrations of certified converters serving modern trade formats.
Brazil
São Paulo and Rio de Janeiro operate divergent out-of-home advertising codes, creating compliance complexity for installation networks. Festival and event formats proliferate, driving short-run signage demand with forty-eight-hour turnaround expectations. Southeast industrial zones concentrate screen-printing capacity for long-duration outdoor applications.
Global Printed Signage Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in materials and substrates. The vendor base stratifies across three tiers: multinational material science conglomerates with pressure-sensitive portfolios, mid-scale regional converters with ISO certification, and fragmented micro-installers serving hyperlocal event markets. Two dominant competitive moves define current positioning: backward integration into substrate manufacturing to secure margin pools, and technology licensing partnerships to compress equipment deployment timelines.
Among material science specialists, Avery Dennison Corporation and ORAFOL Europe GmbH exemplify the premium substrate archetype through their respective pressure-sensitive and reflective film portfolios. Mimaki Engineering Co. Ltd. occupies a position within the system integrator tier, representing the inkjet platform specialization that targets short-run signage workflows. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| ORAFOL Europe GmbH |
| 3M Company |
| Spandex Ltd. |
| LINTEC Corporation |
| Canon Inc. |
| Mimaki Engineering Co. Ltd. |
| EFI |
| 3A Composites GmbH |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese vinyl substrate manufacturing is compressing regional pricing power while forcing converters toward specialty certification tiers to defend margin pools. This utilization imbalance rewards backward-integrated producers with captive resin supply and penalizes distributors exposed to spot-market volatility.
Pricing Analysis
REACH compliance dictates the pricing tier structure across European converter networks, separating premium-certified vinyl formulations from commodity grades. Three-tier pricing stratifies across premium REACH-compliant, standard reformulated, and economy non-certified levels. Price differentiation rests on certification investment and volume scale, with bulk retail procurement teams extracting steepest discounts. Cost compression in standard tiers is intensifying because Chinese capacity exports are flooding Asian spot markets. Event-driven buyers exhibit highest price sensitivity; fleet graphics contracts with seven-year durability requirements show lowest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement negotiations between substrate manufacturers and regional distributors, straining working capital for mid-tier converters. Geographic supply concentrates in China, Germany, and South Korea, with Chinese domestic output feeding sixty percent of Asian installer demand. Raw material dependencies draw from ethylene feedstock, PET resin, and aluminum composite core materials. Single-source vulnerability runs through Chinese vinyl concentration, where municipal permitting delays can strand inventory. Distribution runs through certified-converter networks in tier-two Indian cities and Southeast Asian retail hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The printed signage market is entering a cyclical recovery phase as retail refresh budgets normalize following pandemic-era deferrals. Modern trade expansion across India's tier-two cities provides the demand anchor for this upswing.
For Market Incumbents: Insulate margin pools by securing captive supply of REACH-compliant vinyl formulations before reformulation deadlines tighten. Backward integration into substrate manufacturing in Germany or South Korea reduces exposure to Chinese spot-price volatility. Certification investment in FDA food-contact adhesives creates defensive positioning against specialty-film entrants targeting US grocery retail. For New Entrants and Emerging Players: Mid-market event signage in Brazil's festival circuit represents the most penetrable entry point, where São Paulo-Rio permitting fragmentation disadvantages established networks lacking local compliance expertise. Tier-two Indian cities with modern trade penetration but thin certified-converter presence offer secondary white-space. A compliance-first go-to-market angle—pre-certified fire-retardant substrates—collapses sales cycles versus incumbent recertification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-graphics specialists with multi-year corporate contracts and embedded color-matching protocols. Long-term viability over a five-to-ten-year window favors converters with ISO 9001 certification and multi-country logistics capability over pure-play equipment distributors. The signal to watch is consolidation velocity among Indonesian and Vietnamese installer networks as global procurement platforms rationalize approved-vendor lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Manufacturing | Captive vinyl supply secures margin pools against Chinese spot-price volatility. |
| REACH-Compliant Formulation Certification | European regulatory deadlines filter mid-tier competitors from premium segments. |
| Hybrid UV-Solvent Platform Deployment | Forty-eight-hour turnaround capability captures event-driven demand from offset workflows. |
| Multi-Country Logistics Network Buildout | ISO-certified distribution satisfies global retail procurement platform requirements. |
| FDA Food-Contact Adhesive Qualification | Grocery-aisle deployment access opens underdeveloped premium positioning in US chains. |
Study Parameters
A standing panel of wide-format print service operators, substrate procurement managers at retail chains, inkjet system R&D directors, and municipal permitting consultants provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SEC filings of listed converters, customs trade data on vinyl film imports, and EU ECHA substance restriction databases. Bottom-up volume estimates from installer network surveys triangulated against top-down spending analysis by end-use sector.
Scenario-bracketing anchored the projection framework, with base, upside, and downside cases reflecting varying speeds of digital inkjet displacement in billboard applications. Segmentation dimensions modeled include substrate material tier, print technology platform, end-use vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to normalized baseline spending patterns. Industry-specific forecast inputs incorporated REACH reformulation timelines and Indian modern trade penetration rates.
Practitioners should monitor Chinese vinyl capacity utilization rates and EU Green Deal packaging rule enforcement intensity for early signals of supply-price inflection. Forecasts reflect documented assumptions on substrate substitution elasticities and regulatory compliance cost pass-through. Macroeconomic downturn compressing retail promotional budgets, accelerated REACH restriction expansion, or breakthrough digital inkjet weathering performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
Multiscreen Advertising Market
Advertising and Marketing Media
Digital Out of Home (OOH) Advertising Market
Advertising and Marketing Media
Programmatic Display Advertising Market
Advertising and Marketing Media
Chile OOH and DOOH Market
Advertising and Marketing Media
Billboard and Outdoor Advertising Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
Turkey OOH and DOOH Market