
 Three Proofing Rugged Tablet Market | 2026-2036
Three Proofing Rugged Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Three Proofing Rugged Tablet Market Insights
The EU Green Deal's circular electronics mandates are restructuring procurement criteria for defense and industrial buyers across Europe. Panasonic Corporation leverages its Japanese manufacturing heritage to sustain premium positioning in MIL-STD-certified product lines. Getac Technology Corporation anchors its competitive stance through vertical integration of thermal management components. Zebra Technologies competes aggressively in enterprise logistics segments with Android-based handheld configurations.
Three proofing rugged tablets combine ingress protection (IP65/IP67), drop resistance (MIL-STD-810H), and extreme temperature tolerance (-20°C to 60°C operational) within sealed magnesium alloy or polycarbonate housings; these devices enable continuous data capture in environments where consumer electronics fail within hours. Handheld configurations dominate current military and field service deployments due to portability requirements, while vehicle-mounted variants represent the fastest-growing segment as construction and transportation fleets mandate real-time telematics integration. Windows technology retains entrenched position in enterprise environments demanding legacy software compatibility, though Android gains ground in cost-sensitive developing markets.
FCC Part 15 emissions compliance shapes US market access for wireless-enabled models, while REACH and RoHS restrictions in Europe constrain solder and coating material selections across supply chains. China's MIIT enforces GB standard certifications that foreign manufacturers must obtain for public-sector tenders. Stakeholders must monitor evolving battery transportation regulations from IATA and national aviation authorities, as lithium-ion cell configurations face tightening cargo restrictions that threaten aftermarket logistics and field replacement strategies.
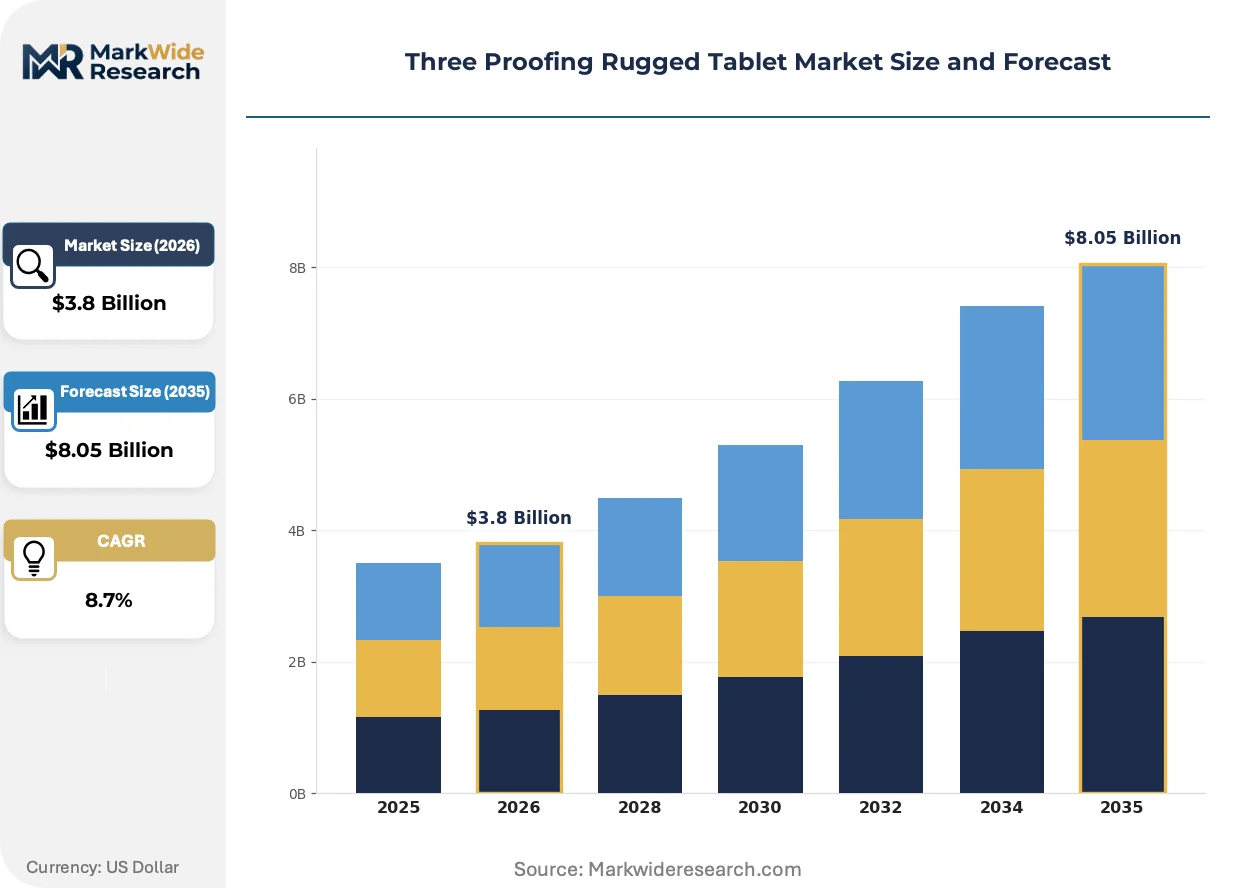
Market Dynamics
MIL-STD-810H certification requirements are tightening procurement standards across defense and heavy industry segments, forcing manufacturers to revalidate thermal management and drop-resistance designs against updated shock profiles.
Growth Catalysts
- EU Green Deal circular electronics mandates:Repairability and recyclability requirements are redirecting R&D budgets toward modular component architectures and standardized fastener systems.
- Automotive OEM shop-floor digitization:Germany's industrial corridor is deploying rugged tablets for real-time quality control and predictive maintenance workflows.
- 5G private network rollouts:Mining and oilfield operators are upgrading field devices to support low-latency telemetry and remote equipment diagnostics.
Market Restraints
- Magnesium alloy supply concentration:Primary smelting capacity clusters in China create input cost volatility and geopolitical exposure for housing manufacturers.
- REACH and RoHS material restrictions:European constraints on lead-free solders and hexavalent chromium coatings extend qualification timelines for new product variants.
- Consumer tablet performance convergence:Improved IP ratings and processor efficiency in mass-market devices threaten entry-level rugged segment pricing power.
Strategic Opportunities
- Vehicle-mounted configuration expansion:Construction and transportation fleets are mandating telematics-integrated tablets for real-time fleet management.
- India PLI scheme for electronics manufacturing:Production-linked incentives are attracting contract manufacturers to establish local assembly for defense and public-sector tenders.
- AI-enabled edge processing:Convergence of rugged hardware with on-device machine learning is opening predictive maintenance applications in remote infrastructure monitoring.
Industry Challenges
- MIL-STD-810H requalification timelines:Updated shock and vibration test protocols demand 12-18 month validation cycles that delay product refresh schedules.
- Legacy Windows software dependency:Enterprise buyers resist migration from x86 architectures despite Android cost advantages, complicating platform roadmap decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three Proofing Rugged Tablet Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Vehicle-Mounted, Wearable, Fixed-Mount End User: Military, Construction, Field Services, Transportation Technology: Windows, Android, Linux, iOS Application: Asset Tracking, Data Collection, Communication, Navigation |
| Companies Covered | Getac Technology Corporation, Zebra Technologies, Panasonic Corporation, Dell Technologies, DT Research, Handheld Group, Winmate Communication, Honeywell International, Leonardo DRS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three Proofing Rugged Tablet Market Trends and Innovations
Thermal management architectures and wireless connectivity modules are undergoing rapid redesign as operating temperature requirements widen and private 5G networks proliferate in heavy industrial settings.
Graphene-enhanced thermal interface materials are integrating into processor subassemblies to maintain performance across -20°C to 60°C operational windows. Mining equipment manufacturers in Australia and Canada are specifying these configurations for pit operations. The technology is integrating passive cooling capacity previously requiring active fan systems, enabling fully sealed IP67-rated designs without ventilation points.
REACH substance restrictions are forcing reformulation of conformal coatings and solder alloys across European supply chains. Manufacturers must now qualify alternative corrosion inhibitors and tin-silver-copper compositions that meet both environmental and MIL-STD reliability criteria. Defense contractors serving NATO procurement programs are absorbing extended qualification costs to maintain continental market access.
Defense buyers are consolidating vendor relationships around dual-use certification pathways that satisfy both military and civilian industrial requirements. Original equipment manufacturers in Germany and France are responding with unified product platforms configurable through firmware rather than hardware variants. This concentration is visible in Bundeswehr and Armée de Terre tender specifications that explicitly favor suppliers with existing automotive or energy sector deployments.
Three Proofing Rugged Tablet Market Segmentation
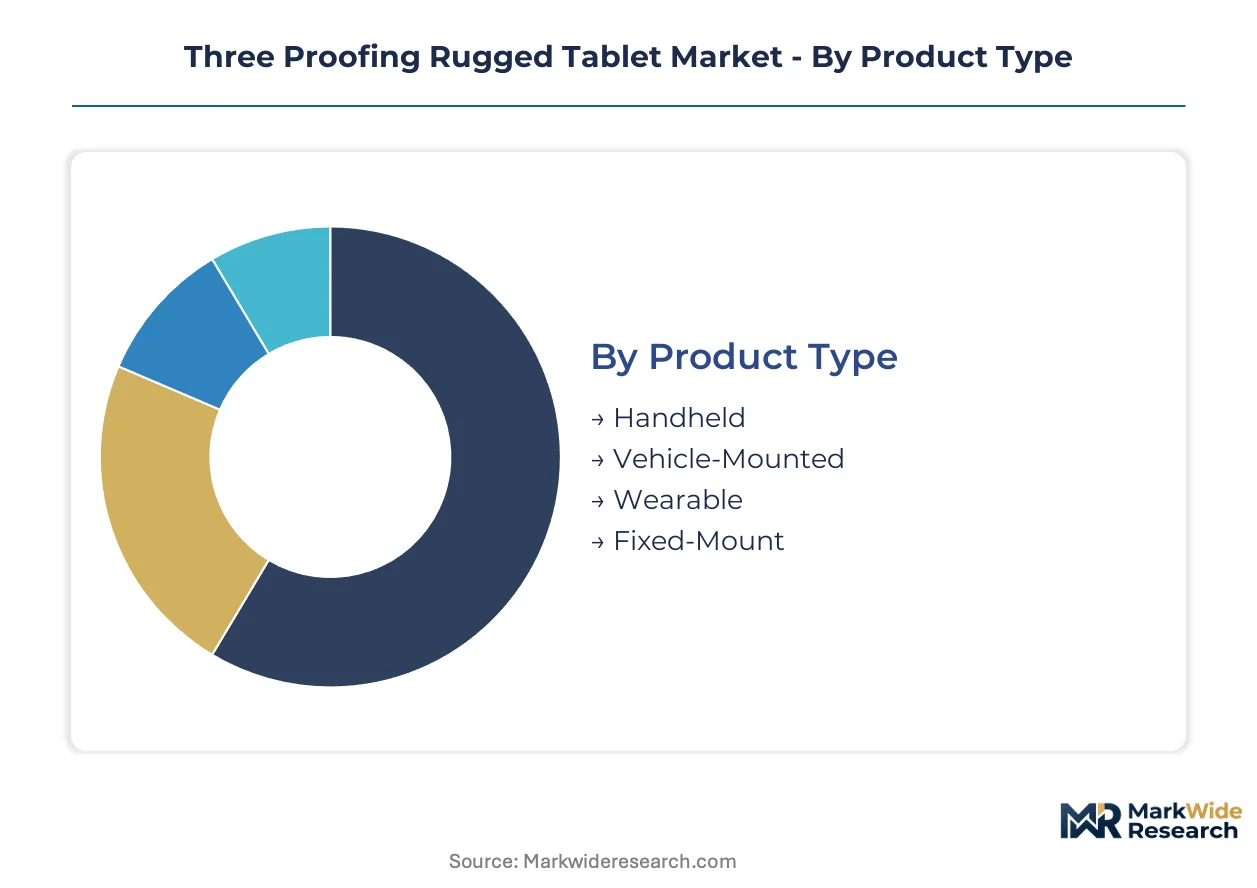
Segmentation in the Three Proofing Rugged Tablet Market reveals how protection specifications, computing architectures, and deployment contexts create distinct competitive arenas. Manufacturers configure thermal management, ingress sealing, and shock absorption differently across form factors and use environments.
Product Type:
Physical configuration determines sealing complexity, thermal dissipation pathways, and mounting integration requirements across deployment scenarios.
- Handheld:Compact magnesium alloy or polycarbonate housings with integrated batteries enable single-operator use in patrol and inspection workflows. NATO military procurement programs and German automotive OEM shop-floor digitization concentrate orders here due to portability demands and MIL-STD-810H certification requirements.
- Vehicle-Mounted:Ruggedized dock systems with vibration isolation and extended temperature tolerance support real-time telematics in construction and transportation fleets. Mining operators in Australia and oilfield services in Canada are expanding specifications for these configurations as 5G private networks enable low-latency equipment diagnostics.
- Wearable:Forearm-mounted or chest-integrated designs with reduced display sizes serve maintenance technicians requiring hands-free operation.
- Fixed-Mount:Panel-integrated installations with passive cooling architectures anchor control stations in heavy machinery and process automation environments.
Handheld configurations lead on scale; vehicle-mounted designs lead on momentum.
End User:
Buyer procurement standards diverge sharply between regulated defense programs and cost-optimized commercial fleets.
- Military:MIL-STD-810H certification mandates 12-18 month requalification cycles for updated shock and vibration protocols. Bundeswehr and Armée de Terre tender specifications favor suppliers with dual-use automotive or energy sector deployments, consolidating vendor relationships around unified certification pathways.
- Construction:Fleet telematics integration and predictive maintenance applications drive vehicle-mounted adoption. EU Green Deal circular electronics mandates are redirecting procurement toward modular, repairable designs with standardized fastener systems.
- Field Services:Asset inspection and work-order management prioritize lightweight handheld units with all-day battery endurance.
- Transportation:Real-time fleet management and regulatory compliance logging require rugged tablets with integrated GPS and cellular connectivity.
Military buyers lead on specification stringency; construction fleets lead on volume expansion.
Technology:
Operating system selection locks in software ecosystem compatibility and hardware architecture decisions across multi-year deployment cycles.
- Windows:x86 processor architectures sustain entrenched positions in enterprise environments demanding legacy software compatibility. Industrial buyers in Germany's machinery sector resist migration despite Android cost advantages, complicating manufacturer platform roadmaps.
- Android:ARM-based designs with lower bill-of-materials costs gain ground in cost-sensitive developing markets and logistics segments. Zebra Technologies competes aggressively here with handheld configurations optimized for warehouse and transportation workflows.
- Linux:Custom kernel deployments serve specialized industrial automation and defense applications requiring source-code visibility.
- iOS:Ecosystem lock-in limits adoption outside specific enterprise mobility management environments with existing Apple infrastructure.
Windows leads on enterprise installed base; Android leads on share expansion.
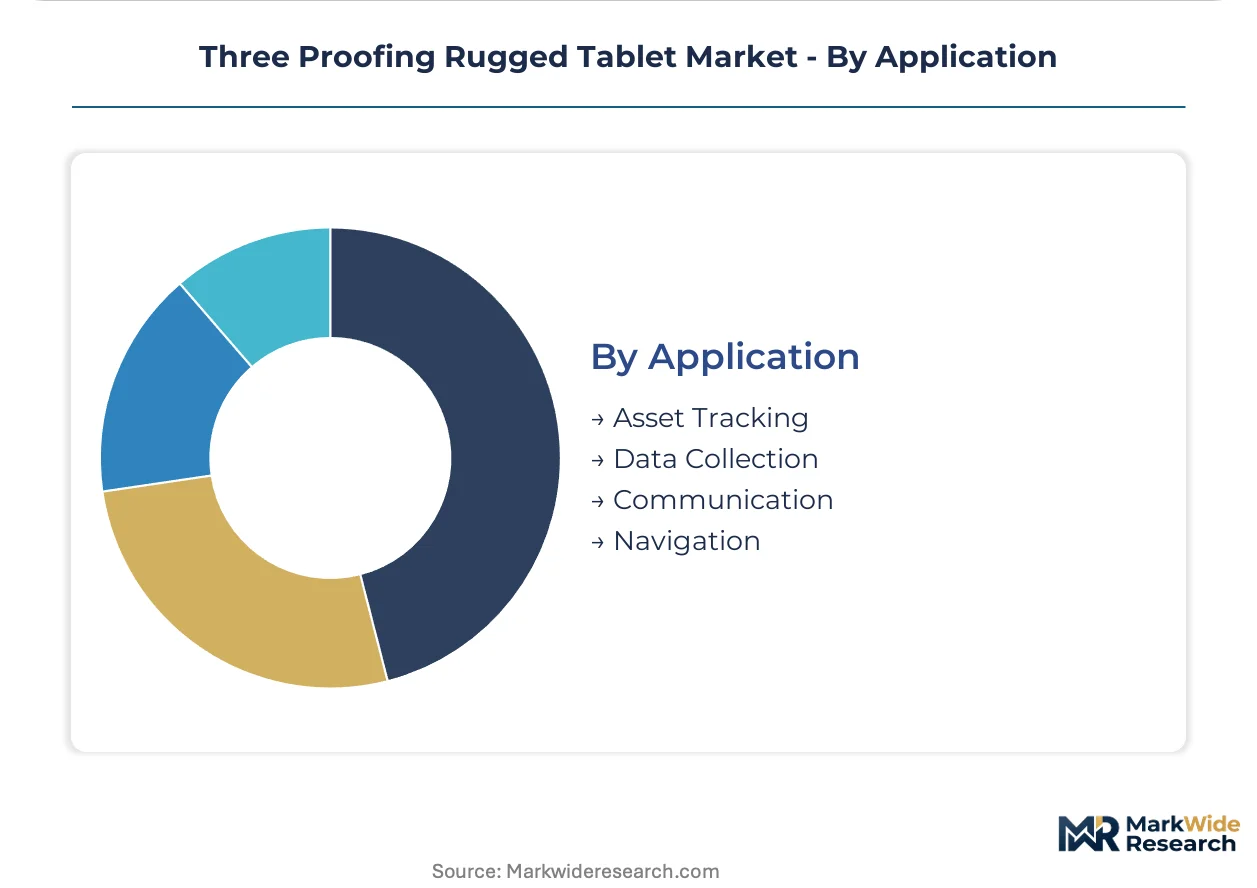
Application:
Functional use case determines sensor integration, software stack, and connectivity requirements.
- Asset Tracking:RFID and barcode scanning modules integrated into rugged housings enable real-time inventory and equipment location monitoring. Mining and oilfield operators are upgrading these capabilities alongside 5G private network rollouts.
- Data Collection:Environmental sensors, high-resolution cameras, and stylus digitization support quality control and inspection documentation. Automotive OEMs in Germany deploy these for shop-floor digitization and predictive maintenance workflows.
- Communication:Push-to-talk, video conferencing, and secure messaging applications require optimized antenna configurations and noise-canceling audio subsystems.
- Navigation:Multi-constellation GPS, dead reckoning, and mapping integration serve dismounted military operations and remote infrastructure survey.
Data collection leads on functional breadth; asset tracking leads on connectivity upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rugged tablet manufacturing originated in Japanese precision electronics and German industrial automation traditions, with production networks later diversifying across Asia-Pacific and North American defense corridors. Geographic demand patterns now track military procurement cycles, automotive OEM digitization programs, and extractive industry automation investments.
United States
Military modernization programs through the Department of Defense sustain MIL-STD-810H certification demand for dismounted soldier systems. FCC Part 15 emissions compliance shapes wireless-enabled model market access, while FAA battery transportation regulations constrain field replacement logistics. Defense contractors in the Virginia-Maryland corridor cluster around Pentagon procurement channels.
Germany
Automotive OEM shop-floor digitization in Baden-Württemberg and Bavaria drives handheld rugged tablet deployment for predictive maintenance workflows. EU Green Deal circular electronics mandates redirect procurement toward modular, repairable designs with standardized fastener systems. KBA certification requirements influence telematics-integrated vehicle-mounted configurations for commercial fleets.
China
MIIT enforces GB standard certifications that foreign manufacturers must obtain for public-sector tenders, creating regulatory barriers to defense and infrastructure contracts. Primary magnesium alloy smelting capacity concentrates in Shanxi and Shaanxi provinces, generating input cost volatility for housing manufacturers. Yangtze River Delta electronics clusters supply thermal management components to international OEMs.
Australia
Mining operators in Western Australia and Queensland specify graphene-enhanced thermal interface materials for pit operations across extreme temperature ranges. 5G private network rollouts in Pilbara iron ore regions enable low-latency equipment diagnostics and real-time fleet telematics. TGA-equivalent equipment certification pathways support dual-use military and civilian industrial deployments.
India
PLI scheme production-linked incentives attract contract manufacturers to establish local assembly for defense and public-sector tenders. BIS certification requirements shape procurement standards for railway and infrastructure applications. Karnataka and Tamil Nadu electronics manufacturing clusters host assembly operations serving domestic military and industrial buyers.
Three Proofing Rugged Tablet Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the rugged tablet value chain, with in-house magnesium alloy machining and thermal management component fabrication separating integrated manufacturers from assembly-dependent competitors. Market structure concentrates around three to five dominant platforms serving NATO defense programs and German automotive OEMs, with mid-tier specialists occupying regional industrial niches. Strategic archetypes include vertically integrated Japanese electronics conglomerates, Taiwan-based ODM specialists with captive thermal component supply, and US defense contractors with classified facility clearances. Competitive moves center on MIL-STD-810H requalification acceleration and modular platform architectures that reduce variant-specific engineering overhead.
Within the integrated manufacturing tier, Panasonic Corporation and Getac Technology Corporation exemplify divergent approaches to premium positioning, with the former leveraging Japanese precision electronics heritage and the latter anchoring competitive stance through upstream control over thermal management components. Zebra Technologies occupies a position among Android-focused enterprise mobility specialists competing aggressively in logistics and transportation segments with cost-optimized handheld configurations. These three anchors represent distinct strategic vectors: premium MIL-STD certification depth, vertical manufacturing integration, and volume-scale Android platform economics.
| Leading Market Players |
|---|
| Getac Technology Corporation |
| Zebra Technologies |
| Panasonic Corporation |
| Dell Technologies |
| DT Research |
| Handheld Group |
| Winmate Communication |
| Honeywell International |
| Leonardo DRS |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal circular electronics mandates are forcing manufacturers to absorb modular redesign costs while maintaining MIL-STD-810H certification premiums, compressing margins across mid-tier suppliers unable to pass compliance expenses to consolidated defense and automotive buyers.
Pricing Analysis
Three-tier pricing structure across MIL-STD-certified premium, industrial-grade standard, and cost-optimized economy levels dominates procurement. Price differentiation hinges on shock-test certification depth and magnesium alloy housing grade. Cost compression in the economy tier is intensifying because consumer tablet IP ratings are encroaching on entry-level rugged specifications. Military buyers exhibit the lowest price sensitivity due to requalification lock-in, while logistics fleet operators in developing markets resist premiums above Android-based alternatives.
Supply Chain Analysis
Magnesium alloy feedstock rests on primary smelting capacity in China, with secondary refining in Russia and emerging recovery operations in Canada. Thermal management components draw from Taiwan semiconductor fabs and Yangtze River Delta electronics clusters. Single-source vulnerability concentrates in Shanxi province rare earth processing for conformal coatings. Distribution runs through defense procurement channels in the Virginia-Maryland corridor and automotive OEM direct contracts in Baden-Württemberg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as NATO procurement programs consolidate vendor relationships around dual-use certification pathways that satisfy both military and civilian industrial requirements.
For Market Incumbents: Extend MIL-STD-810H requalification acceleration programs to compress 12-18 month validation cycles and defend against emerging Taiwan-based ODM specialists. Deepen upstream control over thermal management component fabrication to offset magnesium alloy price volatility from Chinese smelter concentration. Prioritize modular platform architectures that reduce variant-specific engineering overhead across unified product lines. For New Entrants and Emerging Players: Defense integrators with classified facility clearances offer the most penetrable channel for bypassing established certification barriers. Target India's PLI scheme production-linked incentives for local assembly serving domestic military and railway tenders. Lead with Android-based handheld configurations optimized for cost-sensitive logistics segments where Zebra Technologies has not yet entrenched. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap specialists possessing captive thermal component supply and existing automotive sector deployments. Long-term viability over a 5-10 year window favors platforms with demonstrated dual-use certification pathways. Watch for Bundeswehr and Armée de Terre tender specifications that explicitly favor suppliers with cross-sector deployment records as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-810H Requalification Acceleration | Compresses validation cycles against updated shock profiles from the US Department of Defense. |
| Modular Platform Architecture | Enables firmware-based configuration for dual-use military and automotive deployments. |
| Graphene-Enhanced Thermal Interface Integration | Supports passive cooling across Australian mining pit operations from -20°C to 60°C. |
| India PLI Scheme Local Assembly | Captures defense and public-sector tenders requiring BIS certification compliance. |
| REACH-Compliant Coating Reformulation | Maintains European market access under ECHA substance restriction mandates. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with defense procurement officers, automotive OEM manufacturing engineers, thermal management component suppliers, and rugged tablet distribution channel partners. Secondary validation draws from FCC equipment authorization databases, ECHA REACH restriction updates, MIIT GB standard certification records, and NATO tender documentation. Bottom-up demand modeling triangulates against top-down industry aggregation.
Rate-of-change decomposition separates volume expansion from value mix shifts across the projection horizon. Segmentation dimensions include product configuration, end-user procurement standards, operating system technology, and functional application. CAGRs derive from logistic curve fitting to technology adoption patterns and military procurement cycle phasing. Forecast inputs incorporate 5G private network rollout timelines and EU Green Deal implementation schedules.
Revisions become necessary when IATA lithium-ion cargo restrictions tighten, Chinese magnesium alloy export controls materialize, or consumer tablet IP ratings achieve MIL-STD-810H equivalence. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wearable Translator Market
Others
Magnesite Market
Others
DIY Smart Home Market
Others
Profilometer Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Mainframe Market
Others
Hearables Market
Others
Global Crowdsourced Testing Market
Others
Digital Thermal Plates Market
Others
North America Forklift Truck Market
Others
Chip Card Scanners Market
Others
Pin Mills Market
Others
Electric Pallet Jack Truck Market
Others
Cloud Gaming Baas Market
Others
Global Retail Media Networks Market
Others
Global Optical Comparator Market