
 Global Alternative Data Market | 2026-2036
Global Alternative Data Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alternative Data Market Foresight
Subscription-based data feed provisioning is hardening as the dominant commercial model in alternative data. Dataminr Inc. leverages real-time social media signal detection to sustain its position in event-driven trading analytics. Eagle Alpha anchors European hedge fund distribution through curated vendor due diligence and compliance documentation. YipitData Inc. differentiates by controlling proprietary panel methodologies across mobile app usage and web scraping verticals.
Alternative data comprises non-traditional information streams—satellite imagery, geolocation pings, credit card transactions, web-scraped price indices—processed through machine learning pipelines to forecast corporate performance or consumer behavior before it appears in official filings. Data analytics platforms and predictive modeling solutions command the deepest margin pools as asset managers internalize quantitative capabilities rather than outsourcing raw ingestion. Web scraping and mobile app usage represent the fastest-expanding data source types, though satellite imagery retains premium pricing power in agricultural and industrial supply chain monitoring.
The SEC enforces material non-public information boundaries that constrain how alternative data vendors structure exclusivity periods and client tiers. GDPR and the EU AI Act impose algorithmic accountability and data minimization requirements on European-deployed analytics platforms. Stakeholders must monitor evolving jurisdictional fragmentation in cross-border data licensing and decide whether to standardize compliance globally or operate regionally segmented product architectures.
Market Dynamics
Machine learning pipelines now compress raw alternative data into predictive signals faster than quarterly earnings cycles, forcing asset managers to rebuild ingestion architectures or cede alpha to quantitative competitors. This velocity differential is restructuring vendor-client power dynamics and compliance obligations simultaneously.
Growth Catalysts
- EU AI Act algorithmic accountability mandates:European hedge funds now demand documented model lineage from data vendors, creating premium tiers for compliant providers. This regulatory pressure accelerates vendor consolidation around audit-ready platforms.
- Credit card transaction streams:Real-time consumer spending panels enable earnings prediction models that flag revenue inflections weeks before SEC filings. Asset managers embed these signals directly into systematic trading strategies.
- United States:SEC material non-public information boundaries force vendors to engineer precise exclusivity windows and tiered release schedules, professionalizing data distribution infrastructure.
Market Restraints
- GDPR data minimization requirements:European-deployed platforms must purge geolocation histories and transaction identifiers earlier than predictive models prefer, degrading longitudinal panel quality.
- Scraping infrastructure costs:Web crawling at scale demands rotating proxy networks and anti-detection engineering that consumes 15-25% of vendor operating budgets.
- Panel attrition in mobile app tracking:Consumer opt-out rates for app usage monitoring climb as iOS privacy prompts proliferate, thinning proprietary data moats.
Strategic Opportunities
- Synthetic data generation:Generative models trained on satellite imagery and transaction patterns create privacy-compliant substitutes for restricted raw feeds, opening European and Middle Eastern markets previously blocked by GDPR.
- India:SEBI's expanding alternative investment fund regulations and underdeveloped sell-side research infrastructure create first-mover advantages for global data vendors establishing local partnerships.
- Carbon accounting integration:Supply chain emissions tracking via satellite-detected industrial activity merges ESG mandates with traditional alpha generation, attracting European institutional capital.
Industry Challenges
- Quantitative talent scarcity:The intersection of geospatial analytics, natural language processing, and financial modeling demands hybrid skill sets that command compensation premiums exceeding traditional software engineering by 40-60%.
- Legacy system integration friction:Asset managers running decades-old portfolio management software struggle to pipe real-time alternative data feeds into batch-oriented risk engines without expensive middleware rebuilds.
- IP boundary litigation:Web scraping disputes with e-commerce platforms and social media networks generate cease-and-desist exposure that threatens vendor business model viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alternative Data Market |
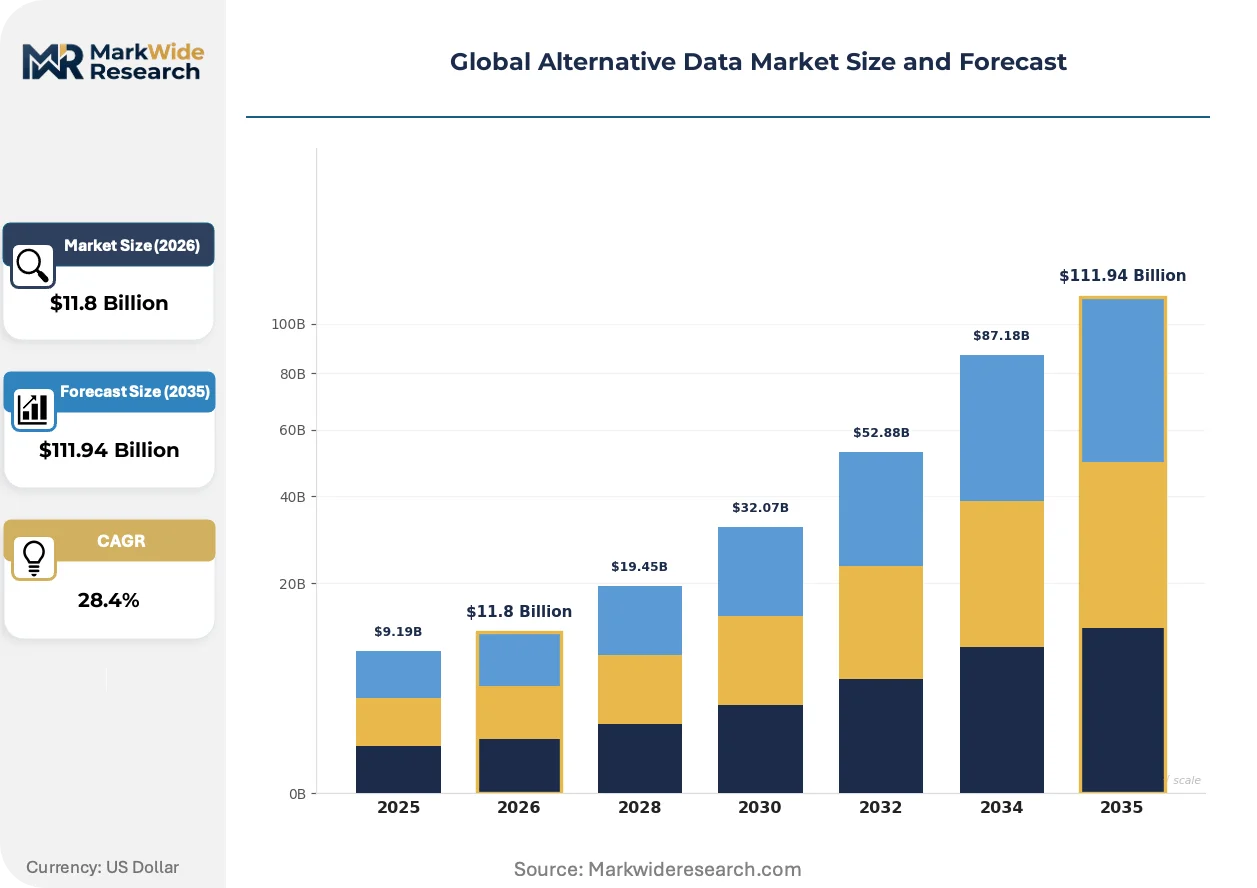
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $111.94 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Source Type: Social Media, Satellite Imagery, Web Scraping, Geolocation, Credit Card Transactions, Mobile App Usage Solution Offering: Data Analytics Platforms, Data Aggregation Services, Predictive Modeling, Market Intelligence Tools, Risk Management Solutions, Compliance Monitoring Use Case: Investment Research, Fraud Detection, Consumer Behavior Analysis, Supply Chain Optimization, Pricing Intelligence, Competitive Benchmarking End User Industry: Hedge Funds, Asset Managers, Insurance Firms, Retail Banks, E-commerce, Telecommunications |
| Companies Covered | 1010Data Inc., Dataminr Inc., Eagle Alpha, M Science LLC, RavenPack International S.L., YipitData Inc., Advan Research Corporation, Thinknum Inc., Earnest Research Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alternative Data Market Shifts & Advancements
Alternative data markets are bifurcating between raw feed commoditization and analytics-layer premium capture, with vendor survival hinging on proprietary signal extraction rather than data volume aggregation.
Natural language processing engines trained on earnings call transcripts, regulatory filings, and executive social media activity are overtaking traditional sentiment indicators derived from equity price momentum alone. Quantitative hedge funds now deploy transformer architectures to detect linguistic micro-shifts that precede guidance revisions. This capability compression is collapsing the information advantage window from weeks to hours.
The EU AI Act's risk classification framework for algorithmic decision-making imposes documentation burdens on European-deployed predictive platforms that US-based competitors avoid. Vendors serving cross-border asset managers now maintain dual compliance architectures, with European instances running stripped-down feature sets to satisfy audit trail requirements. This jurisdictional fragmentation inflates engineering overhead and fragments product roadmaps.
Buy-side procurement teams now unbundle data sourcing from analytics execution, contracting directly with satellite operators and credit card networks while building in-house machine learning layers. This disintermediation pressures traditional aggregators to reposition as infrastructure providers or risk margin erosion. The shift is most pronounced among North American multi-strategy funds with captive quantitative research divisions.
Global Alternative Data Market Segmentation
Alternative data procurement decisions hinge on signal latency, regulatory exposure, and integration complexity rather than price alone. Asset managers evaluate segments through the lens of alpha generation potential versus compliance burden.
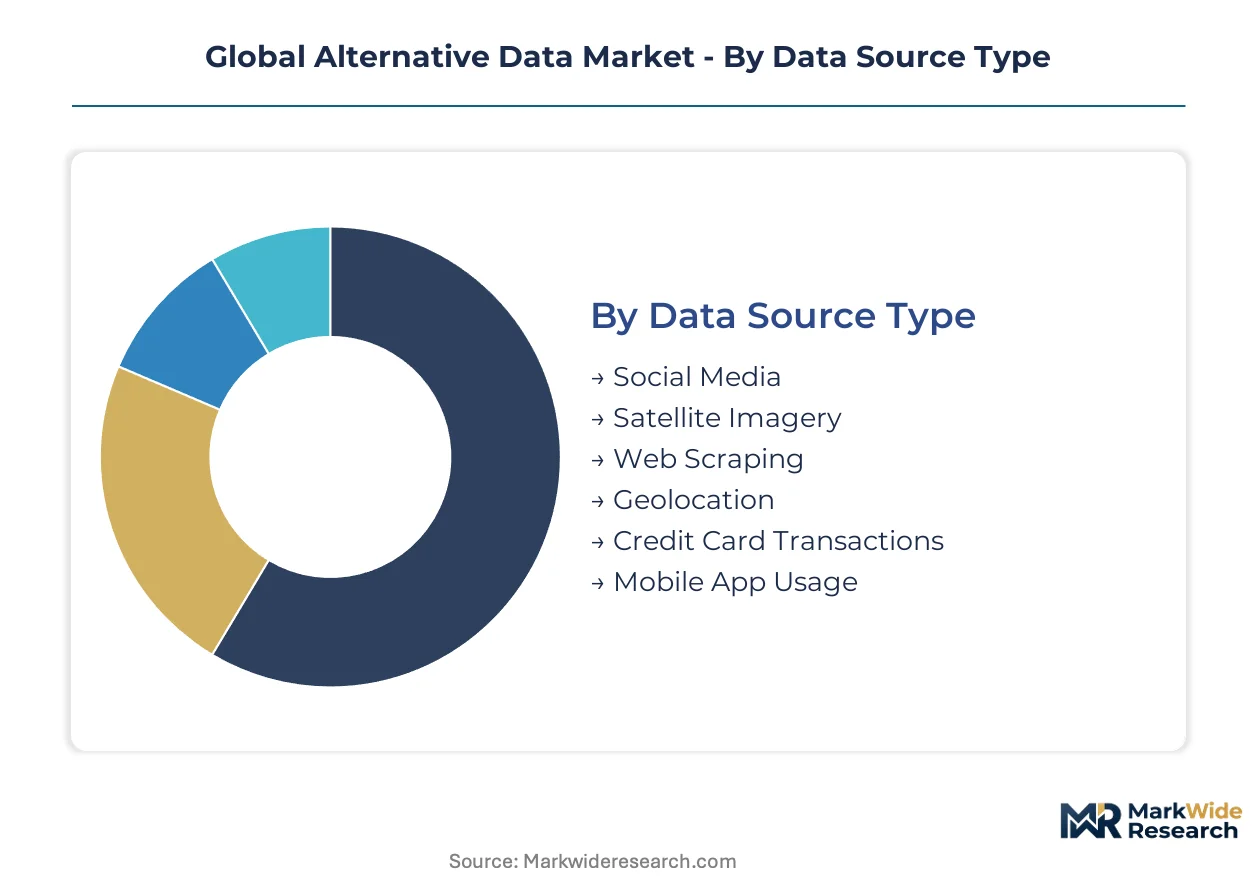
Data Source Type:
Buyers prioritize data freshness and exclusivity windows when selecting source categories.
- Satellite Imagery:Optical and synthetic aperture radar captures of agricultural fields, industrial facilities, and retail parking lots enable supply chain disruption forecasting. Premium pricing persists in agricultural monitoring for commodity trading desks in the United States and Brazil.
- Credit Card Transactions:De-identified consumer spending panels track revenue inflections at merchant-level granularity before quarterly earnings releases. Hedge funds in the United States embed these signals directly into systematic equity strategies.
- Web Scraping:Automated extraction of pricing, inventory, and sentiment data from e-commerce platforms and corporate websites.
- Geolocation:Aggregated mobile device movement patterns tracking foot traffic to retail locations and industrial sites.
- Social Media:Real-time processing of platform posts, comments, and engagement metrics for event detection.
- Mobile App Usage:Panel data on application downloads, session duration, and in-app purchase flows.
Volume sits with web scraping; growth tilts toward credit card transactions.
Solution Offering:
Margin capture concentrates in analytics layers as raw feed commoditization accelerates.
- Data Analytics Platforms:Cloud-native infrastructure for signal extraction, feature engineering, and visualization. Asset managers in the United States and United Kingdom favor platforms with pre-built connectors to portfolio management systems.
- Predictive Modeling:Machine learning pipelines that transform raw alternative data into earnings estimates, default probabilities, or demand forecasts. European hedge funds demand documented model lineage to satisfy EU AI Act audit requirements.
- Data Aggregation Services:Curated vendor relationships and due diligence documentation for procurement teams.
- Market Intelligence Tools:Dashboards and alerts for competitive positioning and industry trend monitoring.
- Risk Management Solutions:Integration of alternative signals into credit, operational, and market risk frameworks.
- Compliance Monitoring:Automated surveillance of regulatory filings, sanctions lists, and adverse media.
Revenue concentrates in data analytics platforms; predictive modeling is climbing the fastest.
Use Case:
Application selection tracks the maturity of internal quantitative capabilities.
- Investment Research:Alpha generation through earnings prediction, event detection, and sentiment analysis. Quantitative hedge funds in the United States deploy transformer architectures on earnings call transcripts.
- Consumer Behavior Analysis:Tracking spending shifts, brand switching, and demographic migration patterns. Retail banks in India leverage mobile app usage panels for credit underwriting.
- Fraud Detection:Anomaly identification in transaction patterns and identity verification workflows.
- Supply Chain Optimization:Disruption forecasting via satellite-detected port congestion and industrial activity.
- Pricing Intelligence:Competitive price monitoring and dynamic pricing algorithm inputs.
- Competitive Benchmarking:Market share estimation and performance comparison against peers.
Deployment breadth favors investment research; steepest expansion trajectory sits with consumer behavior analysis.
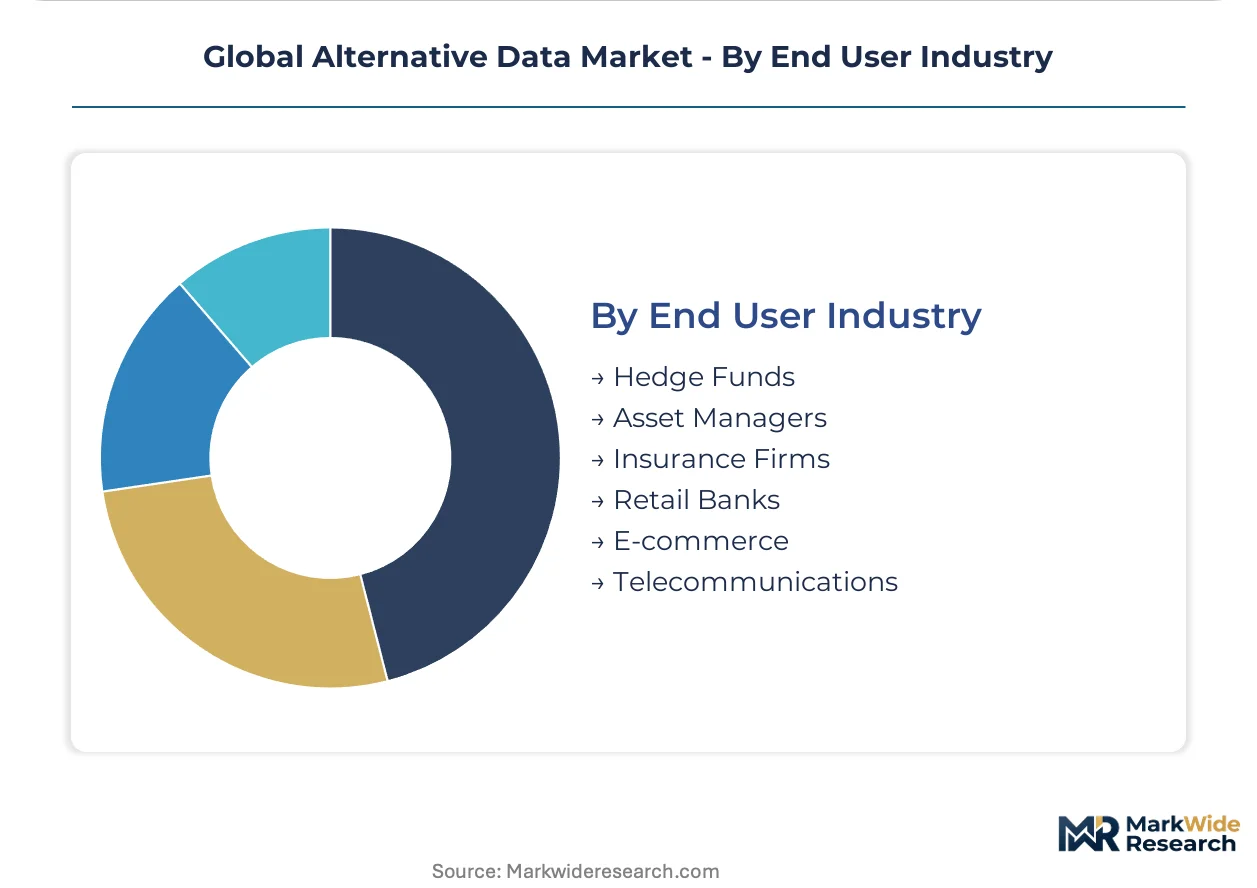
End User Industry:
Customer sophistication determines contract structure and service tier access.
- Hedge Funds:Systematic and discretionary strategies with captive quantitative research teams demanding low-latency feeds and custom signal development. Multi-strategy funds in the United States unbundle data sourcing from analytics execution.
- Asset Managers:Long-only and alternative investment vehicles integrating alternative data into fundamental research processes. European asset managers prioritize GDPR-compliant data sets with documented consent architectures.
- Insurance Firms:Property and casualty underwriters using satellite imagery for catastrophe risk assessment.
- Retail Banks:Credit risk modeling and customer acquisition targeting via transaction and behavioral data.
- E-commerce:Competitive intelligence and demand forecasting for inventory and pricing decisions.
- Telecommunications:Subscriber churn prediction and network planning via geolocation analytics.
Spend concentration rests with hedge funds; asset managers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manhattan's Financial District anchors the world's densest concentration of alternative data procurement desks, where systematic hedge funds and quantitative asset managers cluster within blocks of major exchanges.
United States
SEC material non-public information enforcement shapes vendor contract structures and exclusivity windows. The Dodd-Frank Act's derivatives oversight extends to data-driven trading strategies, requiring documented signal provenance. Chicago's commodity trading houses deploy satellite imagery for agricultural supply chain monitoring alongside New York's equity-focused quantitative funds.
United Kingdom
FCA conduct rules govern how buy-side firms integrate alternative data into investment processes, with particular scrutiny on insider information boundaries. The Bank of England's systemic risk framework now incorporates non-traditional data feeds for stress testing. London's Square Mile hosts Eagle Alpha's European distribution operations, serving continental hedge funds with compliance-documented vendor relationships.
Germany
BaFin's algorithmic trading regulations impose transparency requirements on predictive models using alternative data inputs. The EU AI Act's risk classification system forces Frankfurt-based asset managers to maintain audit trails for machine learning pipelines. Munich's insurance sector applies satellite imagery to catastrophe risk modeling, distinct from the trading-focused applications dominating London and New York.
India
SEBI's alternative investment fund regulations create regulatory clarity for foreign data vendors establishing local partnerships. The RBI's payments data localization requirements constrain cross-border transaction panel construction. Mumbai's domestic mutual funds increasingly license mobile app usage analytics for consumer discretionary stock selection, bypassing underdeveloped sell-side research infrastructure.
Singapore
MAS fintech licensing frameworks accommodate alternative data aggregation as a regulated activity, attracting regional headquarters for global vendors. The Personal Data Protection Act governs geolocation and transaction data processing with stricter consent requirements than US jurisdictions. Singapore's wealth management sector serves as distribution gateway for Southeast Asian family offices seeking systematic strategy exposure.
Global Alternative Data Market Competitive Landscape
Capital-heavy data infrastructure operators compete with asset-light analytics specialists for margin capture in alternative data value chains. The vendor landscape stratifies between raw feed aggregators maintaining direct sensor and panel relationships, platform providers offering cloud-native signal extraction tools, and boutique consultancies delivering bespoke predictive models. Three archetypes dominate: satellite and transaction network operators controlling proprietary data generation, analytics layer vendors compressing raw feeds into investment signals, and compliance-focused intermediaries curating vendor due diligence for regulated buyers. Competitive dynamics center on exclusive data sourcing contracts and API integration depth with portfolio management systems.
Among US-based analytics specialists, Dataminr Inc. and YipitData Inc. exemplify the platform archetype, converting real-time social media detection and mobile app panel data respectively into systematic trading inputs. Eagle Alpha occupies a position within the European compliance intermediary tier, anchoring vendor curation services for GDPR-constrained asset managers. These three entities represent contrasting geographic and functional specializations without implying specific market share or strategic priority.
| Leading Market Players |
|---|
| 1010Data Inc. |
| Dataminr Inc. |
| Eagle Alpha |
| M Science LLC |
| RavenPack International S.L. |
| YipitData Inc. |
| Advan Research Corporation |
| Thinknum Inc. |
| Earnest Research Company |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up data aggregators now dominate the alternative data supply base, compressing vendor margins through portfolio-wide procurement leverage while simultaneously professionalizing pricing discipline through standardized API tiers and audit-ready compliance bundles.
Pricing Analysis
Outcome-based pricing anchors vendor contracts to alpha generation metrics rather than raw data volume. Three-tier pricing structure across premium, standard, and economy levels separates hedge funds with captive quant teams from asset managers outsourcing signal extraction entirely. Cost compression in the standard tier is intensifying because buy-side procurement teams now unbundle data sourcing from analytics execution. Hedge funds with systematic strategies exhibit lowest price sensitivity; regional asset managers in compliance-heavy jurisdictions face highest budget constraints.
Supply Chain Analysis
Reverse-logistics flows barely exist in alternative data, though satellite operators now refurbish decommissioned orbital assets for secondary geolocation panel services. Supply concentrates in the United States, the United Kingdom, and India, where regulatory clarity around SEC, FCA, and SEBI frameworks attracts vendor headquarters. Raw feed generation draws from proprietary sensor networks, consumer panel partnerships, and web crawling infrastructure. Single-source vulnerability threatens providers dependent on exclusive credit card network relationships. Distribution runs through cloud-native API marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alternative data market is becoming a vertical-integration race, with incumbents pursuing backward integration into proprietary sensor networks while new entrants seek downstream control through captive analytics layers.
For Market Incumbents: Cement exclusive data sourcing contracts with satellite operators and credit card networks before consolidation eliminates available partners. Add predictive modeling capacity in London or Frankfurt to satisfy EU AI Act documentation requirements. Margin pressure from buy-side unbundling demands faster signal extraction pipelines to justify premium tiers. For New Entrants and Emerging Players: Begin with synthetic data generation capabilities targeting European asset managers blocked by GDPR from raw geolocation feeds. India's underdeveloped sell-side research infrastructure offers the most penetrable geography for mobile app usage analytics. A regulatory-first go-to-market angle—pre-built compliance documentation—accelerates procurement cycles with risk-conscious buyers. For Investors and Strategic Acquirers: Distressed-cycle entries favor analytics-layer specialists with documented model lineage in Germany or France, where BaFin and EU AI Act enforcement has strained engineering-light competitors. Long-term viability hinges on proprietary signal extraction IP rather than volume aggregation. Watch for SEBI regulatory clarity in India as an inflection indicator for emerging market expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Sensor Network Acquisition | Captive satellite or transaction data feeds eliminate third-party dependency and margin leakage to raw feed aggregators. |
| EU AI Act Compliance Certification | Documented model lineage unlocks European hedge fund procurement budgets constrained by algorithmic accountability mandates. |
| Synthetic Data Generation Platform Launch | Privacy-compliant substitutes open Middle Eastern and European markets previously blocked by GDPR geolocation restrictions. |
| India Local Partnership Formation | SEBI-registered alternative investment fund structures enable first-mover positioning in mobile app analytics for domestic mutual funds. |
| Carbon Accounting Integration | Supply chain emissions tracking via satellite-detected industrial activity merges ESG mandates with traditional alpha generation for European institutional capital. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with hedge fund quantitative researchers, asset manager procurement leads, data vendor product managers, and compliance officers at European regulatory technology firms. SEC enforcement actions, EU AI Act implementation guidance, SEBI circulars, and GDPR supervisory authority decisions provided jurisdictional boundary conditions. Bottom-up vendor revenue estimates triangulated against top-down asset manager spending allocations.
Granularity-level modeling deployed separate forecast frameworks for data source type, solution offering, and end-user industry, with cross-segment interaction effects captured through elasticity matrices. CAGRs derived from trend extrapolation of vendor pricing trajectories and buy-side budget allocation surveys across the projection horizon. Panel attrition rates in mobile app tracking and satellite imagery resolution improvements served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; credit card transaction panels and satellite imagery carry tighter precision than web scraping volumes dependent on anti-detection engineering success. Forecasts reflect assumptions about regulatory enforcement intensity and buy-side internalization of quantitative capabilities. Practitioners should monitor iOS privacy prompt adoption rates and EU AI Act audit frequency for early signals of panel quality degradation and compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Account Aggregators Market
Financial Services
Virtual Account Management Software Market
Financial Services
US Online Trading Platform Market
Financial Services
Foreign Exchange Services Market
Financial Services
Digital Transformation in BFSI Market
Financial Services
Global Product Cost Management Market
Financial Services
Latin America Factoring Services Market
Financial Services
Middle East Financial Consulting Software Market
Financial Services
Benefits Consulting Service Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
BFSI A2P SMS Market
Financial Services
South Korea Trade Finance Market
Financial Services
Debt Settlement Solution Market
Financial Services
Currency Management Market
Financial Services
Islamic Finance Market