
 Europe E-Brokerages Market | 2026-2036
Europe E-Brokerages Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Brokerages Market Foresight
Digital finance talent scarcity across continental Europe is reorganizing how e-brokerages scale their technology stacks. FlatexDEGIRO leverages its combined German-Dutch infrastructure to sustain low-cost execution across multiple exchanges. Interactive Brokers anchors its European presence through direct market access and advanced order routing capabilities.
Europe E-Brokerages are internet-based financial intermediaries that execute securities orders, manage portfolios, and deliver investment analytics through proprietary platforms with sub-second latency requirements and bank-grade encryption protocols. Their primary commercial purpose is to disintermediate traditional wealth management by offering self-directed investors direct control over asset allocation at reduced cost structures. Commission-free trading dominates transaction volume among retail participants, while robo-advisory services capture expanding margin pools from mass-affluent clients seeking automated portfolio construction. Algorithmic trading infrastructure represents the fastest-growing technology segment as institutional demand for systematic execution strategies intensifies.
MiFID II, GDPR, and the EU Digital Operational Resilience Act (DORA) collectively shape product architecture, data handling protocols, and cybersecurity investment requirements for platforms operating across EU member states. The European Securities and Markets Authority (ESMA) enforces leverage limits and negative balance protection rules that directly constrain spread betting and forex trading business models. Stakeholders must monitor how the EU AI Act's risk classification framework will apply to algorithmic trading engines and automated advisory algorithms before committing to multi-year platform development roadmaps.
Market Dynamics
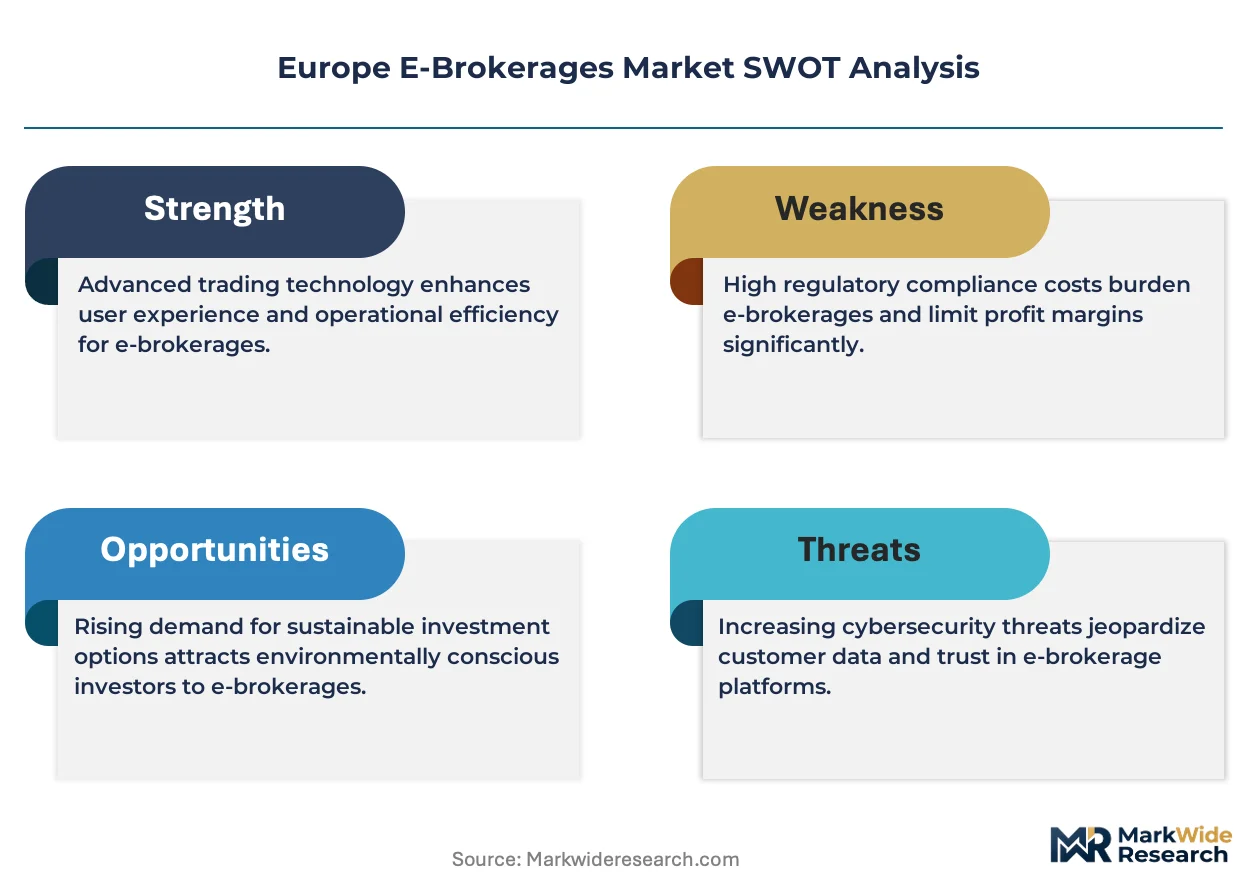
MiFID II transparency mandates and the EU Digital Operational Resilience Act are compressing legacy fee structures while forcing infrastructure consolidation among continental platforms. The collision between regulatory compliance costs and commission-free pricing models is restructuring competitive economics across Germany, France, and the Netherlands.
Growth Catalysts
- Algorithmic Execution Infrastructure:Systematic trading strategies from institutional clients demand sub-millisecond latency, pulling investment into co-located server networks and direct exchange connectivity.
- Retail Self-Direction:Mass-affluent investors across the Netherlands and France are abandoning traditional wealth advisors for self-controlled portfolio allocation through mobile-native interfaces.
- DORA Compliance Investment:The EU Digital Operational Resilience Act mandates bank-grade cybersecurity and operational continuity frameworks, creating vendor consolidation opportunities for platforms with pre-certified infrastructure.
Market Restraints
- Negative Balance Protection Rules:ESMA-enforced leverage limits on forex and spread betting products constrain margin revenue from high-frequency retail traders.
- Cloud Concentration Risk:Dependence on hyperscale providers (AWS, Azure, GCP) for trade execution infrastructure creates single-point-of-failure exposure during regional outages.
- Technical Debt Burden:Legacy core banking integrations from acquired subsidiaries fragment order routing efficiency and inflate maintenance overhead.
Strategic Opportunities
- Robo-Advisory White Space:Automated portfolio construction for mass-affluent segments in Spain and Italy remains underpenetrated relative to Northern European adoption rates.
- ESG Data Monetization:MiFID II sustainability disclosure requirements create demand for proprietary ESG scoring engines that can be licensed to third-party advisors.
- API-First Distribution:Embedded finance partnerships with neobanks and fintech apps enable customer acquisition without direct marketing spend.
Industry Challenges
- Quantitative Developer Scarcity:Competition for Python and C++ engineers with derivatives pricing expertise outpaces supply in Frankfurt and Amsterdam tech labor markets.
- Cross-Border Licensing Complexity:Passporting rights under MiFID II require maintaining separate compliance frameworks for each member state's national regulator.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Brokerages Market |
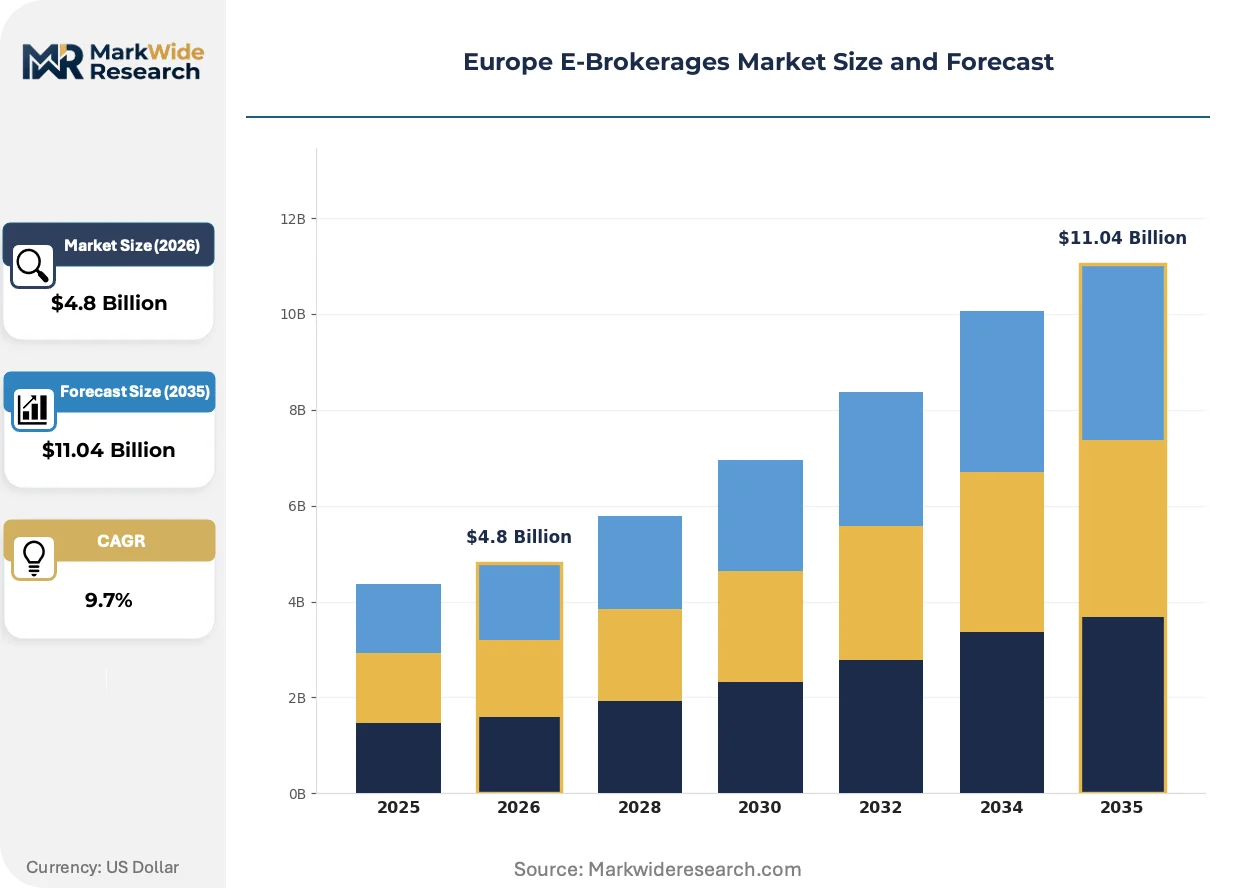
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Online Trading, Robo-Advisory, Forex Trading, Investment Research Customer Type: Retail Investors, Institutional Traders, Financial Advisors, Wealth Managers Technology: Algorithmic Trading, Blockchain, Mobile Platforms, AI Analytics Business Model: Commission-Based, Subscription, Free Trading, Spread Betting |
| Companies Covered | FlatexDEGIRO, Flatex, Interactive Brokers, N26, Revolut, Trade Republic, DEGIRO, Charles Schwab, Scalable Capital, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Brokerages Market Shifts & Advancements
Platform architecture is fragmenting into modular, API-connected components as regulatory pressure and cost competition force specialization. The separation of execution, custody, and advisory functions into interoperable layers is redefining competitive moats.
Microservices-based trading infrastructure is decomposing monolithic legacy platforms into containerized execution, risk, and settlement modules. Tier-two e-brokerages in France and Germany are adopting this architecture to reduce time-to-market for new products from months to weeks. The decomposition of vertically integrated stacks is enabling smaller platforms to compete on feature velocity without matching the capital expenditure of full-stack competitors.
GDPR Article 17 right-to-erasure mandates are forcing architectural redesign of trade history databases and audit trail systems. Platforms must now maintain cryptographically verifiable records while enabling complete data deletion for departing clients. The German and Dutch markets are experiencing the most acute compliance friction due to their stringent national data protection authority interpretations.
Subscription-based advisory models are displacing transaction-dependent revenue structures among established European platforms. Mass-affluent clients in the Netherlands increasingly prefer fixed monthly fees for unlimited trading over per-order commissions. This behavioral shift is most visible among investors aged 30-45 who prioritize predictable costs over occasional zero-commission promotions.
Europe E-Brokerages Market Segmentation
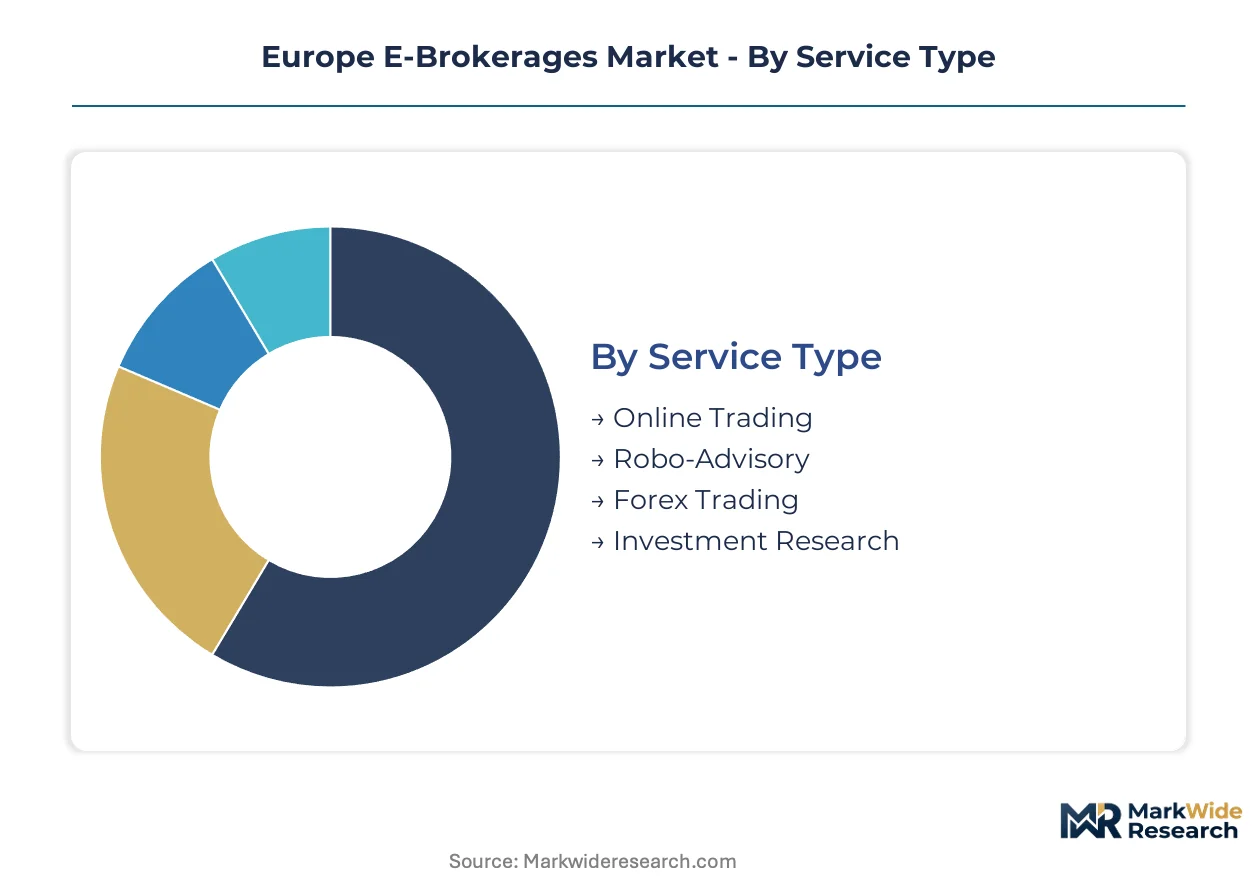
Segmentation in Europe E-Brokerages reveals how regulatory frameworks and investor behavior fragment platform economics across service tiers. Understanding these divisions exposes where commission compression hits hardest and which technology investments yield defensive positioning.
Service Type:
Domestic retail flows concentrate in execution-heavy segments, while cross-border institutional demand pulls toward advisory and research layers.
- Online Trading:Direct market access interfaces for equities, ETFs, and derivatives with sub-second order routing. German and Dutch retail investors drive volume here, though MiFID II best-execution rules force continuous infrastructure upgrades that squeeze per-trade margins.
- Robo-Advisory:Automated portfolio construction using risk-tolerance algorithms and passive fund allocation. Mass-affluent segments in France and the Netherlands adopt fastest, attracted by fixed-fee predictability amid volatile commission structures.
- Forex Trading:Currency pair speculation with leveraged positions. ESMA leverage caps constrain revenue per account, pushing platforms toward higher-volume, lower-margin client acquisition in Southern Europe.
- Investment Research:Proprietary analytics and third-party data subscriptions. GDPR Article 17 erasure mandates complicate historical data retention for personalized recommendation engines.
Online Trading commands the established base. The steepest expansion runs through Robo-Advisory.
Customer Type:
Cost tier separation dominates: self-directed retail tolerates zero-commission models, while institutional and advisory channels demand premium execution and compliance infrastructure.
- Retail Investors:Self-directed individuals executing trades through mobile-native interfaces. Netherlands and German markets show highest penetration, with subscription fatigue emerging among users cycling between promotional zero-fee offers.
- Institutional Traders:Asset managers and hedge funds requiring direct market access and algorithmic execution. Co-location fees and exchange connectivity investments concentrate demand among Frankfurt and Amsterdam trading desks.
- Financial Advisors:Intermediaries using platform infrastructure for client portfolio management. MiFID II suitability requirements force API integrations that smaller platforms struggle to certify.
- Wealth Managers:High-net-worth-focused practices demanding white-label custody and reporting. French private banking networks increasingly outsource execution to specialized e-brokerage infrastructure.
Retail Investors anchor volume throughput. Institutional Traders deliver the most resilient fee capture.
Technology:
Maturity gradients separate proven execution stacks from experimental layers still seeking regulatory clarity under EU AI Act risk classifications.
- Algorithmic Trading:Systematic execution strategies using co-located infrastructure and direct exchange feeds. Frankfurt-based quantitative desks drive demand, though DORA operational resilience audits now delay deployment timelines.
- Blockchain:Distributed ledger prototypes for settlement and tokenized asset custody. Regulatory ambiguity from national financial supervisors fragments pilot programs across member states.
- Mobile Platforms:Native iOS and Android interfaces with biometric authentication. French and Spanish retail adoption depends on simplified KYC flows that clash with GDPR data minimization principles.
- AI Analytics:Machine learning models for price prediction and risk scoring. EU AI Act high-risk system classifications threaten to mandate external auditing for advisory algorithms.
Algorithmic Trading holds the production-critical position. AI Analytics faces the steepest regulatory climb.
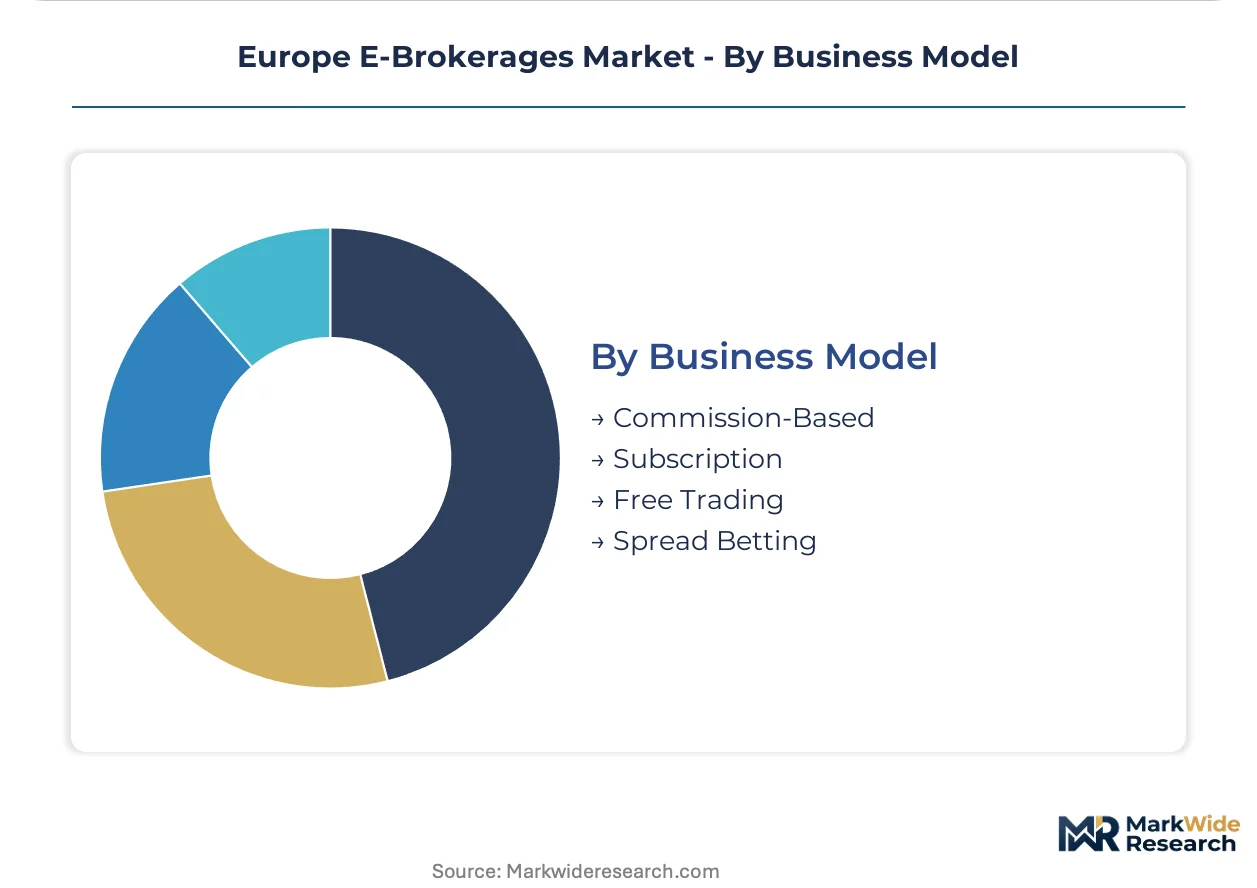
Business Model:
Margin structure varies sharply: spread-dependent models suffer under ESMA leverage limits, while recurring revenue streams gain favor as transaction volatility rises.
- Commission-Based:Per-trade fees on executed orders. MiFID II transparency rules have collapsed these structures to near-zero in competitive markets, forcing ancillary revenue dependence.
- Subscription:Fixed monthly fees for unlimited trading and premium features. Dutch investors aged 30-45 show strongest preference, valuing cost predictability over occasional promotional pricing.
- Free Trading:Zero-commission execution with payment-for-order-flow or securities lending offsets. German BaFin scrutiny of PFOF arrangements threatens this model's sustainability.
- Spread Betting:Derivative contracts on price movements without underlying ownership. UK-origin platforms dominate, though continental expansion hits ESMA product intervention barriers.
Commission-Based models retain legacy account bases. Subscription structures are gaining share fastest among new customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ESMA's MiFID II enforcement framework anchors the regulatory environment across European e-brokerages. The analysis spans five national markets where platform adoption, regulatory interpretation, and infrastructure investment diverge materially.
Germany
BaFin's scrutiny of payment-for-order-flow arrangements is pressuring zero-commission sustainability models. The German regulator's 2024 guidance on best execution transparency forced immediate disclosure upgrades across Frankfurt-based platforms. Bavaria's quantitative trading clusters around Munich and Nuremberg are absorbing DORA-mandated operational resilience audits that delay algorithmic deployment timelines.
Netherlands
Dutch retail investors aged 30-45 are driving subscription-based advisory adoption faster than any neighboring market. The Dutch Authority for Financial Markets enforces strict negative balance protection that limits leveraged forex revenue per account. Amsterdam's co-location facilities concentrate institutional algorithmic demand, with Euronext connectivity investments pulling Frankfurt and London desks into Dutch infrastructure.
France
AMF enforcement of MiFID II suitability requirements is fragmenting platform certification burdens for API integrations. The French regulator's interpretation of GDPR Article 17 is forcing architectural redesign of trade history databases. Paris-based private banking networks increasingly outsource execution to specialized e-brokerage infrastructure, concentrating demand in Île-de-France.
United Kingdom
FCA leverage limits on spread betting products constrain continental expansion for UK-origin platforms. The British regulator's operational resilience rules predate DORA but align closely enough to ease cross-border compliance for dual-authorized firms. London's fintech corridor retains concentration in white-label custody and reporting technology despite post-Brexit passporting friction.
Spain
CNMV supervision of simplified KYC flows is clashing with GDPR data minimization principles for mobile-native onboarding. The Spanish regulator's retail investor protection framework lags Northern European stringency, attracting platform marketing spend. Madrid's emerging robo-advisory adoption trails Netherlands and France by several years, leaving automated portfolio construction underpenetrated among mass-affluent segments.
Europe E-Brokerages Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across execution, advisory, and technology provision. The upper tier combines direct market access infrastructure with multi-exchange connectivity and bank-grade custody frameworks. Three strategic archetypes dominate: full-stack incumbents with legacy banking integrations, mobile-native challengers with subscription-first revenue models, and infrastructure specialists selling API access to third-party distributors. Competitive moves concentrate on M&A consolidation to absorb compliance costs and geographic expansion through passporting rights optimization.
Within the integrated infrastructure tier, FlatexDEGIRO and Interactive Brokers exemplify divergent scale strategies. FlatexDEGIRO leverages its combined German-Dutch operational footprint to sustain low-cost execution across multiple European exchanges. Interactive Brokers anchors its positioning through direct market access capabilities and advanced order routing infrastructure. Among mobile-native challengers, Trade Republic represents the subscription-model archetype that has captured Dutch and German retail segments seeking cost predictability.
| Leading Market Players |
|---|
| FlatexDEGIRO |
| Flatex |
| Interactive Brokers |
| N26 |
| Revolut |
| Trade Republic |
| DEGIRO |
| Charles Schwab |
| Scalable Capital |
| Others |
Supply & Pricing Matrix
MiFID II best-execution transparency mandates gate both infrastructure qualification and price differentiation across European e-brokerages simultaneously. Platforms must maintain co-located server networks and direct exchange connectivity to compete, while subscription models and zero-commission tiers segment buyers by cost predictability preferences.
Pricing Analysis
Long-term subscription contracts dominate mass-affluent client relationships, offsetting spot-transaction volatility from retail traders. Three-tier pricing structure across premium algorithmic execution, standard self-directed trading, and economy zero-commission tiers separates institutional desks from subscription-paying retail and payment-for-order-flow dependent accounts. Cost compression in the commission-free segment intensifies as BaFin scrutiny of PFOF arrangements threatens revenue offsets. Retail investors aged 30-45 in the Netherlands exhibit lowest price sensitivity, prioritizing fixed-fee predictability over promotional zero-commission offers.
Supply Chain Analysis
Just-in-time infrastructure deployment prevails for cloud-based execution stacks, though DORA-mandated operational resilience audits are forcing strategic stockpiles of redundant connectivity and backup custody arrangements. Hyperscale providers in Ireland, Germany, and the Netherlands anchor primary trade execution infrastructure, drawing from AWS, Azure, and GCP data center networks. Raw material dependencies span sub-millisecond fiber connectivity, cryptographic hardware security modules, and proprietary order routing software. Single-source vulnerability concentrates in cloud provider concentration risk. Distribution runs through API-first partnerships with neobanks and embedded finance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European e-brokerages present a defensive-moat market anchored in regulatory entrenchment. MiFID II passporting rights and DORA certification requirements create switching costs that protect established platforms from unqualified entrants.
For Market Incumbents: Shield market position by deepening backward integration into proprietary custody infrastructure and accelerating DORA pre-certification across acquired subsidiaries. Payment-for-order-flow regulatory threat from BaFin demands alternative revenue stream development. Vertical integration into ESG data scoring engines offers licensing revenue diversification. For New Entrants and Emerging Players: Anchor in Spain and Italy's underpenetrated robo-advisory segments, where automated portfolio construction trails Northern European adoption by measurable gaps. API-first distribution partnerships with regional neobanks enable customer acquisition without direct marketing spend. White-label advisory infrastructure for French private banking networks represents the most penetrable institutional channel. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across algorithmic trading infrastructure as co-location fees and exchange connectivity investments escalate. Five-to-ten year viability favors platforms with pre-certified DORA frameworks and existing MiFID II passporting rights. Acquisition targets should display modular microservices architecture enabling rapid product iteration. Watch for EU AI Act high-risk system classifications triggering external audit mandates for advisory algorithms as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Distribution Partnerships | Embedded finance integrations with neobanks reduce customer acquisition costs across Netherlands and German retail segments. |
| ESG Data Engine Development | Proprietary sustainability scoring capabilities address MiFID II disclosure mandates while creating licensable third-party revenue streams. |
| Microservices Architecture Migration | Containerized execution modules reduce time-to-market for new products from months to weeks in competitive tier-two platforms. |
| DORA Pre-Certification Investment | Bank-grade operational resilience frameworks create vendor consolidation opportunities as smaller platforms face compliance cost barriers. |
| Robo-Advisory Geographic Expansion | Automated portfolio construction penetration in Spain and Italy captures mass-affluent segments underserved by existing advisory infrastructure. |
Research Methodology
Desk research of regulatory filings from ESMA, BaFin, AMF, and AFM preceded structured interviews with platform CTOs, quantitative trading desk heads, neobank partnership leads, and custody infrastructure vendors. Secondary validation drew from MiFID II best-execution reports, DORA implementation guidance, EU AI Act risk classification frameworks, and exchange connectivity disclosure filings. Bottom-up segmentation modeling triangulated against top-down market sizing from European Securities and Markets Authority data.
Variance-decomposition across service type, customer tier, technology stack, and business model dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate assumptions calibrated to regulatory implementation timelines and technology adoption curves. Forecast inputs incorporated algorithmic trading infrastructure investment cycles, robo-advisory penetration differentials across national markets, and subscription model migration patterns among mass-affluent demographics.
Material uncertainties — EU AI Act enforcement timing, payment-for-order-flow regulatory prohibitions, and hyperscale cloud provider outage events — sit outside the modeled envelope. Forecasts reflect assumptions regarding MiFID II passporting continuity and DORA certification pathway stability. Revision becomes warranted when ESMA product intervention rules or national data protection authority interpretations cross thresholds that fragment cross-border platform economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
US Healthcare Finance Solutions Market
Financial Services
Financial Services Application Market
Financial Services
Account Aggregators Market
Financial Services
Multivendor ATM Software Market
Financial Services
Italy Gift Card and Incentive Card Market
Financial Services
E-Brokerage Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Islamic Finance Market
Financial Services
North America B2B Legal Services Market
Financial Services
Smart Finance Services Market
Financial Services
Pawn Shop Market
Financial Services
United States Payroll Services Market
Financial Services
Treasury Management Market
Financial Services
Digital Account Opening Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
Intellectual Property Rights and Royalty Management Market