
 Streaming Media Services Market | 2026-2036
Streaming Media Services Market Size, Share, and Industry Trends Forecast 2026-2036
Streaming Media Services Market Outlook
Streaming bundle consolidation is hardening as a dominant configuration pattern across the industry. Netflix anchors its competitive position through sustained investment in original programming across multiple international markets. Disney+ leverages its deep content archives and franchise intellectual property to differentiate its subscription tiering strategy. Amazon Prime Video extends its reach by integrating video delivery with broader e-commerce and logistics memberships.
Streaming media services deliver audiovisual content over internet protocol networks using adaptive bitrate streaming technologies such as HLS and DASH, with primary commercial purpose centered on direct monetization of entertainment, educational, and sports programming to end users. Subscription-based service models currently dominate revenue capture, while ad-supported tiers represent the fastest-expanding segment as platforms pursue price-sensitive demographics and reduce churn exposure. Smart TV deployment as the primary viewing device concentrates margin pools in operating system licensing and pre-installed application distribution agreements.
The FCC in the United States oversees net neutrality and broadband infrastructure standards that directly affect streaming quality and market access conditions, while the EU Digital Services Act and GDPR impose content moderation and data handling obligations on platforms operating across European markets. Regulatory scrutiny of algorithmic recommendation systems and child protection standards is intensifying across multiple jurisdictions. Stakeholders must monitor evolving platform accountability frameworks and their operational compliance costs as these reshape competitive economics and subscriber pricing flexibility.
Market Dynamics
Bundle consolidation among major platforms is compressing subscriber acquisition costs while intensifying price competition across the United States, forcing standalone services to differentiate through exclusive content libraries or risk churn to integrated offerings.
Growth Catalysts
- Ad-Supported Tier Expansion:Platforms are introducing lower-price subscription options to capture price-sensitive households and reduce cancellation rates. The FCC's broadband infrastructure investments enable wider addressable audiences for these tiers.
- 5G Network Deployment:Mobile carriers are prioritizing video-optimized network slicing. This technology enables seamless 4K streaming on smartphones and tablets without buffering interruptions.
- Smart TV OS Licensing:Television manufacturers in South Korea and Japan are embedding streaming applications directly into device firmware. Pre-installed distribution agreements lock in default platform visibility at point of purchase.
Market Restraints
- Content Licensing Cost Inflation:Sports broadcasting rights and premium film catalogs command escalating fees. These input costs compress platform margins and limit pricing flexibility for competitive tiers.
- Subscriber Acquisition Saturation:Household penetration of major services approaches ceiling levels in mature broadband markets. New customer acquisition costs are rising faster than lifetime value projections.
- Cross-Border Content Restrictions:The EU Digital Services Act imposes territorial licensing compliance obligations. Platforms face operational friction in delivering consistent catalogs across member state boundaries.
Strategic Opportunities
- India Market Underpenetration:Mobile-first video consumption is accelerating among tier-2 and tier-3 city populations. Local language original programming investments can capture subscriber growth ahead of saturation.
- Live Sports Streaming Integration:Interactive viewing features and real-time wagering overlays are converging with traditional broadcast. This application expansion attracts advertising budgets migrating from linear television.
- Cloud Gaming Convergence:Streaming infrastructure built for video is repurposing for interactive entertainment delivery. Technology overlap creates subscriber retention synergies between passive and active content formats.
Industry Challenges
- Algorithmic Recommendation Compliance:The EU AI Act mandates transparency in content curation systems. Engineering teams must rebuild ranking architectures to satisfy audit requirements without degrading engagement metrics.
- Legacy Payment System Integration:Emerging market expansion requires accommodating cash-based and carrier-billing preferences. Platform billing infrastructure must reconfigure for heterogeneous financial ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Streaming Media Services Market |
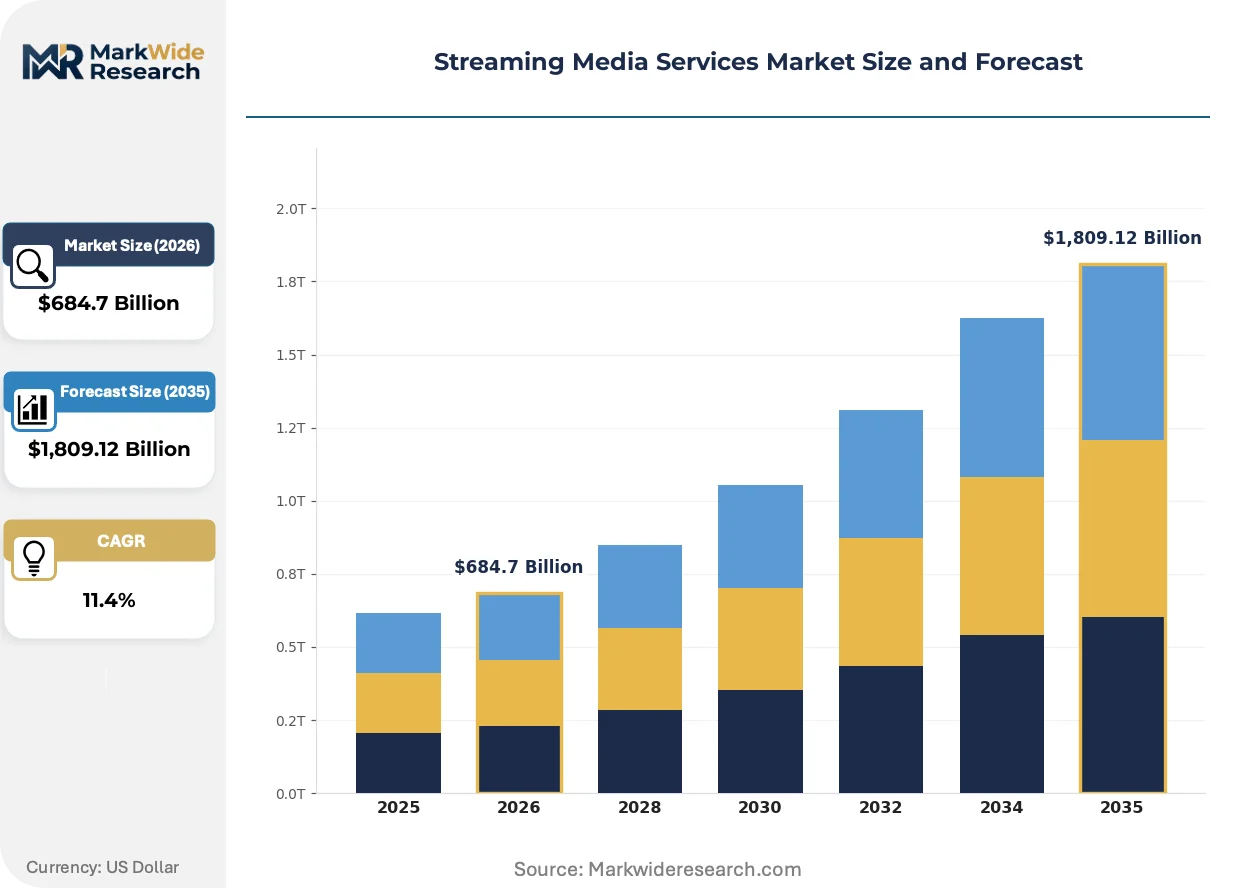
| Market Size in 2026 | $684.7 Billion |
| Market Size in 2035 | $1,809.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription-Based, Ad-Supported, Transactional Video on Demand, Premium Content Type: Movies, TV Shows, Sports, Documentaries Device Type: Smart TVs, Mobile Devices, Streaming Sticks, Game Consoles End User: Individuals, Households, Educational Institutions, Businesses |
| Companies Covered | Max, Paramount+, Netflix, Alphabet Inc., Apple TV+, Amazon Prime Video, Hulu, Roku, Disney+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Streaming Media Services Market Strategic Shifts
Artificial intelligence is reshaping content production workflows and viewer personalization engines, compressing development timelines while intensifying regulatory scrutiny of automated decision systems across major jurisdictions.
Generative AI tools for script development, dubbing, and visual effects are electrifying post-production pipelines. Mid-tier studios in Canada and Australia are adopting these capabilities to accelerate multilingual release schedules. The technology is compressing localization costs and enabling same-day global premieres that previously required staggered regional rollouts.
The EU Digital Services Act mandates algorithmic transparency and content moderation accountability for platforms exceeding threshold user bases. Enforcement mechanisms require documented risk assessments and external audit trails. European operations are responding by establishing dedicated compliance engineering teams and modifying recommendation system architectures to satisfy documentation requirements.
Household viewing patterns are fragmenting across multiple simultaneous subscriptions with shorter commitment cycles. Consumers are rotating service memberships monthly rather than maintaining year-round bundles. This behavior is most visible in the United States, where churn rates have accelerated and platforms are responding with annual discount incentives and limited-content tier experiments to extend average subscriber duration.
Streaming Media Services Market Segmentation
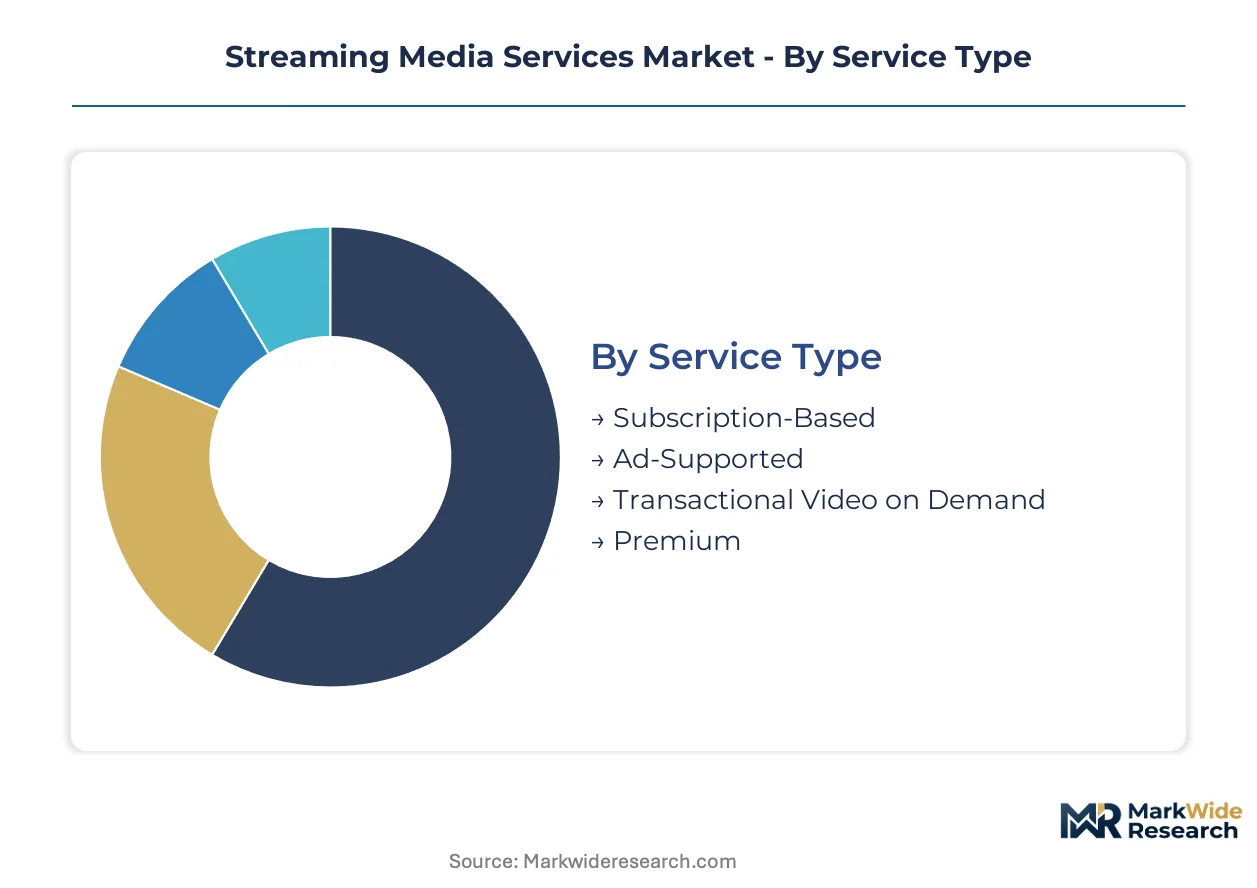
Streaming media services fragment across multiple demand dimensions that determine infrastructure investment priorities and content acquisition strategies. Understanding these segment boundaries clarifies where platforms concentrate capital deployment and which user cohorts drive margin expansion.
Service Type:
Capital intensity varies sharply across monetization models, with original content production and subscriber acquisition technology representing the dominant upfront outlays.
- Subscription-Based:Recurring revenue models demand sustained investment in exclusive content libraries and churn-reduction algorithms. Households in the United States concentrate here, driven by broadband penetration and willingness to maintain multiple simultaneous memberships.
- Ad-Supported:Lower price points attract price-sensitive demographics through targeted advertising insertion. Demand concentrates among mobile-first viewers in India, where carrier-billing integration and data-cost sensitivity constrain premium tier uptake.
- Transactional Video on Demand:Pay-per-view releases of theatrical windows and live events. Studio licensing agreements dominate cost structures.
- Premium:Bundled access to highest-fidelity streams and early-release theatrical content. Affluent households in Japan and South Korea anchor adoption.
Most installed capacity flows through Subscription-Based. Expansion is steepest in Ad-Supported.
Content Type:
Production cost profiles and territorial licensing complexity create divergent margin structures across programming categories.
- Movies:Feature-length productions command the highest per-minute production budgets and windowing restrictions. Theatrical release schedules in the United States and theatrical bypass experiments in China shape acquisition strategies.
- TV Shows:Serialized episodic content drives subscriber retention through binge-release and weekly-drop formats. European co-production treaties facilitate cross-border financing.
- Sports:Live broadcasting rights carry inflationary cost pressure and regional blackout obligations. League-specific carriage disputes fragment catalog consistency.
- Documentaries:Lower production costs enable rapid scaling of topical and educational programming. Festival acquisition pipelines in Canada and Australia supplement original production.
Catalog depth concentrates in TV Shows. Production investment is climbing fastest in Sports.
Device Type:
Hardware ecosystem control determines distribution economics and default application visibility at consumer point-of-purchase.
- Smart TVs:Operating system licensing agreements embed streaming applications directly into television firmware. South Korean and Japanese manufacturers leverage pre-installation defaults to extract revenue share from platforms.
- Mobile Devices:Smartphone and tablet consumption depends on 5G network slicing and adaptive bitrate optimization. Indian tier-2 and tier-3 cities concentrate growth as data costs decline.
- Streaming Sticks:Low-cost HDMI dongles extend legacy television compatibility. Retail shelf placement in United States big-box channels drives seasonal purchase spikes.
- Game Consoles:Console manufacturers integrate streaming alongside interactive entertainment. Japanese hardware platforms maintain tight control over store-front merchandising.
Viewing hours concentrate on Smart TVs. Subscriber additions are expanding most quickly through Mobile Devices.
End User:
Organizational procurement patterns and payment infrastructure requirements segment addressable demand by account type.
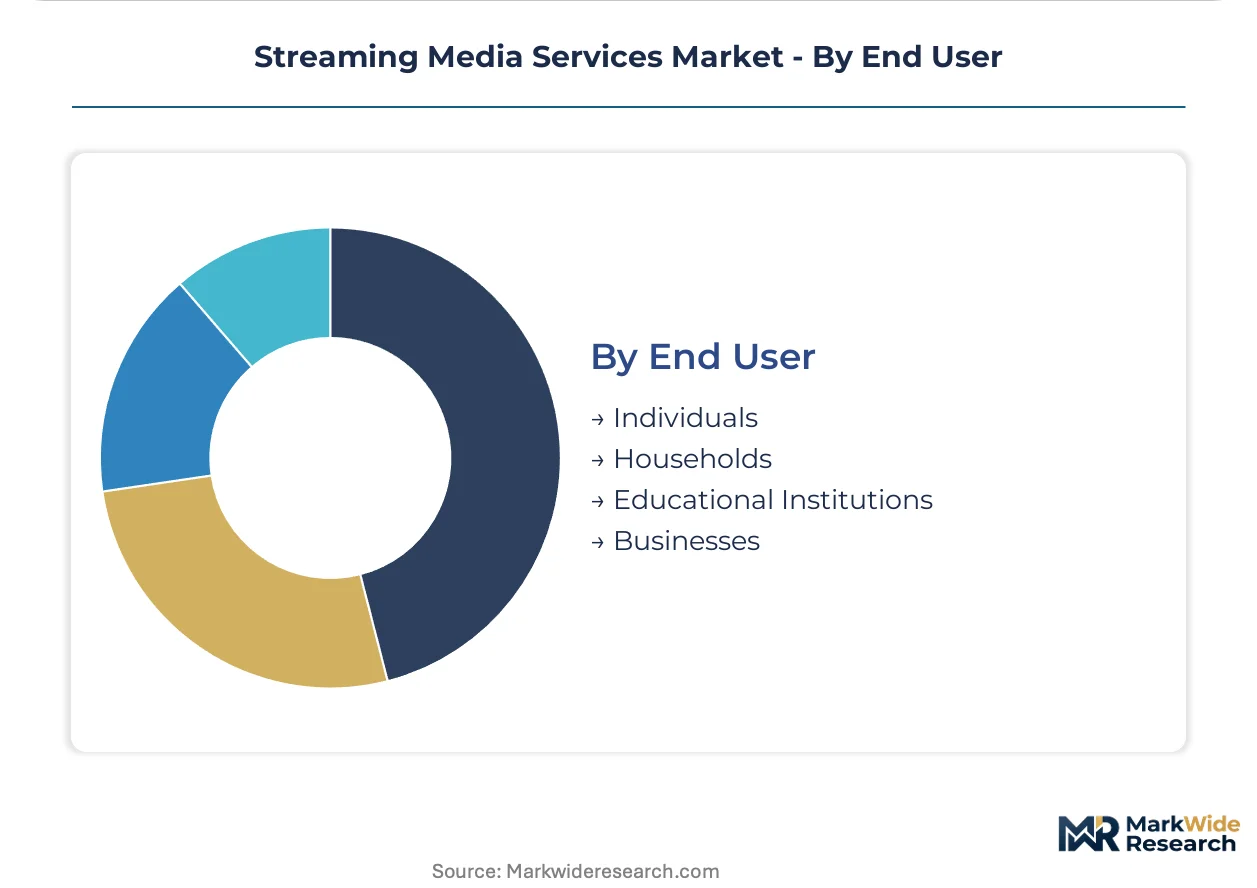
- Individuals:Single-user accounts with personalized recommendation profiles and individual payment credentials. Young adult demographics in urban United States markets drive discretionary entertainment spending.
- Households:Multi-profile family plans with parental controls and concurrent stream limits. Churn reduction tactics concentrate here through annual discounting.
- Educational Institutions:Campus-wide licensing for documentary and instructional content procurement. United States university library consortia negotiate collective access agreements.
- Businesses:Commercial display licensing for hospitality and retail ambient entertainment. European hospitality chains face GDPR compliance obligations for guest network streaming.
Revenue concentration sits with Households. Contract value is rising fastest in Businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The streaming media services industry traces its commercial origins to the United States, where broadband infrastructure and venture capital concentration enabled the first scaled subscription platforms in the early 2000s. This foundation established technical and business model templates that subsequently diffused across international markets.
United States
Household broadband penetration exceeds 90 percent, sustaining multiple simultaneous subscription memberships and driving bundle consolidation among major platforms. The FCC oversees net neutrality enforcement and infrastructure investment programs that directly affect streaming quality standards. Los Angeles and New York anchor original content production clusters, where studio facilities and post-production houses concentrate talent and capital deployment.
South Korea
5G network slicing enables seamless 4K mobile streaming, with smartphone consumption accounting for the majority of viewing hours among younger demographics. The Korea Communications Commission imposes content rating and platform accountability frameworks that shape catalog curation. Seoul's Gangnam district hosts headquarters operations for major telecom-affiliated streaming services and smart TV operating system developers.
India
Mobile-first video consumption accelerates across tier-2 and tier-3 cities as data costs decline and regional language content libraries expand. TRAI regulates net neutrality and interconnect charges that affect platform delivery economics. Mumbai's film industry infrastructure supports original programming production for Hindi and Marathi markets, while Bengaluru's technology corridor supplies engineering talent for platform development.
Germany
High household broadband penetration supports premium-tier subscriptions, though price sensitivity sustains demand for ad-supported alternatives. The EU Digital Services Act and GDPR impose algorithmic transparency and data handling obligations on platforms operating across German markets. Berlin's startup ecosystem hosts multiple niche streaming services targeting documentary and independent film segments.
Japan
Smart TV deployment concentrates viewing hours on large-format displays, with manufacturer-controlled operating systems determining default application visibility. METI oversees content distribution frameworks and cross-border data flow regulations. Tokyo's Shibuya and Roppongi districts cluster animation production studios whose content underpins platform differentiation strategies across Asian markets.
Streaming Media Services Market Competitive Environment
Premium-margin players sit above commodity-margin players across content exclusivity and technology integration dimensions. The market structure consolidates around entertainment conglomerates with deep intellectual property libraries, telecom operators with network infrastructure control, and technology platforms with data-driven personalization capabilities. Three archetypes dominate: original content producers, distribution-integrated bundlers, and device-ecosystem gatekeepers. Competitive moves concentrate on exclusive sports rights acquisition and smart TV operating system pre-installation agreements.
Within the entertainment conglomerate tier, Netflix and Disney+ exemplify original programming strategies that lock subscriber retention through exclusive franchise content. Amazon Prime Video occupies a position bridging e-commerce membership integration with standalone streaming distribution. Among technology-platform operators, Alphabet Inc. represents the advertising-optimized distribution model that reduces subscription friction through data-monetization alternatives.
| Leading Market Players |
|---|
| Max |
| Paramount+ |
| Netflix |
| Alphabet Inc. |
| Apple TV+ |
| Amazon Prime Video |
| Hulu |
| Roku |
| Disney+ |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration between content production and distribution infrastructure anchors pricing power for entertainment conglomerates while compressing margins for standalone services dependent on licensed programming. This structural positioning enables bundled offerings to extract premium subscriber commitments through exclusive catalog control, whereas ad-supported tiers compete on cost efficiency enabled by cloud delivery economics.
Pricing Analysis
Subscription tiering with ad-supported alternatives anchors revenue capture across the streaming media services market. Price differentiation rests on content exclusivity depth and concurrent stream allowances, with premium tiers commanding higher commitments for 4K fidelity and early theatrical access. Cost compression in ad-supported tiers is intensifying because programmatic advertising yields lag subscription revenue per user. Mobile-first viewers in India exhibit highest price sensitivity, while affluent households in Japan and South Korea sustain premium tier uptake.
Supply Chain Analysis
Content licensing agreements with territorial distribution restrictions gate supply chain participation for platform operators. Production gravity centers on the United States, South Korea, and Japan for original programming, with post-production services drawing from Canada and Australia. Cloud infrastructure and CDN delivery networks hinge on hyperscaler capacity in regional availability zones. Single-source vulnerability concentrates in exclusive sports broadcasting rights held by league-specific consortiums. Distribution runs through smart TV operating system pre-installation agreements and mobile carrier billing integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in streaming media services rests on ad-tier revenue optimization and cloud infrastructure cost discipline as platforms shift subscriber mix toward higher-yield segments.
For Market Incumbents: To counter churn acceleration from subscription rotation behavior, Disney+ and Netflix should deepen exclusive franchise content pipelines and lock annual commitments through discounted prepayment structures. Smart TV operating system pre-installation agreements represent critical defensive positioning against emerging platform distribution. For New Entrants and Emerging Players: Capture documentary and educational programming white space in Germany and niche sports verticals underserved by major bundles. Regional language original production in Indian tier-2 cities offers penetrable subscriber acquisition with lower content cost intensity than Hindi blockbuster competition. For Investors and Strategic Acquirers: Roll-up economics work for telecom-affiliated streaming services because network infrastructure control creates captive subscriber bases with lower acquisition costs. Mid-cap platforms with exclusive sports rights or smart TV OS licensing represent viable acquisition targets. Watch for inflection in FCC broadband infrastructure deployment pacing as signal for addressable market expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Ad-Supported Tier Expansion | Captures price-sensitive households through TRAI-regulated carrier billing in Indian mobile markets. |
| Exclusive Sports Rights Acquisition | Defends subscriber retention against bundle consolidation through NFL and Premier League carriage. |
| Smart TV OS Pre-Installation | Locks default application visibility via Samsung and LG licensing in South Korean manufacturing. |
| Original Content Localization | Enables same-day global premieres through generative AI dubbing pipelines in Canadian post-production. |
| Cloud Gaming Infrastructure Repurposing | Extends video CDN utilization into interactive entertainment for Japanese console platform convergence. |
Study Parameters
Direct dialogue with platform strategy executives, content acquisition leads, smart TV manufacturer licensing directors, and telecom streaming partnership managers grounded qualitative findings. Secondary validation drew from FCC broadband deployment reports, EU Digital Services Act implementation guidance, TRAI regulatory circulars, SEC 10-K filings from entertainment conglomerates, and hyperscaler capex disclosures. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from infrastructure capacity and content spend analysis.
Segment-level projections across service type, content category, device platform, and end-user archetype structured the analytical framework over the projection horizon. CAGRs derived from regression against broadband penetration curves, smartphone adoption patterns, and content production cost indices. Cloud infrastructure scaling economics and advertising yield optimization served as industry-specific forecast inputs alongside regulatory compliance cost trajectories.
Regulatory enforcement timing, sports rights auction outcomes, and smart TV OS market share shifts are the dominant revision risks to modeled trajectories. Forecasts reflect assumptions on subscriber lifetime value stability and advertising market depth. A model refresh is warranted upon material change in FCC infrastructure subsidy allocation or EU algorithmic transparency audit implementation pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Online Streaming Service Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Media Streaming Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Streaming Services Market
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market
Video Streaming (OTT) Services
India Smart TV and OTT Market