
 Latin America OTT Platform Market | 2026-2036
Latin America OTT Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America OTT Platform Market Intelligence
Standalone subscription unbundling is decoupling premium content from legacy pay-TV bundles across Latin America. Netflix leverages original Portuguese and Spanish-language production to sustain subscriber retention in São Paulo and Mexico City. Disney anchors family-oriented content libraries that dominate parental purchasing decisions regionally. GloboPlay controls Brazil's domestic sports and telenovela rights, positioning its platform as a must-have in Latin America's largest media market.
Latin America OTT platforms deliver audiovisual content via internet protocol-based streaming infrastructure with adaptive bitrate encoding that adjusts video quality to bandwidth conditions between 0.5 Mbps and 25 Mbps. These systems serve commercial entertainment distribution, replacing satellite and cable transmission with direct-to-consumer digital delivery. SVOD subscription models generate the deepest revenue pools as consumers prioritize ad-free viewing experiences across smartphone and smart TV device categories. AVOD segments capture price-sensitive audiences where advertising loads partially offset subscription costs. Smart TV device penetration concentrates platform reach in middle-income households where large-screen viewing remains preferred for serialized drama and live sports content.
Brazil's ANATEL enforces net neutrality provisions that prevent broadband providers from throttling OTT traffic, preserving platform access equality. Mexico's IFT regulates must-carry obligations and cross-media ownership limits that shape content licensing negotiations. Argentina's ENACOM oversees broadcast digitization timelines that accelerate smart TV replacement cycles. Stakeholders must monitor how each national regulator adapts audiovisual competition rules as streaming platforms displace traditional broadcasters in advertising revenue and audience attention.
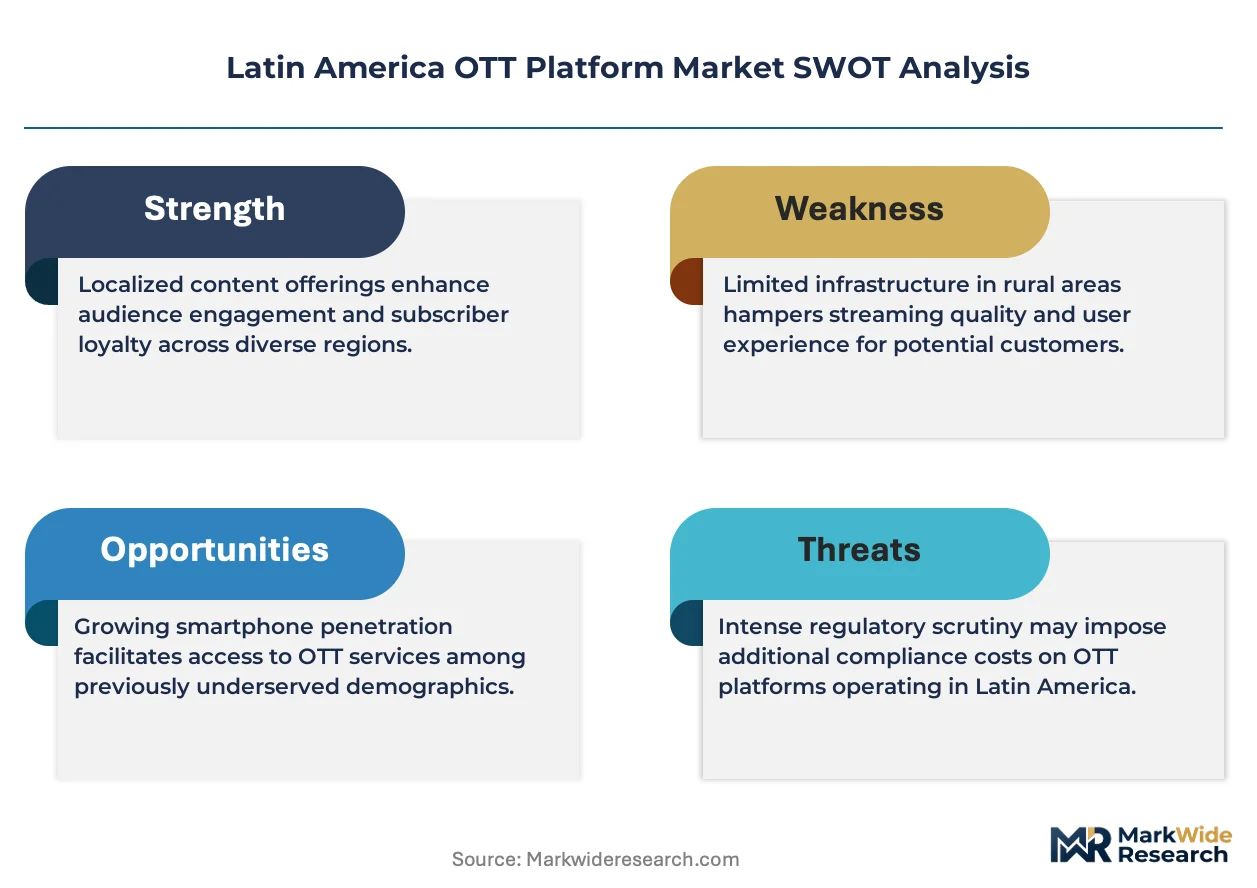
Market Dynamics
Smart TV penetration in middle-income Latin American households is compressing the window between theatrical release and streaming premiere, forcing platforms to renegotiate windowing agreements with cinema distributors across São Paulo, Mexico City, and Buenos Aires.
Growth Catalysts
- ANATEL net neutrality enforcement:Brazil's telecom regulator prevents broadband throttling of OTT traffic, preserving platform access equality and preventing ISP discrimination against streaming services.
- Smartphone-first consumption clusters:Urban centers in Colombia and Argentina concentrate mobile video demand, driving platform investment in adaptive bitrate encoding for 0.5-5 Mbps connections.
- Original Portuguese and Spanish production:Local-language content creation sustains subscriber retention in São Paulo and Mexico City where dubbed foreign content underperforms.
Market Restraints
- Cross-border licensing fragmentation:Mexico's IFT must-carry obligations and ownership limits create friction in pan-regional content negotiations, forcing platforms to maintain separate catalog structures per country.
- Input cost volatility in CDN infrastructure:Energy and data center costs in Argentina fluctuate with peso instability, compressing margins for platforms serving Buenos Aires metropolitan subscribers.
- Legacy pay-TV bundle stickiness:Satellite and cable operators in Brazil retain sports rights exclusivity, blocking OTT access to live football matches that drive subscription decisions.
Strategic Opportunities
- Underpenetrated Andean corridor:Peru, Chile, and Ecuador present whitespace for AVOD models where price-sensitive audiences reject SVOD premiums but accept advertising loads.
- ENACOM broadcast digitization timelines:Argentina's regulator mandates smart TV replacement cycles, accelerating device turnover that favors app-based platform distribution over terrestrial.
- Live sports streaming unbundling:Regional football league rights in Brazil and Mexico approach renewal windows where OTT platforms can outbid traditional broadcasters.
Industry Challenges
- Localization talent scarcity:Subtitle and dubbing studio capacity in Portuguese and Spanish constrains release velocity for platforms expanding catalog depth.
- Payment infrastructure heterogeneity:Cash-based economies and underbanked populations in Colombia and Peru require platform investment in carrier billing and prepaid voucher systems.
- Piracy platform competition:Unlicensed streaming sites offering Brazilian telenovela and Mexican football content capture price-sensitive audiences before legal conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America OTT Platform Market |
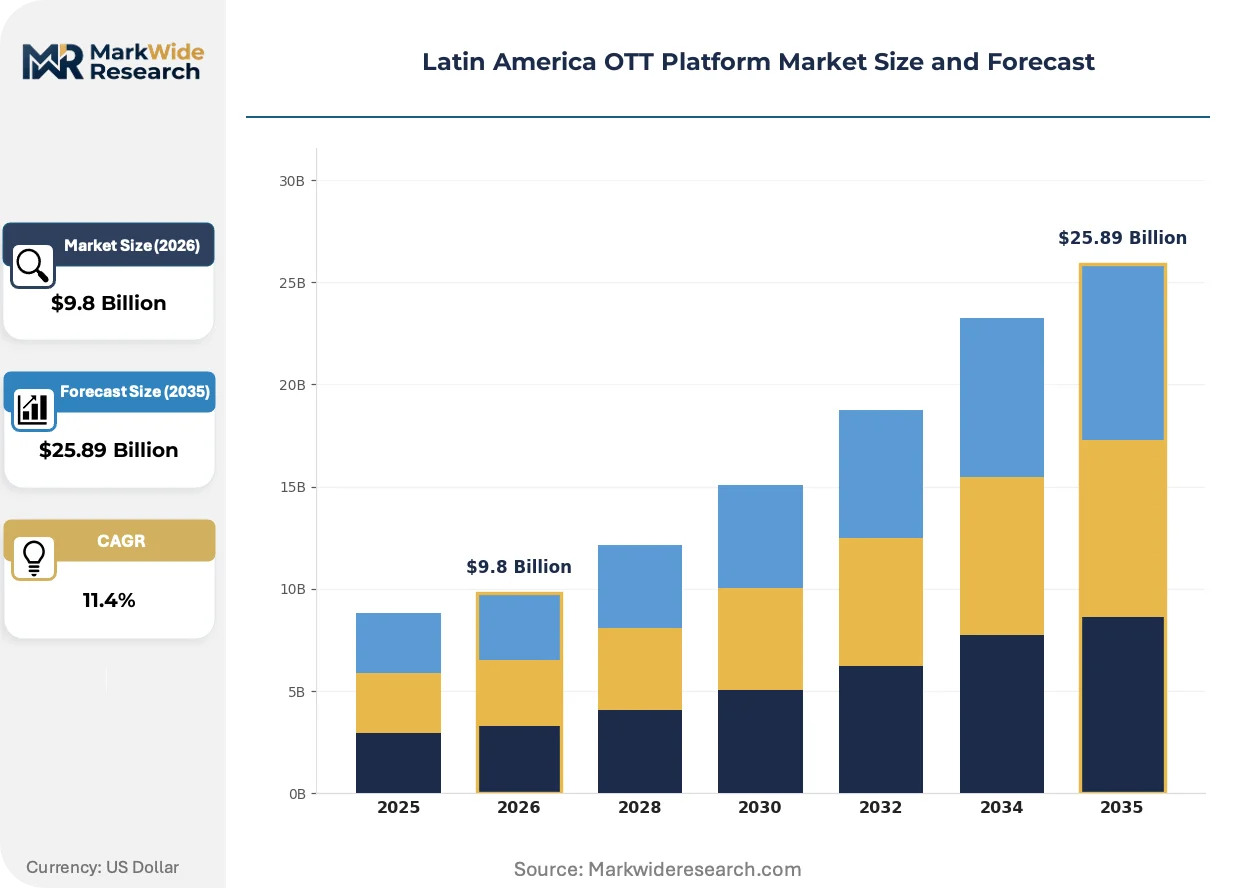
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Video Streaming, Music Streaming, Live Events, Educational Content Subscription Model: SVOD, AVOD, TVOD, Freemium Device Type: Smart TVs, Smartphones, Tablets, Set-top Boxes Target Audience: Families, Young Adults, Children, Professionals |
| Companies Covered | Warner Media, Claro Video, Netflix, Movistar Play, ViX (TelevisaUnivision), Disney, GloboPlay, Apple TV+, Amazon Prime Video, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America OTT Platform Market Strategic Shifts & Innovations
Streaming infrastructure in Latin America is pivoting from satellite backup to pure IP delivery, compressing distribution costs while forcing platforms to build proprietary encoding stacks for variable bandwidth conditions.
Adaptive bitrate streaming technology adjusts video quality dynamically to connection speeds between 0.5 Mbps and 25 Mbps. Brazilian and Mexican platforms deploy this most aggressively for mobile-first subscribers. The technology is converging with edge caching nodes in São Paulo and Mexico City, reducing latency for live sports broadcasts.
Brazil's Marco Civil da Internet establishes intermediary liability frameworks that shield platforms from content-related lawsuits while mandating data retention for law enforcement. This regulatory architecture influences how platforms structure local entity presence and content moderation staffing. Family-oriented services face heightened scrutiny under these provisions.
Subscription fatigue among middle-income households is fragmenting wallet share across multiple platforms. Brazilian consumers increasingly rotate monthly between GloboPlay, Netflix, and Disney based on content release calendars rather than maintaining simultaneous subscriptions. This behavior compresses average revenue per user and forces platforms into promotional pricing cycles in São Paulo and Rio de Janeiro metropolitan zones.
Latin America OTT Platform Market Segmentation
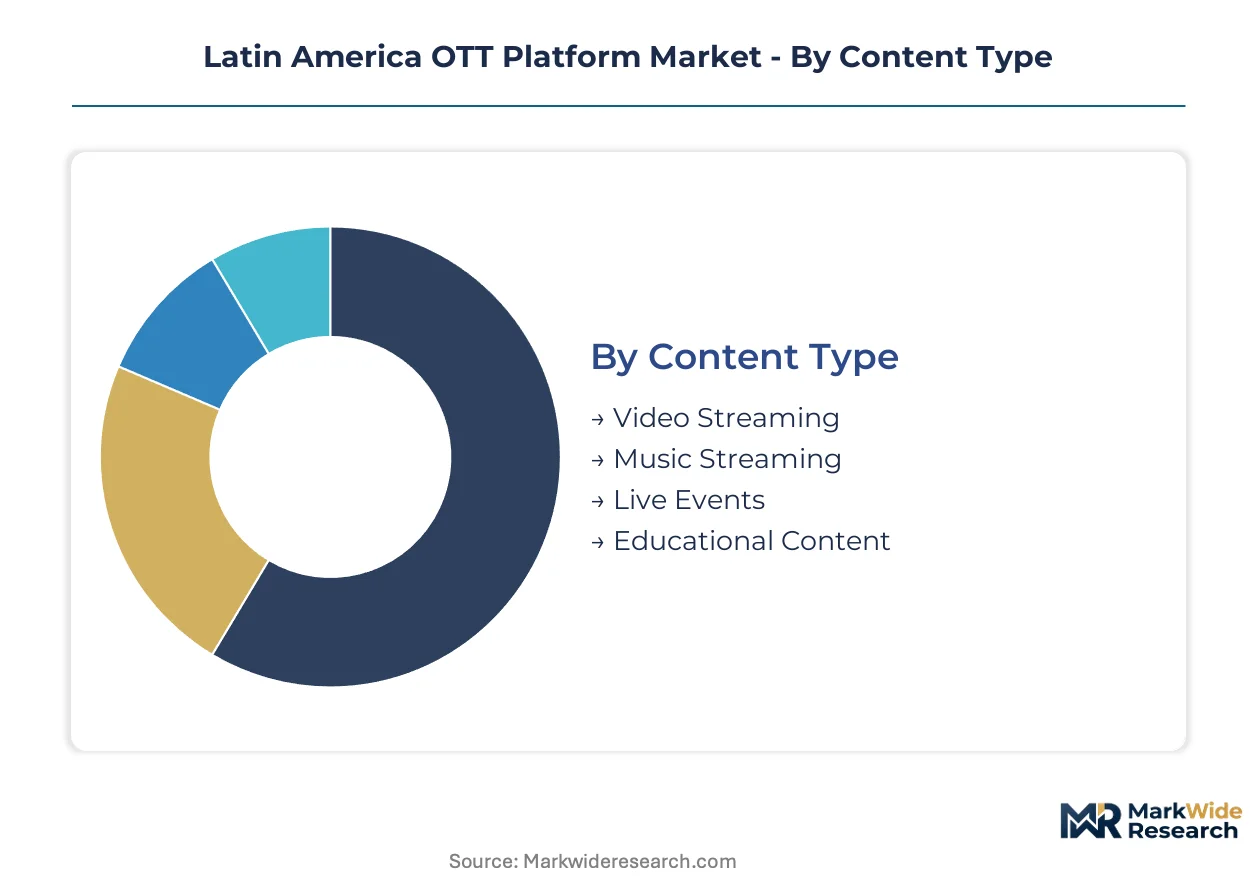
Segmentation in the Latin America OTT Platform Market reveals how platform economics diverge across content formats, payment tolerance, and device ecosystems. Each dimension exposes distinct margin structures and subscriber acquisition costs that shape competitive positioning.
Content Type:
Volume-driven entertainment commands the largest subscriber bases, while premium live content extracts higher per-user revenue.
- Video Streaming:Serialized drama and film libraries dominate consumption hours across São Paulo and Mexico City. Brazilian telenovela catalogs on GloboPlay and Netflix's Portuguese originals sustain retention in middle-income households where large-screen viewing remains preferred.
- Music Streaming:Audio platforms operate on lower per-subscriber margins with higher churn tolerance. Spotify and regional competitors concentrate subscriber growth in urban Argentina and Colombia where smartphone-first consumption clusters.
- Live Events:Concert and festival streaming captures ephemeral demand spikes. Deployment concentrates around major cultural calendars in Brazil and Mexico.
- Educational Content:Corporate training and language instruction serve B2B contracts. Uptake accelerates in professional segments across Santiago and Buenos Aires.
Mature deployment sits with Video Streaming. Newer deployment is concentrated in Educational Content.
Subscription Model:
Revenue predictability versus audience scale defines the trade-off between locked-in payments and advertising-supported reach.
- SVOD:Subscription video-on-demand generates the deepest revenue pools. Brazilian and Mexican consumers prioritize ad-free viewing for serialized content, driving platform investment in exclusive originals.
- AVOD:Advertising-supported models capture price-sensitive audiences. Peru, Chile, and Ecuador present whitespace where viewers reject SVOD premiums but accept advertising loads.
- TVOD:Transactional video-on-demand serves theatrical windowing. Compression between cinema release and streaming premiere forces renegotiation with distributors.
- Freemium:Tiered access converts sampling to paid tiers. Music platforms deploy this most aggressively in underbanked Colombian and Peruvian markets.
Established revenue concentration favors SVOD. AVOD is expanding most quickly as platforms target lower-income demographics.
Device Type:
Screen size and connectivity infrastructure determine encoding investments and content format optimization.
- Smart TVs:Large-screen devices concentrate platform reach in Brazilian middle-income households. Argentina's ENACOM broadcast digitization timelines accelerate smart TV replacement cycles favoring app-based distribution.
- Smartphones:Mobile-first consumption dominates Colombian and Argentine urban centers. Adaptive bitrate encoding for 0.5-5 Mbps connections receives priority engineering resources.
- Tablets:Secondary screens serve portable viewing in transit corridors. Demand clusters in Mexico City and São Paulo metropolitan transit zones.
- Set-top Boxes:Legacy hardware bridges satellite-to-IP transition. Brazilian pay-TV bundle stickiness sustains this segment temporarily.
Smart TV deployment leads in revenue per user. Smartphone deployment is gaining share fastest as mobile infrastructure improves.
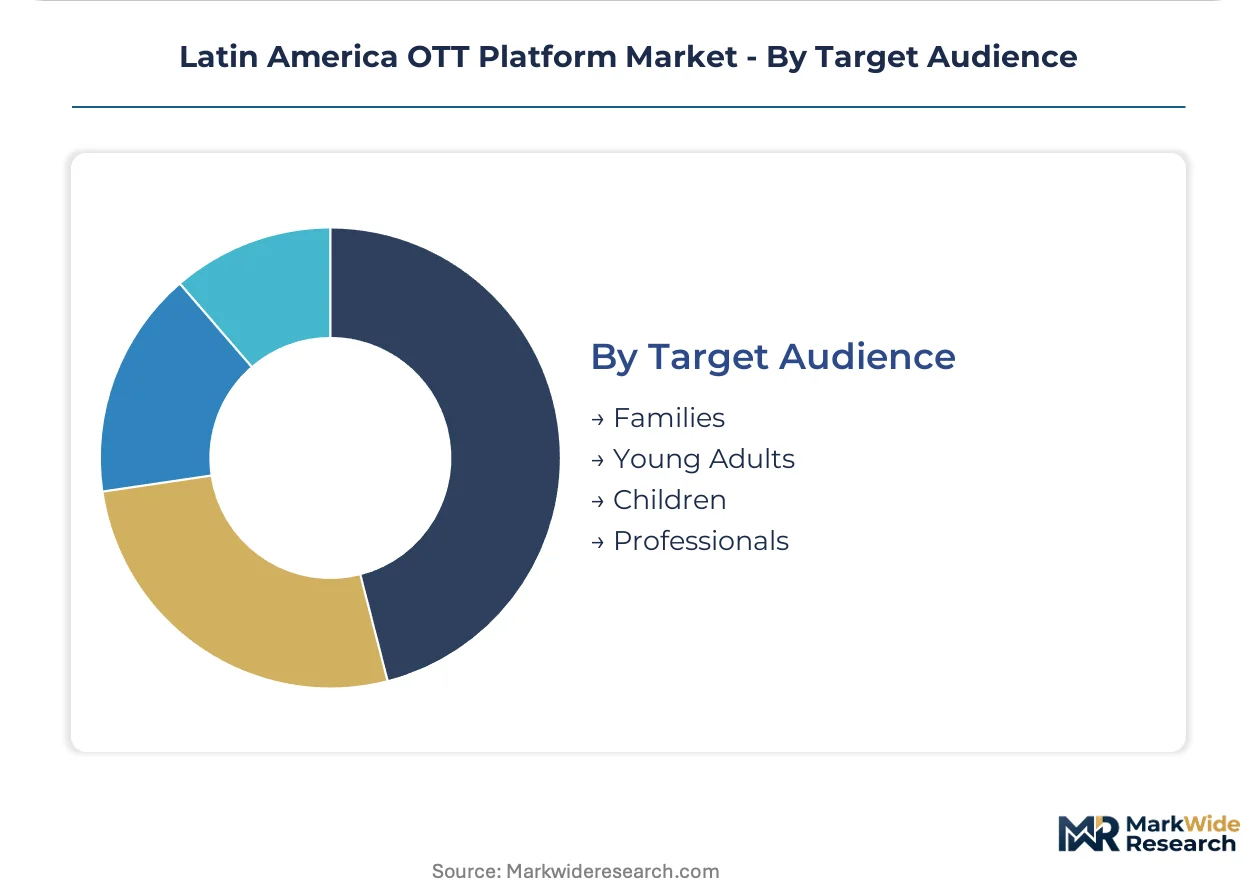
Target Audience:
Household composition and life stage drive content licensing priorities and parental control feature investment.
- Families:Disney and similar platforms anchor purchasing decisions through children's content libraries. Parental subscription retention depends on multi-profile functionality and content ratings compliance.
- Young Adults:Genre diversity and social viewing features sustain engagement. Brazilian and Mexican originals in horror, comedy, and documentary formats perform strongest here.
- Children:Dedicated interfaces and educational content requirements trigger regulatory scrutiny under Brazil's Marco Civil da Internet intermediary liability frameworks.
- Professionals:Time-shifted news and business content serves fragmented viewing windows. Concentrated demand in Santiago, Buenos Aires, and São Paulo financial districts.
Family segment deployment shows highest retention rates. Young Adult deployment is climbing the fastest as platform original production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Content production concentrates in São Paulo and Mexico City while consumption spreads across secondary urban centers. Brazil and Mexico generate the deepest subscriber revenue pools. Argentina, Colombia, and Chile present expansion corridors where infrastructure investment outpaces platform saturation.
Brazil
ANATEL enforces net neutrality provisions that preserve OTT platform access equality against ISP throttling. São Paulo anchors original Portuguese-language production studios that supply Netflix and GloboPlay with serialized drama. Smart TV penetration in middle-income households compresses theatrical-to-streaming windows.
Mexico
IFT must-carry obligations and cross-media ownership limits reshape content licensing negotiations for Disney and ViX. Mexico City concentrates dubbing studio capacity that constrains release velocity for regional catalog expansion. Mobile-first consumption clusters drive adaptive bitrate engineering for 0.5-5 Mbps connections.
Argentina
ENACOM broadcast digitization timelines accelerate smart TV replacement cycles favoring app-based distribution. Buenos Aires metropolitan subscribers face CDN margin pressure from peso-linked energy cost volatility. Professional segments in financial districts sustain demand for time-shifted news and business content.
Colombia
Underbanked populations in Bogotá and Medellín require carrier billing and prepaid voucher systems for platform access. Urban smartphone-first consumption clusters concentrate video demand in transit corridors. AVOD models capture price-sensitive audiences who reject SVOD premiums.
Chile
Santiago's professional segments drive corporate training and educational content contracts for B2B platform tiers. Payment infrastructure heterogeneity persists despite higher banking penetration than Andean neighbors. Whitespace remains for advertising-supported models in lower-income demographics.
Latin America OTT Platform Market Key Industry Players
The competitive structure tilts toward global streaming platforms with localized production arms. Market concentration splits between US-based subscription giants and domestic broadcasters with sports and telenovela exclusivity. Two archetypes dominate: global SVOD operators with original language production capabilities, and national media conglomerates controlling live sports rights. Competitive moves center on exclusive content licensing and mobile-first encoding infrastructure deployment.
Among US-based streaming operators, Netflix, Disney, and Amazon Prime Video exemplify the global platform archetype with Portuguese and Spanish original production commitments. Domestic incumbents GloboPlay and ViX occupy positions anchored to exclusive sports and telenovela rights in Brazil and Mexico respectively. Warner Media and Apple TV+ represent secondary global entrants competing through premium content positioning rather than volume-driven local production.
| Leading Market Players |
|---|
| Warner Media |
| Claro Video |
| Netflix |
| Movistar Play |
| ViX (TelevisaUnivision) |
| Disney |
| GloboPlay |
| Apple TV+ |
| Amazon Prime Video |
| Others |
Cost & Logistics Intelligence
Adaptive bitrate encoding migration from satellite backup to pure IP delivery simultaneously compresses distribution economics and concentrates supply chain leverage among hyperscale CDN operators. Brazil's ANATEL net neutrality enforcement prevents broadband throttling, preserving platform access equality while locking in infrastructure cost structures that favor established players with proprietary encoding stacks.
Pricing Analysis
Margin tightening in SVOD tiers reflects subscription fatigue among Brazilian middle-income households rotating monthly between platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by content exclusivity and simultaneous stream count, with AVOD models capturing price-sensitive Andean audiences who reject subscription premiums. Cost-down pressure on CDN infrastructure accelerates because Argentina's peso-linked energy volatility compresses margins for Buenos Aires metropolitan delivery. Young adult segments show lowest price sensitivity for original Portuguese and Spanish content, while underbanked Colombian populations demand carrier billing flexibility.
Supply Chain Analysis
CDN infrastructure supply rests on hyperscale operators concentrated in São Paulo, Mexico City, and Miami edge nodes serving Latin American latency requirements. Proprietary encoding hardware, adaptive bitrate software licenses, and smart TV chipset manufacturing feed from East Asian semiconductor foundries and US-based cloud computing platforms. Single-source vulnerability concentrates in Brazil's GloboPlay exclusive telenovela and sports rights holdings. Distribution runs through direct-to-consumer app stores, smart TV native platforms, and mobile carrier bundled partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's Marco Civil da Internet establishes intermediary liability frameworks that create compliance moats shielding platforms from content-related litigation while mandating data retention infrastructure investments that deter undercapitalized entrants.
For Market Incumbents: Deploy exclusive sports rights acquisition as the primary defensive lever. Secure renewal windows for Brazilian football league and Mexican Liga MX streaming rights before traditional broadcasters adapt. Lock in dubbing studio capacity in São Paulo and Mexico City to constrain release velocity for emerging competitors. Counter piracy platform competition through prepaid voucher distribution networks reaching underbanked Colombian and Peruvian populations. For New Entrants and Emerging Players: Begin with AVOD deployment in Peru, Chile, and Ecuador where price-sensitive audiences reject SVOD premiums but accept advertising loads. Target smartphone-first consumption clusters in Bogotá and Medellín transit corridors with adaptive bitrate optimization for 0.5-5 Mbps connections. Pursue carrier billing integration as the go-to-market angle for cash-based economies requiring alternative payment rails. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation among domestic broadcasters with exclusive sports and telenovela rights. Long-term viability hinges on original Portuguese and Spanish production scale sustaining subscriber retention against global platform originals. Acquisition target archetype: regional AVOD platforms with established advertising sales infrastructure in underpenetrated Andean markets. Watch ENACOM broadcast digitization timelines as the signal indicating smart TV replacement acceleration favoring app-based distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Original Language Production Scale-Up | Portuguese and Spanish originals sustain retention in São Paulo and Mexico City where dubbed content underperforms. |
| Live Sports Rights Acquisition | Brazilian football and Mexican Liga MX exclusivity blocks OTT access to subscription-driving matches. |
| Mobile-First Encoding Investment | Adaptive bitrate technology for 0.5-5 Mbps connections captures Colombian and Argentine urban smartphone clusters. |
| Carrier Billing Infrastructure | Prepaid voucher systems unlock underbanked populations in Colombia and Peru rejecting credit-card subscriptions. |
| Smart TV Native App Distribution | Argentina's ENACOM digitization timelines accelerate device turnover favoring app-based platform reach. |
Research Approach
SEC filings, ANATEL regulatory disclosures, and IFT licensing records formed the secondary backbone for market sizing validation. Primary interviews with platform engineering directors, content licensing executives, and carrier billing specialists at mobile network operators supplied operational data on encoding infrastructure and payment system deployment. Bottom-up and top-down triangulation reconciled subscriber counts by country with revenue recognition patterns across SVOD, AVOD, and TVOD model splits.
Bottom-up modeling aggregated country-level subscriber projections across Brazil, Mexico, Argentina, Colombia, and Chile before cross-referencing against top-down addressable market estimates. Segmentation dimensions spanned content type, subscription model, device category, and target audience demographics throughout the forecast period. CAGRs derived from historical growth trajectories adjusted for smart TV penetration curves and mobile infrastructure investment timelines. Forecast inputs incorporated ENACOM broadcast digitization mandates and ANATEL net neutrality enforcement stability assumptions.
Underlying measurement precision varies by segment; SVOD subscriber counts carry tighter precision than AVOD audience estimates where advertising load and viewability metrics introduce uncertainty. Forecasts reflect documented assumptions regarding regulatory continuity and sports rights renewal competitive dynamics. Piracy platform competition and peso-linked CDN cost volatility warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Video Servers Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
United States Online Video Platform Market