
 Video Servers Market | 2026-2036
Video Servers Market Size, Share, and Industry Trends Forecast 2026-2036
Video Servers Market Analysis
The capital-intensity divergence between custom ASIC-based platforms and commodity x86 architectures is redrawing competitive boundaries in video server infrastructure. Cisco Systems, Inc. leverages its networking heritage to integrate switching silicon with media processing blades. Huawei Technologies Co., Ltd. sustains vertical integration from chip design to system software, compressing cost structures for telecom operators. Dell Technologies Inc. competes through modular server architectures that accommodate GPU acceleration cards for transcoding workloads.
Video servers are specialized computing platforms engineered for ingest, storage, transcoding, and distribution of compressed video streams, typically supporting H.264, HEVC, or AV1 codecs with throughput measured in concurrent gigabits per second. These systems serve television broadcasters, over-the-top platforms, and enterprise communication networks requiring deterministic latency for live content delivery. Streaming servers command the largest revenue pool as direct-to-consumer platforms expand capacity, while edge computing deployments represent the fastest structural expansion as content delivery networks push processing closer to viewers. Storage servers retain stable demand from archive and replay applications, though margin compression from cloud object storage alternatives constrains pricing power.
The Federal Communications Commission in the United States mandates closed-captioning and emergency alert interoperability for broadcast video infrastructure, forcing server vendors to maintain legacy protocol support alongside IP-native stacks. The European Union's Cybersecurity Act and GDPR frameworks impose data residency and encryption standards on cloud-based video processing, elevating compliance costs for cross-border content distribution. Stakeholders must evaluate whether to anchor R&D in sovereign cloud certifications or pursue portable architectures that satisfy multiple jurisdictional requirements without hardware fragmentation.
Market Dynamics
The migration from on-premise broadcast infrastructure to cloud-native streaming architectures is compressing hardware refresh cycles while expanding software-defined video processing capacity across content delivery networks.
Growth Catalysts
- Live streaming bandwidth expansion:OTT platforms and sports broadcasters are provisioning edge nodes closer to metropolitan viewers to reduce latency for real-time events.
- AV1 codec mandate pressure:The Alliance for Open Media's royalty-free standard is gaining traction among ad-supported streaming services seeking to reduce CDN egress costs.
- EU Cybersecurity Act certification:Cloud video processing providers are pursuing sovereign cloud credentials to serve public sector broadcasters under GDPR data residency requirements.
Market Restraints
- GPU supply concentration:Transcoding acceleration depends on NVIDIA and AMD silicon, creating procurement bottlenecks for high-density encoding farms.
- Legacy SDI protocol persistence:Broadcast facilities retain hybrid infrastructure, forcing vendors to maintain expensive dual-stack development for SMPTE 2110 and baseband coexistence.
- Cloud object storage substitution:Amazon S3, Google Cloud Storage, and Azure Blob are eroding margins for dedicated video storage server hardware in archive applications.
Strategic Opportunities
- India's rural broadband buildout:The BharatNet project is extending fiber connectivity to tier-3 cities, creating demand for localized edge caching infrastructure.
- AI-generated content pipelines:Synthetic media workflows require new ingest and rendering server configurations that traditional broadcast hardware cannot accommodate.
- Japan's 8K broadcast mandate:NHK's Super Hi-Vision roadmap is driving replacement demand for 120fps-capable encoding platforms in production facilities.
Industry Challenges
- Real-time systems engineering talent scarcity:Expertise in kernel-level video pipeline optimization and FPGA programming commands premium compensation, constraining vendor R&D scaling.
- Multi-cloud orchestration complexity:Broadcasters deploying hybrid architectures face integration friction between on-premise hardware and AWS, Azure, and Google Cloud transcoding APIs.
- SMPTE ST 2110 interoperability certification:The Professional Media over IP standard's fragmented implementation across vendors delays deployment timelines for IP-native facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Servers Market |
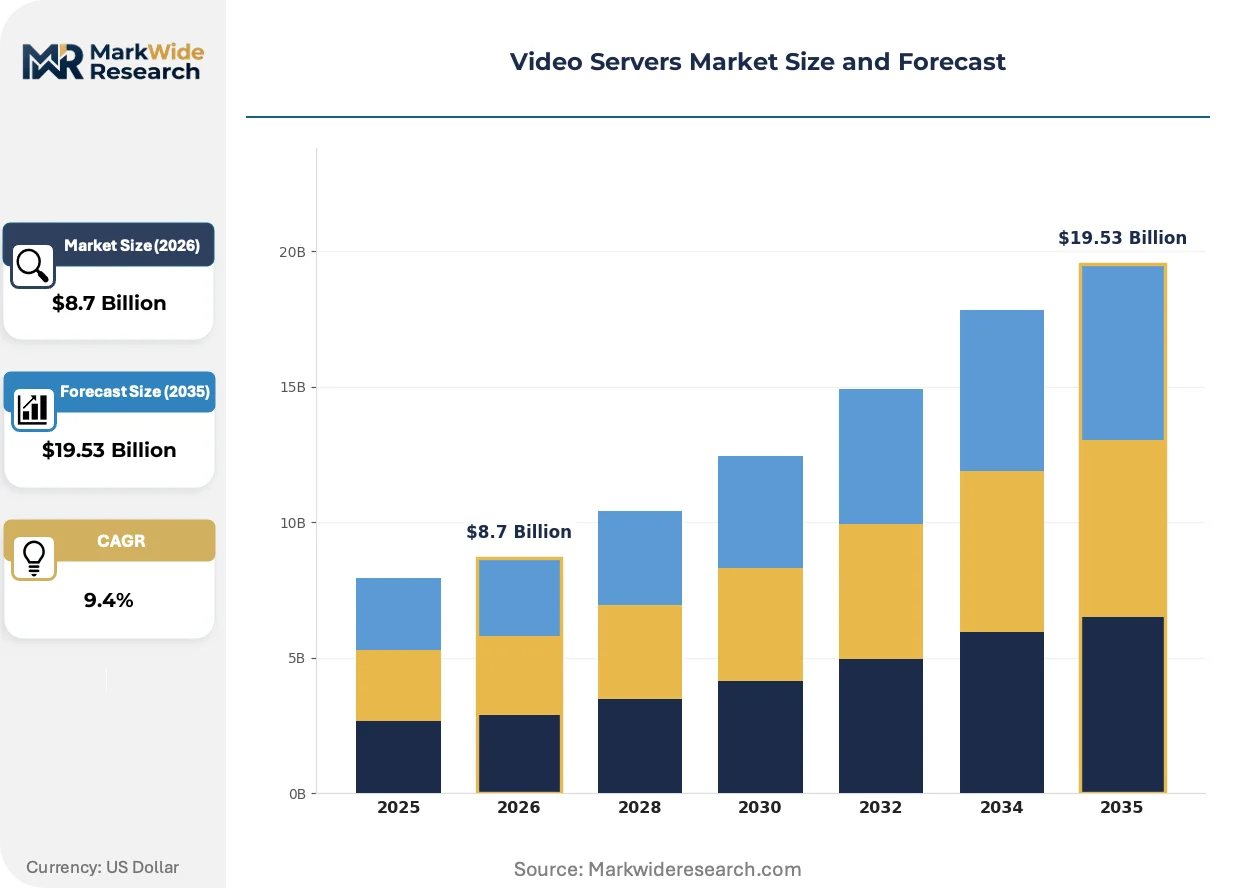
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Servers, Storage Servers, Load Balancers, Media Gateways Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Television Broadcasters, Content Providers, Enterprises, Educational Institutions Application: Live Streaming, Video Conferencing, Video Surveillance, Digital Signage |
| Companies Covered | Cisco Systems, Inc., Hewlett Packard Enterprise Development LP, Huawei Technologies Co., Ltd., Dell Technologies Inc., SeaChange International, Inc., VITEC, Imagine Communications Corp., Evertz Microsystems Ltd., Telestream, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Servers Market Emerging Trajectories
Software-defined video processing is decoupling media functions from dedicated hardware, enabling elastic capacity scaling that aligns infrastructure costs with actual viewership patterns rather than peak provisioning.
ARM-based server processors with dedicated media acceleration blocks are supplanting x86 architectures in power-constrained edge deployments. CDNs operating metropolitan caching nodes are adopting Ampere Altra and AWS Graviton3 instances for H.264 and HEVC transcoding. The shift is compressing energy costs per stream while reducing dependence on discrete GPU cards for mid-density workloads.
The Federal Communications Commission's updated closed-captioning requirements for internet-delivered video are forcing IP-native platforms to embed legacy 608/708 caption data streams. Streaming services must retrofit software pipelines to maintain compliance with rules originally designed for terrestrial broadcast. Vendors serving the US market are bifurcating product roadmaps to satisfy divergent regulatory baselines across jurisdictions.
Consumption of short-form vertical video is fragmenting encoding profiles away from traditional 16:9 broadcast standards. Social media platforms and news organizations are commissioning server configurations optimized for 9:16 aspect ratios at variable bitrates. This behavioral pivot is most visible in mobile-first markets where TikTok, Instagram Reels, and YouTube Shorts dominate viewing time.
Video Servers Market Segmentation
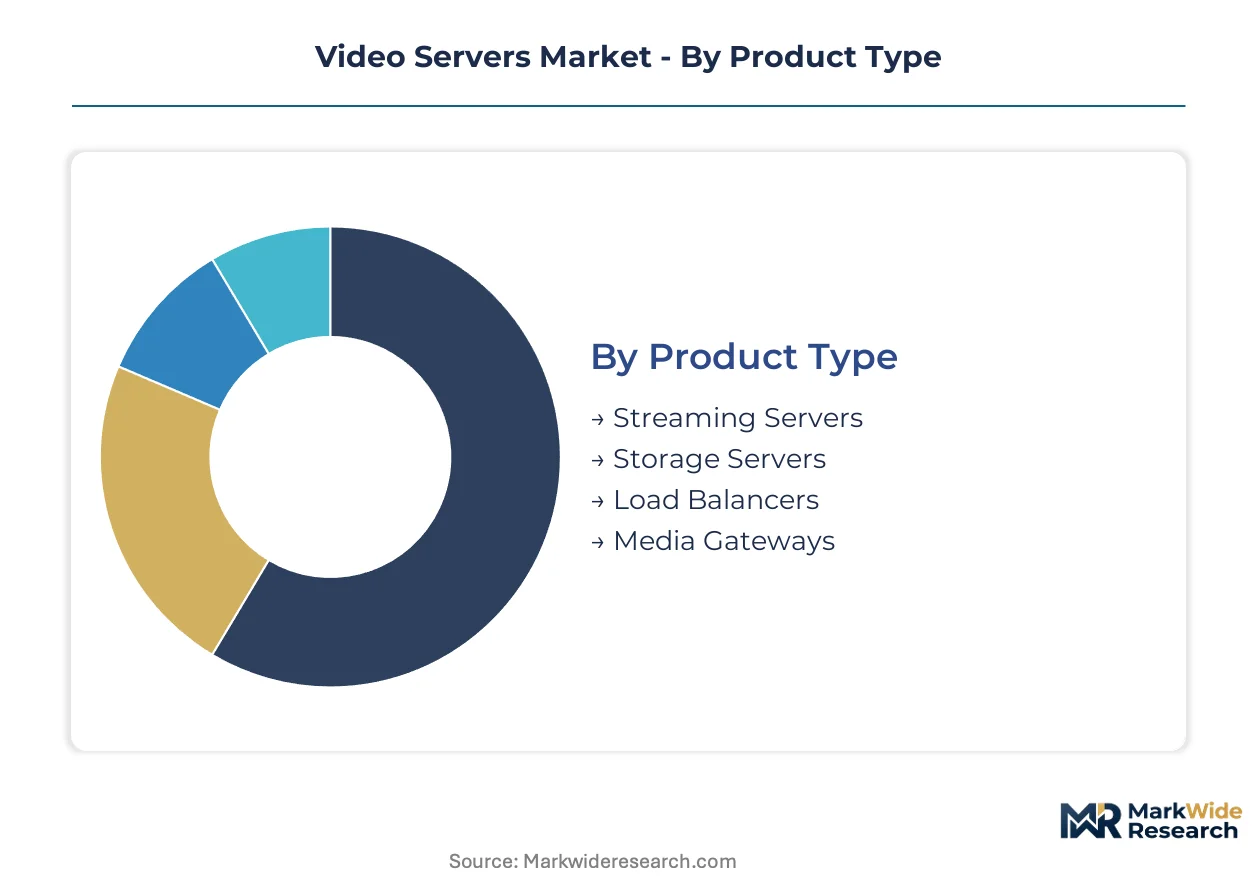
Video server procurement patterns diverge sharply across deployment contexts, with broadcast infrastructure subject to FCC emergency alert mandates while cloud-native streaming platforms navigate GDPR data residency frameworks. Understanding these segment boundaries clarifies where vendors must maintain dual-stack protocol support versus pure IP-native architectures.
Product Type:
FCC closed-captioning mandates for internet-delivered video force streaming server vendors to embed legacy 608/708 caption streams, while GDPR encryption standards shape storage server configurations for EU broadcasters.
- Streaming Servers:These platforms manage real-time ingest, transcoding, and distribution of H.264, HEVC, and AV1 compressed streams at throughput measured in concurrent gigabits per second. Demand concentrates among over-the-top platforms and sports broadcasters provisioning edge nodes closer to metropolitan viewers to reduce latency for real-time events, though GPU supply concentration from NVIDIA and AMD creates procurement bottlenecks for high-density encoding farms.
- Storage Servers:Systems engineered for video archive, replay, and content library management with deterministic access patterns for broadcast workflows. Broadcast facilities in the United States and Germany retain stable demand for on-premise storage despite cloud object storage substitution from Amazon S3, Google Cloud Storage, and Azure Blob eroding hardware margins in long-tail archive applications.
- Load Balancers:Traffic distribution appliances optimizing server utilization across distributed video processing clusters.
- Media Gateways:Protocol translation systems bridging SMPTE 2110 IP streams with legacy SDI baseband infrastructure.
Streaming servers handle the majority of throughput; edge-optimized media gateways are climbing the fastest on share as hybrid facilities accelerate IP migration.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premise installations from operational expenditure models dominating streaming platform procurement.
- On-Premises:Dedicated hardware installations in broadcast facilities and enterprise data centers requiring full control over latency and security parameters. Japanese broadcasters under NHK's Super Hi-Vision mandate drive replacement demand for 120fps-capable on-premise encoding platforms.
- Cloud-Based:Elastic compute resources for transcoding and distribution with usage-aligned pricing. India's rural broadband buildout through the BharatNet project creates demand for localized edge caching infrastructure that cloud providers are positioning to serve.
- Hybrid:Architectures combining on-premise hardware with burst capacity to AWS, Azure, and Google Cloud transcoding APIs. Broadcasters deploying these configurations face integration friction between legacy SDI protocol stacks and IP-native cloud services.
- Edge Computing:Distributed processing nodes positioned within metropolitan networks to minimize last-mile latency. ARM-based processors with dedicated media acceleration blocks from Ampere and AWS Graviton3 are supplanting x86 architectures in these power-constrained deployments.
Cloud-based deployments absorb the largest share of new capacity investment; edge computing nodes are expanding most quickly as content delivery networks push processing closer to viewers.
End User:
Customer type determines codec complexity requirements and regulatory compliance burden, from emergency alert interoperability for broadcasters to data residency for institutional users.
- Television Broadcasters:Traditional terrestrial, cable, and satellite operators maintaining hybrid SDI-IP infrastructure with deterministic latency requirements. The FCC mandates closed-captioning and emergency alert interoperability that forces these users to retain legacy protocol support alongside IP-native stacks.
- Content Providers:Over-the-top streaming platforms and direct-to-consumer video services. AV1 codec mandate pressure from the Alliance for Open Media drives these users toward royalty-free encoding standards to reduce CDN egress costs.
- Enterprises:Corporate communication networks and internal video distribution systems.
- Educational Institutions:Universities and K-12 systems deploying lecture capture and remote learning infrastructure.
Content providers command the largest revenue pool; educational institutions are gaining share fastest as hybrid learning models institutionalize video infrastructure spending.
Application:
Volume concentration varies by latency sensitivity, with real-time applications commanding premium hardware configurations versus asynchronous workloads tolerating commodity cloud resources.
- Live Streaming:Real-time event distribution requiring sub-second latency for sports, news, and interactive broadcasts. EU Cybersecurity Act certification requirements shape procurement for public sector broadcasters under GDPR data residency mandates.
- Video Conferencing:Enterprise communication platforms with variable bitrate adaptation for heterogeneous network conditions.
- Video Surveillance:Security and monitoring applications with continuous recording and analytics integration.
- Digital Signage:Out-of-home display networks with scheduled content distribution and remote management requirements.
Live streaming handles the majority of throughput; AI-generated content pipelines are reshaping video conferencing applications with synthetic media workflows that traditional broadcast hardware cannot accommodate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in video server equipment tilt toward net-import positions in emerging broadcast markets while established production hubs in the United States, Germany, and Japan retain technology export advantages. Cloud infrastructure deployment patterns are redistributing demand geographically as content delivery networks localize processing capacity.
United States
FCC mandates for closed-captioning and emergency alert interoperability drive hardware refresh cycles among terrestrial broadcasters. The Infrastructure Investment and Jobs Act channels federal funding toward rural broadband expansion, creating edge computing node demand in underserved markets. Los Angeles and New York media clusters anchor content production infrastructure requiring 4K and 8K-capable encoding platforms.
Germany
EU Cybersecurity Act certification requirements shape procurement decisions for public sector broadcasters operating under GDPR data residency frameworks. Industrial Mittelstand firms in Bavaria and Baden-Württemberg deploy video infrastructure for manufacturing process monitoring and remote collaboration. Berlin's startup ecosystem incubates software-defined video processing ventures targeting pan-European streaming platforms.
Japan
METI oversight of NHK's Super Hi-Vision roadmap mandates 120fps-capable encoding platforms for 8K broadcast production facilities. Domestic semiconductor fabrication strengths support custom ASIC development for broadcast-specific transcoding workloads. Osaka and Nagoya industrial corridors concentrate system integrators serving regional television networks.
India
TRAI regulations on net neutrality and content delivery influence edge caching infrastructure placement decisions by international platforms. The BharatNet project extends fiber connectivity to tier-3 cities, generating localized server demand for regional language streaming services. Bengaluru and Hyderabad technology clusters host engineering operations for global CDN providers.
United Kingdom
Ofcom broadcasting codes enforce accessibility standards that cascade into video server procurement specifications for commercial television operators. Post-Brexit data localization considerations affect cloud deployment architectures for UK-focused streaming services. Manchester and Glasgow production hubs sustain demand for on-premise hardware in independent television production.
Video Servers Market Vendor Landscape
Concentration sits with diversified technology conglomerates possessing networking silicon and server manufacturing capabilities. The vendor landscape exhibits tiered structure with infrastructure-scale suppliers commanding broadcast and telecom accounts while specialized media technology firms retain positions in production-centric workflows. Two dominant archetypes emerge: integrated platform providers combining switching and processing functions, and modular system vendors emphasizing GPU acceleration flexibility. Competitive dynamics center on strategic partnerships for codec licensing and geographic expansion through sovereign cloud certifications.
Among networking-heritage conglomerates, Cisco Systems, Inc. and Huawei Technologies Co., Ltd. exemplify integrated platform strategies spanning silicon through system software. Dell Technologies Inc. occupies a position within the modular server architecture tier, accommodating acceleration card configurations for transcoding-intensive workloads. These three anchors illustrate divergent approaches to capital intensity—custom ASIC integration versus commodity x86 flexibility—reshaping procurement patterns across broadcaster and streaming platform accounts.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Hewlett Packard Enterprise Development LP |
| Huawei Technologies Co., Ltd. |
| Dell Technologies Inc. |
| SeaChange International, Inc. |
| VITEC |
| Imagine Communications Corp. |
| Evertz Microsystems Ltd. |
| Telestream, LLC |
| Others |
Supply Flow & Price Mechanics
GPU foundry capacity utilization at TSMC and Samsung Foundry anchors cost structures across video server tiers, compressing margins for mid-density encoding platforms while concentrating pricing power among vertically integrated semiconductor suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in video server procurement. Price differentiation separates FCC-certified broadcast-grade systems from cloud-native edge nodes and commodity storage servers, with certification level and volume scale as primary drivers. Pricing pressure stems from cloud object storage substitution eroding hardware margins in archive applications. Content providers exhibit highest price sensitivity due to elastic capacity scaling needs, while television broadcasters under emergency alert mandates show lowest sensitivity to secure deterministic latency guarantees.
Supply Chain Analysis
Taiwan Strait shipping lanes underwrite critical GPU and ASIC delivery schedules for transcoding acceleration hardware. Component sourcing draws from Taiwan for advanced silicon fabrication, South Korea for memory modules, and Japan for precision broadcast components. Single-source vulnerability concentrates in NVIDIA and AMD GPU supply for high-density encoding farms. Distribution runs through direct OEM relationships with broadcast equipment integrators and hyperscaler cloud procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscaler cloud platforms and consolidated streaming conglomerates, fragmenting vendor negotiation leverage across the installed base.
For Market Incumbents: Fortify ASIC-based platform differentiation against commodity x86 competition through deeper kernel-level optimization partnerships with broadcast software vendors. Invest in sovereign cloud certifications for EU Cybersecurity Act compliance to defend public sector accounts against modular server competitors. Prioritize backward integration into ARM-based media acceleration silicon to reduce GPU supply dependency. For New Entrants and Emerging Players: Lead with AI-generated content pipeline infrastructure as the most penetrable white-space segment, where traditional broadcast hardware vendors lack synthetic media workflow expertise. Target India's BharatNet rural broadband buildout for localized edge caching deployments. Pursue channel partnerships with regional system integrators in Osaka and Nagoya industrial corridors rather than direct hyperscaler competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular architecture vendors with GPU acceleration flexibility over integrated platform providers locked into custom silicon roadmaps. Long-term viability hinges on software-defined video processing capabilities that decouple media functions from hardware refresh cycles. Monitor AV1 codec mandate adoption rates among ad-supported streaming services as the primary inflection signal for royalty-free encoding standard displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU Cybersecurity Act credentials unlock GDPR-compliant public sector broadcaster procurement in Germany and France. |
| ARM-Based Media Acceleration | Ampere Altra and AWS Graviton3 instances reduce edge node energy costs per stream in power-constrained metropolitan deployments. |
| Legacy Protocol Dual-Stack Development | SMPTE 2110 and SDI coexistence maintains hybrid facility market access during broadcast infrastructure transition periods. |
| Edge Caching Infrastructure Partnership | BharatNet fiber connectivity creates localized server demand for regional language streaming services in tier-3 Indian cities. |
| AI-Generated Content Pipeline Integration | Synthetic media workflows require new ingest configurations that traditional broadcast hardware cannot accommodate. |
Methodological Framework
Initial hypotheses were tested against primary input from broadcast engineering directors, CDN infrastructure architects, semiconductor procurement leads, and regulatory compliance officers, then refined through secondary validation against hyperscaler capex disclosures, FCC equipment authorization databases, ETSI technical specifications, and customs trade flow records. Bottom-up unit economics triangulated against top-down market sizing across deployment models and end-user segments.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within streaming server, storage server, and edge computing node categories. Segmentation dimensions modeled include deployment architecture, codec complexity tier, regulatory compliance cluster, and regional production hub. CAGRs were derived from installed base growth rates and replacement cycle compression observed across the analysis window, with specific weighting applied to 8K broadcast mandate timelines and rural broadband infrastructure buildouts.
Forecasts assume regulatory continuity in FCC closed-captioning regimes and EU GDPR data residency frameworks; material policy shifts would require re-modeling across jurisdictional boundaries. Practitioners should keep alternative scenarios live as GPU supply concentration and AV1 codec adoption trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Global Live Streaming Video Platform Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market