
 Online Cosmetics Market | 2026-2036
Online Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Online Cosmetics Market Outlook
ISO 22716 Good Manufacturing Practices certification is bifurcating vendor eligibility between compliant direct-to-consumer brands and unqualified marketplace sellers. L'Oréal leverages integrated R&D labs to sustain formulation leadership across digital channels. Sephora anchors its competitive stance through exclusive brand partnerships and loyalty data infrastructure.
Online cosmetics encompass beauty and personal care products distributed through digital commerce infrastructure, requiring stability-tested formulations, tamper-evident packaging, and temperature-controlled logistics to preserve active ingredient efficacy. Skincare commands the deepest margin pools due to repeat purchase cycles and subscription mechanics, while social media platforms represent the fastest-growing acquisition channel through influencer-led conversion funnels. Fragrance remains the most challenging category online given the absence of sensory trial, though virtual sampling tools are narrowing this gap.
FDA cosmetic registration requirements under MoCRA reshape product safety documentation obligations for US-bound sellers, while EU REACH and the EU Green Deal tighten ingredient disclosure and sustainability claims across European listings. China's NMPA and SAMR enforce live-streaming commerce disclosure rules that govern influencer-led cosmetic transactions. Stakeholders must decide whether to build proprietary fulfillment networks or outsource to third-party logistics providers as cross-border regulatory fragmentation intensifies.
Market Dynamics
Live-streaming commerce infrastructure is compressing traditional brand-retailer relationships as influencer-led transactions capture purchase intent at the point of content consumption.
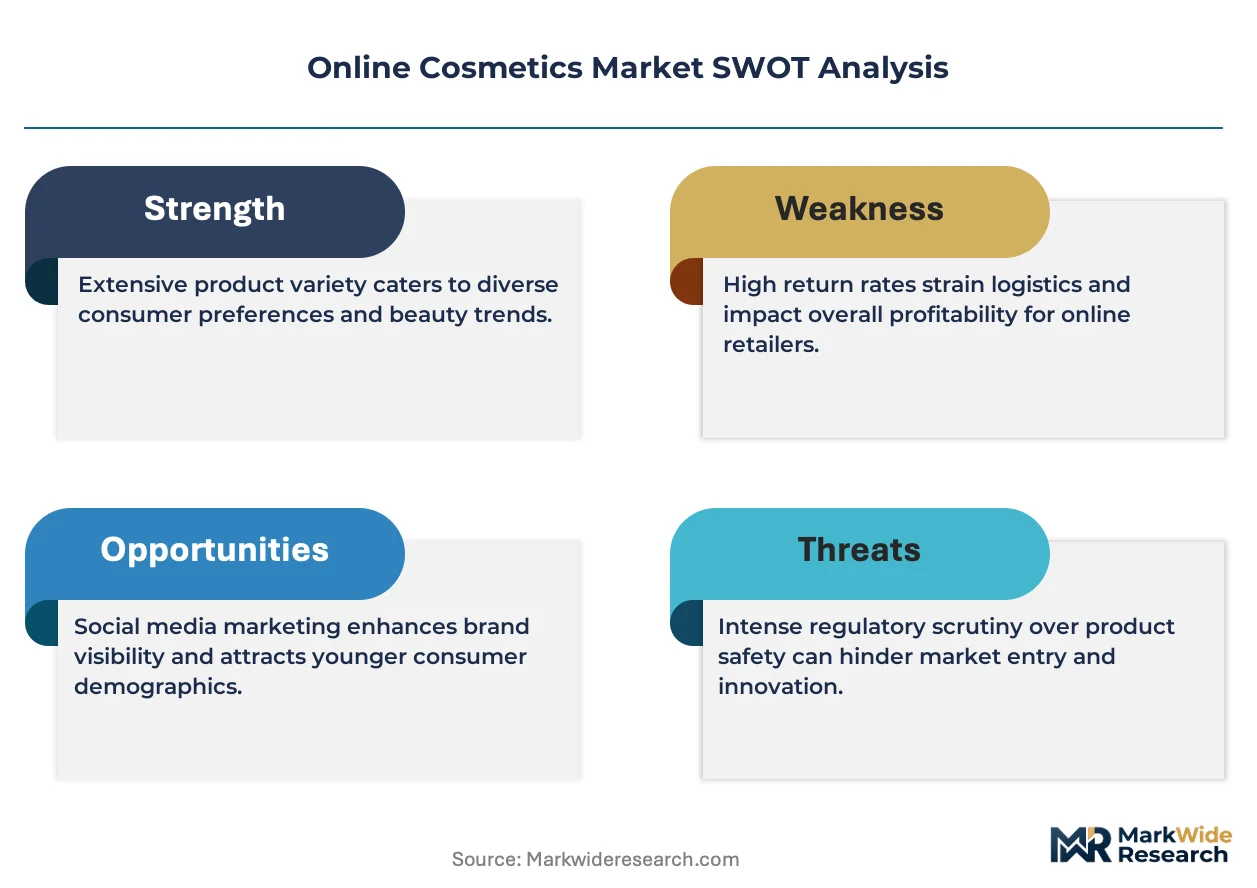
Growth Catalysts
- EU REACH compliance mandates:Ingredient disclosure requirements are accelerating transparency investments among cross-border sellers seeking European market access.
- Social commerce platforms:Short-form video integration enables direct checkout from content, collapsing the discovery-to-purchase funnel for Gen Z demographics.
- Temperature-controlled logistics networks:Cold-chain fulfillment expansion preserves active ingredient stability in retinol and vitamin C formulations during last-mile delivery.
Market Restraints
- Cross-border regulatory fragmentation:Divergent cosmetic registration requirements between FDA MoCRA, EU REACH, and China NMPA create compliance cost stacking for multi-territory sellers.
- Fragrance sensory trial gap:Absence of olfactory evaluation before purchase limits online conversion rates in perfume and cologne categories.
- Active ingredient volatility:Retinol and peptide stability requirements necessitate specialized packaging that elevates unit economics above mass-market thresholds.
Strategic Opportunities
- Subscription skincare mechanics:Replenishment automation captures lifetime value through recurring revenue models in serum and moisturizer categories.
- Virtual sampling tools:AI-powered skin analysis and augmented reality try-on functions narrow the sensory gap in fragrance and color cosmetics.
- ISO 22716 certification differentiation:Good Manufacturing Practices compliance creates vendor eligibility bifurcation favoring certified direct-to-consumer brands over marketplace resellers.
Industry Challenges
- Formulation stability testing:Extended shelf-life validation timelines compress product launch windows against fast-trending social commerce cycles.
- Influencer disclosure compliance:China SAMR live-streaming commerce rules impose real-time transaction transparency requirements that increase operational overhead.
- Cold-chain fulfillment integration:Temperature-controlled last-mile logistics require capital deployment that strains emerging brand balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Cosmetics Market |
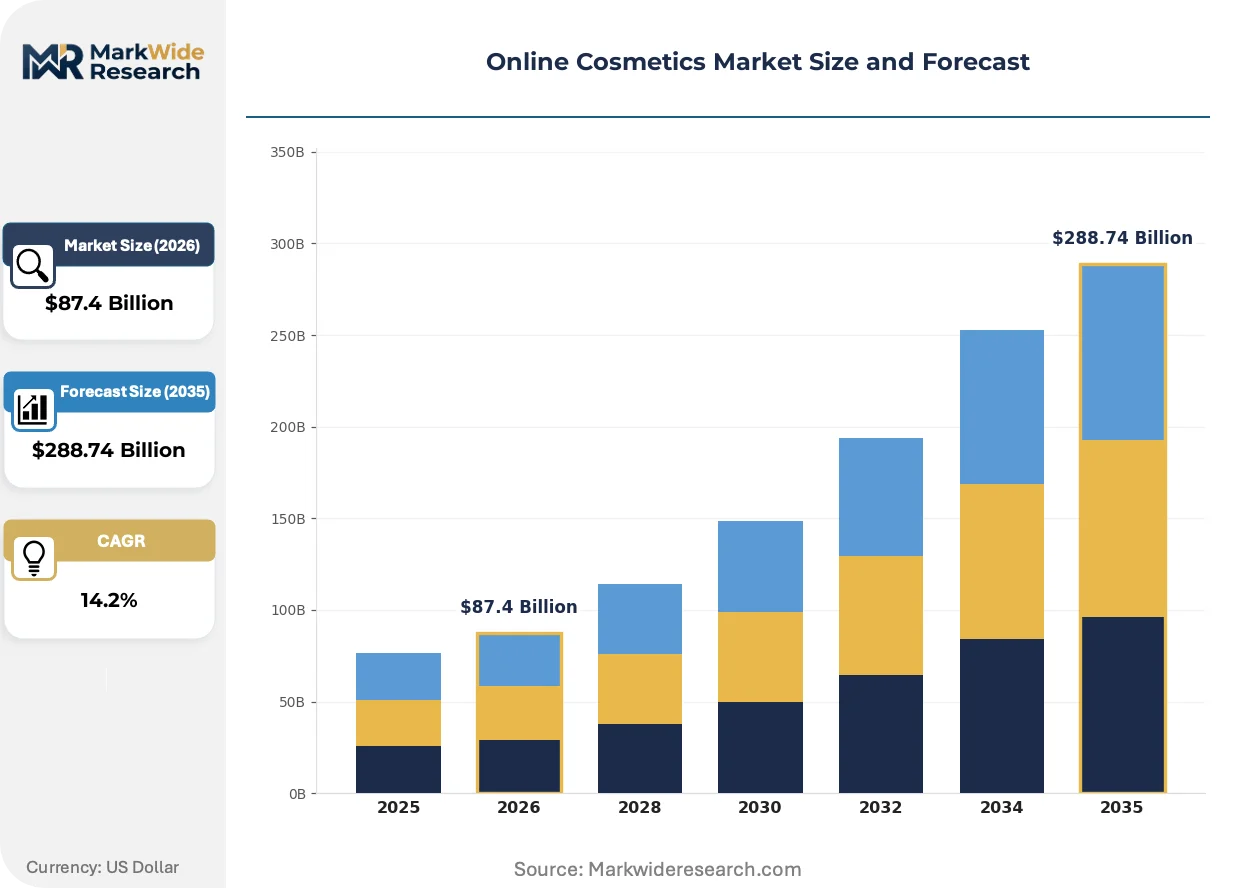
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $288.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Makeup, Skincare, Fragrance, Hair Care Customer Type: Millennials, Gen Z, Professionals, Moms Platform: Website, Mobile App, Social Media, Third-Party Retailers Price Tier: Luxury, Mid-Range, Budget, Premium |
| Companies Covered | L'Oréal, Estée Lauder Companies, Procter & Gamble, Unilever, Beiersdorf, Shiseido, Henkel, Coty, Sephora, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Cosmetics Market Strategic Shifts
Digital commerce infrastructure is embedding diagnostic and personalization capabilities directly into the purchase journey, shifting competitive advantage from assortment breadth to data-driven formulation matching.
Portable skin analysis hardware is miniaturizing diagnostic capabilities previously confined to clinical settings. Direct-to-consumer brands integrate spectroscopic sensors into smartphone attachments for at-home moisture and sebum measurement. This capability compression enables personalized serum recommendations without dermatologist intermediation.
EU Green Deal sustainability claims enforcement is tightening substantiation requirements for cosmetic packaging and ingredient sourcing. The regulation mandates lifecycle documentation that elevates compliance costs for brands relying on unverified "clean beauty" positioning. European listings now require third-party certification for biodegradability and carbon footprint assertions.
Buyer concentration in China's tier-one cities is rotating demand toward live-streaming commerce anchors. Influencer-led transactions displace traditional e-commerce search-and-compare behavior in Beijing, Shanghai, and Shenzhen. This channel shift compresses brand control over pricing and messaging as key opinion leaders intermediate consumer relationships.
Online Cosmetics Market Segmentation
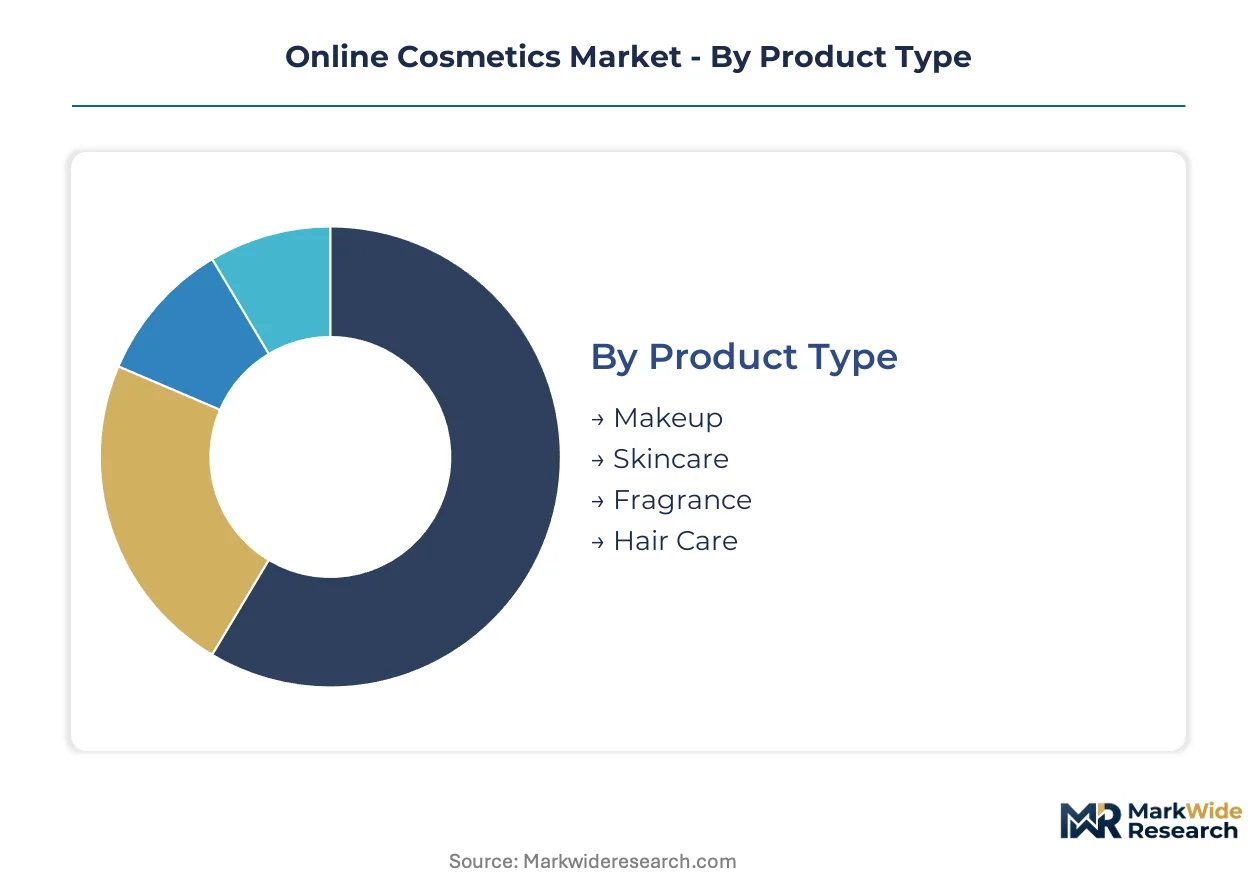
Segmentation in online cosmetics determines fulfillment infrastructure requirements, regulatory documentation scope, and channel-specific margin structures. Each dimension carries distinct implications for cold-chain logistics, ingredient disclosure obligations, and customer acquisition economics.
Product Type:
Channel mix varies sharply across product categories, with skincare and makeup dominating direct-to-consumer websites while fragrance and hair care concentrate in third-party retailer ecosystems.
- Makeup:Color cosmetics with formulation stability across temperature ranges. Virtual try-on tools and AR shade-matching drive conversion in China's tier-one cities where live-streaming commerce anchors purchase behavior.
- Skincare:Serum and moisturizer formulations containing retinol, vitamin C, and peptides require temperature-controlled logistics. Repeat purchase cycles and subscription mechanics in this category generate the deepest margin pools across digital channels.
- Fragrance:Olfactory-dependent products face the steepest online conversion barriers due to absent sensory trial.
- Hair Care:Shampoo and conditioner sets with lower per-unit value ship efficiently through standard fulfillment networks.
By volume, Skincare leads. By growth pace, Fragrance virtual sampling investments are climbing the fastest.
Customer Type:
Cost tier alignment separates these segments, with Gen Z and Millennials clustering in mid-range and budget tiers while Professionals and Moms concentrate in premium and luxury price bands.
- Millennials:Digital-native cohort with established subscription relationships and cross-platform purchasing habits. This segment concentrates demand in mobile app environments where loyalty program integration drives retention.
- Gen Z:Short-form video-native consumers entering the market through social commerce discovery. SAMR disclosure requirements in China and FTC guidelines in the US impose compliance overhead on influencer-led transactions targeting this demographic.
- Professionals:Time-constrained buyers prioritizing curated assortments and expedited fulfillment.
- Moms:Household-centric purchasers with bulk-buying patterns and sensitivity to ingredient transparency.
By volume, Millennials dominate current spend. By growth pace, Gen Z is gaining share fastest.
Platform:
Supply concentration determines platform economics, with owned channels capturing first-party data while third-party ecosystems absorb customer acquisition costs.
- Website:Proprietary e-commerce infrastructure enabling full margin retention and direct customer relationships. EU REACH compliance documentation and FDA MoCRA registration requirements flow through this channel for cross-border sellers.
- Mobile App:Push-notification-driven engagement with integrated loyalty mechanics and subscription management. This platform anchors retention strategies in tier-one Chinese cities where super-app ecosystems consolidate beauty transactions.
- Social Media:Content-embedded checkout collapsing discovery-to-purchase funnels.
- Third-Party Retailers:Marketplace access with diluted margins but expanded reach.
By volume, Third-Party Retailers lead. By growth pace, Social Media is expanding most quickly.
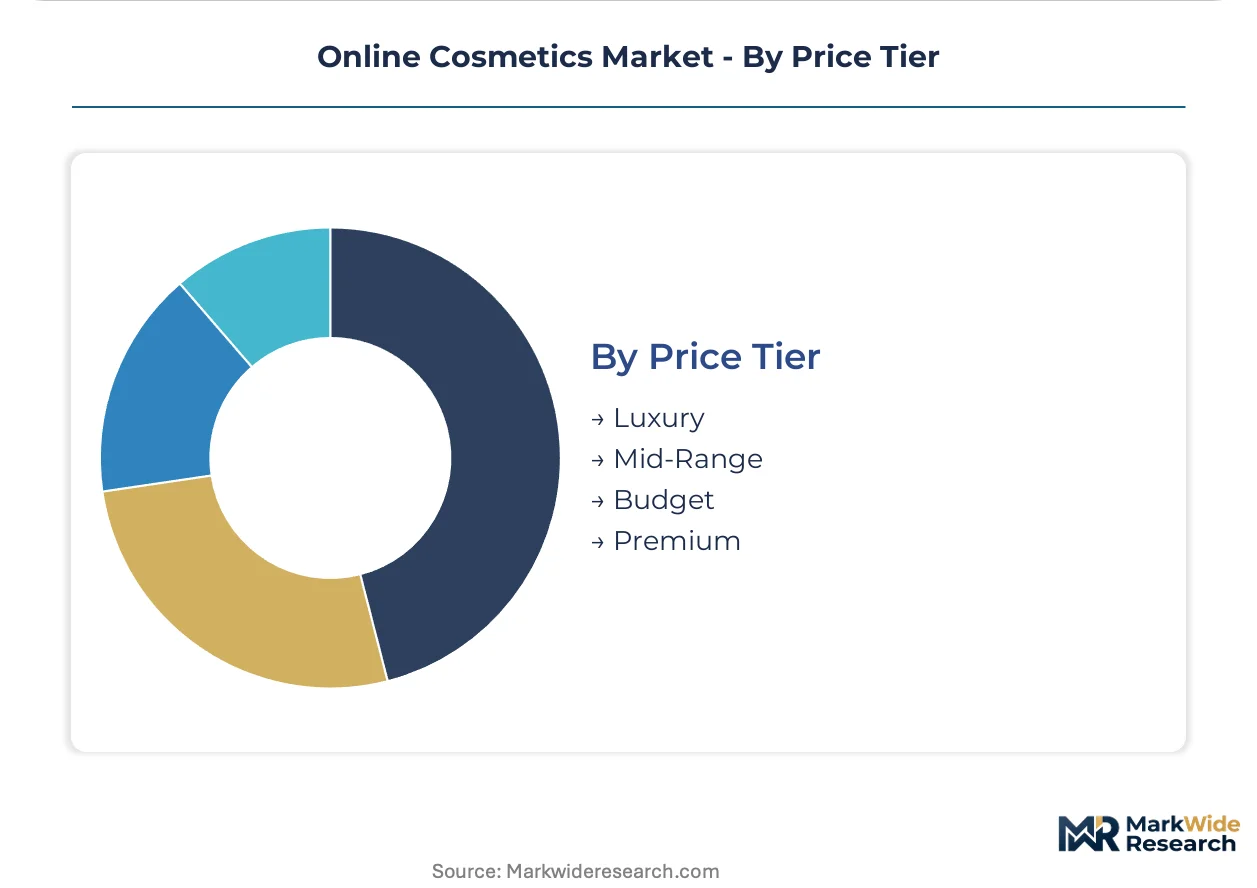
Price Tier:
Margin structure stratifies across tiers, with luxury and premium segments absorbing cold-chain costs while budget and mid-range compete on logistics efficiency and scale economics.
- Luxury:High-margin positioning with packaging-driven differentiation and exclusive distribution. ISO 22716 certification requirements create vendor eligibility bifurcation favoring compliant direct-to-consumer brands in this tier.
- Premium:Science-backed formulations with clinical validation claims and dermatologist endorsements. EU Green Deal substantiation requirements for sustainability claims impose documentation costs that this tier absorbs more readily than lower price bands.
- Mid-Range:Mass-market accessibility with influencer-driven discovery.
- Budget:Price-sensitive positioning with streamlined packaging and standard fulfillment.
By volume, Mid-Range leads. By growth pace, Premium is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z buyers concentrate in China's tier-one cities, the United States coastal metros, and Germany's urban centers, driving platform-specific demand for social commerce and subscription skincare mechanics across distinct regulatory environments.
China
Live-streaming commerce anchors cosmetic transactions in Beijing, Shanghai, and Shenzhen where SAMR disclosure rules govern influencer-led sales. NMPA registration requirements enforce ingredient safety documentation for cross-border sellers. The Yangtze River Delta cluster concentrates fulfillment infrastructure for temperature-sensitive retinol and peptide formulations.
United States
Subscription skincare mechanics dominate customer retention in New York and Los Angeles metro areas. FDA MoCRA registration reshapes product safety documentation obligations for domestic and imported cosmetics. The Pacific Northwest corridor hosts cold-chain logistics expansion serving direct-to-consumer brands with active ingredient stability requirements.
Germany
EU REACH compliance mandates accelerate transparency investments among brands seeking European market access through Berlin and Munich digital commerce hubs. ECHA enforcement tightens substantiation requirements for sustainability claims on packaging. The North Rhine-Westphalia cluster anchors third-party logistics networks handling cross-border cosmetic fulfillment.
Japan
Premium-tier demand concentrates in Tokyo and Osaka where METI standards intersect with ISO 22716 certification preferences among quality-sensitive buyers. PMDA cosmetic safety guidelines impose documentation requirements distinct from Western frameworks. The Kansai region hosts formulation R&D facilities serving digital-first domestic brands.
United Kingdom
Post-Brexit regulatory divergence creates compliance cost stacking for sellers navigating both UK and EU REACH frameworks through London and Manchester distribution nodes. The Medicines and Healthcare products Regulatory Agency maintains cosmetic safety notification requirements. Southeast England clusters last-mile fulfillment infrastructure for same-day delivery in premium skincare categories.
Online Cosmetics Market Competitive Environment
Player mix skews toward integrated multinational conglomerates with captive R&D and direct-to-consumer infrastructure, creating a tiered structure where ISO 22716 certification bifurcates vendor eligibility. Three archetypes dominate: science-backed formulation leaders with integrated labs, platform-anchored retailers with exclusive brand partnerships, and social-native direct-to-consumer brands built on influencer acquisition. Competitive moves concentrate on exclusive distribution partnerships and cold-chain fulfillment network expansion.
Within the integrated multinational tier, L'Oréal and Estée Lauder Companies occupy positions exemplifying R&D-forward architecture, while Sephora represents platform-anchored retail archetype with loyalty data infrastructure. Shiseido sits within the Asia-Pacific formulation specialist category. These entities collectively illustrate the competitive tension between proprietary channel control and third-party marketplace access.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder Companies |
| Procter & Gamble |
| Unilever |
| Beiersdorf |
| Shiseido |
| Henkel |
| Coty |
| Sephora |
| Others |
Value Chain & Pricing Dynamics
Subscription-based capacity reservations lock in multi-year ingredient supply agreements for retinol and peptide formulations, anchoring price visibility for direct-to-consumer brands navigating EU REACH compliance costs and cold-chain logistics investments. This contract structure concentrates procurement power among ISO 22716-certified manufacturers while elevating unit economics for temperature-sensitive skincare above mass-market thresholds.
Pricing Analysis
Cost-plus contracts with commodity chemical indexation dominate raw material procurement for active ingredients, linking formulation costs to fluctuating retinol and vitamin C feedstock markets. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22716-certified brands from uncertified marketplace resellers, with certification grade and cold-chain delivery cost as primary differentiation drivers. Price compression in the budget tier intensifies as unqualified sellers absorb regulatory documentation overhead to maintain volume. Gen Z consumers in social commerce channels exhibit highest price sensitivity, while Professionals in premium tiers prioritize formulation stability over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate fragrance and color cosmetics with stable shelf-life profiles, while strategic stockpiling prevails in retinol and peptide formulations vulnerable to temperature excursions during transit. Manufacturing concentration centers on China for packaging components, France for fragrance compounds, and South Korea for advanced skincare actives. Raw material dependencies include palm-derived emollients, synthetic retinoids, and glass packaging substrates. Single-source vulnerability in specialized cold-chain carriers elevates risk exposure for direct-to-consumer brands. Distribution runs through third-party logistics networks in China's Yangtze River Delta, Germany's North Rhine-Westphalia, and the US Pacific Northwest corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from social-native direct-to-consumer brands capturing Gen Z purchase intent through influencer-led discovery, collapsing traditional brand-retailer intermediation.
For Market Incumbents: Compound formulation leadership through captive R&D integration and exclusive raw material offtake agreements with South Korean active ingredient suppliers. Deepen cold-chain fulfillment infrastructure in China's tier-one cities to defend against social commerce entrants eroding loyalty program retention. ISO 22716 certification expansion creates vendor eligibility moats against uncertified marketplace resellers. For New Entrants and Emerging Players: Differentiate on virtual sampling capabilities targeting fragrance's sensory trial gap, where AI-powered skin analysis and AR try-on functions narrow conversion barriers. White-space concentration sits in subscription skincare mechanics for peptide and retinol categories underserved by incumbent replenishment automation. SAMR-compliant influencer disclosure infrastructure enables regulatory-first positioning in China's live-streaming commerce channels. For Investors and Strategic Acquirers: Social-native direct-to-consumer brands with proprietary virtual sampling IP and ISO 22716 certification represent the highest-conviction acquisition archetype for portfolio exposure to Gen Z channel shift. Long-term viability hinges on cold-chain logistics integration and EU Green Deal substantiation capabilities. Watch for inflection when SAMR enforcement intensity in live-streaming commerce triggers compliance cost stacking that consolidates vendor bases.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Fulfillment Network Expansion | Preserves retinol and vitamin C efficacy during last-mile delivery in tier-one Chinese cities. |
| ISO 22716 Certification Investment | Creates vendor eligibility bifurcation favoring compliant direct-to-consumer brands over marketplace resellers. |
| Virtual Sampling Technology Deployment | AI-powered skin analysis narrows sensory trial gaps in fragrance and color cosmetics conversion. |
| Subscription Skincare Mechanics Launch | Replenishment automation captures lifetime value through recurring revenue in serum categories. |
| EU Green Deal Substantiation Program | Third-party certification for biodegradability claims defends premium positioning in European listings. |
Study Parameters
Operator-level perspectives from brand managers at direct-to-consumer skincare companies, category buyers at Sephora and third-party retailers, cold-chain logistics planners, and regulatory affairs leads specializing in FDA MoCRA and EU REACH compliance anchored the qualitative base. Secondary validation drew from FDA cosmetic registration filings, ECHA substance documentation databases, SAMR live-streaming commerce disclosure records, and Nielsen retail audit data for beauty categories. Bottom-up demand modeling across customer segments triangulated with top-down market sizing from customs trade flows and platform transaction disclosures.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity scenarios, cold-chain cost inflation bands, and social commerce platform algorithm changes throughout the projection horizon. Segmentation dimensions modeled include product type, customer cohort, platform channel, and price tier alongside formulation stability requirements and certification status. CAGRs derived from historical trajectory analysis and adoption curve fitting for virtual sampling tools and subscription mechanics. Industry-specific inputs incorporated NMPA registration timelines, EU Green Deal substantiation cost curves, and influencer disclosure compliance overhead estimates.
Material uncertainties — regulatory enforcement divergence between FDA, ECHA, and SAMR frameworks, cold-chain carrier capacity constraints, and social commerce platform policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions on certification adoption rates and virtual sampling technology penetration. Revision becomes warranted when cross-border compliance cost stacking exceeds threshold levels that trigger vendor base consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
Organic Baby Shampoo Market
Beauty & Personal Care
Pore Strips Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Electric Face Cleanser Market
Beauty & Personal Care
Europe Cosmetics Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
Nail Care Products Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market