
 Beauty Devices Market | 2026-2036
Beauty Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Beauty Devices Market Intelligence
Aftermarket service revenue is rewriting profit architecture across the beauty devices sector. Lumenis leverages its installed base of laser platforms to capture recurring consumables and maintenance contracts. Alma Lasers anchors its position through direct regional service hubs that minimize third-party dependence. HUIMAIN competes on hardware-plus-subscription bundling that locks clinic clients into multi-year upgrade cycles.
Beauty devices are electromechanical or optical instruments engineered to deliver controlled energy outputs—typically between 400 nm and 10,600 nm wavelength for laser modalities—to modify skin or hair biology for cosmetic outcomes. Radiofrequency and laser & light therapy segments dominate capital deployment among medical aesthetic centers seeking wrinkle reduction and skin tightening protocols. LED light therapy occupies the fastest-expanding tier as home-use manufacturers drive cost-down engineering for acne treatment applications. Facial cleansing devices represent the most mature margin pool, with brand loyalty sustaining premium pricing despite commoditization at lower tiers.
FDA 510(k) premarket notifications and EU MDR conformity assessments shape device commercialization timelines and clinical evidence requirements for manufacturers targeting the United States and European markets. China's NMPA medical device registration mandates local testing partnerships that extend market access lead times for foreign RF and ultrasound platforms. Stakeholders must monitor how FDA software-as-medical-device guidance evolves for AI-powered skin analysis tools that increasingly control treatment parameters.
Market Dynamics
AI-powered skin analysis tools are virtualizing treatment parameter control, compressing the traditional clinician-intermediated consultation model and forcing hardware manufacturers to defend device margins through software differentiation.
Growth Catalysts
- RF and laser 510(k) clearance pathways:FDA streamlined premarket notifications accelerate commercialization timelines for radiofrequency and laser platforms entering US dermatology clinics.
- Medical aesthetic center scaling in China:Tier-one city clinics expand premium service menus, concentrating capital deployment into professional-grade energy-based devices.
- Home-use LED engineering cost-downs:Manufacturing process innovations reduce component costs for acne treatment wavelengths, expanding addressable consumer bases.
Market Restraints
- EU MDR conformity assessment complexity:Extended clinical evidence requirements and notified body bottlenecks delay laser system launches in European markets.
- NMPA local testing mandates:China's medical device regulator requires domestic partnership testing for foreign RF and ultrasound platforms, extending market access lead times.
- LED wavelength commoditization:Mature semiconductor supply chains for 415 nm and 630 nm diodes erode hardware differentiation and compress unit economics.
Strategic Opportunities
- AI-software-as-medical-device guidance evolution:FDA draft frameworks for algorithm-controlled treatment parameters create first-mover advantage for compliant skin analysis platforms.
- Consumables and maintenance contract expansion:Installed base monetization through recurring revenue streams rewrites profit architecture for capital equipment vendors.
- Hardware-plus-subscription bundling:Multi-year upgrade cycle lock-in models shift clinic relationships from transactional to contractual, improving lifetime value capture.
Industry Challenges
- Software validation for AI treatment control:FDA software-as-medical-device evidentiary standards demand specialized regulatory affairs talent scarce among legacy hardware engineering teams.
- Legacy device interoperability:New AI-powered platforms face integration friction with existing clinic management systems and electronic health record infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beauty Devices Market |
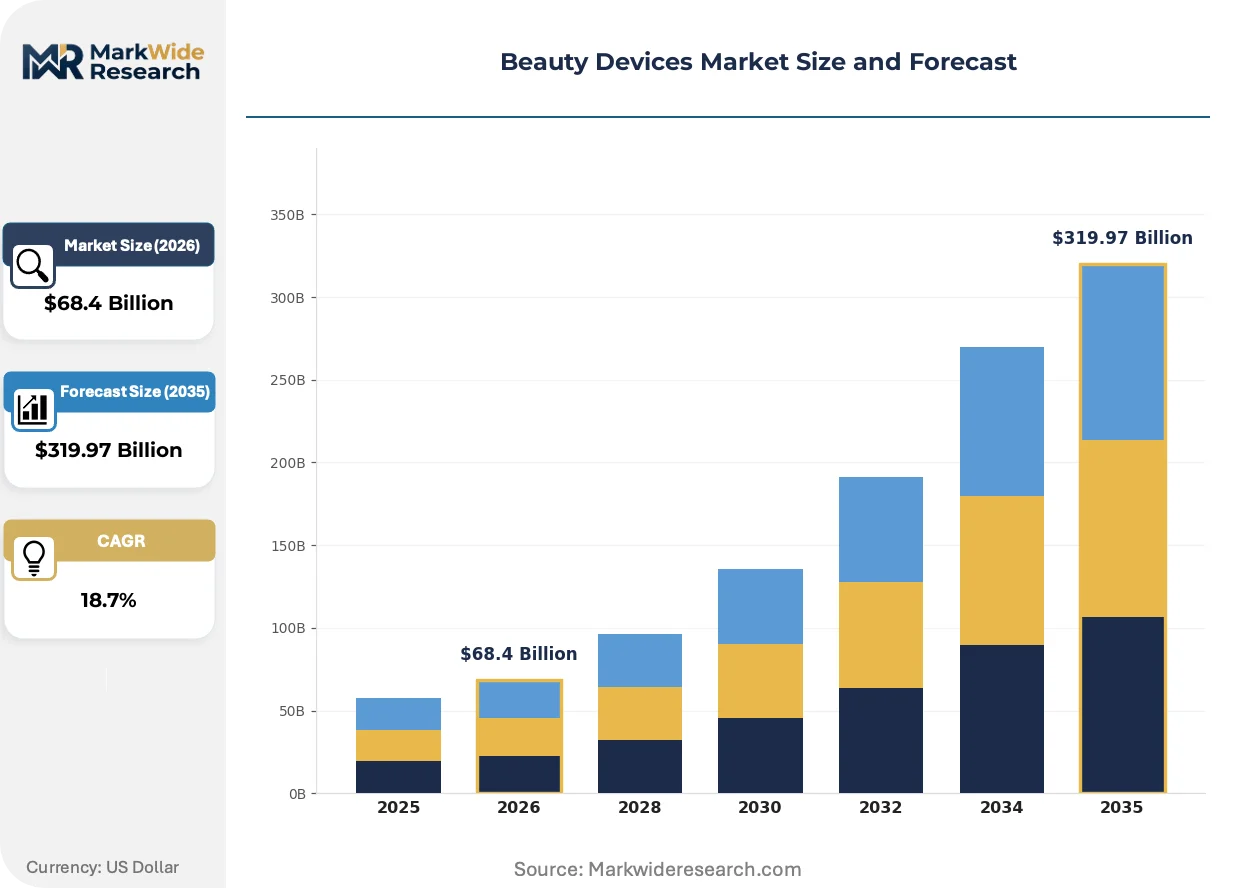
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $319.97 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Cleansing Devices, Hair Removal Devices, Anti-Aging Devices, Body Shaping Devices, Oral Care Devices Technology: Radiofrequency, Laser & Light Therapy, Ultrasound, Microcurrent, LED Light Therapy Application: Wrinkle Reduction, Skin Tightening, Acne Treatment, Hair Removal, Skin Rejuvenation End User: Home Users, Beauty Salons, Dermatology Clinics, Spas, Medical Aesthetic Centers |
| Companies Covered | Lumenis, Alma Lasers, HUIMAIN, Cutera, Venus Concept, BTL Aesthetics, InMode, Zimmer MedizinSysteme, Cynosure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beauty Devices Market Strategic Shifts & Innovations
Digital skin analysis and algorithmic treatment personalization are compressing the traditional clinical consultation layer, forcing device economics to migrate from hardware margins toward software-enabled recurring revenue streams.
AI-powered diagnostic cameras with embedded spectral analysis are virtualizing the initial patient assessment function previously performed by trained clinicians. Medical aesthetic centers in South Korea and the United States are adopting these platforms at accelerating cadence to standardize treatment protocols across practitioner skill levels. This virtualization is compressing consultation time per patient while generating proprietary skin condition datasets that lock clinics into specific hardware ecosystems.
FDA software-as-medical-device guidance evolution is redefining evidentiary requirements for algorithm-controlled energy delivery systems. Manufacturers must now submit clinical validation data for AI models that adjust laser parameters in real-time, extending development timelines but creating regulatory moats against unvalidated competitors. Dermatology device segments with higher treatment complexity—particularly fractional laser and multi-wavelength platforms—face the steepest compliance adaptation costs.
Clinic procurement patterns are fragmenting across ownership models, with independent medical aesthetic centers favoring lease-based hardware access over capital purchases. Device vendors respond with outcome-linked financing structures that tie payment obligations to utilization metrics. This shift is most pronounced in China's tier-one cities and Brazil's São Paulo corridor, where clinic formation rates outpace traditional credit facility availability.
Beauty Devices Market Segmentation
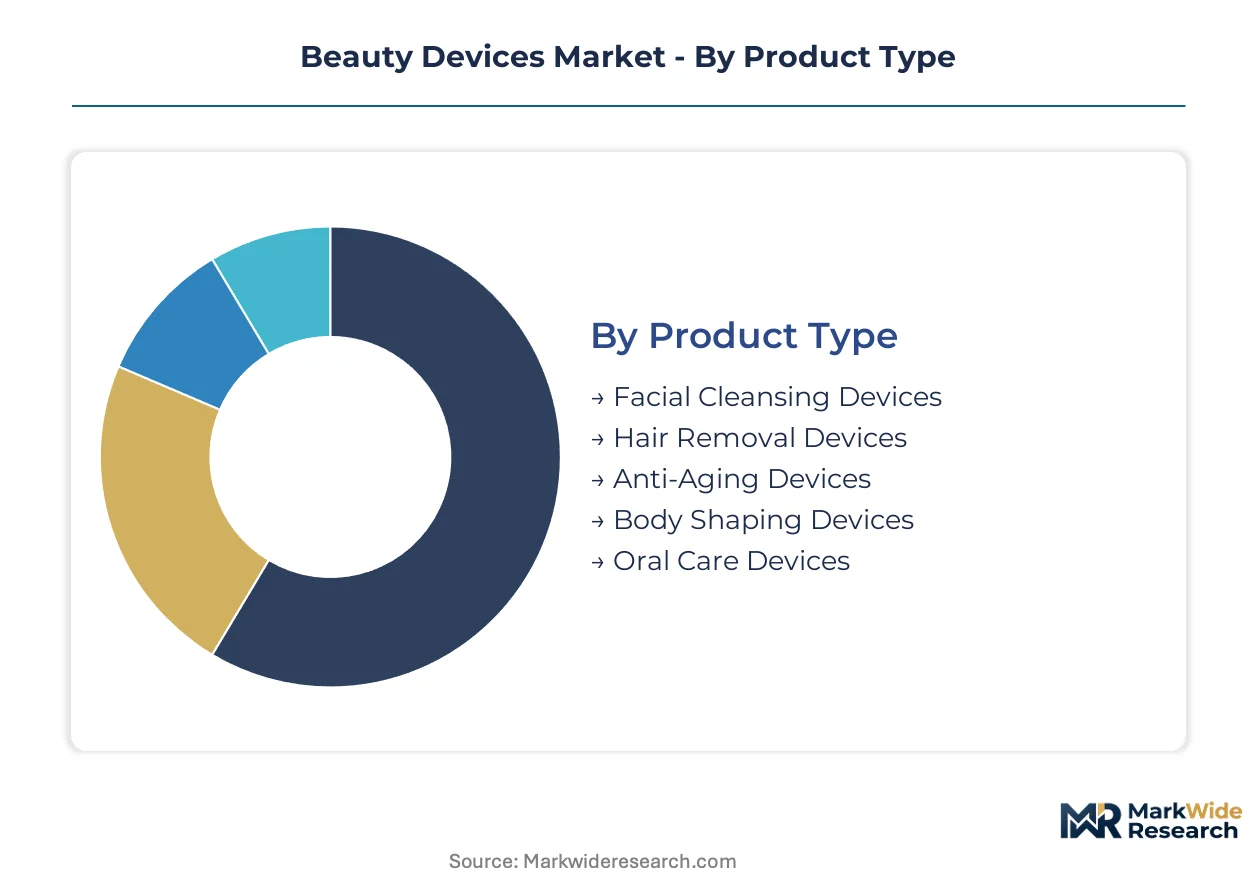
Segmentation in beauty devices reveals how technology maturity, clinical validation requirements, and consumer access tiers create distinct competitive battlegrounds. Manufacturers must align R&D pipelines and distribution strategies against specific segment economics rather than treating the market as monolithic.
Product Type:
Maturity varies sharply across this category, with decades-old cleansing formats contrasting against emerging body contouring platforms still accumulating clinical evidence.
- Facial Cleansing Devices:Sonic oscillation and silicone-bristle systems dominate this saturated tier. Brand loyalty sustains premium pricing in the United States and South Korea despite commoditized entry-level alternatives from Shenzhen manufacturing clusters.
- Hair Removal Devices:IPL and diode laser systems for home use concentrate demand in Germany and Japan where regulatory familiarity accelerates consumer adoption. FDA 510(k) clearance requirements for professional-grade platforms create margin protection for established vendors.
- Anti-Aging Devices:RF and microcurrent formats target wrinkle reduction protocols in medical aesthetic centers.
- Body Shaping Devices:Cryolipolysis and ultrasound fat reduction platforms command capital deployment from clinic chains in Brazil and Mexico.
- Oral Care Devices:LED whitening and water flosser systems occupy the lowest clinical validation tier with consumer-direct distribution dominance.
Facial cleansing devices retain volume leadership; body shaping devices hold the steepest expansion curve.
Technology:
Cost tier stratification separates professional-grade energy platforms from mass-market semiconductor implementations.
- Radiofrequency:Monopolar and bipolar configurations deliver controlled dermal heating for collagen remodeling. Tier-one city clinics in China scale multi-generational RF platforms as core service menu anchors.
- Laser & Light Therapy:Fractional CO2 and erbium:YAG systems at 10,600 nm and 2,940 nm wavelengths dominate scar revision and resurfacing protocols. FDA premarket notification pathways for laser modifications compress upgrade cycles for US dermatology practices.
- Ultrasound:Microfocused ultrasound platforms target subcutaneous tissue layers for non-surgical lifting applications.
- Microcurrent:Low-level electrical stimulation devices occupy the home-use tier with minimal regulatory burden.
- LED Light Therapy:415 nm blue and 630 nm red diode arrays drive manufacturing cost-downs for acne treatment consumer devices.
Laser and light therapy retains volume leadership; LED light therapy holds the steepest expansion curve.
Application:
Customer type fragmentation splits demand between clinician-administered protocols and self-directed consumer regimens.
- Wrinkle Reduction:Botulinum toxin adjacency drives RF and laser platform adoption in medical aesthetic centers. South Korean clinic chains standardize combination protocols across practitioner skill levels.
- Skin Tightening:Non-invasive lifting demand concentrates among 35-55 demographic segments in the United States and United Kingdom. Ultrasound and RF modalities compete on downtime minimization and pain profile differentiation.
- Acne Treatment:Blue light LED protocols expand into teenage and young adult consumer bases through direct-to-retail channels.
- Hair Removal:Permanent reduction claims require regulatory substantiation that favors established IPL and laser vendors.
- Skin Rejuvenation:Broad indication captures fractional laser, intense pulsed light, and combination energy platform demand.
Wrinkle reduction retains volume leadership; skin tightening holds the steepest expansion curve.
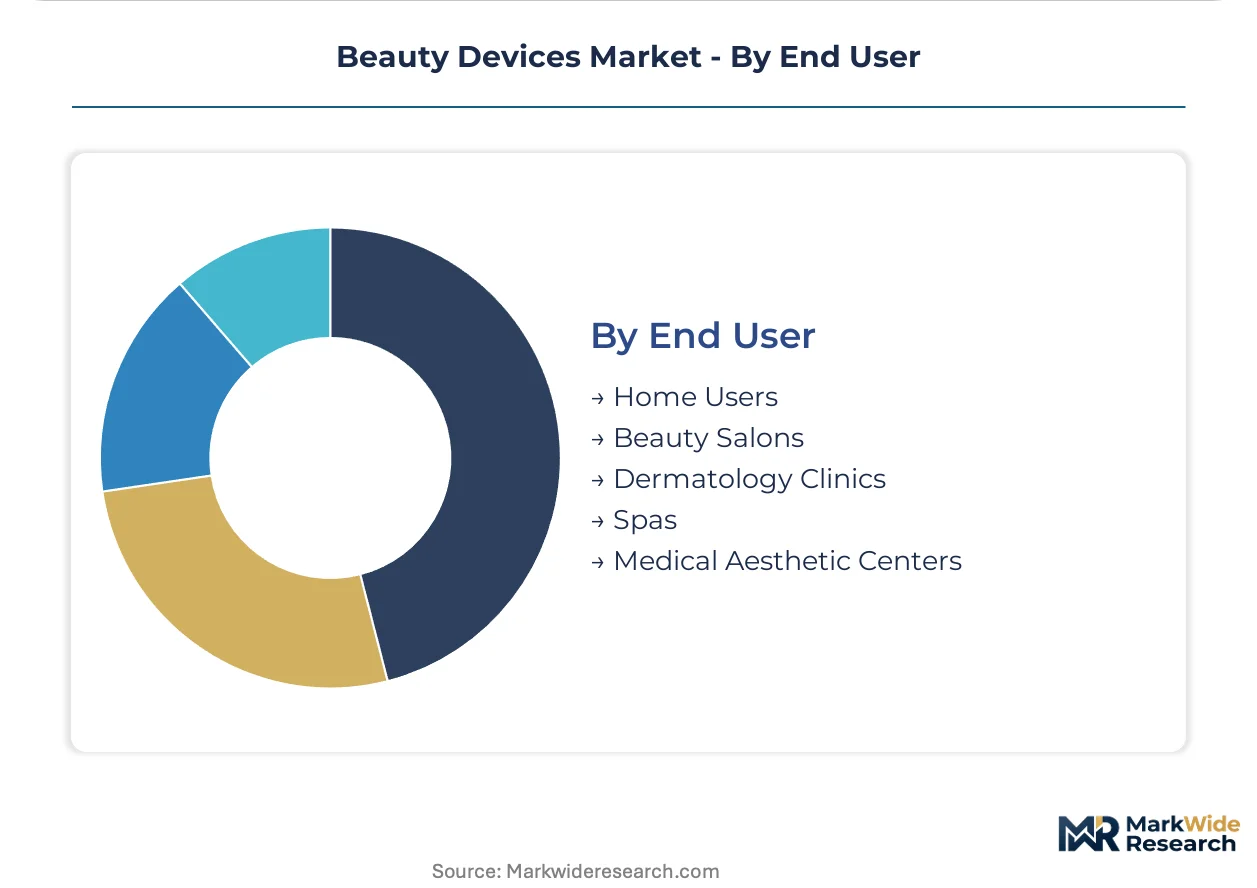
End User:
Procurement authority and capital availability create divergent purchasing patterns across ownership models.
- Home Users:Consumer-direct channels dominate with price elasticity driving semiconductor-based LED and microcurrent formats. Amazon and Tmall Global distribution concentrates volume in the United States and China.
- Beauty Salons:Non-medical aesthetic venues in France and Italy favor lease-based equipment access over capital purchases due to credit facility constraints.
- Dermatology Clinics:Physician-supervised settings in Germany and Switzerland demand FDA and CE-marked platforms with published clinical evidence.
- Spas:Wellness-oriented venues prioritize experiential treatment protocols with lower energy density requirements.
- Medical Aesthetic Centers:Multi-location chains in São Paulo and Mexico City deploy outcome-linked financing for high-unit-cost laser and ultrasound systems.
Home users retain volume leadership; medical aesthetic centers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home-use consumers in Germany and Japan exhibit the lowest price elasticity, while clinic buyers in Brazil and Mexico face acute capital constraints that reshape procurement patterns toward lease structures.
United States
FDA 510(k) clearance pathways for RF and laser systems compress commercialization timelines for dermatology device vendors. The agency's evolving software-as-medical-device guidance demands clinical validation for AI-controlled treatment parameters. Los Angeles and New York metro medical aesthetic centers scale multi-location device fleets with outcome-linked financing structures.
Germany
EU MDR conformity assessments create notified body bottlenecks that delay laser system launches despite strong clinic demand for wrinkle reduction protocols. The country's national pharmaceutical regulator enforces extended clinical evidence requirements for energy-based devices. Frankfurt and Munich dermatology practices concentrate procurement of CE-marked fractional CO2 platforms.
China
NMPA local testing mandates extend market access lead times for foreign RF and ultrasound platforms entering tier-one city clinics. The medical device regulator requires domestic partnership testing that complicates foreign vendor entry. Shanghai and Beijing medical aesthetic centers scale premium service menus with hardware-plus-subscription bundling models.
Brazil
São Paulo corridor clinic formation rates outpace traditional credit facility availability, forcing outcome-linked financing for high-unit-cost laser systems. ANVISA registration pathways for imported energy devices add compliance layers that favor established distributors. Rio de Janeiro and Minas Gerais aesthetic chains deploy cryolipolysis and ultrasound fat reduction platforms with utilization-tied payment structures.
South Korea
MFDS accelerated review pathways for AI-powered diagnostic cameras support adoption of algorithmic skin analysis tools in Seoul clinic chains. The national regulator's framework for software-controlled treatment parameters creates first-mover advantages for compliant platforms. Busan-Ulsan and Daegu-Gyeongbuk medical aesthetic centers standardize combination protocols across practitioner skill levels using embedded spectral analysis systems.
Beauty Devices Market Key Industry Players
Capability concentration sits with specialized laser and RF engineering houses; scale advantage sits with diversified aesthetic platform vendors. The vendor base separates into three functional tiers: legacy energy device manufacturers with installed base monetization strategies, emerging AI-software integrators seeking regulatory moats, and contract manufacturers serving private-label home-use brands. Competitive moves center on consumables contract expansion and direct regional service hub establishment to displace third-party maintenance networks.
Within the installed-base monetization tier, Lumenis and Alma Lasers exemplify recurring revenue architectures through consumables and maintenance lock-in. HUIMAIN occupies a position on the hardware-plus-subscription vector that shifts clinic relationships toward multi-year contractual structures. These three entities represent divergent strategic responses to the same margin compression pressure from LED wavelength commoditization at the home-use tier.
| Leading Market Players |
|---|
| Lumenis |
| Alma Lasers |
| HUIMAIN |
| Cutera |
| Venus Concept |
| BTL Aesthetics |
| InMode |
| Zimmer MedizinSysteme |
| Cynosure |
| Others |
Cost & Logistics Intelligence
Shenzhen manufacturing clusters anchor global capacity for LED diode arrays and microcurrent assemblies, concentrating component cost leverage among contract manufacturers serving home-use brands. This geographic density enables rapid cost-down engineering for consumer-tier devices while compressing margin pools for premium hardware vendors competing on clinical validation depth.
Pricing Analysis
Consumables and maintenance contract tiers drive lifetime value capture for capital equipment vendors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared professional platforms from CE-marked clinic systems and unregulated home-use alternatives. Cost compression in LED wavelengths intensifies as mature semiconductor supply chains for 415 nm and 630 nm diodes erode hardware differentiation. Home users exhibit highest price sensitivity; medical aesthetic centers in Germany and Switzerland demonstrate lowest elasticity due to clinical evidence requirements.
Supply Chain Analysis
Upstream feedstock for laser resonator crystals draws from Russia, Kazakhstan, and synthetic growth facilities in the United States. RF electrode assemblies rest on copper and silver-plated conductor supplies concentrated in Chinese and German metalworking centers. Single-source vulnerability sits with high-purity sapphire substrates for IPL flashlamps sourced primarily from Ukrainian and Russian crystal growers. Distribution runs through authorized dealer networks for professional-grade platforms and direct-to-consumer e-commerce for home-use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-powered treatment parameter control represents a high-growth disruption, with FDA software-as-medical-device guidance evolution creating regulatory moats that reshape competitive viability for algorithm-dependent platforms.
For Market Incumbents: Build regulatory moats through FDA software-as-medical-device pre-submissions for AI-controlled energy delivery systems. Deepen backward integration into laser resonator crystal supply to offset Ukrainian and Russian sourcing concentration. Prioritize consumables contract expansion to lock clinic clients into multi-year maintenance dependencies that resist LED commoditization pressure. For New Entrants and Emerging Players: Pursue white-space positioning in outcome-linked financing structures for clinic chains in Brazil and Mexico where capital constraints outpace traditional credit availability. Target lease-based hardware access models for independent medical aesthetic centers in France and Italy facing credit facility limitations. Anchor go-to-market execution through direct regional service hub establishment that displaces third-party maintenance networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified aesthetic platform vendors with installed base monetization capabilities over pure-play hardware manufacturers. Long-term viability hinges on recurring revenue architecture rather than transactional equipment sales. Monitor FDA draft guidance finalization timelines as the critical inflection signal for algorithm-controlled treatment platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Establishes regulatory moat for AI-controlled laser parameter systems against unvalidated competitors. |
| Direct Regional Service Hub Establishment | Displaces third-party maintenance networks and captures recurring consumables revenue from clinic installed bases. |
| Hardware-Plus-Subscription Bundling | Shifts clinic relationships from transactional purchases to multi-year contractual structures in tier-one Chinese cities. |
| Backward Integration into Laser Crystal Supply | Reduces dependency on Ukrainian and Russian sapphire substrate sources for IPL flashlamp manufacturing. |
| Outcome-Linked Financing Structure Launch | Addresses acute capital constraints among São Paulo corridor clinic formations outpacing traditional credit availability. |
Research Approach
Desk research of FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, and NMPA medical device registration filings preceded structured interviews with dermatology clinic procurement directors, biomedical engineering leads at hospital systems, and regulatory affairs specialists at energy-based device manufacturers. Primary fieldwork with GPO contracts managers and medical aesthetic center operators combined with secondary validation against customs import records and SEC equipment vendor filings. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from installed base analysis.
Assumptions held fixed include regulatory pathway timelines for FDA software-as-medical-device guidance evolution and NMPA local testing mandate persistence, while tariff exposure and semiconductor supply chain disruption probability were varied across sensitivity scenarios. The analytical framework modeled product type, technology modality, application indication, and end-user procurement authority dimensions across the projection horizon. CAGRs were computed from segment-level growth trajectory synthesis incorporating clinic formation rates, home-use adoption curves, and upgrade cycle compression patterns.
Macroeconomic conditions sit as an overlay; deviation in medical aesthetic center credit availability, consumer discretionary spending on home-use devices, or cross-border regulatory reciprocity agreements would shift the trajectory. Forecasts reflect documented assumptions regarding AI treatment control validation standards and LED component cost-down engineering pace. Cross-checking against hospital capital equipment procurement databases and clinic management system adoption metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Medicated Personal Care Products Market
Beauty & Personal Care
Hair Removal Epilator Market
Beauty & Personal Care
Hair Conditioner Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Salon Service Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Skin Care Luxury Cosmetic Market
Beauty & Personal Care
Hand Soap in Retail Market
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
Philippines Beauty & Personal Care Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
Japan Beauty and Personal Care Products Market
Beauty & Personal Care
Natural Deodorant Crystal Market
Beauty & Personal Care
United States Bath Soap Market