
 E-Pharmacy Beauty and Personal Care (BPC) Market | 2026-2036
E-Pharmacy Beauty and Personal Care (BPC) Market Size, Share, and Industry Trends Forecast 2026-2036
E-Pharmacy Beauty and Personal Care (BPC) Market Analysis
Online pharmacy distribution is fragmenting as legacy drugstore chains, mass retailers, and pure-play digital health platforms compete for the same beauty and personal care shopper. CVS Health leverages its pharmacy benefit infrastructure to bundle prescription adherence with skincare replenishment programs. Walgreen Company sustains neighborhood pickup density that defends its position against delivery-only entrants. Walmart Inc. anchors its BPC assortment within broader grocery baskets, extracting higher order values through cross-category bundling.
E-Pharmacy Beauty and Personal Care encompasses cosmeceuticals, dermatologist-recommended skincare, and over-the-counter personal grooming products sold through licensed digital pharmacy platforms, typically requiring cold-chain or temperature-stable logistics for active-ingredient integrity. Its primary commercial purpose bridges regulated health-adjacent distribution with consumer self-care, capturing shoppers who trust pharmacy credentials over general e-commerce for sensitive-skin formulations. Skincare dominates current revenue pools due to higher per-unit prices and repeat purchase frequency, while haircare competes on subscription-model retention among platform-loyal customers. Mobile Apps represents the fastest-growing distribution channel as pharmacy operators rebuild native interfaces for one-tap reordering and telehealth-integrated skin consultations.
FDA oversight of cosmetic safety claims and EPA registration for certain antimicrobial personal care ingredients shape product eligibility for pharmacy shelves, forcing digital platforms to verify supplier compliance before listing. The EU's MDR and REACH frameworks extend these requirements for cross-border sellers, raising documentation burdens for American and European operators alike. Stakeholders must monitor whether emerging state-level pharmacy compounding rules will restrict certain active-ingredient concentrations sold online, as regulatory fragmentation between jurisdictions threatens unified assortment planning.
Market Dynamics
Mobile-first pharmacy platforms are compressing the path between dermatological consultation and product fulfillment, collapsing what was once a multi-day prescription journey into same-hour delivery loops that lock in repeat purchase behavior.
Growth Catalysts
- CDSCO labeling mandates:India's tightened cosmetic disclosure rules force offline inventory into compliant digital channels, expanding platform-assured product availability.
- Cold-chain logistics maturation:Temperature-stable last-mile networks now protect retinol and peptide integrity, opening previously restricted active-ingredient categories to postal delivery.
- Telehealth integration:Dermatology consultations embedded within pharmacy apps convert clinical recommendations directly into shoppable SKUs without platform switching.
Market Restraints
- API concentration risk:Bulk pharmaceutical ingredient sourcing clusters in specific manufacturing zones, exposing finished goods to single-point supply disruption.
- REACH documentation burdens:EU chemical safety filings impose fixed compliance costs that disproportionately burden smaller cross-border sellers.
- Refrigerated last-mile cost structure:Gel-based and probiotic formulations require controlled logistics that inflate per-unit fulfillment economics versus ambient-stable alternatives.
Strategic Opportunities
- Tier-2 Indian city penetration:Pharmacy apps now achieve sub-two-hour delivery in Lucknow and Indore, capturing first-mover loyalty before infrastructure saturation.
- Subscription model expansion:Recurring replenishment programs for chronic skin conditions generate predictable revenue streams with lower customer acquisition costs than episodic purchase.
- AI-driven skin diagnostics:Computer vision tools that analyze user-submitted photographs create personalized regimen recommendations that lift average order values through bundled product suggestions.
Industry Challenges
- Regulatory fragmentation across state pharmacy boards:Compounding rules for active-ingredient concentrations vary by jurisdiction, complicating unified national assortment planning.
- Integration complexity with legacy ERP systems:Established drugstore chains struggle to synchronize inventory visibility between physical shelves and digital storefronts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Pharmacy Beauty and Personal Care (BPC) Market |
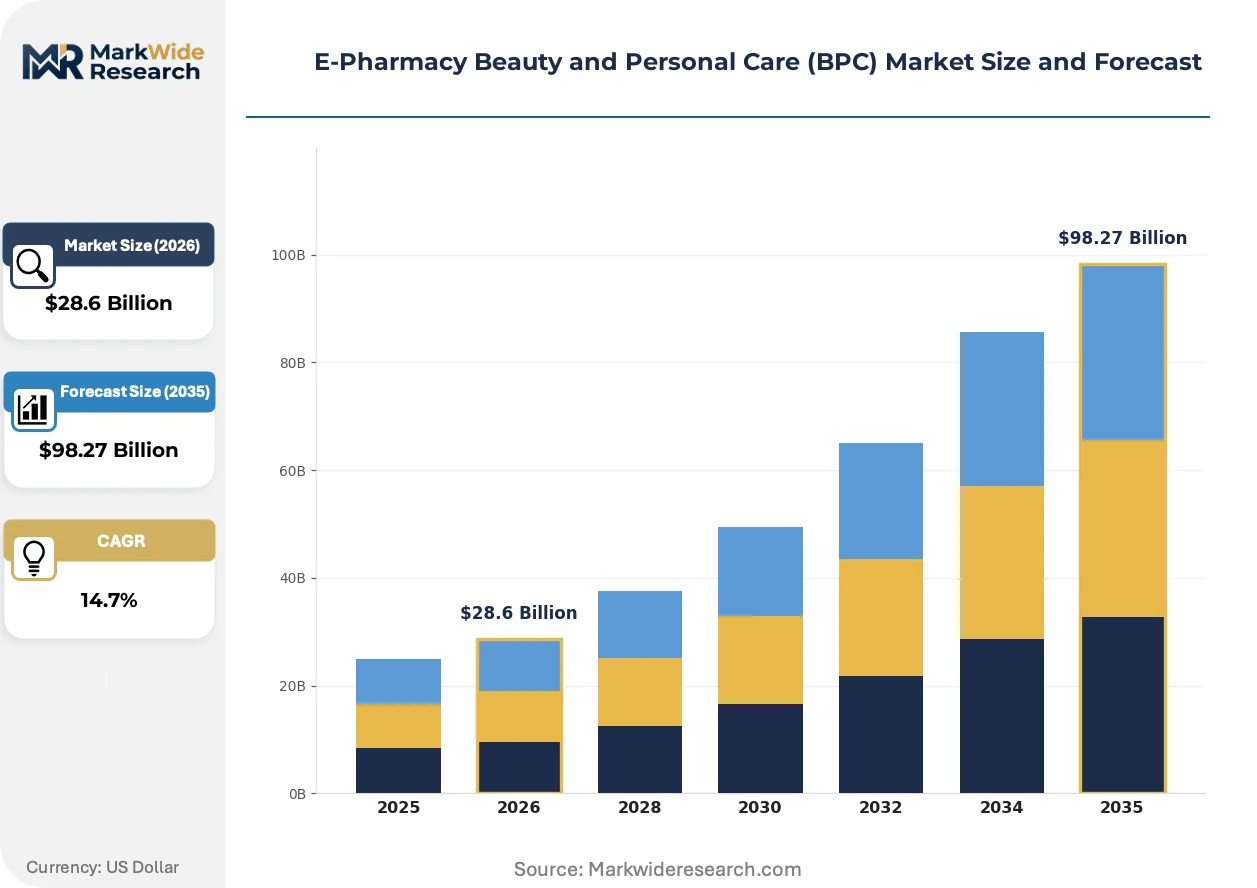
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $98.27 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Make-up, Fragrance Distribution Channel: Online Retail, Social Media, Mobile Apps, Direct Sales Customer Type: Millennials, Gen Z, Working Professionals, Seniors Formulation: Cream, Serum, Gel, Spray |
| Companies Covered | CVS Health, Walgreen Company, The Kroger Co., Walmart Inc., DocMorris, Lloyds Pharmacy Limited, Rowlands Pharmacy, Express Scripts Holding Company, Giant Eagle Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Pharmacy Beauty and Personal Care (BPC) Market Emerging Trajectories
Digital pharmacy platforms are rewiring how consumers access regulated beauty products, replacing the traditional counter consultation with algorithmic personalization and on-demand logistics that collapse the gap between clinical advice and commercial transaction.
Prescription-strength retinoids and azelaic acid formulations are migrating from clinic-exclusive distribution to direct-to-consumer pharmacy channels. Dermatology patients in urban India and the United States now initiate treatment through app-based consultations rather than office visits. This shift is compressing the addressable market for traditional medi-spa dispensing while expanding unit volumes through lower-friction repurchase pathways.
India's CDSCO has mandated expanded ingredient disclosure on cosmetic labels, including fragrance allergens and nanomaterial presence. Domestic pharmacy platforms must now verify supplier documentation before listing, raising barriers for unbranded imports. Compliance-forward operators are capturing shelf space as generalist marketplaces retreat from regulated categories.
Subscription-based replenishment now dominates retention strategy for chronic-condition skincare. Platform-loyal customers in tier-2 Indian cities auto-reorder ceramide moisturizers and sunscreen through one-tap interfaces. This behavior concentrates purchase frequency within native pharmacy apps, displacing browser-based shopping and third-party affiliate traffic.
E-Pharmacy Beauty and Personal Care (BPC) Market Segmentation
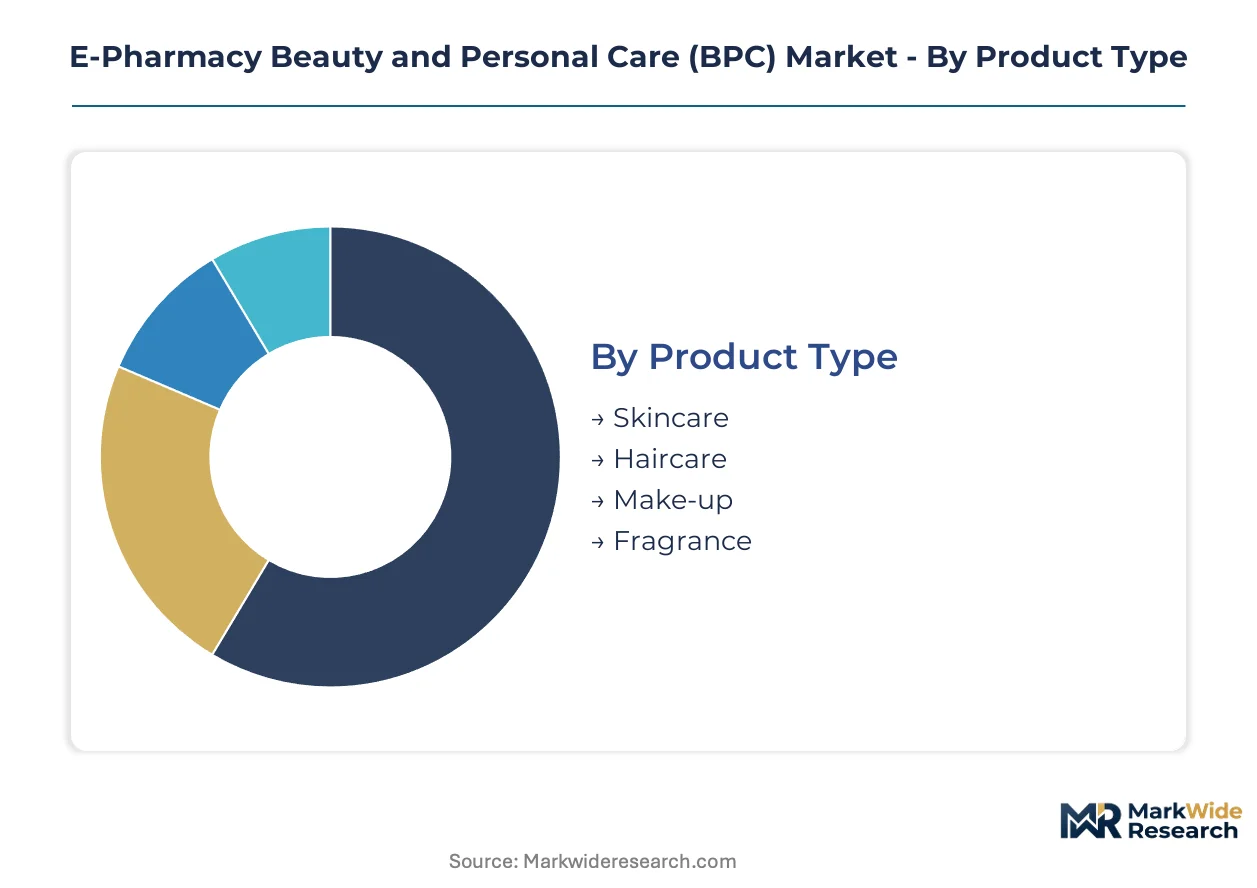
Segmentation in the E-Pharmacy BPC market reveals how pharmacy platforms must architect distinct logistics, pricing, and engagement models for each product type and channel. Understanding these divides separates operators who capture repeat pharmacy-loyal customers from those competing as undifferentiated generalist retailers.
Product Type:
Mature cosmeceutical categories coexist with emerging digital-native formats as pharmacy platforms calibrate inventory depth against prescription-adjacent credibility requirements.
- Skincare:Dermatologist-recommended formulations including retinoids, peptides, and ceramide-based barrier repair products dominate pharmacy platform revenue through higher per-unit pricing and chronic-condition repeat purchase cycles. Demand concentrates among urban millennials in India's tier-2 cities where pharmacy apps now deliver temperature-sensitive active-ingredient products within two hours, though cold-chain logistics costs constrain margin expansion for gel-based and probiotic formulations.
- Haircare:Subscription-model retention programs for anti-dandruff shampoos, minoxidil solutions, and scalp treatments generate predictable recurring revenue with lower customer acquisition costs than episodic purchase patterns. Working professionals in metropolitan India auto-reorder through one-tap native app interfaces, displacing browser-based shopping and third-party affiliate traffic.
- Make-up:Pharmacy-listed color cosmetics carry stricter documentation burdens under CDSCO labeling mandates for fragrance allergens and nanomaterial presence, raising barriers for unbranded imports.
- Fragrance:Personal scents represent lower pharmacy platform penetration due to limited prescription adjacency and ambient-stable logistics requirements that attract generalist marketplace competition.
Skincare retains volume leadership; haircare holds the steepest expansion curve through subscription mechanics.
Distribution Channel:
Channel economics diverge sharply between high-touch native platforms and lower-friction social discovery pathways.
- Mobile Apps:Native pharmacy interfaces with one-tap reordering, telehealth-integrated skin consultations, and embedded AI-driven diagnostics capture platform-loyal customers through personalized regimen recommendations that lift average order values. India's pharmacy operators rebuilt these interfaces specifically for dermatology-to-fulfillment compression, collapsing multi-day prescription journeys into same-hour delivery loops.
- Online Retail:Browser-based pharmacy storefronts serve price-comparison shoppers and first-time buyers with broader assortment visibility but lower retention rates than app-native users.
- Social Media:Influencer-driven discovery channels convert awareness into pharmacy-platform transactions through shoppable content, though attribution complexity challenges loyalty program integration.
- Direct Sales:Telehealth consultation outcomes that route directly to pharmacy fulfillment bypass traditional clinic dispensing, expanding unit volumes through lower-friction repurchase pathways.
Mobile apps command the highest customer lifetime value; social media offers the lowest acquisition friction for new user pools.
Customer Type:
Generational and occupational segments demand distinct platform capabilities from AI personalization to simplified senior interfaces.
- Millennials:Urban mobile-first purchasers drive current online skincare volume through pharmacy apps that bundle prescription adherence with beauty replenishment programs.
- Gen Z:Digital-native consumers initiate treatment through app-based dermatology consultations rather than office visits, compressing the addressable market for traditional medi-spa dispensing.
- Working Professionals:Time-constrained auto-reorder behavior concentrates within native pharmacy apps through subscription programs for chronic-condition skincare regimens.
- Seniors:Pharmacy-credibility-dependent shoppers trust regulated distribution for sensitive-skin formulations but require simplified interfaces and assisted telehealth onboarding.
Millennials anchor current revenue contribution; Gen Z is climbing the fastest through consultation-first purchase behavior.
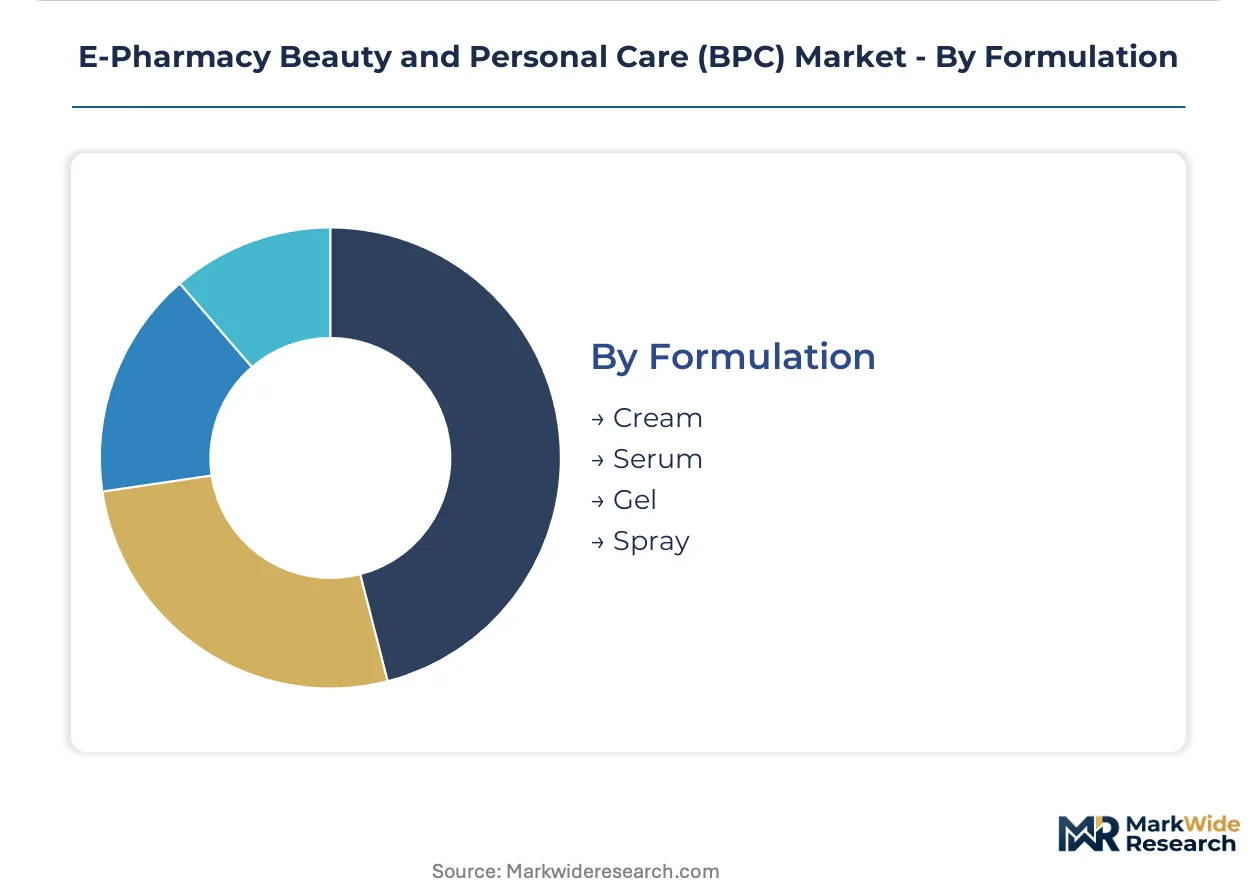
Formulation:
Physical product state determines logistics infrastructure requirements and regulatory documentation intensity across pharmacy networks.
- Cream:Temperature-stable emulsions with broad ambient distribution compatibility and established CDSCO documentation pathways dominate mass-market pharmacy listings.
- Serum:High-concentration active-ingredient formulations including retinol and peptide solutions require cold-chain integrity protection, opening previously restricted categories to postal delivery as last-mile networks mature.
- Gel:Water-based carriers for acne treatments and soothing formulations demand controlled logistics that inflate per-unit fulfillment economics versus ambient-stable alternatives.
- Spray:Aerosol and pump-dispensed products face EPA registration requirements for antimicrobial claims and compressed-gas shipping restrictions that shape product eligibility for pharmacy shelves.
Cream formulations retain volume leadership; serums gain share fastest through cold-chain logistics maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO labeling mandates in India are reshaping how pharmacy platforms verify supplier documentation before listing cosmetic products, creating compliant digital channels that expand platform-assured availability across multiple continents.
United States
Urban millennials drive online skincare volume through mobile-first pharmacy apps that bundle prescription adherence with beauty replenishment programs. FDA oversight of cosmetic safety claims forces digital platforms to verify supplier compliance before listing sensitive-skin formulations. Dermatology patients in metropolitan clusters now initiate treatment through app-based consultations rather than office visits, compressing traditional medi-spa dispensing timelines.
India
Tier-2 city demand concentrates in Lucknow and Indore where pharmacy apps achieve sub-two-hour delivery of regulated beauty products. CDSCO mandates expanded ingredient disclosure including fragrance allergens and nanomaterial presence, raising barriers for unbranded imports. Compliance-forward operators capture shelf space as generalist marketplaces retreat from regulated categories.
Germany
Working professionals auto-reorder chronic-condition skincare regimens through subscription programs that generate predictable recurring revenue. EU REACH documentation burdens impose fixed compliance costs that disproportionately burden smaller cross-border sellers. DocMorris anchors telehealth-integrated fulfillment networks that convert clinical recommendations directly into shoppable SKUs.
United Kingdom
Pharmacy-credibility-dependent shoppers trust regulated distribution for sensitive-skin formulations requiring simplified senior interfaces. Lloyds Pharmacy Limited and Rowlands Pharmacy sustain neighborhood pickup density that defends position against delivery-only entrants. London and Southeast England clusters concentrate platform-loyal customers who auto-reorder through one-tap native app interfaces.
China
Cold-chain logistics maturation protects retinol and peptide integrity, opening previously restricted active-ingredient categories to postal delivery. NMPA registration requirements shape product eligibility for pharmacy shelves, forcing verification of supplier compliance before listing. Yangtze River Delta manufacturing zones expose finished goods to single-point supply disruption risks that operators must hedge through diversified sourcing.
E-Pharmacy Beauty and Personal Care (BPC) Market Vendor Landscape
Legacy drugstore chains and mass retailers split the market against pure-play digital health platforms competing for the same beauty and personal care shopper. Consolidation pressures intensify as pharmacy operators rebuild native interfaces for one-tap reordering and telehealth-integrated skin consultations. Three archetypes dominate: vertically integrated pharmacy-benefit managers, grocery-anchored cross-category bundlers, and telehealth-native fulfillment specialists. Competitive moves center on M&A to capture telehealth capabilities and strategic partnerships to secure cold-chain logistics capacity.
Among US-based pharmacy-benefit managers, CVS Health and Express Scripts Holding Company exemplify the vertically integrated archetype that bundles prescription infrastructure with skincare replenishment programs. Walgreen Company and Walmart Inc. anchor the mass-retail tier, with the former defending neighborhood pickup density and the latter extracting higher order values through cross-category grocery bundling. These four entities occupy positions that reflect divergent bets on consultation-to-fulfillment compression versus physical convenience retention.
| Leading Market Players |
|---|
| CVS Health |
| Walgreen Company |
| The Kroger Co. |
| Walmart Inc. |
| DocMorris |
| Lloyds Pharmacy Limited |
| Rowlands Pharmacy |
| Express Scripts Holding Company |
| Giant Eagle Inc. |
| Others |
Supply Flow & Price Mechanics
Last-mile cold-chain corridors from Mumbai to Lucknow and Indore compress fulfillment windows while inflating per-unit logistics costs, concentrating pricing power among operators who have secured temperature-stable capacity. CDSCO compliance documentation adds fixed overhead that widens the spread between verified pharmacy-platform pricing and generalist marketplace alternatives.
Pricing Analysis
Configured-to-order dermatology consultations command premium spreads over standard replenishment pricing, with telehealth-integrated skin diagnostics lifting average order values through bundled regimen recommendations. Three-tier pricing structure across premium, standard, and economy levels separates prescription-strength retinoids from mass-market ceramide moisturizers and unbranded imports. Price differentiation rests on CDSCO certification status and cold-chain delivery guarantees. Cost compression in ambient-stable haircare subscriptions is intensifying because platform-loyal auto-reorder behavior concentrates volume within native apps. Working professionals in India's tier-2 cities demonstrate lowest price sensitivity for same-hour delivery, while browser-based price-comparison shoppers drive softness in online retail channels.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk planning for peptide and retinol active-ingredient sourcing. API manufacturing concentrates in China's Yangtze River Delta and India's Hyderabad-Visakhapatnam corridor, with secondary capacity in Germany's Rhine-Ruhr pharmaceutical cluster. Raw material dependencies span bulk pharmaceutical ingredients, specialized cold-chain packaging, and temperature-monitoring IoT sensors. Single-source vulnerability persists for probiotic formulations requiring controlled logistics. Distribution runs through pharmacy-benefit managers and telehealth-native fulfillment specialists, with mass retailers anchoring cross-category grocery bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth-integrated dermatology platforms are compressing consultation-to-fulfillment timelines, creating high-growth disruption as CDSCO labeling mandates force offline inventory into compliant digital channels.
For Market Incumbents: Entrench platform loyalty through one-tap reordering interfaces and subscription-model retention programs that lock in chronic-condition skincare customers. CVS Health and Walgreen Company should deepen backward integration into cold-chain logistics capacity to defend margin position against delivery-only entrants. Telehealth-native specialists threaten prescription-adjacent credibility advantages unless legacy operators accelerate AI-driven skin diagnostic deployment. For New Entrants and Emerging Players: Pursue tier-2 Indian city penetration in Lucknow and Indore where sub-two-hour delivery infrastructure remains undersaturated. Compliance-forward positioning captures shelf space as generalist marketplaces retreat from CDSCO-regulated categories. Go-to-market execution should anchor on dermatologist partnership networks that convert clinical recommendations directly into native app transactions. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy drugstore chains struggling to synchronize inventory visibility between physical shelves and digital storefronts. Long-term viability across the analysis window favors telehealth-native fulfillment specialists with captive cold-chain capacity. Watch for state-level pharmacy compounding rule fragmentation as the signal forcing unified assortment planning revisions.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | CVS Health and DocMorris collapse prescription journeys into same-hour delivery loops. |
| Cold-Chain Logistics Partnership | Walgreen Company secures temperature-stable capacity for retinol integrity protection. |
| AI-Driven Skin Diagnostic Launch | Computer vision tools lift average order values through bundled regimen recommendations. |
| Subscription Model Expansion | Platform-loyal auto-reorder behavior concentrates purchase frequency within native apps. |
| CDSCO Compliance Certification | Forward operators capture shelf space as generalist marketplaces retreat from regulated categories. |
Methodological Framework
Operator-level perspectives from pharmacy platform executives, dermatology telehealth leads, cold-chain logistics directors, CDSCO regulatory affairs specialists, and tier-2 city operations managers anchored the qualitative base. Secondary validation drew from CDSCO cosmetic labeling filings, FDA cosmetic safety claim registrations, EU REACH documentation databases, pharmacy app download and engagement metrics, and customs trade data for active-ingredient imports. Bottom-up unit economics modeling and top-down market sizing triangulation cross-verified volume and value estimates.
Scenario-bracketing framed optimistic, baseline, and conservative growth paths across the projection horizon. Segmentation dimensions modeled included product type, distribution channel, customer generation, formulation state, and regional regulatory cluster. CAGRs derived from compounded annual growth trajectory analysis incorporating telehealth penetration curves, cold-chain logistics cost deflation, and subscription-model retention coefficients.
Sensitivities concentrate around CDSCO enforcement intensity, state-level pharmacy compounding rule fragmentation, and cold-chain logistics capacity bottlenecks. Forecasts reflect documented assumptions regarding telehealth adoption velocity and platform loyalty concentration. Material shifts in India's tier-2 city infrastructure buildout or active-ingredient API supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Natural Hair Care Product Market
Beauty & Personal Care
Saudi Arabia Body Care and Personal Hygiene Market
Beauty & Personal Care
Bar Soap Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
DIY Haircut Kits Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
BB Cushions Market
Beauty & Personal Care
Deodorant & Anti-Perspirant Market
Beauty & Personal Care
Organic Baby Shampoo Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Europe Cosmetics Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Asia-Pacific Bath and Shower Products Market
Beauty & Personal Care
Hairstyling Products Market