
 Hair Removal Creams for Private Parts Market | 2026-2036
Hair Removal Creams for Private Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Removal Creams for Private Parts Market Insights
ISO 22716 Good Manufacturing Practices for cosmetics is rotating as the baseline qualification for private-label and contract manufacturers seeking entry into intimate-care formulations. Reckitt Benckiser leverages its Veet brand infrastructure to sustain shelf dominance across mass retail and pharmacy channels in Western Europe. Church & Dwight anchors its Nair portfolio through specialized variants engineered for sensitive skin zones, competing on dermatologist endorsement rather than price alone.
Hair removal creams for private parts are topical depilatory formulations containing thioglycolate salts or calcium hydroxide that chemically reduce disulfide bonds in keratin, enabling wipe-away hair elimination without mechanical extraction. These products incorporate pH buffers between 11.5 and 12.5 to maintain efficacy while minimizing epidermal irritation in mucosal-adjacent skin areas. The ingredient type dimension shows natural botanical extracts gaining share as consumers reject traditional chemical actives, though hypoallergenic certifications command premium positioning in pharmacy and clinic channels. Cream formulations dominate unit volume due to familiar application rituals, while gel textures capture faster growth among male-identifying users seeking non-drip precision.
FDA oversight of cosmetic safety through the Federal Food, Drug, and Cosmetic Act requires adverse event reporting for depilatory products, while REACH registration in Europe mandates full chemical disclosure for thioglycolate compounds above threshold volumes. These frameworks elevate compliance costs for new entrants but simultaneously protect incumbent positions by raising technical barriers. Stakeholders must monitor evolving state-level legislation on intimate care product labeling transparency, as California's Safer Consumer Products program signals broader regulatory momentum that will reshape formulation roadmaps and supply chain documentation requirements.
Market Dynamics
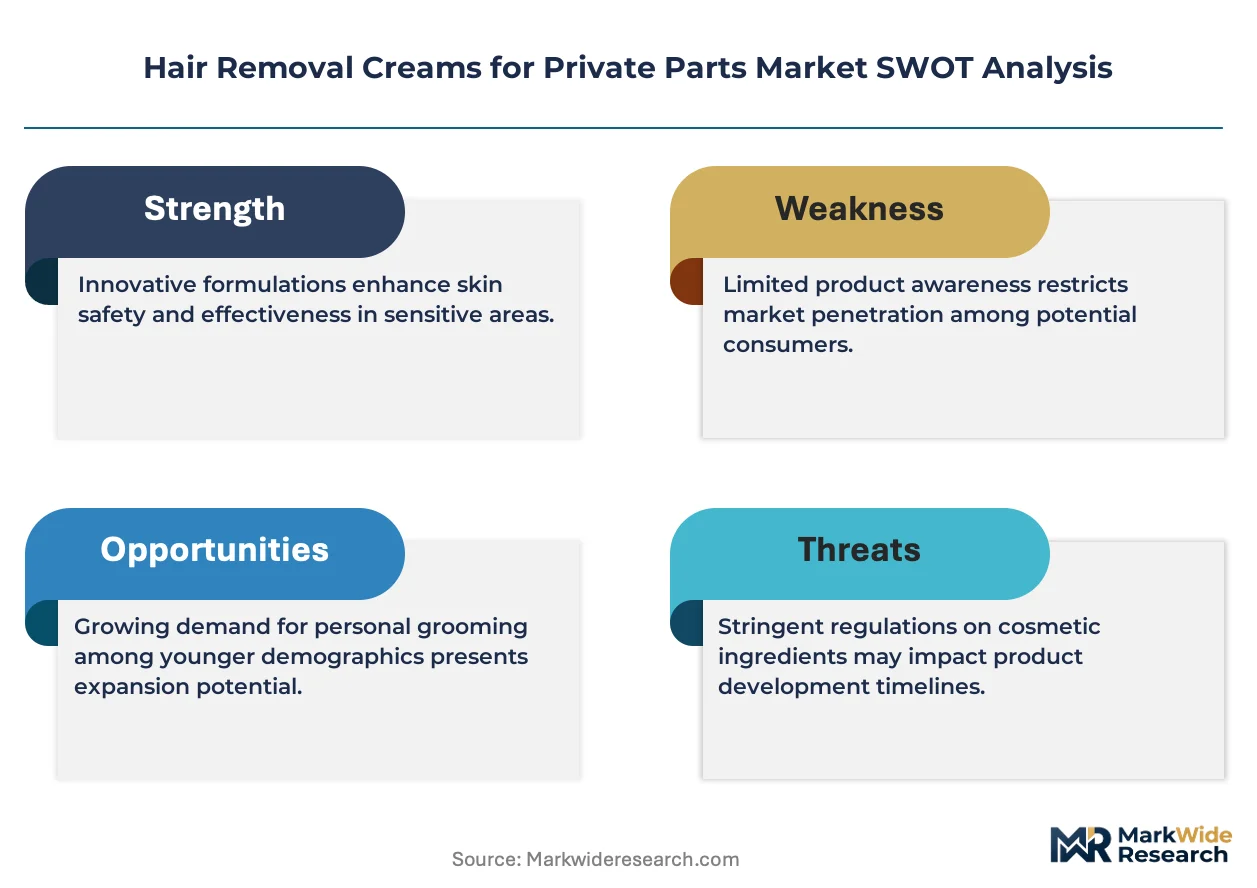
REACH registration mandates for thioglycolate compounds are elevating technical barriers across European supply chains, forcing smaller formulators to consolidate or exit while ISO 22716 certification becomes the non-negotiable entry ticket for private-label manufacturing contracts.
Growth Catalysts
- Gen Z channel migration:Direct-to-consumer platforms capture volume as younger demographics bypass traditional retail for subscription-based intimate care regimens.
- REACH compliance differentiation:Full chemical disclosure requirements protect incumbent positions by raising capital thresholds for new market entrants.
- Botanical extract substitution:Natural pH buffers derived from aloe and chamomile displace synthetic stabilizers in premium pharmacy-tier formulations.
Market Restraints
- Thioglycolate input volatility:Petrochemical feedstock fluctuations compress margin predictability for mid-tier contract manufacturers dependent on spot purchasing.
- European supply concentration:Specialty chemical production for depilatory actives clusters in Germany and the Netherlands, creating single-source vulnerability.
- Substitution by laser devices:At-home IPL technology captures permanent hair reduction demand among higher-income urban consumers.
Strategic Opportunities
- Brazilian market underpenetration:Cultural grooming norms in São Paulo and Rio de Janeiro drive pharmacy-channel expansion for dermatologist-endorsed sensitive-skin variants.
- California labeling transparency:The Safer Consumer Products program signals state-level momentum that rewards early compliance with multi-jurisdiction documentation systems.
- Telehealth convergence:Virtual dermatology consultations create prescription-adjacent distribution channels for clinically positioned depilatory kits.
Industry Challenges
- Formulation chemist scarcity:Expertise in mucosal-adjacent pH balancing commands premium compensation, constraining R&D throughput for emerging brands.
- ISO 22716 certification timelines:Eighteen-month qualification cycles delay private-label contract wins for manufacturers lacking pre-existing intimate-care GMP infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Removal Creams for Private Parts Market |
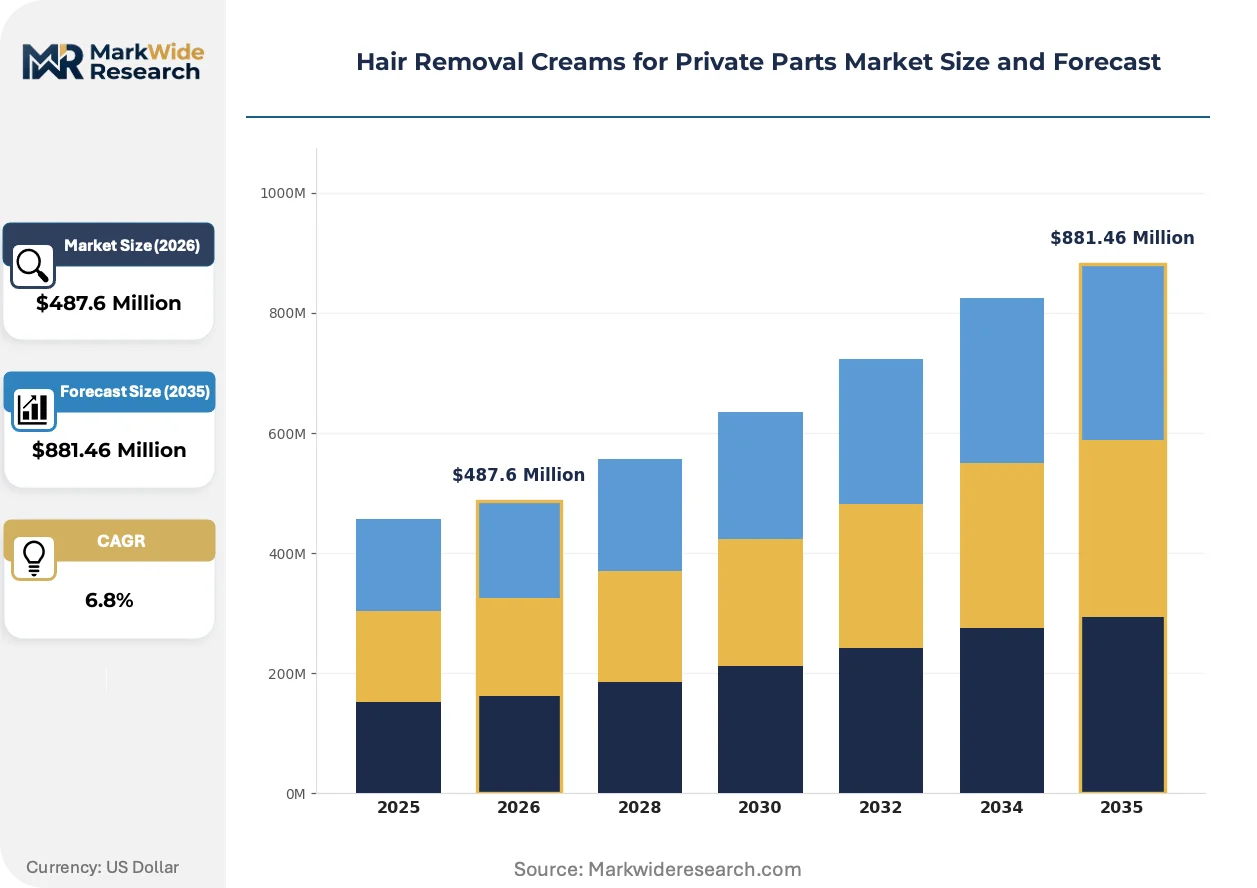
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Gel, Foam, Lotion Ingredient Type: Natural, Chemical, Hypoallergenic, Moisturizing Application Method: Topical, Wipe, Sprayer, Brush Target Gender: Female, Male, Unisex, Others |
| Companies Covered | SI&D (Aust) Pty Ltd - Nad's Hair Removal, Dabur India Ltd., Reckitt Benckiser (Veet), HCP Wellness Private Limited, Jolen Inc., Church & Dwight (Nair), Procter & Gamble, Sirona Hygiene Private Limited, Sally Hansen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Removal Creams for Private Parts Market Trends and Innovations
Formulation science is pivoting toward biomimetic keratin management as consumer tolerance for traditional alkaline depilation erodes, while regulatory disclosure requirements and channel fragmentation simultaneously reshape competitive entry economics.
Microencapsulated thioglycolate delivery systems are fragmenting conventional cream-gel taxonomy by enabling time-release alkalinity that reduces epidermal exposure duration. Male-identifying users in the United States and India adopt these precision formats fastest, demanding non-drip application control. The technology is fragmenting established texture preferences and opening dedicated men's grooming sub-lines previously subsumed within unisex portfolios.
REACH Article 33 extended SCIP database obligations now mandate supply chain communication on thioglycolate presence in articles, not just substances in isolation. This disclosure cascade forces reformulation roadmaps for brands serving EU markets. Small and mid-sized private-label manufacturers face documentation burdens that favor vertically integrated competitors with captive regulatory affairs functions.
Subscription replenishment models displace pharmacy impulse purchasing among millennial cohorts in the United States and United Kingdom. Direct-to-consumer platforms capture recurring revenue through personalized skin-sensitivity questionnaires that algorithmically match formulation strength to user profiles. This behavioral shift concentrates customer lifetime value with data-capable brands while eroding traditional retail slotting fee economics.
Hair Removal Creams for Private Parts Market Segmentation
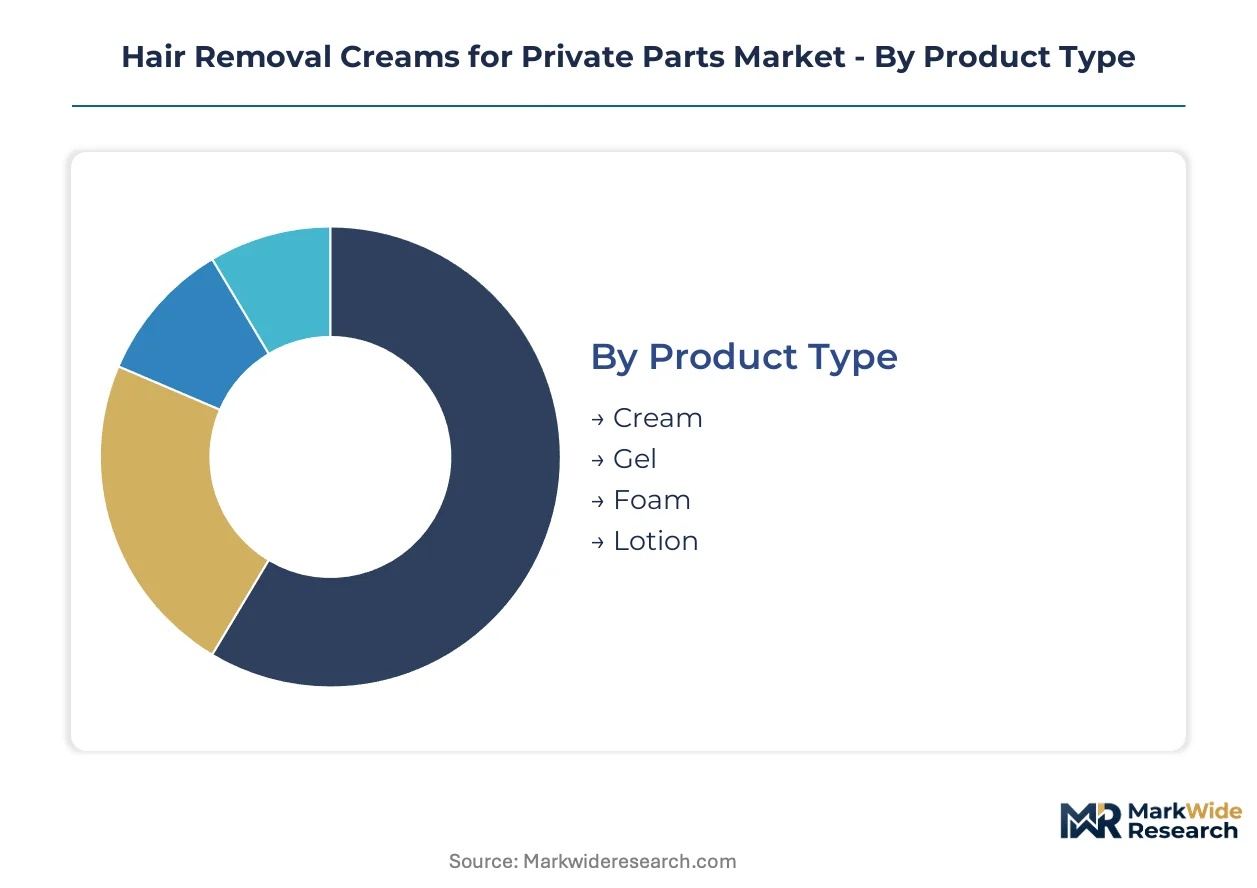
Depilatory formulations for intimate zones fragment across texture, chemistry, and application mechanics that determine channel placement and pricing architecture. Understanding segment boundaries reveals where formulation investment concentrates versus where private-label commoditization dominates.
Product Type:
Cream and gel formats command pharmacy and direct-to-consumer channels respectively, while foam and lotion variants occupy divergent retail tiers with distinct margin profiles.
- Cream:Thioglycolate-based emulsions with pH buffers between 11.5 and 12.5 dominate mass retail shelf space through familiar application rituals. United States pharmacy chains sustain volume concentration for sensitive-skin variants endorsed by dermatology clinics.
- Gel:Viscous formulations incorporating carbomer thickeners enable precision application without drip, capturing male-identifying users in India and the United States through subscription direct-to-consumer platforms. Non-drip control drives fastest expansion among younger demographics bypassing traditional retail.
- Foam:Aerosol-dispensed formats with propellant systems occupy economy-tier mass merchant channels in Brazil.
- Lotion:Lower-viscosity fluids with extended spreadability target price-sensitive volume in Indian general trade.
By volume, cream leads. By growth pace, gel is expanding most quickly.
Ingredient Type:
Cost tiers stratify sharply between petrochemical-derived actives and botanical-positioned premium lines, with certification grades determining pharmacy access.
- Natural:Botanical extracts from aloe vera and chamomile displace synthetic stabilizers in formulations targeting EU markets where REACH disclosure requirements elevate consumer scrutiny. Pharmacy-tier pricing in Germany and the Netherlands rewards full ingredient transparency.
- Chemical:Thioglycolate salts and calcium hydroxide remain the workhorse depilatory chemistry for mass-market penetration across Brazilian and Indian retail, though margin compression from feedstock volatility constrains mid-tier manufacturers.
- Hypoallergenic:Dermatologist-tested certifications command premium positioning in clinic-adjacent channels.
- Moisturizing:Glycerin-enriched variants capture repeat purchase loyalty in United Kingdom subscription models.
Natural ingredients gain share fastest in premium channels, while chemical actives retain volume dominance in emerging markets.
Application Method:
Customer type divides between ritual-driven repeat users favoring tactile application and convenience-seekers adopting disposable formats.
- Topical:Direct hand-application of cream or gel sustains highest customer lifetime value in subscription replenishment models, where personalized skin-sensitivity questionnaires algorithmically match formulation strength to user profiles in United States and United Kingdom direct-to-consumer platforms.
- Wipe:Pre-saturated towelettes with measured active dosing capture travel and gym-bag occasions in urban United States convenience retail, sacrificing unit economics for impulse accessibility.
- Sprayer:Pump-dispensed formats target male grooming lines seeking reduced contact time.
- Brush:Applicator-included kits command premium in Brazilian pharmacy channels.
Topical application retains the largest installed base, while wipe formats climb the fastest among mobile urban consumers.
Target Gender:
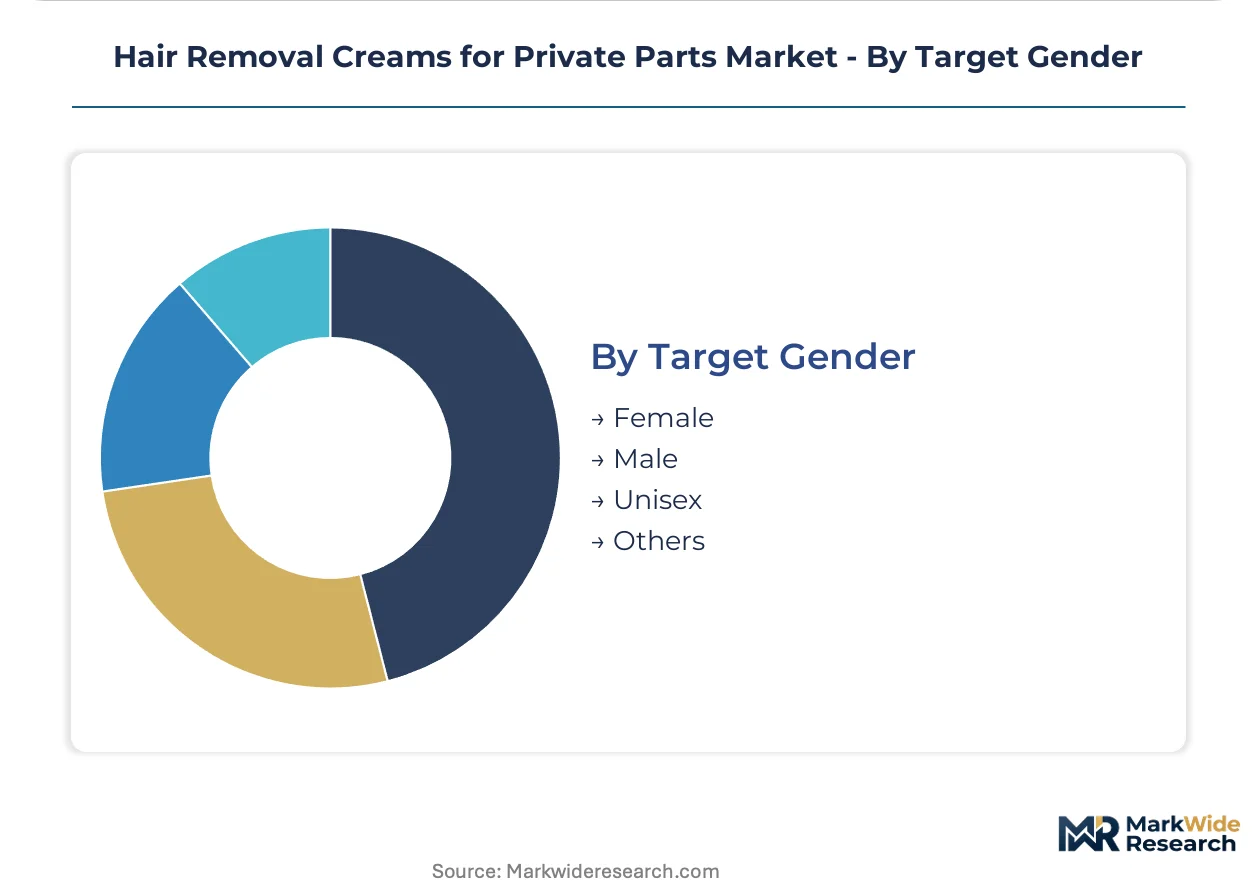
Volume concentration and margin structure diverge between legacy female-skewed retail and emerging male-identified direct-to-consumer growth vectors.
- Female:Established demand concentration in United States and Brazilian pharmacy and mass retail channels sustains the revenue base, though growth rates moderate as market penetration matures.
- Male:Dedicated sub-lines with precision gel formats and subdued fragrance profiles expand fastest in India and United States through digital-native subscription platforms, fragmenting previously unisex portfolios.
- Unisex:Legacy formulations face compression as gender-specific positioning gains traction.
- Others:Non-binary marketing approaches test in United Kingdom direct-to-consumer channels.
Female-targeted products lead by volume, while male-identified segments show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration mandates in Europe and FDA adverse event reporting in the United States are elevating compliance thresholds that favor incumbent manufacturers with captive regulatory affairs functions.
United States
Subscription direct-to-consumer platforms capture millennial and Gen Z volume through algorithmic skin-sensitivity matching. California's Safer Consumer Products program mandates ingredient transparency that exceeds federal baselines. Pharmacy chains in New York and Los Angeles sustain dermatologist-endorsed sensitive-skin variant distribution.
Germany
Specialty chemical production for thioglycolate actives clusters around Ludwigshafen and Leverkusen, creating upstream supply concentration. ECHA REACH enforcement requires full Article 33 SCIP database disclosure on depilatory articles. Berlin and Hamburg direct-to-consumer startups leverage ISO 22716 certification to access pharmacy-tier private-label contracts.
Brazil
Cultural grooming norms in São Paulo and Rio de Janeiro drive pharmacy-channel expansion for premium variants. ANVISA cosmetic safety regulations align with Mercosur harmonization efforts. São Paulo state concentrates both manufacturing and consumption, with local formulators capturing general trade volume through economy-tier foam formats.
India
Male-identifying users adopt precision gel formats fastest through digital-native subscription platforms in Mumbai and Bangalore. BIS cosmetic standards and CDSCO adverse event reporting create dual-track compliance. Gujarat chemical manufacturing clusters supply calcium hydroxide actives to domestic formulators and export markets.
United Kingdom
Subscription replenishment models displace pharmacy impulse purchasing among urban millennials in London and Manchester. MHRA cosmetic safety guidance implements EU-aligned disclosure requirements post-Brexit. London-based direct-to-consumer brands test non-binary marketing approaches in clinic-adjacent channels.
Hair Removal Creams for Private Parts Market Competitive Landscape
Player mix skews toward multinational consumer goods conglomerates with established intimate-care portfolios and ISO 22716-certified contract manufacturers serving private-label demand. Tiered structure separates pharmacy-premium positioning from mass retail economy penetration. Strategic archetypes include dermatologist-endorsed sensitive-skin specialists, botanical-positioned natural formulators, and precision-application technology developers. Dominant competitive moves center on portfolio diversification into gender-specific sub-lines and backward integration into captive thioglycolate supply.
Within the multinational tier, Reckitt Benckiser and Church & Dwight occupy positions that exemplify mass retail and pharmacy-channel differentiation respectively. Among India-based specialists, Dabur India Ltd. and Sirona Hygiene Private Limited represent archetypes of Ayurvedic-positioned natural formulations and direct-to-consumer intimate-care focus. These anchors illustrate how geographic origin and stated portfolio emphasis shape competitive positioning without guaranteeing segment dominance.
| Leading Market Players |
|---|
| SI&D (Aust) Pty Ltd - Nad's Hair Removal |
| Dabur India Ltd. |
| Reckitt Benckiser (Veet) |
| HCP Wellness Private Limited |
| Jolen Inc. |
| Church & Dwight (Nair) |
| Procter & Gamble |
| Sirona Hygiene Private Limited |
| Sally Hansen Inc. |
| Others |
Pricing and Supply Chain Analysis
ISO 22716 Good Manufacturing Practices certification gates both supply qualification and price differentiation simultaneously, as contract manufacturers lacking this baseline credential forfeit pharmacy-tier private-label contracts regardless of cost position. REACH registration in Europe and FDA adverse event reporting in the United States impose parallel compliance burdens that stratify pricing power between incumbent multinationals with captive regulatory affairs and spot-market-dependent mid-tier formulators.
Pricing Analysis
Certification level creates the primary spread between pharmacy-premium and mass-economy tiers. Three-tier pricing structure across premium, standard, and economy levels segments by dermatologist endorsement, hypoallergenic testing depth, and botanical extract concentration. Cost compression in mid-tier chemical-actives runs through thioglycolate feedstock volatility, while subscription-based direct-to-consumer models exhibit lowest price sensitivity due to algorithmic personalization locking in customer lifetime value.
Supply Chain Analysis
Germany and the Netherlands anchor specialty chemical production for thioglycolate actives, with Ludwigshafen and Leverkusen clusters supplying downstream formulators across Western Europe. Gujarat in India feeds calcium hydroxide inputs to domestic manufacturers and export markets. Single-source vulnerability concentrates in European thioglycolate synthesis, where petrochemical feedstock fluctuations transmit directly to margin predictability. Distribution runs through pharmacy chains in developed markets and general trade in emerging economies, with direct-to-consumer platforms capturing fastest-growing subscription volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs customer acquisition as algorithmic skin-sensitivity matching in subscription models creates data moats that traditional retail slotting fees cannot replicate. Interoperability between telehealth dermatology consultations and prescription-adjacent depilatory kit distribution signals ecosystem consolidation ahead.
For Market Incumbents: Shield pharmacy-channel positioning through accelerated ISO 22716 certification acquisition for contract manufacturing partners, denying private-label entry to emerging competitors. Backward integration into captive thioglycolate supply insulates margin predictability against petrochemical feedstock volatility. Defend against at-home IPL substitution by emphasizing dermatologist endorsement in sensitive-skin variants.
For New Entrants and Emerging Players: Anchor in male-identifying precision gel formats through digital-native subscription platforms, where unisex portfolio fragmentation creates white-space expansion. Target São Paulo and Rio de Janeiro pharmacy channels with dermatologist-endorsed variants, as cultural grooming norms outpace supply localization. Exploit California's Safer Consumer Products program by building multi-jurisdiction documentation systems that incumbent legacy infrastructure adapts to slowly.
For Investors and Strategic Acquirers: REACH Article 33 SCIP database obligations reshape the acquisition landscape by favoring vertically integrated competitors with captive regulatory affairs over documentation-burdened private-label manufacturers. Long-term viability centers on brands with algorithmic personalization capabilities and subscription replenishment infrastructure. The signal to watch is telehealth platform partnership announcements that signal prescription-adjacent channel access.
| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Extract Substitution | Aloe and chamomile pH buffers displace synthetic stabilizers in EU pharmacy-tier formulations. |
| Microencapsulated Delivery Systems | Time-release thioglycolate technology fragments cream-gel taxonomy for male precision application. |
| Subscription Platform Integration | Algorithmic skin-sensitivity matching concentrates customer lifetime value with data-capable brands. |
| Telehealth Channel Partnership | Virtual dermatology consultations create prescription-adjacent distribution for clinically positioned kits. |
| Backward Integration into Actives | Captive thioglycolate supply insulates margin predictability from petrochemical feedstock volatility. |
Research Methodology
A spread of perspectives from formulation chemists, pharmacy category buyers, contract manufacturing executives, and regulatory affairs specialists converged on the working assumptions underlying demand and supply trajectories. Primary field engagement with direct-to-consumer platform operators and intimate-care brand managers supplemented secondary validation through FDA adverse event databases, ECHA REACH registration filings, ANVISA cosmetic safety submissions, and BIS standards documentation. Bottom-up unit volume modeling across texture, ingredient, and application segments triangulated against top-down market sizing from trade flow analysis.
Segmentation dimensions modeled include product texture hierarchy, ingredient chemistry tier, application mechanics, target gender positioning, and regional regulatory cluster across the projection horizon. CAGRs derive from trend extrapolation of Gen Z channel migration velocity, botanical extract substitution rates, and male-identified segment penetration. Industry-specific forecast inputs incorporate thioglycolate feedstock price indices and ISO 22716 certification timeline elasticity for contract manufacturer qualification.
Material uncertainties — regulatory disclosure requirement expansion, at-home IPL technology cost curves, and formulation chemist labor market tightness — sit outside the modeled envelope. Forecasts reflect assumptions about sustained direct-to-consumer platform growth and REACH enforcement continuity. Recalibration cycles align with material shifts in state-level labeling transparency legislation and telehealth regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global and North America Organic and Natural Feminine Care Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Hair Straightener Market
Beauty & Personal Care
US Sexual Wellness Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Vanity Mirror Market
Beauty & Personal Care
Anti-Acne Cosmetics Market
Beauty & Personal Care
Philippines Beauty & Personal Care Market
Beauty & Personal Care
United Kingdom Hair Care Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
India Hair Oil Market