
 Organic Shampoo Market | 2026-2036
Organic Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Shampoo Market Analysis
REACH compliance is repositioning the cost-of-entry calculus for new entrants in organic shampoo manufacturing. L'Oréal SA leverages its R&D infrastructure to navigate complex certification requirements across multiple geographies. The Hain Celestial Group Inc. anchors its portfolio in clean-label positioning that resonates with ingredient-conscious consumers. Hindustan Unilever Ltd. competes through extensive distribution networks that penetrate tier-two and tier-three cities in emerging markets.
Organic shampoo denotes a hair cleansing formulation containing at least 95% naturally derived ingredients, excluding synthetic sulfates, parabens, and artificial fragrances, manufactured through cold-process or saponification methods that preserve botanical active compounds. Its primary commercial purpose centers on delivering scalp-compatible cleansing while meeting third-party organic certification standards such as COSMOS or USDA Organic. Hydrating variants dominate volume given their universal applicability across hair textures and climates, while anti-dandruff formulations represent the fastest-growing segment as consumers seek zinc pyrithione alternatives from tea tree oil and salicylic acid sources. Essential oils command premium positioning within ingredient-type segmentation due to their dual functional and aromatic properties, though natural surfactants capture expanding share as formulators replace sodium lauryl sulfate with coco-glucoside and decyl glucoside systems.
EMA guidelines on cosmetic ingredient safety, ECHA REACH registration requirements, and USDA Organic certification standards collectively shape product formulation boundaries and market access conditions for organic shampoo producers. EFSA evaluations of botanical extract safety profiles directly influence which herbal ingredients gain formulation approval in European markets. Stakeholders must monitor evolving definitions of natural versus naturally derived across regulatory jurisdictions, as divergent standards threaten to fragment compliance strategies and complicate global product portfolios.
Market Dynamics
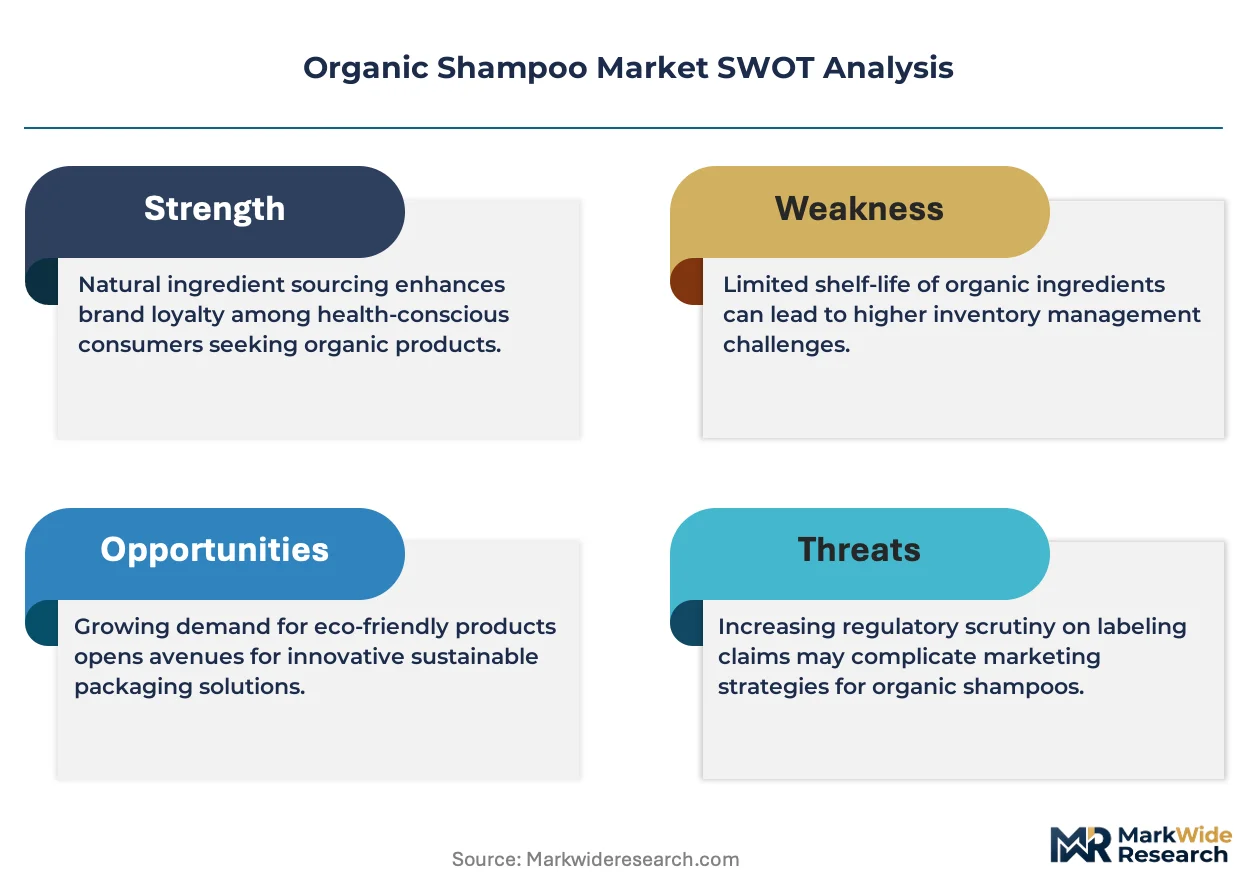
REACH registration requirements are forcing organic shampoo formulators to rebuild supply chains around ECHA-approved botanical inputs, compressing the supplier base and elevating compliance costs for mid-tier manufacturers.
Growth Catalysts
- EU Green Deal chemical transparency mandates:The framework accelerates salon channel conversion to certified organic formulations as professional buyers preempt liability exposure from ingredient disclosure rules.
- Cold-process manufacturing:This method preserves heat-sensitive botanical actives in tea tree oil and salicylic acid systems, enabling functional equivalence to synthetic anti-dandruff agents without zinc pyrithione.
- Germany:The country's COSMOS certification penetration in personal care creates template adoption patterns that spill into neighboring Benelux and Nordic markets.
Market Restraints
- Essential oil price volatility:Lavender and rosemary harvest fluctuations in Provence and Bulgaria destabilize input cost structures for premium positioning variants.
- Natural surfactant supply concentration:Coco-glucoside and decyl glucoside production clusters in Southeast Asia create single-source vulnerability for sulfate-free formulators.
- COSMOS-REACH divergence:Differing definitions of naturally derived versus natural origin across jurisdictions force redundant testing and dual-label packaging.
Strategic Opportunities
- Professional salon channel expansion:Backbar sizing and stylist education programs unlock recurring revenue streams distinct from retail velocity dependence.
- USDA Organic certification:This standard opens duty-advantaged access to North American natural products retailers seeking import alternatives to domestic supply constraints.
- Biotechnology-fermented actives:Convergence of precision fermentation with traditional saponification enables novel preservative systems that satisfy clean-label positioning.
Industry Challenges
- Formulation chemist scarcity:Expertise in cold-process emulsion stability and natural preservation systems remains concentrated among legacy natural cosmetics specialists.
- Certification timeline compression:COSMOS and USDA Organic audit cycles extend new product launch windows, delaying revenue recognition against fixed R&D amortization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Shampoo Market |
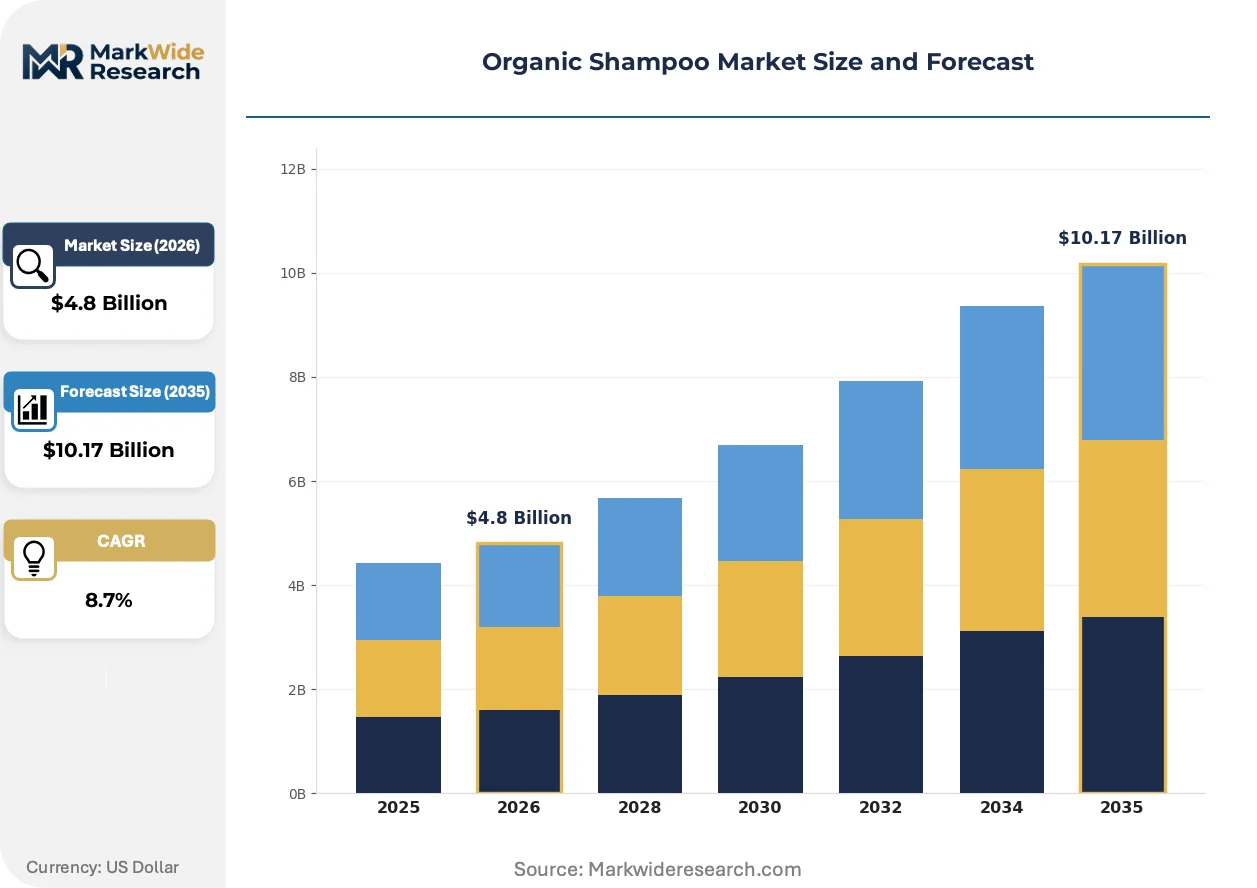
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating, Volumizing, Anti-Dandruff, Color-Safe Ingredient Type: Essential Oils, Herbal Extracts, Amino Acids, Natural Surfactants Packaging Type: Plastic Bottles, Glass Containers, Biodegradable Packs, Pumps End User: Salons, Retail Consumers, Wholesale Distributors, Organic Brands |
| Companies Covered | Colgate Palmolive Co., Amway Corp., L'Oréal SA, Hindustan Unilever Ltd., LVMH Group, Unilever, Johnson and Johnson Services Inc., The Hain Celestial Group Inc., The Estee Lauder Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Shampoo Market Emerging Trajectories
Formulation science is pivoting from ingredient substitution toward process innovation, with manufacturing methods and certification architectures becoming primary differentiation vectors rather than mere marketing claims.
Waterless shampoo concentrates are decentralizing production economics by eliminating shipping weight and enabling local compounding at salon or retail points. Professional distributors in Germany and France are adopting these systems to reduce inventory carrying costs. The technology is decentralizing the historical centralization of manufacturing in industrial cosmetic clusters.
EMA guidelines on cosmetic ingredient safety are tightening botanical extract approval pathways, forcing reformulation of legacy herbal staples. European manufacturers must now submit comprehensive safety dossiers for traditional ingredients previously grandfathered under historical use exemptions. Hydrating variants containing aloe vera and chamomile face the steepest re-evaluation burden.
Ingredient-conscious consumers are now verifying claims through third-party apps rather than trusting front-label positioning. This behavior compresses the value of marketing expenditure and elevates the importance of COSMOS or USDA Organic logo presence. Germany exhibits the highest scan-and-verify rates, with penetration spreading into Austrian and Swiss German-speaking markets.
Organic Shampoo Market Segmentation
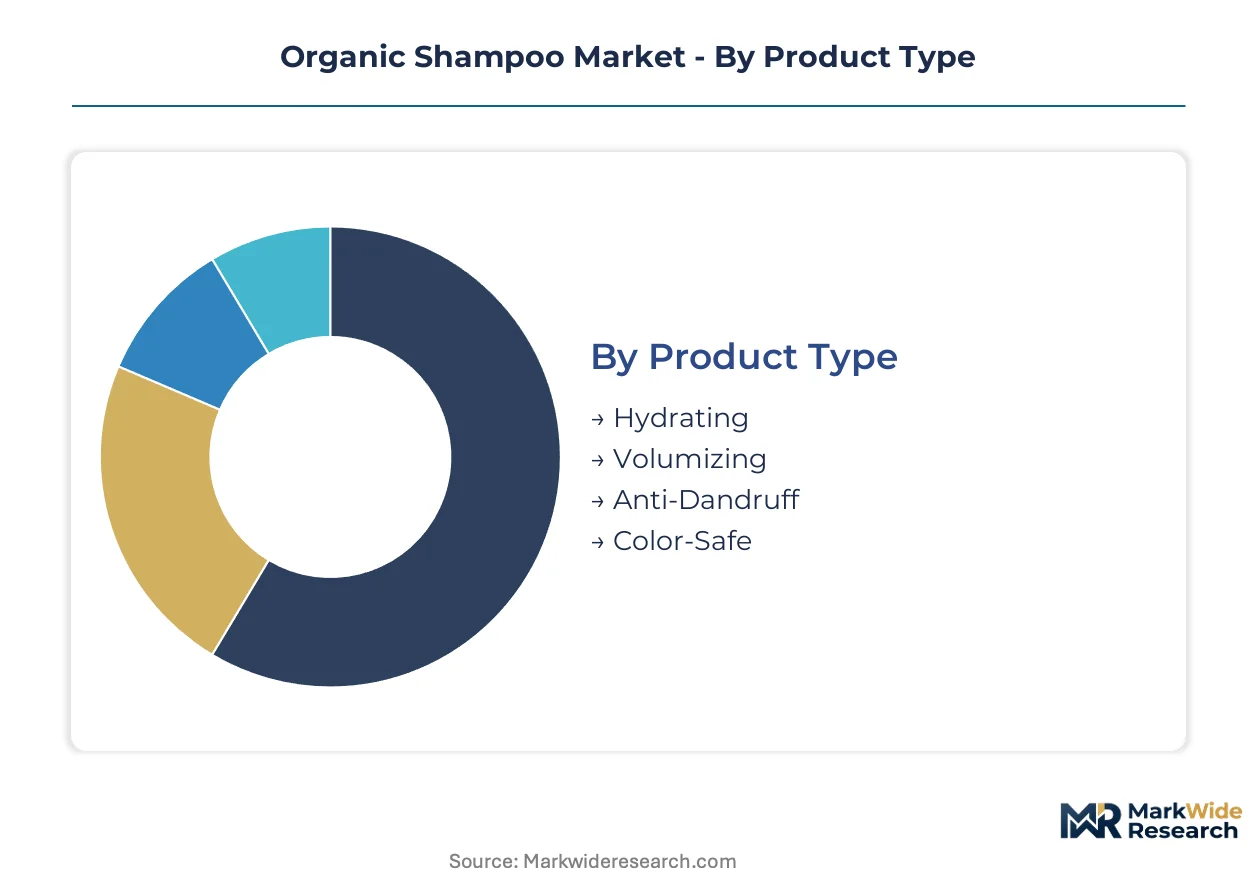
Segmentation in organic shampoo markets tracks how certification standards, ingredient sourcing constraints, and channel economics partition demand across distinct buyer profiles. Formulators must align product architectures with the divergent technical requirements of salon professionals versus retail consumers.
Product Type:
Salon professionals prioritize functional performance over price elasticity, driving premium positioning for clinically validated variants.
- Hydrating:Formulations center on aloe vera and chamomile extracts to restore moisture barriers across chemically treated hair. Demand concentrates in Germany's professional channel where COSMOS-certified backbar sizing dominates procurement decisions.
- Anti-Dandruff:Tea tree oil and salicylic acid systems displace zinc pyrithione through cold-process preservation of antimicrobial actives. Growth tilts toward this segment as EMA guidelines restrict synthetic anti-fungal approvals in European markets.
- Volumizing:Rice protein and panthenol combinations build film-forming complexes without silicone buildup.
- Color-Safe:pH-balanced formulations below 5.5 seal cuticle layers to extend oxidative dye longevity.
Volume sits with Hydrating; growth tilts toward Anti-Dandruff.
Ingredient Type:
Raw material traceability requirements are compressing the supplier base toward ECHA-registered botanical sources.
- Essential Oils:Lavender and rosemary terpenes deliver dual functional-aromatic positioning at 40-60% cost premiums over synthetic fragrance systems. Supply volatility in Provence and Bulgarian harvest zones destabilizes margin structures for premium variants.
- Natural Surfactants:Coco-glucoside and decyl glucoside systems replace sodium lauryl sulfate through mild cleansing profiles compatible with sensitive scalps. Manufacturing clusters in Southeast Asia create procurement concentration risk for sulfate-free formulators.
- Herbal Extracts:Nettle and horsetail infusions target scalp circulation claims under EFSA evaluation frameworks.
- Amino Acids:Wheat and silk proteins rebuild disulfide bonds in damaged hair shafts.
Revenue concentrates in Essential Oils; procurement risk accumulates in Natural Surfactants.
Packaging Type:
EU Green Deal circular economy mandates are accelerating material transition timelines beyond cost parity thresholds.
- Biodegradable Packs:Mycelium and seaweed-derived films decompose within 180 days in industrial composting facilities. Germany's Verpackungsgesetz enforcement drives adoption among domestic organic brands seeking regulatory preemption.
- Glass Containers:Amber and cobalt bottles preserve photosensitive essential oil integrity through UV-blocking properties. Premium positioning in French and Italian pharmacy channels supports 25-35% price premiums over plastic equivalents.
- Plastic Bottles:Post-consumer recycled content satisfies minimum thresholds under extended producer responsibility schemes.
- Pumps:Airless dispensing systems extend natural preservative efficacy by limiting oxidation exposure.
Unit economics favor Plastic Bottles; regulatory momentum shifts toward Biodegradable Packs.
End User:
Channel economics diverge sharply between recurring professional consumption and episodic retail purchasing patterns.
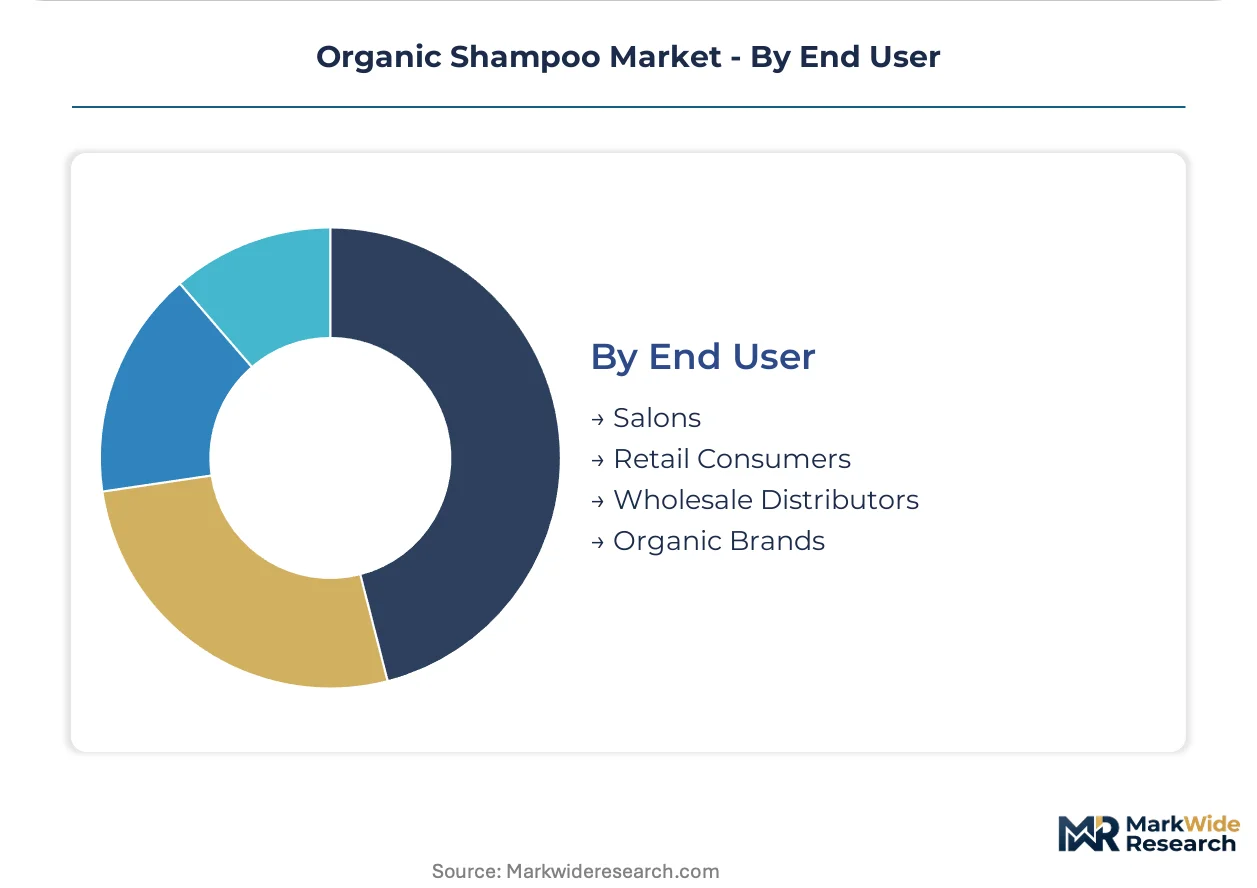
- Salons:Backbar sizing at 1-5 liter volumes generates recurring revenue streams with 60-70% lower customer acquisition costs than retail. Stylist education programs in German-speaking markets lock in formulation loyalty through certification-aligned technical training.
- Organic Brands:Private-label manufacturers supply COSMOS-certified base formulations for retailer-exclusive lines. Contract manufacturing agreements in France and Italy concentrate capacity among legacy natural cosmetics specialists.
- Retail Consumers:Direct-to-consumer subscriptions capture lifetime value through replenishment automation.
- Wholesale Distributors:Inventory carrying cost absorption enables smaller organic brands to access pharmacy and specialty retail placement.
Margin stability resides with Salons; capacity concentration clusters around Organic Brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Cosmetic Valley special economic zone outside Paris concentrates organic formulation R&D, drawing mid-tier manufacturers seeking proximity to ECHA regulatory expertise and COSMOS certification bodies.
Germany
Salon channel procurement drives volume, with professional buyers in Munich and Hamburg mandating COSMOS-certified backbar sizing. The country's Verpackungsgesetz packaging law accelerates biodegradable pack transitions ahead of EU deadlines. Manufacturing clusters in North Rhine-Westphalia specialize in cold-process saponification for sulfate-free formulations.
United States
USDA Organic certification opens duty-advantaged access for imports targeting natural products retailers in California and the Northeast. FDA cosmetic ingredient oversight intersects with state-level clean beauty legislation in New York and California. Precision fermentation startups in Boston and San Francisco develop novel preservative systems for clean-label positioning.
France
Essential oil supply chains anchor demand, with lavender harvests in Provence and rosemary cultivation in the Drôme valley destabilizing input costs. ANSM cosmetic safety guidelines tighten botanical extract approvals beyond EMA baselines. The Cosmetic Valley cluster southeast of Paris houses legacy natural cosmetics specialists with cold-process expertise.
United Kingdom
Post-Brexit regulatory divergence from REACH creates dual compliance burdens for formulators serving EU and UK markets. London-based specialty retailers drive scan-and-verify consumer behavior through third-party certification apps. Manufacturing capacity in the Midlands concentrates on private-label organic brands supplying pharmacy chains.
India
Tier-two and tier-three city penetration accelerates through extensive distribution networks, with Maharashtra and Gujarat emerging as herbal extract sourcing hubs. BIS cosmetic standards and FSSAI ingredient safety frameworks shape formulation boundaries. Ayurveda-inspired formulations from Kerala and Karnataka command premium positioning in domestic and export markets.
Organic Shampoo Market Vendor Landscape
European producers anchor the premium certification tier; North American specialists hold clean-label positioning. The market structures around three tiers: multinational consumer goods conglomerates with R&D infrastructure, mid-cap organic specialists with legacy natural cosmetics expertise, and private-label contract manufacturers serving retailer-exclusive lines. Competitive moves concentrate on M&A to acquire cold-process formulation capabilities and strategic partnerships to secure ECHA-registered botanical supply chains.
Within the multinational tier, L'Oréal SA and Unilever occupy positions defined by geographic certification navigation and distribution scale. The Hain Celestial Group Inc. exemplifies the mid-cap organic specialist archetype, anchoring portfolio positioning in ingredient-conscious consumer segments. These three entities represent divergent strategic paths: regulatory infrastructure leverage, network penetration, and clean-label purity positioning.
| Leading Market Players |
|---|
| Colgate Palmolive Co. |
| Amway Corp. |
| L'Oréal SA |
| Hindustan Unilever Ltd. |
| LVMH Group |
| Unilever |
| Johnson and Johnson Services Inc. |
| The Hain Celestial Group Inc. |
| The Estee Lauder Companies Inc. |
| Others |
Supply Flow & Price Mechanics
Captive integration into ECHA-registered botanical supply chains anchors both procurement security and premium pricing power for organic shampoo manufacturers navigating REACH compliance costs. German producers leveraging in-house cold-process saponification capacity capture margin advantages that outsourced formulators sacrifice to certification audit fees.
Pricing Analysis
Short lead-time premiums for COSMOS-certified backbar sizing reward salon distributors with 48-hour replenishment guarantees against spot-market discounts on standard retail SKUs. Three-tier pricing structure across premium essential-oil variants, standard herbal-extract lines, and economy natural-surfactant systems stratifies by certification depth and volume scale. Pricing pressure stems from lavender and rosemary harvest volatility in Provence and Bulgaria destabilizing input cost structures. Professional salon buyers exhibit lowest price sensitivity given recurring consumption patterns, while retail consumers in tier-two Indian cities drive aggressive economy-tier negotiation.
Supply Chain Analysis
EU Green Deal circular economy mandates and Germany's Verpackungsgesetz packaging law are reshaping sourcing toward biodegradable mycelium and seaweed-derived films compliant with industrial composting standards. Raw material dependencies center on Southeast Asian coco-glucoside and decyl glucoside production clusters, Bulgarian lavender harvest zones, and Provence rosemary cultivation. Single-source vulnerability concentrates in natural surfactant supply given limited ECHA-registered alternative suppliers. Distribution runs through professional salon channels in German-speaking markets, pharmacy chains in France and Italy, and wholesale distributors absorbing inventory carrying costs for smaller organic brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-process manufacturing technology is displacing heat-intensive legacy production, compressing launch timelines for zinc-pyrithione-free anti-dandruff formulations while elevating formulation chemist scarcity risks.
For Market Incumbents: Anchor defensive positioning through backward integration into ECHA-registered botanical supply chains and captive cold-process saponification capacity in North Rhine-Westphalia manufacturing clusters. Certification audit timeline compression from COSMOS and USDA Organic bodies threatens revenue recognition delays against fixed R&D amortization, demanding pre-positioned compliance infrastructure. For New Entrants and Emerging Players: The price-point gap between premium essential-oil salon variants and economy-tier retail lines offers white-space entry through mid-positioned hydrating formulations targeting Austrian and Swiss German-speaking markets. Anti-dandruff segments displace synthetic actives fastest under EMA guideline tightening. Direct-to-consumer subscription models with replenishment automation capture lifetime value absent retail slotting fee burdens. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational consumer goods conglomerates seeking cold-process formulation capabilities and ECHA-registered supply chain access. Long-term viability across the analysis window favors mid-cap organic specialists with legacy natural cosmetics expertise over pure-play private-label contract manufacturers. Watch biotechnology-fermented active approvals as inflection signal for next-generation preservative system viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Process Manufacturing Scale-Up | Preserves heat-sensitive tea tree oil and salicylic acid actives for anti-dandruff functional equivalence. |
| COSMOS Certification Investment | Unlocks salon channel procurement in Germany where professional buyers mandate certified backbar sizing. |
| Biodegradable Packaging Transition | Preempts Verpackungsgesetz enforcement ahead of EU Green Deal circular economy deadlines. |
| Precision Fermentation Partnership | Develops novel preservative systems satisfying clean-label positioning without synthetic compounds. |
| Professional Salon Channel Expansion | Generates recurring revenue streams with 60-70% lower customer acquisition costs than retail velocity. |
Methodological Framework
Trade databases, ECHA REACH registration filings, and COSMOS certification body records formed the secondary backbone for supply chain mapping and regulatory boundary identification. Primary interviews with organic formulation chemists, salon procurement managers, and biodegradable packaging suppliers combined with secondary validation through customs records and retail audit data. Bottom-up and top-down triangulation anchored volume estimates across product type, ingredient category, and channel segmentation dimensions.
Bottom-up modeling built from individual country-level salon channel penetration rates and certification adoption patterns, while top-down approaches cross-checked against aggregate personal care spending shifts. Segmentation tracked product type, ingredient sourcing, packaging format, and end-user channel across the projection horizon. CAGRs derived from fitted growth curves incorporating EMA guideline evolution assumptions and EU Green Deal implementation pacing. Forecast inputs included essential oil harvest yield variability and cold-process manufacturing capacity expansion timelines.
Inputs from ECHA, COSMOS certification bodies, and German salon distributor networks were available through the study window; gaps in proprietary formulation cost structures and private-label contract manufacturing margins introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions on regulatory timeline adherence and certification audit cycle compression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Private Label Cosmetics Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
GCC Hair Styling Products Market
Beauty & Personal Care
US Skincare Market
Beauty & Personal Care
Bath and Body Products Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
South America E-Commerce Skin Care Products Market
Beauty & Personal Care
Deodorant Wipes Market
Beauty & Personal Care
DIY Haircut Kits Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Body Care Products Market
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
BB Cushions Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Handmade False Eyelash Market