
 Face Makeup Market | 2026-2036
Face Makeup Market Size, Share, and Industry Trends Forecast 2026-2036
Face Makeup Market Intelligence
EU REACH compliance is recalibrating the cost-of-entry calculus for new entrants in the face makeup sector. Estée Lauder Companies leverages its captive R&D pipeline to preempt regulatory thresholds ahead of enforcement dates. Shiseido anchors its competitive stance through geographic dominance across Asian prestige channels. Coty differentiates via brand strength in celebrity-licensed fragrance-adjacent color cosmetics.
Face makeup comprises pigmented cosmetic preparations designed for application to facial skin, including foundation with titanium dioxide or iron oxide dispersions in emulsion bases, concealer with higher pigment loading for localized coverage, blush with pressed powder or cream formats for cheek coloration, and highlighter with mica or pearl-derived light-reflecting particles for dimensional enhancement. These products serve commercial purposes spanning daily consumer grooming, professional photography and broadcast preparation, and theatrical performance. Foundation in liquid formulation occupies the largest volume position due to universal daily-use penetration across age demographics. Powder blush represents a mature margin pool sustained by replenishment cycles in established Western markets. Online retail distribution is capturing the fastest growth trajectory, driven by influencer-led trial and algorithmic personalization engines.
FDA color additive regulations, EU REACH chemical restrictions, and China's NMPA cosmetic registration requirements collectively shape formulation transparency, ingredient prohibition lists, and pre-market testing obligations. Compliance divergence between FDA and EU frameworks forces parallel development tracks for multinational portfolios. Stakeholders must monitor regulatory harmonization negotiations between major trading blocs to anticipate whether unified standards emerge or fragmentation deepens.
Market Dynamics
Live-stream commerce is compressing purchase cycles across the face makeup sector, forcing incumbent brands to rebuild their digital infrastructure around real-time engagement rather than static retail shelf presence.
Growth Catalysts
- EU Green Deal ingredient disclosure mandates:Regulatory pressure is accelerating transparency investments that build consumer trust and preempt competitor positioning.
- Professional bridal and entertainment segments:Makeup artists are expanding product adoption through kit standardization and on-set recommendation authority.
- Titanium dioxide dispersion advances:Improved emulsion stability is extending wear duration and broadening climate applicability for liquid foundation formulations.
Market Restraints
- Mica supply concentration:Highlighter production depends on concentrated sourcing from specific mining regions, creating input volatility for light-reflecting formulations.
- FDA-EU regulatory divergence:Parallel compliance tracks for color additive approvals inflate development costs and delay portfolio synchronization.
- Silicone substitute performance gaps:Clean beauty transitions face texture and spreadability limitations when replacing dimethicone in primer and foundation bases.
Strategic Opportunities
- India tier-two urban penetration:Prestige channel density remains low in secondary cities, opening whitespace for localized shade range development.
- Algorithmic personalization engines:AI-driven shade matching is reducing return rates and building subscription loyalty in direct-to-consumer channels.
- China NMPA streamlined registration:Domestic brand favorability is rising as regulatory pathways simplify for locally manufactured formulations.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in pigment stabilization and emulsion chemistry is concentrating at established R&D hubs.
- Pre-market testing timeline compression:Accelerated product cycles strain safety assessment protocols without compromising EU REACH documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Makeup Market |
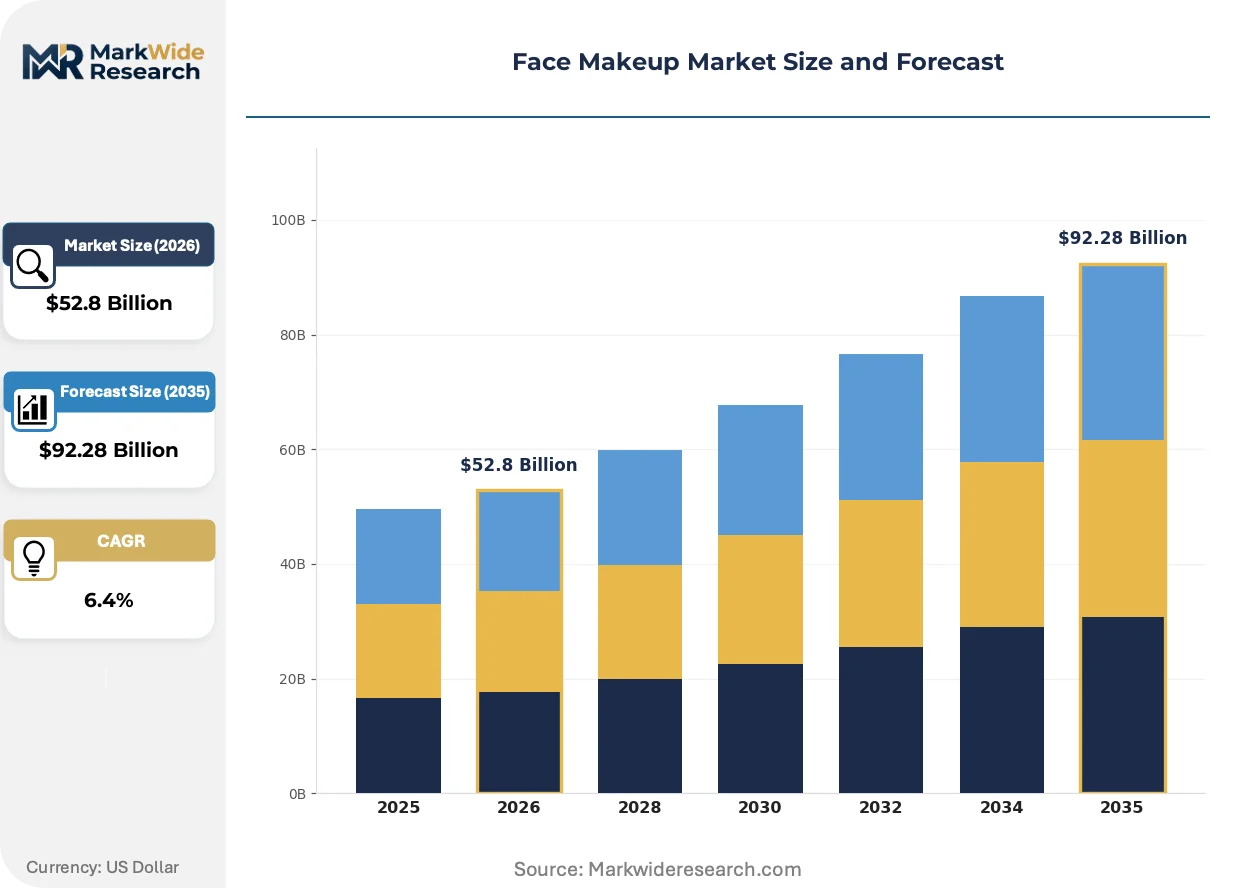
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foundation, Concealer, Blush, Highlighter Formulation: Liquid, Cream, Powder, Stick Customer Type: Professional, Casual Users, Makeup Artists, Influencers Distribution Channel: Online Retail, Department Stores, Specialty Stores, Drugstores |
| Companies Covered | Chanel, Amorepacific, L'Oréal, Coty, Procter & Gamble, Estée Lauder Companies, Shiseido, e.l.f. Beauty, LVMH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Makeup Market Strategic Shifts & Innovations
Digital-first discovery is displacing traditional counter sampling as the primary trial mechanism, reshaping how texture, finish, and shade accuracy are communicated pre-purchase.
AI-powered skin analysis tools are decentralizing shade matching authority from in-store consultants to consumer-controlled mobile applications. Younger demographics are adopting these diagnostic platforms at accelerated rates, bypassing traditional color-matching services. This shift is compressing the role of department store beauty advisors and reallocating training investment toward digital asset creation.
REACH chemical restriction expansions are forcing reformulation cycles across preservative and fragrance component portfolios. The industrial consequence is rising R&D allocation toward biotech-derived alternatives that satisfy hazard classification thresholds. Prestige brands with captive laboratories are responding faster than contract manufacturers serving mid-tier labels.
Subscription replenishment models are capturing recurring revenue from powder blush and concealer categories previously dominated by discretionary repurchase. Direct-to-consumer platforms are displacing drugstore impulse buying through predictive shipping algorithms. This pattern is most visible in the United States, where algorithmic personalization has achieved highest penetration among millennial and Gen Z cohorts.
Face Makeup Market Segmentation
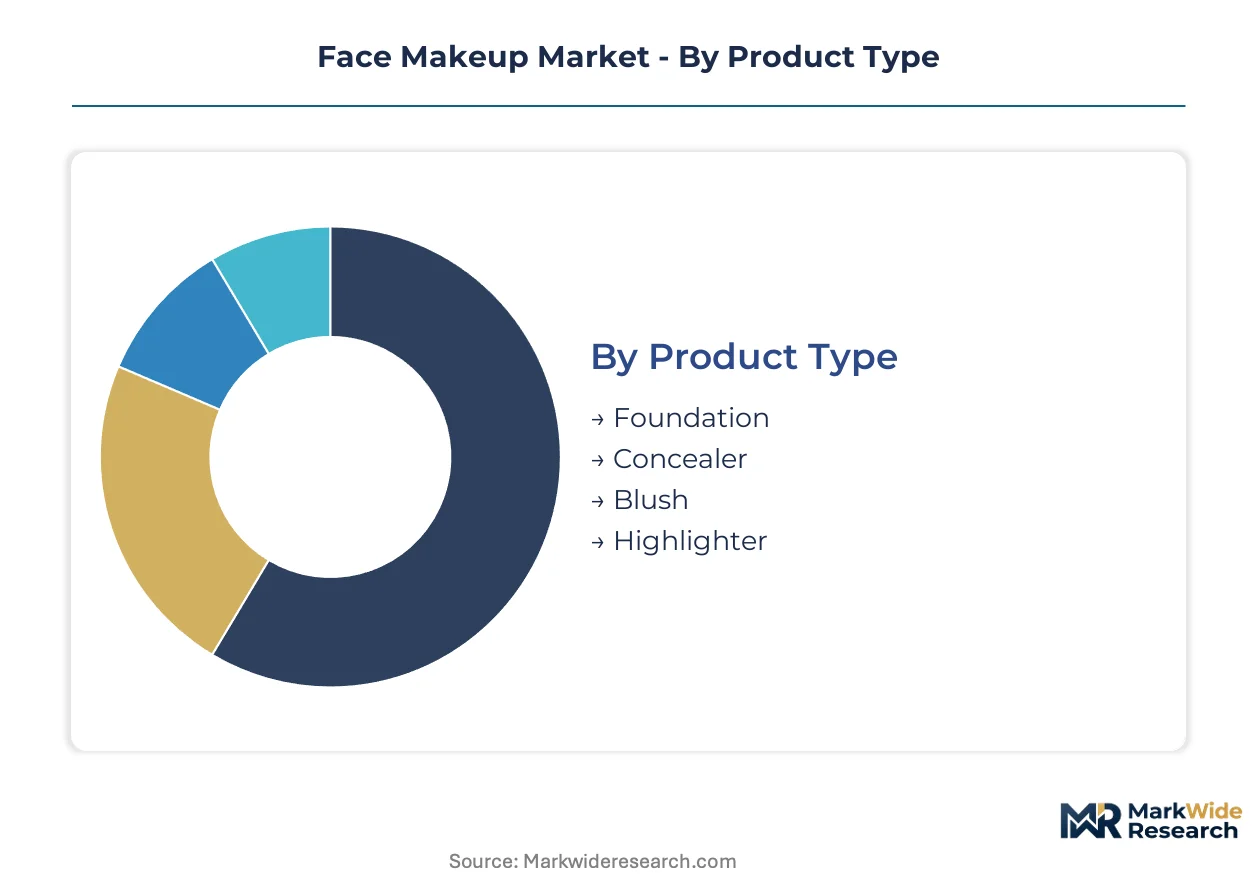
Segmentation in face makeup determines formulation complexity, margin architecture, and channel strategy. Product type dictates raw material procurement patterns while distribution channel selection shapes customer acquisition economics and replenishment frequency.
Product Type:
Supply concentration in titanium dioxide and mica feedstocks privileges scale players in pigment-intensive categories.
- Foundation:Liquid emulsions with titanium dioxide or iron oxide dispersions dominate volume throughput. Demand concentrates in China and the United States where daily-use penetration across age demographics sustains replenishment cycles. Climate-adaptive wear extensions are expanding geographic applicability for liquid formulations.
- Concealer:Higher pigment loading enables localized coverage for blemish and under-eye application. Professional makeup artists in bridal and entertainment segments are driving kit standardization and on-set recommendation authority for premium concealer SKUs.
- Blush:Pressed powder and cream formats deliver cheek coloration through iron oxide or carmine-based systems. Mature margin pools in Western markets sustain replenishment cycles.
- Highlighter:Mica or pearl-derived light-reflecting particles create dimensional enhancement. Concentrated sourcing from specific mining regions generates input volatility for light-reflecting formulations.
Today's leader: Foundation. Tomorrow's challenger: Concealer.
Formulation:
Cost tier stratification separates premium liquid R&D investments from mass-market powder manufacturing efficiency.
- Liquid:Emulsion-based systems with silicone or silicone-alternative spreadability agents capture universal daily-use penetration. AI-driven shade matching in direct-to-consumer channels is reducing return rates and building subscription loyalty for liquid foundation.
- Cream:Balanced pigment saturation with emollient bases targets professional application and mature skin demographics. Makeup artists in bridal segments favor cream formats for blendability and photography performance.
- Powder:Pressed or loose mineral systems with talc or silica carriers serve oil-control and setting functions. Drugstore impulse buying persists in established Western markets.
- Stick:Solid emulsion formats with wax structuring agents enable portable application and travel retail placement. Convenience positioning targets casual users with simplified routines.
Volume gravity sits with liquid. Margin expansion favors cream.
Customer Type:
Application intensity separates professional kit investment from casual user trial-and-replenishment patterns.
- Professional:Salons, photography studios, and broadcast operations maintain standardized kit inventories with high SKU breadth. EU REACH compliance documentation requirements favor established brands with captive R&D pipelines.
- Casual Users:Daily grooming consumers with discretionary repurchase patterns and influencer-driven discovery behaviors. Algorithmic personalization engines are displacing traditional counter sampling for this segment.
- Makeup Artists:Freelance and agency-based professionals with kit standardization authority and on-set recommendation leverage. Live-stream commerce is compressing their purchase cycles toward real-time engagement platforms.
- Influencers:Content creators with affiliate-driven trial generation and algorithmic reach-based monetization. Younger demographics adopt AI-powered skin analysis tools at accelerated rates, bypassing traditional color-matching services.
Makeup artists command authority. Influencers capture discovery.
Distribution Channel:
Geography determines channel maturity, with digital infrastructure penetration varying sharply between urban clusters.
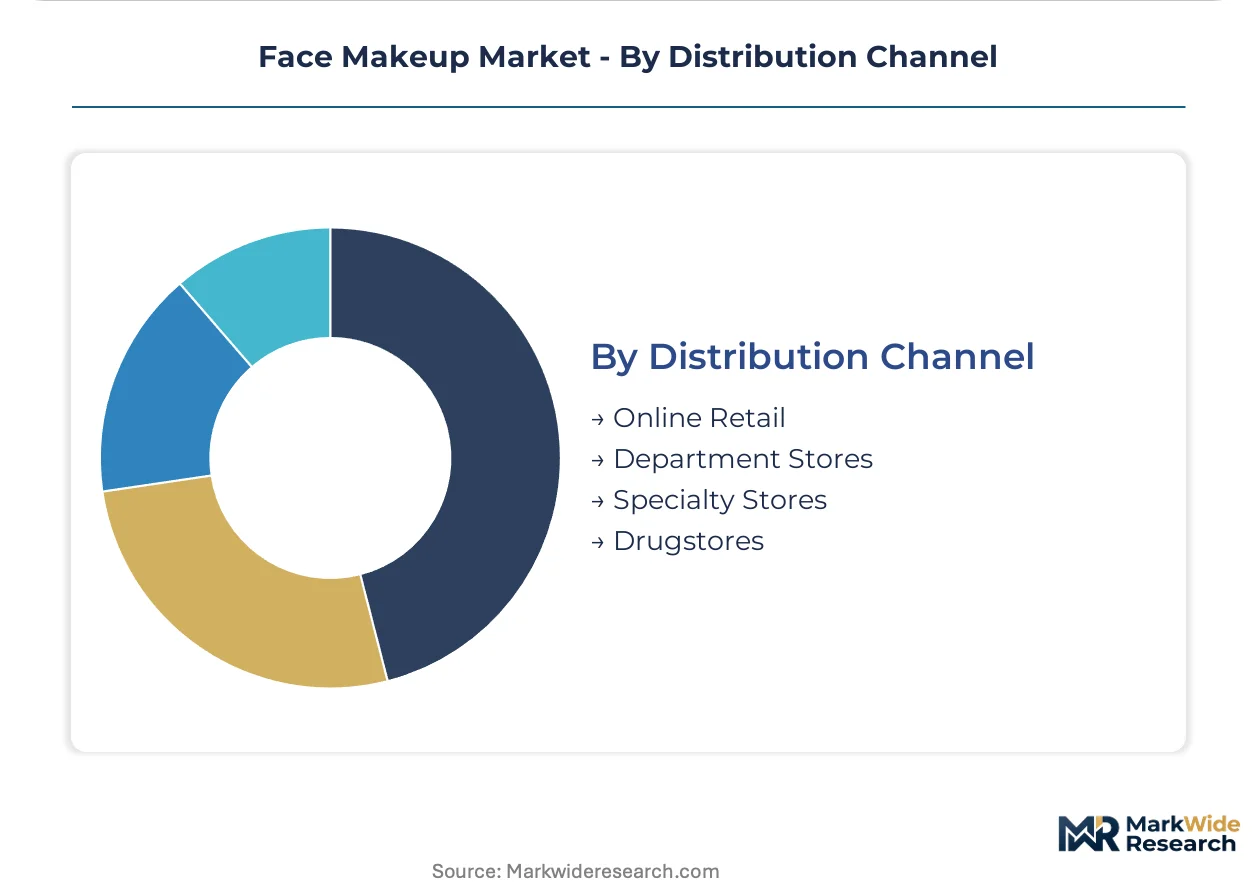
- Online Retail:Direct-to-consumer platforms and marketplace aggregators with algorithmic personalization and subscription replenishment. The United States shows highest algorithmic personalization penetration among millennial and Gen Z cohorts.
- Department Stores:Prestige counters with beauty advisor consultation and sampling services. AI-powered skin analysis tools are compressing the role of in-store consultants.
- Specialty Stores:Sephora, Ulta, and equivalent beauty-focused retailers with curated brand portfolios and experiential merchandising. Clean beauty transitions face texture limitations when replacing dimethicone in primer and foundation bases.
- Drugstores:Mass-market placement with impulse purchase dynamics and promotional pricing. Predictive shipping algorithms in subscription models are displacing discretionary repurchase patterns.
Online retail climbs fastest. Department stores defend margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Face makeup industrialization traces its modern lineage to early twentieth-century Parisian perfumeries and subsequent scaling through New York department store counters, establishing geographic patterns that persist in today's prestige channel distribution.
United States
Algorithmic personalization engines in direct-to-consumer channels capture millennial and Gen Z replenishment patterns for liquid foundation and concealer. FDA color additive regulations enforce pre-market testing obligations distinct from EU frameworks, forcing parallel formulation tracks. Los Angeles anchors entertainment industry kit standardization where makeup artists drive professional-grade SKU adoption.
China
Domestic brand favorability accelerates through live-stream commerce compression of purchase cycles across tier-one and tier-two urban clusters. NMPA streamlined registration pathways for locally manufactured formulations reduce time-to-market for Shanghai and Hangzhou-based innovators. Yangtze River Delta manufacturing hubs concentrate pigment dispersion and emulsion chemistry capabilities.
France
Prestige heritage positioning sustains margin architecture in fragrance-adjacent color cosmetics through Parisian flagship retail. EU REACH chemical restrictions and Green Deal ingredient disclosure mandates accelerate biotech-derived alternative investments. Île-de-France R&D clusters concentrate formulation expertise in pigment stabilization.
Japan
Prestige channel density across Asian markets anchors geographic dominance for emulsion-based liquid formulations. METI standards and PMDA cosmetic regulations shape preservative and fragrance component portfolios. Kanto region laboratories concentrate silicone-substitute development for clean beauty texture requirements.
India
Tier-two urban penetration opens whitespace for localized shade range development in powder blush and concealer categories. BIS cosmetic standards and CDSCO regulatory frameworks govern import and domestic manufacturing compliance. Maharashtra and Karnataka industrial corridors concentrate contract manufacturing capacity for multinational brand localization.
Face Makeup Market Key Industry Players
The competitive structure tilts toward multinational conglomerates with captive R&D pipelines and prestige heritage positioning. Scale advantages concentrate in pigment procurement and emulsion chemistry capabilities. Three archetypes dominate: vertically integrated beauty conglomerates with fragrance-color cosmetics adjacencies, Asia-anchored prestige specialists with regional channel control, and digital-native challengers with algorithmic personalization infrastructure. Portfolio diversification and geographic expansion constitute the dominant competitive moves, with regulatory pre-positioning ahead of enforcement dates as a secondary vector.
Among French heritage conglomerates, LVMH and Chanel exemplify prestige-tier archetypes anchored in fragrance-adjacent color cosmetics with flagship retail presence. L'Oréal occupies a position spanning mass-market through luxury tiers with diversified brand architecture. Estée Lauder Companies represents the vertically integrated multinational with captive R&D pipelines preempting regulatory thresholds. Shiseido anchors Asian prestige channel dominance through geographic concentration. Coty sits within celebrity-licensed fragrance-color cosmetics convergence. Amorepacific exemplifies Korea-origin innovation in emulsion technology. e.l.f. Beauty represents digital-native challenger positioning with algorithmic personalization capabilities.
| Leading Market Players |
|---|
| Chanel |
| Amorepacific |
| L'Oréal |
| Coty |
| Procter & Gamble |
| Estée Lauder Companies |
| Shiseido |
| e.l.f. Beauty |
| LVMH |
| Others |
Cost & Logistics Intelligence
Titanium dioxide dispersion costs cascade through prestige and mass-market tiers, with pigment-grade differentials separating liquid foundation price bands from raw material procurement through Shanghai and Rotterdam trading hubs.
Pricing Analysis
Three-tier pricing structure across prestige, professional, and mass-market levels anchors the face makeup sector, with brand heritage and EU REACH compliance documentation as primary price differentiation drivers. Cost compression in mass-market liquid foundation intensifies because domestic Chinese manufacturers exploit NMPA streamlined registration pathways. Casual users in tier-two Indian cities exhibit highest price sensitivity, while prestige bridal segments in France and Japan demonstrate lowest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from multinational brand owners now require qualified mica suppliers across both Jharkhand mining clusters and synthetic pearl-derived alternatives from Japanese biotech laboratories. Geographic supply concentration spans China for titanium dioxide processing, India for iron oxide pigments, and Brazil for natural mica extraction. Raw material dependencies rest on silicone alternatives for clean beauty emulsions, carmine for red pigment systems, and wax structuring agents for stick formats. Single-source vulnerability in Jharkhand mica creates supply chain risk. Distribution runs through Yangtze River Delta manufacturing hubs into direct-to-consumer platforms and prestige retail counters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The face makeup market functions as a stable compounder, with regulatory-driven reformulation cycles ensuring consistent R&D reinvestment and premium pricing maintenance across prestige tiers.
For Market Incumbents: Lock in captive pigment dispersion capabilities through backward integration into titanium dioxide processing or long-term offtake agreements with Yangtze River Delta suppliers. Secure EU REACH pre-registration documentation ahead of Green Deal enforcement dates to preempt competitor positioning. Channel control in live-stream commerce platforms represents the critical defensive lever against algorithmic-native challengers. For New Entrants and Emerging Players: AI-powered skin analysis tools offer a technology-first wedge into the direct-to-consumer subscription channel, where algorithmic personalization reduces return rates and builds loyalty. India tier-two urban clusters present the most penetrable geography for localized shade range development. A digital-first go-to-market angle leveraging influencer affiliate networks bypasses traditional prestige counter infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where cosmetic chemist talent scarcity concentrates formulation expertise at established R&D hubs. Long-term viability favors vertically integrated beauty conglomerates with fragrance-color cosmetics adjacencies and captive laboratory infrastructure. Watch NMPA registration pathway simplification for domestic Chinese brands as the inflection signal indicating competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Positioning | EU REACH compliance documentation ahead of Green Deal enforcement dates builds competitive moats. |
| Algorithmic Personalization Investment | AI-driven shade matching in direct-to-consumer channels reduces return rates and captures subscription revenue. |
| Backward Integration into Pigment Processing | Captive titanium dioxide dispersion capabilities secure supply and margin in liquid foundation production. |
| Live-Stream Commerce Infrastructure | Real-time engagement platforms in China compress purchase cycles and displace static retail presence. |
| Clean Beauty Reformulation | Biotech-derived silicone alternatives satisfy EU hazard classification thresholds and command premium positioning. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic chemists, brand managers at prestige houses, procurement leads at contract manufacturers, and live-stream commerce platform operators with secondary validation. Regulatory filings from ECHA, FDA color additive petitions, and NMPA registration databases anchored compliance analysis. Retail audit data from Nielsen and customs records traced import patterns. Bottom-up SKU-level modeling and top-down category sizing triangulated market estimates.
Comparable-period anchoring linked historical replenishment cycles to projected algorithmic personalization penetration rates across the analysis window. Segmentation dimensions included product type, formulation chemistry, customer application intensity, and distribution channel maturity. CAGRs derived from regression analysis against professional makeup artist kit standardization trends and live-stream commerce growth curves. Forecast inputs incorporated EU REACH chemical restriction expansion timelines and China domestic brand favorability indices.
The model holds under stable regulatory enforcement schedules; deviation in EU-REACH harmonization negotiations or NMPA pathway reversals would shift competitive positioning materially. Deviation in mica supply disruption frequency or synthetic pearl-derived substitute cost curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Intensive Conditioner Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Shower Gel Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Sun Protection Spray Market
Beauty & Personal Care
Personal Care Ingredients Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Face Steaming Devices Market
Beauty & Personal Care
Gua Sha Tools Market
Beauty & Personal Care
Hair Color Spray Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Bangladesh Shampoo Market