
 Hydration Containers Market | 2026-2036
Hydration Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydration Containers Market Analysis
The EU Green Deal is expanding the addressable market for reusable hydration vessels across member states. YETI Holdings sustains premium positioning through thermal performance specialization and direct-to-consumer channel control. Hydro Flask dominates the insulated stainless steel segment with color customization and outdoor retail partnerships. Newell Brands leverages mass-market distribution scale to compete on price-accessibility in plastic alternatives.
Hydration containers are engineered vessels designed for portable liquid storage, typically constructed with double-wall vacuum insulation, BPA-free polymers, or borosilicate glass to maintain temperature stability and chemical safety for consumer use. Water bottles lead volume sales due to universal daily-use applicability, while hydration packs capture higher margins in technical outdoor and cycling applications where hands-free delivery systems command premium pricing. Stainless steel occupies the fastest-growing material position as consumers prioritize durability and taste neutrality over lighter plastic alternatives.
FDA food-contact regulations in the United States govern material safety certifications, while REACH compliance in Europe restricts phthalate and bisphenol content in polymer formulations, directly shaping supplier qualification requirements. ECHA substance evaluations continue tightening thresholds for migratory compounds, forcing reformulation investments across plastic-dependent manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks, as packaging waste directives in multiple jurisdictions threaten to impose end-of-life collection obligations on brands previously exempt from circular economy compliance.
Market Dynamics
EU Green Deal single-use plastic restrictions are structurally redirecting consumer spending toward durable hydration vessels, while municipal refill infrastructure investments in Germany and France normalize premium reusable ownership patterns.
Growth Catalysts
- REACH compliance thresholds:ECHA substance evaluations tightening migratory compound limits force plastic-dependent manufacturers toward stainless steel and glass alternatives, expanding addressable markets for premium vessels.
- Outdoor recreation participation:Technical cycling and trail running communities drive demand for hands-free hydration pack systems with integrated filtration and thermal management features.
- Municipal refill station density:German cities including Berlin and Munich deploy networked public water fountains, reducing friction for daily reusable bottle carrying behavior.
Market Restraints
- Nickel price volatility:Stainless steel feedstock cost swings compress margin stability for vacuum-insulated manufacturers dependent on 18/8 grade alloys.
- Asian contract manufacturer concentration:Double-wall vacuum sealing capacity clusters in Guangdong and Zhejiang provinces, creating geographic supply risk and logistics complexity.
- Lightweight polymer substitution:Tritan copolyester and recycled PET alternatives retain cost and weight advantages for price-sensitive mass-market segments.
Strategic Opportunities
- Extended Producer Responsibility frameworks:Packaging waste directives in France and Italy threaten to impose end-of-life collection obligations on brands, creating first-mover advantage for circular-designed vessels with take-back programs.
- Smart hydration integration:Bluetooth-enabled bottles with UV-C purification and consumption tracking converge with wellness app ecosystems, opening premium pricing in corporate wellness and healthcare verticals.
- Direct-to-consumer channel control:Subscription-based replacement part programs for gaskets and lids build recurring revenue and reduce customer acquisition costs.
Industry Challenges
- Vacuum seal technician scarcity:Double-wall manufacturing requires specialized welding and helium leak detection expertise that outpaces vocational training pipeline output.
- Multi-jurisdiction certification timelines:FDA food-contact approval, LFGB Germany testing, and Japan Food Sanitation Law compliance create sequential market entry delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydration Containers Market |
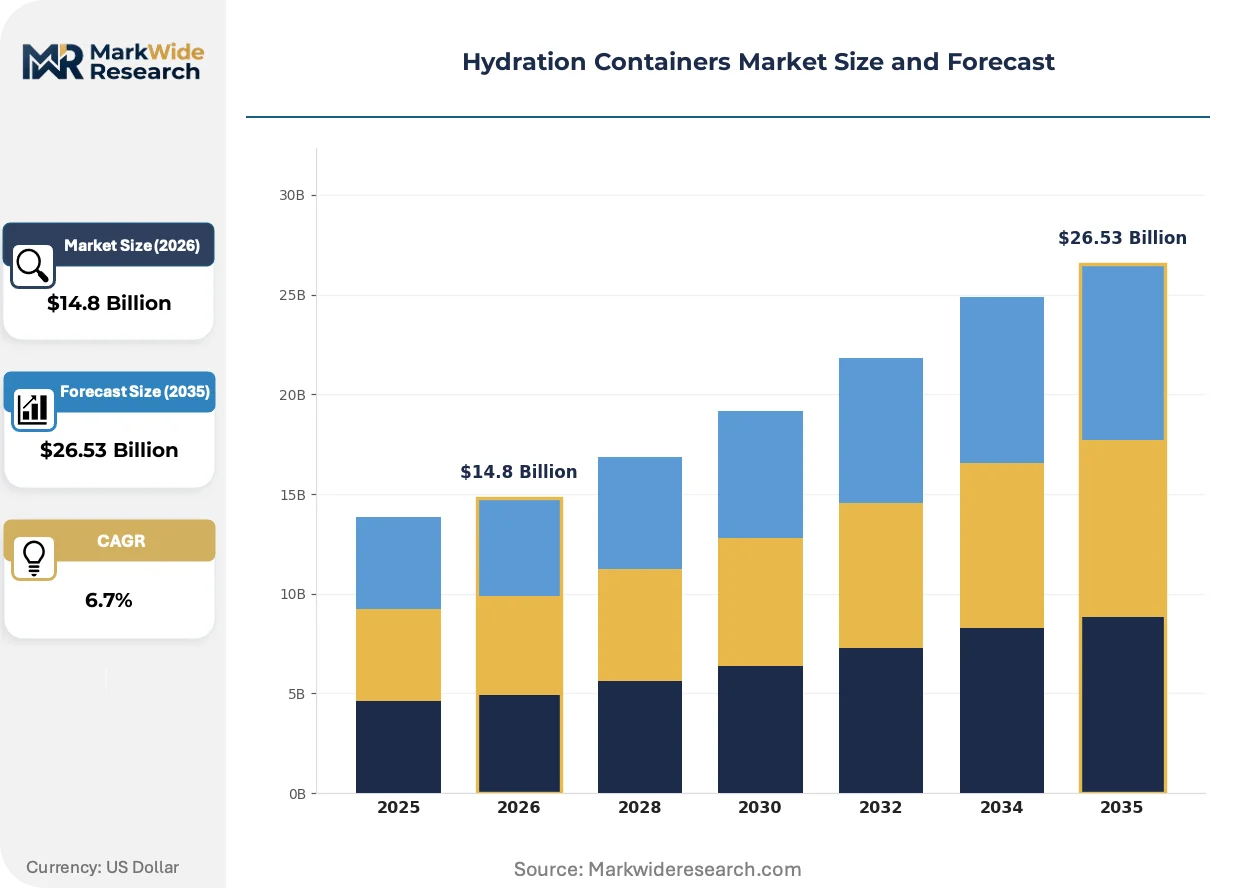
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Bottles, Hydration Packs, Soft Flasks, Tumblers Material: Plastic, Stainless Steel, Glass, Aluminum End User: Outdoor Enthusiasts, Athletes, Students, Office Workers Capacity: 500ml, 1L, 2L, 3L |
| Companies Covered | Helen of Troy Limited, YETI Holdings, Inc., CamelBak Products, LLC, Newell Brands Inc., Thermos L.L.C., Hydro Flask, S'well LLC, Tupperware Brands Corporation, Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydration Containers Market Emerging Trajectories
Product architecture is fragmenting into interoperable subsystems as manufacturers respond to repairability mandates and consumer customization expectations. Thermal performance, modularity, and digital integration now define competitive differentiation.
Vacuum insulation technology is modularizing around standardized mouthpiece, cap, and base attachment interfaces. Outdoor enthusiasts and urban commuters swap filtration inserts, carrying loops, and temperature-display lids across compatible vessel platforms. This interoperability compresses replacement cycle revenue while building ecosystem loyalty.
EU Green Deal packaging regulations are forcing material disclosure and recyclability scoring on hydration container labeling. Manufacturers reformulate polymer blends and publish end-of-life processing instructions to maintain shelf placement in French and Dutch retail chains. Stainless steel suppliers accelerate recycled content certification to satisfy CSRD supply chain reporting requirements.
Corporate procurement departments now specify reusable vessel programs as scope-three emissions reduction tactics. Facility management vendors bundle branded bottle distribution with hydration station installation, displacing single-use plastic contracts in tech campuses and healthcare systems. This B2B pivot concentrates in California and Washington state where building code water access mandates intersect with corporate sustainability targets.
Hydration Containers Market Segmentation
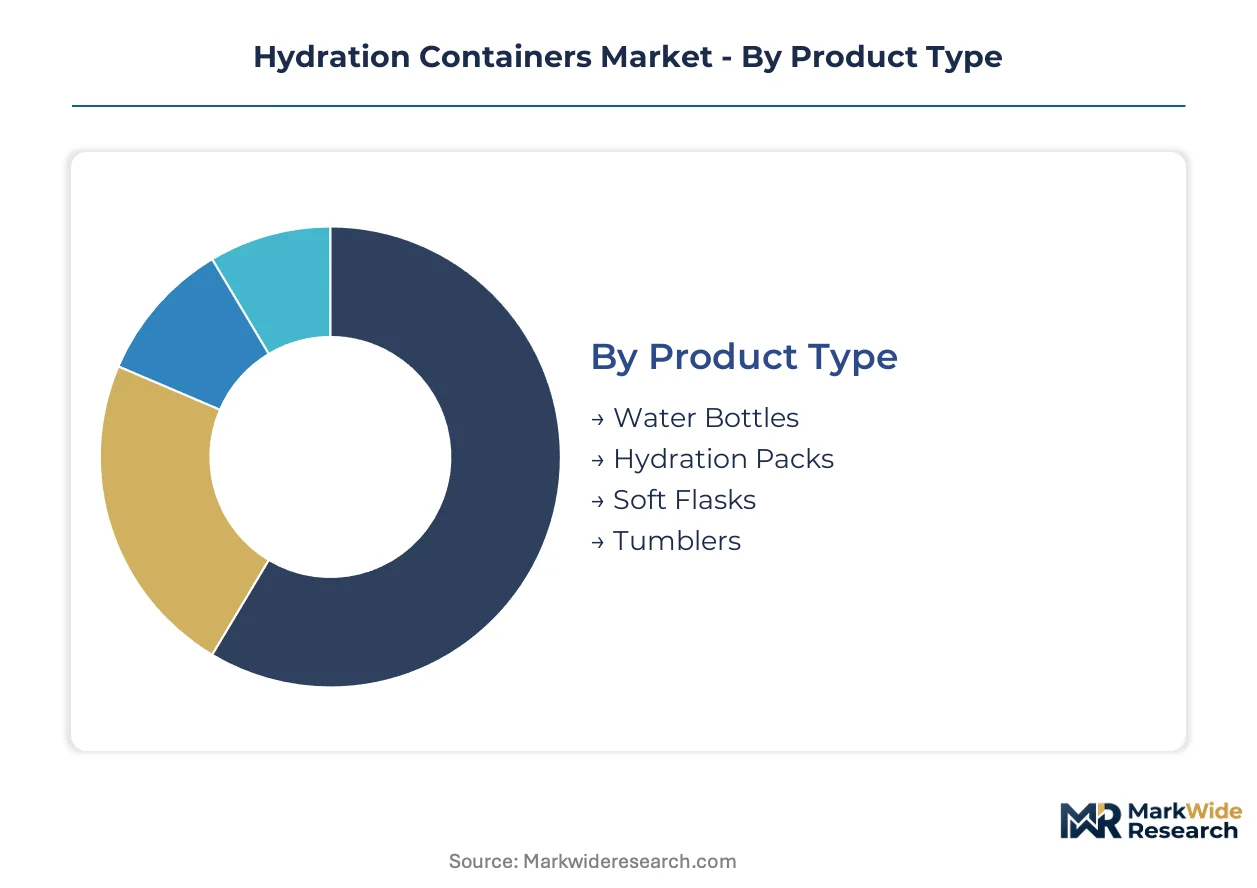
Segmentation in hydration containers reveals how thermal performance requirements, portability constraints, and regulatory material restrictions fragment demand across distinct buyer cohorts. Manufacturers optimize vessel architecture around specific use-case durability and capacity specifications rather than pursuing universal designs.
Product Type:
Purchase frequency and replacement cycles diverge sharply between daily-carry vessels and technical outdoor systems.
- Water Bottles:Universal daily-use vessels constructed with single-wall or double-wall insulation for temperature retention across commuting and workplace contexts. Demand concentrates in Germany and France where municipal refill infrastructure normalizes premium reusable ownership, with EU Green Deal restrictions accelerating displacement of single-use alternatives.
- Hydration Packs:Hands-free liquid delivery systems integrating flexible reservoirs with shoulder-strap distribution for cycling and trail running applications. Technical outdoor communities in the Alps and Pyrenees drive premium pricing for integrated filtration and thermal management features.
- Soft Flasks:Collapsible polymer vessels designed for compression as liquid depletes, reducing bulk during ultramarathon and fastpacking activities.
- Tumblers:Open-top insulated cups optimized for stationary consumption in vehicle cup holders and office desk environments.
Water bottles lead on scale; hydration packs lead on momentum.
Material:
Regulatory thresholds on migratory compounds and end-of-life obligations reshape material selection economics.
- Stainless Steel:Double-wall vacuum-insulated construction using 18/8 grade alloys for taste neutrality and impact resistance. REACH compliance tightening on phthalate limits forces plastic-dependent manufacturers toward metal alternatives, expanding addressable markets for premium vessels.
- Plastic:BPA-free polymers and Tritan copolyester formulations retaining cost and weight advantages for price-sensitive mass-market segments. ECHA substance evaluations continue restricting bisphenol content, forcing reformulation investments.
- Glass:Borosilicate construction offering chemical inertness and visual clarity for taste-purists and beverage aesthetic preferences.
- Aluminum:Lightweight single-wall vessels with internal polymer linings for cycling and climbing applications where gram reduction dominates.
Plastic dominates volume; stainless steel commands the steepest expansion trajectory.
End User:
Activity-specific hydration behaviors determine capacity requirements, durability specifications, and attachment system complexity.
- Outdoor Enthusiasts:Technical users requiring filtration compatibility, thermal management, and modular attachment systems for multi-day expeditions. German and Austrian alpine communities normalize premium vessel ownership through equipment rental integration and trailhead refill infrastructure.
- Athletes:Performance-focused buyers prioritizing ergonomic mouthpieces, squeeze-flow rates, and electrolyte compatibility for training and competition contexts.
- Students:Price-sensitive cohort selecting vessels based on color customization and campus refill station proximity.
- Office Workers:Desktop-oriented users emphasizing thermal retention duration and spill-resistant lid mechanisms for meeting and commute contexts.
Outdoor enthusiasts anchor premium pricing; athletes drive innovation velocity.
Capacity:
Portability constraints and consumption patterns fragment demand across volume tiers with distinct margin structures.
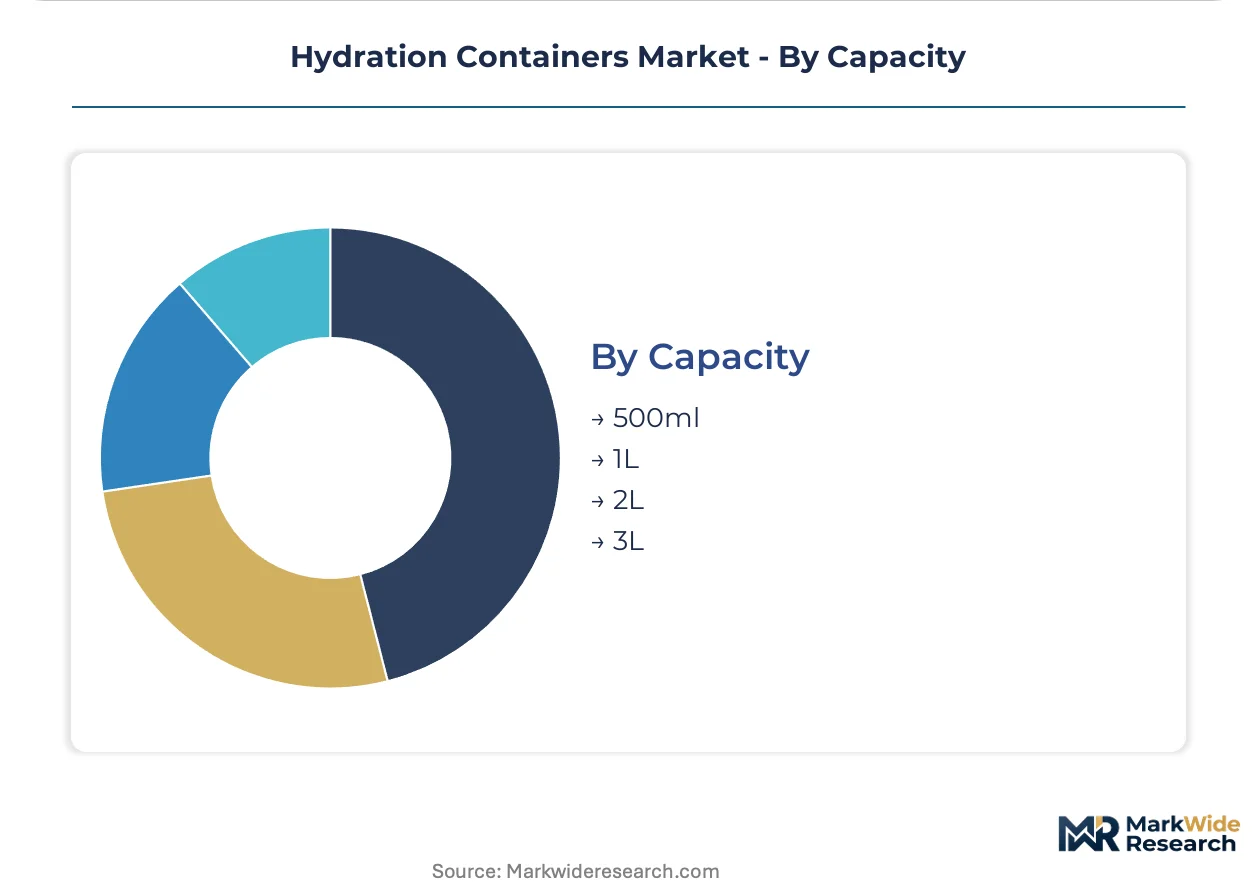
- 500ml:Pocket-compatible vessels for urban commuting and short-duration activities where weight minimization outweighs volume requirements.
- 1L:Standard daily-carry format balancing hydration adequacy with bag-fit compatibility across student and professional segments.
- 2L:Extended-activity reservoirs for half-day hiking and cycling routes where refill access is intermittent.
- 3L:Technical expedition capacity integrated into hydration pack systems for remote terrain traversal without water source dependency.
1L vessels capture mainstream volume; 3L systems extract highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized vacuum-seal technicians and polymer formulation chemists concentrate in Germany's industrial belt and China's Pearl River Delta, anchoring production capacity for double-wall insulated vessels and BPA-free polymer alternatives.
Germany
Municipal refill station density in Berlin and Munich normalizes daily reusable bottle carrying behavior among commuters. REACH compliance thresholds enforced by ECHA tighten migratory compound limits, forcing manufacturers toward stainless steel alternatives. Bavaria's precision manufacturing clusters around Nuremberg host specialized vacuum-seal technicians serving premium thermal vessel producers.
United States
Corporate procurement departments in California and Washington specify reusable vessel programs as scope-three emissions reduction tactics. FDA food-contact regulations govern material safety certifications for polymer and metal formulations. The Pacific Northwest's outdoor recreation economy sustains demand for technical hydration packs with integrated filtration systems.
China
Double-wall vacuum sealing capacity clusters in Guangdong and Zhejiang provinces, supplying contract manufacturing for global brands. The country's national quality regulator enforces GB standards for food-contact materials alongside export-market certifications. Shenzhen's electronics manufacturing ecosystem supports smart hydration integration with Bluetooth-enabled tracking and UV-C purification modules.
France
Extended producer responsibility frameworks under EU packaging waste directives threaten end-of-life collection obligations on hydration container brands. ANSM and environmental agencies enforce material disclosure requirements on product labeling. The Île-de-France region's corporate headquarters concentration drives B2B procurement of branded vessel programs for facility management contracts.
Japan
Precision manufacturing traditions in the Kansai region sustain expertise in thin-wall stainless steel forming for lightweight vessels. METI oversees Japan Food Sanitation Law compliance, creating sequential certification timelines alongside FDA and LFGB requirements. Tokyo's dense urban transit culture normalizes compact 500ml bottle formats for pocket-compatible daily carry.
Hydration Containers Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated manufacturers control thermal performance technology while brand marketers outsource fabrication to Asian contract foundries. The vendor base separates into three strategic archetypes: premium thermal specialists commanding direct-to-consumer channels, mass-market distributors leveraging retail scale, and outdoor equipment integrators bundling hydration into technical gear systems. Dominant competitive moves include geographic diversification of manufacturing footprints to mitigate supply concentration risk, and portfolio extension into smart-enabled vessels with digital hydration tracking.
Within the premium thermal vessel tier, YETI Holdings, Inc. and Hydro Flask exemplify brand-differentiated positioning through specialized insulation engineering and color customization programs. Newell Brands Inc. represents mass-market scale economics, distributing polymer alternatives through broad retail networks. These three entities anchor distinct competitive vectors rather than converging on identical capability sets, with each occupying a position that reflects upstream manufacturing relationships and downstream channel control priorities.
| Leading Market Players |
|---|
| Helen of Troy Limited |
| YETI Holdings, Inc. |
| CamelBak Products, LLC |
| Newell Brands Inc. |
| Thermos L.L.C. |
| Hydro Flask |
| S'well LLC |
| Tupperware Brands Corporation |
| Amcor Plc |
| Others |
Supply Flow & Price Mechanics
Nickel feedstock volatility cascades from Guangdong contract foundries through vacuum-insulated vessel pricing tiers, compressing margins for premium thermal specialists while forcing mid-market brands toward polymer alternatives. Stainless steel alloy cost swings tether directly to 18/8 grade sourcing from Indonesian nickel processing, creating divergent pricing power between integrated manufacturers and brand marketers outsourcing fabrication.
Pricing Analysis
Bundled replacement-part subscriptions separate premium vessel economics from transactional unbundled sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal performance certification and direct-to-consumer channel control. Cost compression in the mass-market tier intensifies because Tritan copolyester alternatives undercut stainless steel on unit economics. Students and price-sensitive commuters exhibit highest price sensitivity; outdoor enthusiasts and corporate procurement departments demonstrate lowest sensitivity due to durability requirements and scope-three emissions accounting.
Supply Chain Analysis
Ocean freight rate fluctuations from Guangdong and Zhejiang provinces to European and North American distribution centers amplify landed cost variability for brand marketers without captive manufacturing. Double-wall vacuum sealing capacity concentrates in China, South Korea, and Germany, drawing from nickel ore processed in Indonesia and the Philippines. Single-source vulnerability clusters around helium leak detection equipment and specialized welding technician pools. Distribution runs through outdoor retail partnerships, direct-to-consumer platforms, and corporate facility management vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydration container margins expand through premium-tier thermal performance specialization and recurring replacement-part revenue, offsetting nickel cost volatility through subscription economics rather than unit pricing alone.
For Market Incumbents: Cement direct-to-consumer channel control by acquiring specialized vacuum-seal technician training programs and backward integration into 18/8 alloy sourcing. Counter emerging smart-enabled vessel entrants through Bluetooth-enabled hydration tracking partnerships with wellness app ecosystems. Prioritize LFGB and FDA food-contact certification investments to extend multi-jurisdiction market access timelines. For New Entrants and Emerging Players: EU Green Deal single-use plastic restrictions in Germany and France open a window for circular-designed vessels with take-back programs and recycled content certification. Target municipal refill station infrastructure expansion in Berlin, Munich, and Paris for premium reusable bottle placement. Pursue corporate wellness procurement channels in California and Washington where building code water access mandates intersect with sustainability targets. For Investors and Strategic Acquirers: Consolidation pressure builds where vacuum-seal technician scarcity constrains production scaling for mid-tier thermal vessel specialists. Five-to-ten-year viability favors brands with circular economy compliance infrastructure and smart hydration integration capabilities. Monitor ECHA substance evaluation timelines for migratory compound threshold tightening as inflection indicator for material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | YETI and Hydro Flask demonstrate margin protection through owned digital storefronts controlling pricing and customer data. |
| Smart Hydration Integration | Shenzhen electronics ecosystem enables Bluetooth-enabled UV-C purification modules converging with corporate wellness verticals. |
| Circular Design Certification | CSRD supply chain reporting requirements and French extended producer responsibility frameworks reward recycled content transparency. |
| Replacement Part Subscription Programs | Recurring revenue from gasket and lid replacements reduces customer acquisition costs and extends vessel lifecycle attachment. |
| Geographic Manufacturing Diversification | Bavarian precision clusters and South Korean metal forming reduce Guangdong concentration risk for vacuum-insulated production. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at outdoor retailers, supply planners at contract manufacturers, and sustainability officers at corporate procurement departments with secondary validation. Bottom-up vessel shipment data triangulated against top-down consumer spending patterns across Germany, the United States, China, France, and Japan. Secondary sources included customs and trade records, SEC filings from publicly traded container specialists, ECHA substance evaluation databases, and municipal refill station deployment statistics from Berlin and Munich planning authorities.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning product type, material composition, end-user activity, and capacity tier. CAGRs derived from fitted growth curves applied to normalized base-year consumption patterns, incorporating nickel price trajectory assumptions and EU packaging waste directive implementation schedules as industry-specific forecast inputs.
Revisions become necessary when ECHA migratory compound thresholds tighten beyond modeled scenarios or when municipal refill infrastructure deployment accelerates in unanticipated geographies. Forecasts reflect documented assumptions regarding stainless steel cost normalization and smart hydration adoption curves. A model refresh is warranted upon material change in extended producer responsibility framework enforcement across France, Italy, or Germany.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Paper Towel Dispenser Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Smart Bathtub Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Air Freshener Market
Household Items
Nebulizing Diffuser Market
Household Items
Dry Vacuum Cleaner Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Wipes Market
Household Items
Countertop Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
South Korea Cookware Market
Household Items
Cups and Pots Market
Household Items
Washing Capsules Market
Household Items
Smart Spin Mop Market