
 North America Secondary Wood Products Market | 2026-2036
North America Secondary Wood Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Secondary Wood Products Market Intelligence
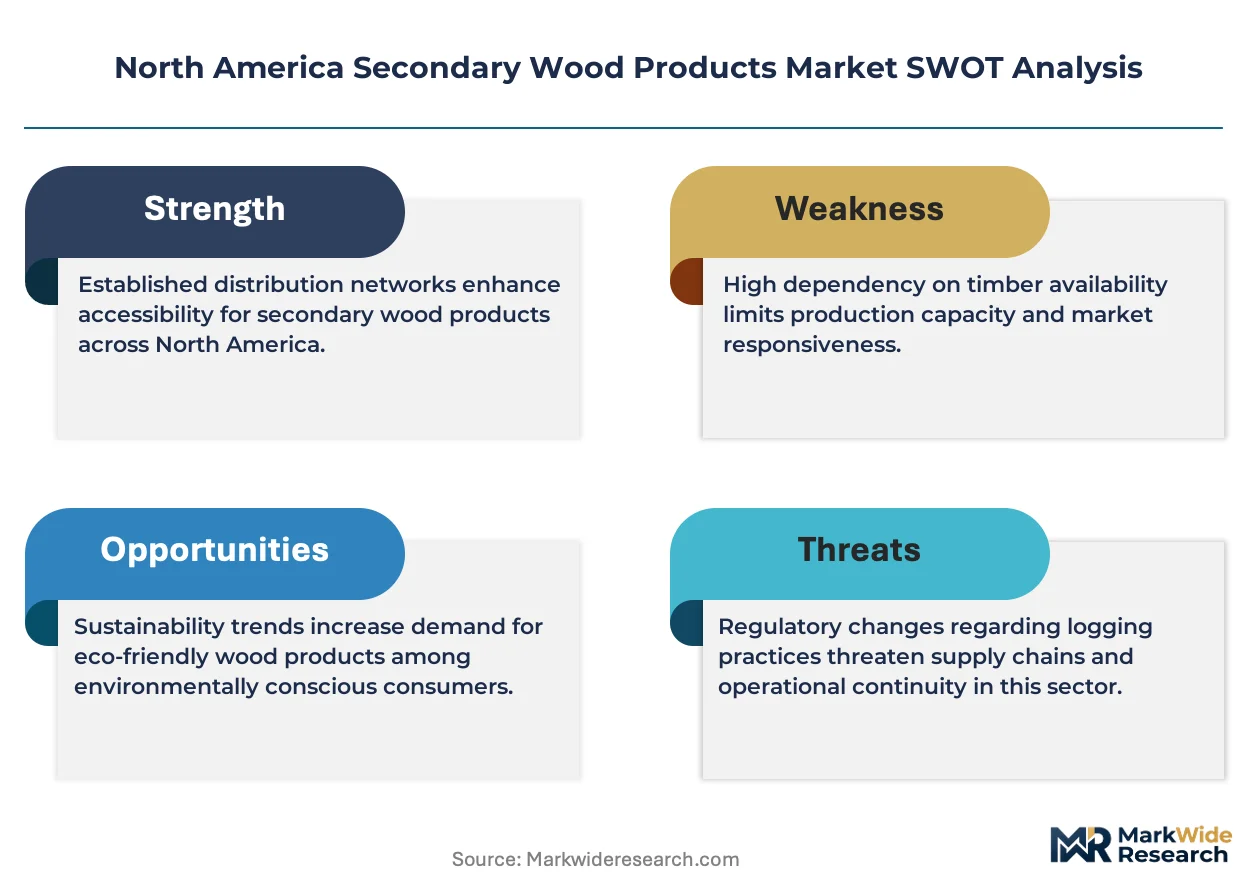
Cross-laminated timber is realigning cost structures for multi-story residential and commercial builds across North America. Weyerhaeuser Company leverages its Pacific Northwest timber base to supply certified structural panels for institutional projects. Ashley Furniture Industries anchors a vast procurement network across the Carolinas, securing particle board and medium density fibreboard volumes for case goods production. Herman Miller competes on premium office systems, sourcing engineered substrates that meet stringent indoor air quality protocols.
Secondary wood products encompass engineered panels and processed lumber derivatives manufactured from veneers, fibers, strands, or particles bonded under heat and pressure, typically with moisture-resistant adhesives meeting ANSI A208.1 or CSA O437.0 standards. These materials serve as structural substrates, furniture cores, and interior finish components across residential, commercial, and industrial construction. Plywood retains dominance in structural sheathing applications where wet-service ratings and span ratings govern specification, while oriented strand board captures share in floor and roof decking through cost-efficient production. Medium density fibreboard concentrates margin pools in specialty thin-board grades destined for laminated cabinetry and molded furniture components.
The International Building Code, administered by the International Code Council in the United States, together with Canada's National Building Code and the EPA Toxic Substances Control Act Title VI formaldehyde emissions standards, shape product certification requirements and market access for panel producers. State-level amendments in California through the Air Resources Board push emission thresholds below federal benchmarks, forcing reformulation of resins and adhesive systems. Stakeholders must monitor evolving ANSI/HPVA and CSA performance standards as cross-laminated timber and mass timber assemblies seek broader code recognition for taller building envelopes.
Market Dynamics
Cross-laminated timber adoption is compressing traditional steel and concrete specifications in mid-rise construction across the United States and Canada, forcing engineered panel producers to retool adhesive formulations and certification protocols for structural load-bearing applications.
Growth Catalysts
- Updated IRC/IBC building codes:The International Residential Code and International Building Code in the United States now permit mass timber in structures up to 18 stories, unlocking institutional and commercial verticals previously reserved for concrete and steel framing.
- Sun Belt residential construction:Population migration into southeastern and southwestern states is absorbing oriented strand board and plywood sheathing at volumes that sustain regional mill capacity utilization above break-even thresholds.
- Formaldehyde emission standards:EPA TSCA Title VI and California Air Resources Board Phase 2 limits are accelerating resin system reformulation toward phenol-formaldehyde and soy-based alternatives that qualify for LEED and WELL building certifications.
Market Restraints
- Adhesive input cost volatility:Methanol and phenol prices track crude oil and natural gas benchmarks, compressing margins for medium density fibreboard producers when energy markets spike without corresponding panel price pass-through mechanisms.
- Pacific Northwest supply concentration:Douglas fir veneer availability concentrates in Oregon and Washington state operations, exposing plywood manufacturers to wildfire disruption and rail logistics bottlenecks through the Cascade corridor.
- Structural steel substitution threat:Cold-formed steel framing retains cost advantages in high-wind and seismic zones where building officials impose conservative mass timber connection detailing requirements.
Strategic Opportunities
- Canadian tall wood building mandates:British Columbia and Quebec provincial codes are advancing toward 12-story mass timber permissions ahead of U.S. adoption curves, positioning cross-border producers for early-mover specification capture.
- Prefabricated panel integration:Offsite construction modules incorporating pre-cut engineered wood components are penetrating multifamily and hospitality verticals, demanding precision-manufactured subfloor and wall assemblies.
- Biogenic carbon accounting:Emerging green building standards that credit stored atmospheric carbon in wood products are electrifying architect and developer preference for mass timber in corporate and educational portfolios.
Industry Challenges
- Mass timber engineering talent scarcity:Structural designers proficient in CLT and glulam connection detailing remain concentrated in Pacific Northwest and Nordic consulting practices, constraining project pipeline expansion.
- Plant retooling capex intensity:Converting legacy particle board lines to thin-board medium density fibreboard grades for laminated cabinetry requires press rebuilds and continuous belt investments exceeding standard maintenance cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Secondary Wood Products Market |
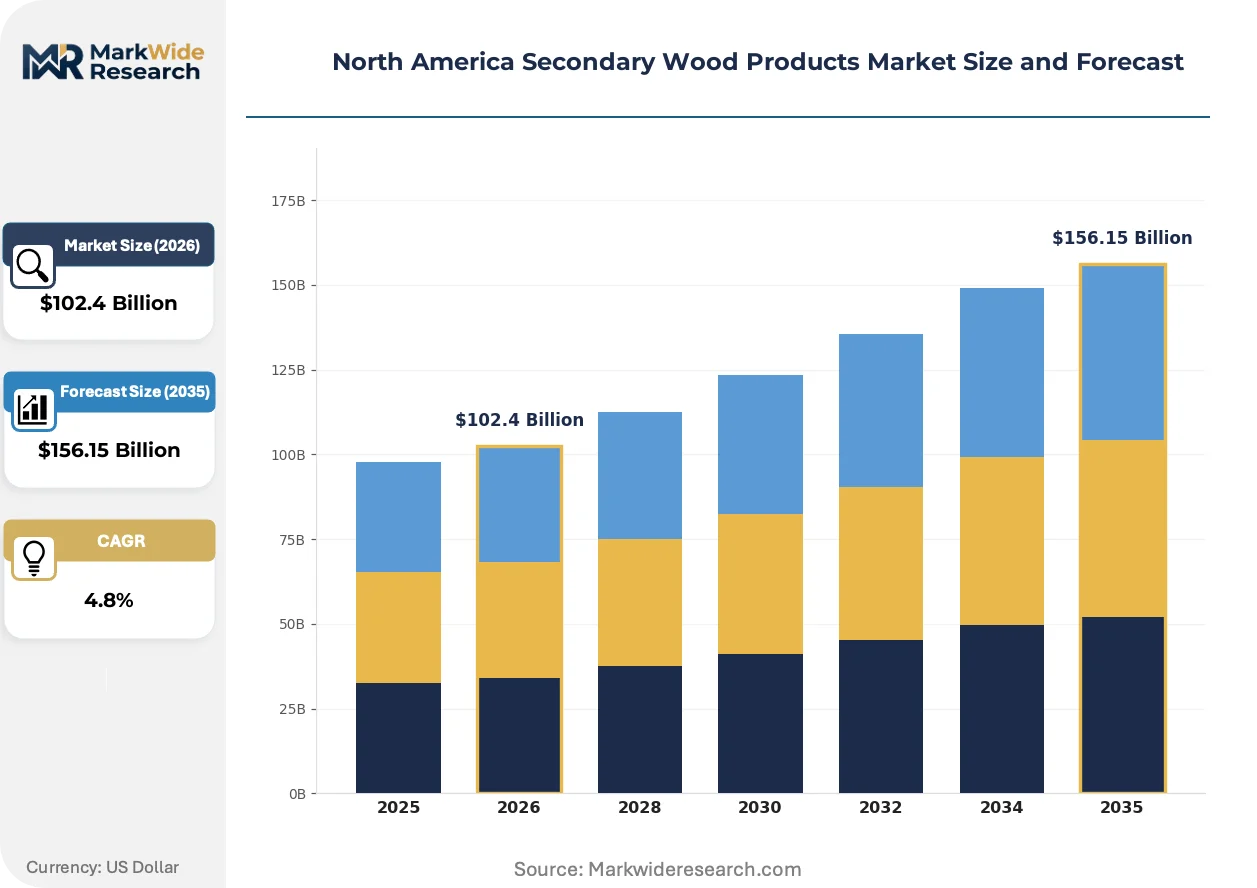
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $156.15 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, Particle Board, Medium Density Fibreboard, Oriented Strand Board End User: Furniture Manufacturers, Construction, Cabinet Makers, Flooring Installers Application: Residential Use, Commercial Use, Interior Decoration, Industrial Applications Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale Distributors |
| Companies Covered | Herman Miller, IKEA, Ashley Furniture Industries, La-Z-Boy, Masco Corporation, Steelcase, Weyerhaeuser Company, Ethan Allen, HNI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Secondary Wood Products Market Strategic Shifts & Innovations
Digital fabrication and automated pressing controls are compressing specification cycles between architectural design and mill production, while regulatory harmonization efforts across U.S. and Canadian jurisdictions are standardizing performance testing protocols for structural wood products.
Hybrid cross-laminated timber-concrete composite floor systems are electrifying mid-rise construction economics by reducing structural depth and enabling longer clear spans without intermediate columns. Developers in Vancouver, Seattle, and Minneapolis are specifying these assemblies for office and residential mixed-use projects. The technology is compressing floor-to-floor heights and mechanical routing complexity, delivering rentable area gains that offset premium material costs.
The International Code Council's introduction of mass timber construction types in the 2021 and 2024 IBC cycles is mandating fire resistance ratings and encapsulation methods that diverge from traditional heavy timber precedents. Manufacturers must submit new qualification testing data to ICC-ES and Canadian Construction Materials Centre evaluators. Southeastern U.S. jurisdictions adopting these provisions are experiencing specification lag as local building officials await state-level amendment adoptions.
Direct mill-to-developer procurement contracts are displacing traditional two-step distribution through lumberyard intermediaries for large multifamily and commercial projects. Volume buyers in Texas, Florida, and Georgia are negotiating panel package pricing with engineered wood producers for 500-plus unit developments. This channel compression is most visible in the Sun Belt, where vertical integration between regional mills and national homebuilders is tightening specification control and compressing lead time variability.
North America Secondary Wood Products Market Segmentation
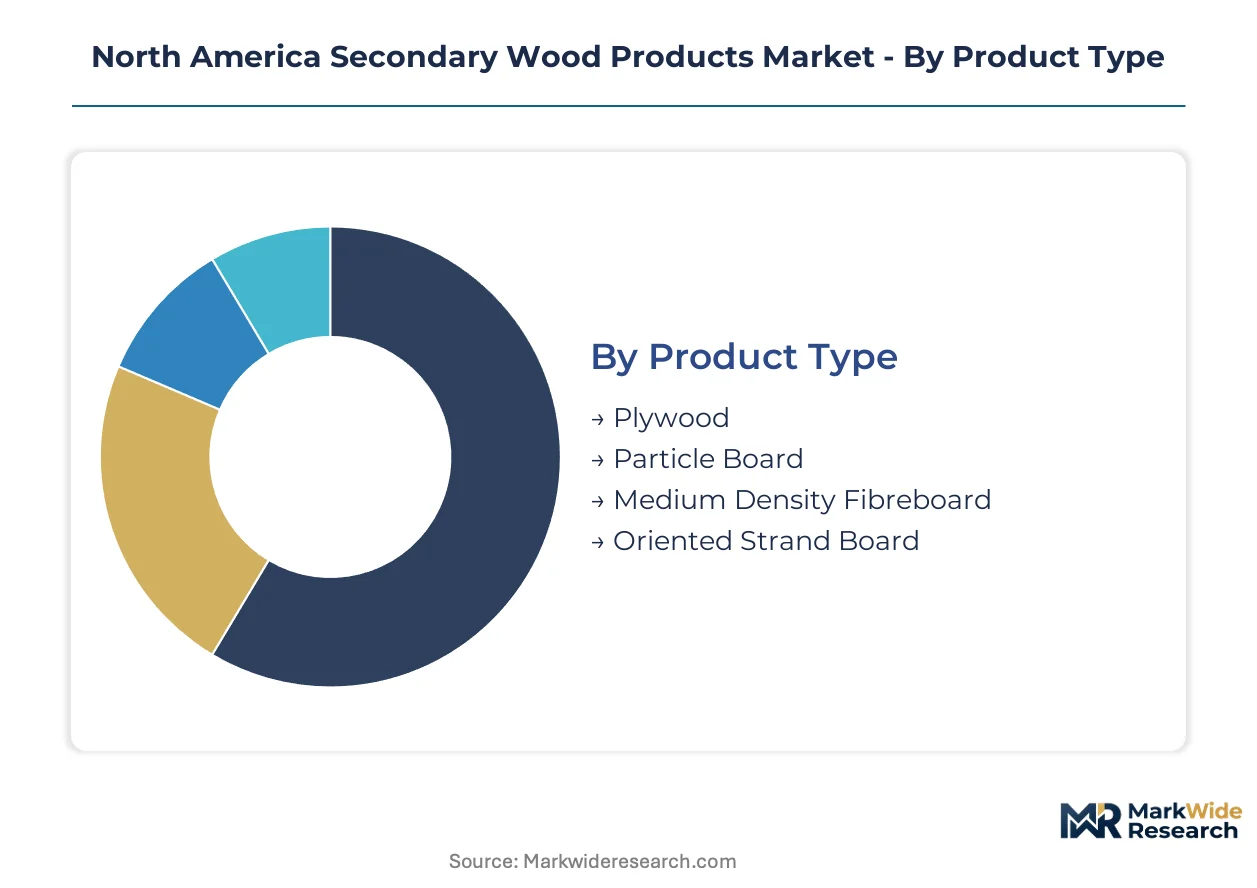
Secondary wood products serve distinct performance requirements across structural, aesthetic, and industrial applications. Specification cycles differ sharply between new construction and replacement demand, with product lifecycles spanning decades in structural uses versus 7-12 year refresh rates in furniture manufacturing.
Product Type:
Upgrade cycles vary dramatically across engineered panel categories, with structural sheathing replacement driven by code-mandated performance thresholds while furniture substrates track interior design trend velocities.
- Plywood:Cross-banded veneer construction delivers wet-service ratings and span-rated structural performance for roof and wall sheathing. Demand concentrates in hurricane-prone Gulf Coast states where IRC wind uplift requirements specify plywood over OSB for roof decking in high-velocity zones.
- Oriented Strand Board:Mat-formed wood strands bonded with phenol-formaldehyde resins provide cost-efficient floor and roof decking. Sun Belt residential construction absorbs OSB volumes at rates sustaining southeastern mill capacity above break-even thresholds through single-family housing cycles.
- Particle Board:Wood particles bonded with urea-formaldehyde serve as economical furniture cores and underlayment. California Air Resources Board Phase 2 emission limits are forcing resin reformulation toward lower-formaldehyde systems.
- Medium Density Fibreboard:Refined wood fiber matrices enable precision-machined edges and smooth surfaces for laminated cabinetry. North Carolina and Georgia furniture clusters source thin-board grades for case goods production.
Volume placements concentrate in Oriented Strand Board; the faster expansion belongs to Medium Density Fibreboard.
End User:
Cost-tier segmentation separates commodity specification from premium performance requirements, with certification-grade demand commanding 15-25% price premiums over standard grades.
- Furniture Manufacturers:High-volume procurement of particle board and MDF for case goods, upholstery frames, and ready-to-assemble products. LEED and WELL building certifications are elevating indoor air quality specifications for corporate and hospitality furniture.
- Construction:Structural sheathing, subflooring, and wall panels for residential and commercial builds. IRC/IBC code updates permitting mass timber in mid-rise structures are expanding engineered wood specifications for institutional verticals.
- Cabinet Makers:Moisture-resistant MDF and plywood grades for kitchen and bath installations. Direct mill relationships are compressing lead times for custom fabrication shops.
- Flooring Installers:Underlayment panels and engineered hardwood substrates. Prefinished flooring systems are shifting specification control from distributors to national flooring brands.
Construction absorbs the largest volume share; furniture manufacturers are climbing the fastest as reshoring trends rebuild North American production capacity.
Application:
Application-based demand patterns reflect divergent durability requirements, with residential replacement cycles of 20-30 years contrasting commercial refresh rates of 7-10 years.
- Residential Use:Structural sheathing, subflooring, and interior finish materials for single-family and multifamily construction. Sun Belt population migration is sustaining above-average absorption rates in Texas, Florida, and Arizona markets.
- Commercial Use:Office, retail, and hospitality installations requiring fire-rated and acoustic-rated assemblies. Mass timber code permissions are penetrating corporate and educational portfolios through biogenic carbon accounting incentives.
- Interior Decoration:Wall paneling, molding, and architectural millwork. Design-driven specification cycles track shorter trend horizons than structural applications.
- Industrial Applications:Pallets, crating, and manufacturing fixtures. Cost minimization dominates specification with lower-grade particle board and OSB substitutes.
Residential Use maintains volume dominance; Commercial Use shows the steepest expansion trajectory as mass timber codes mature.
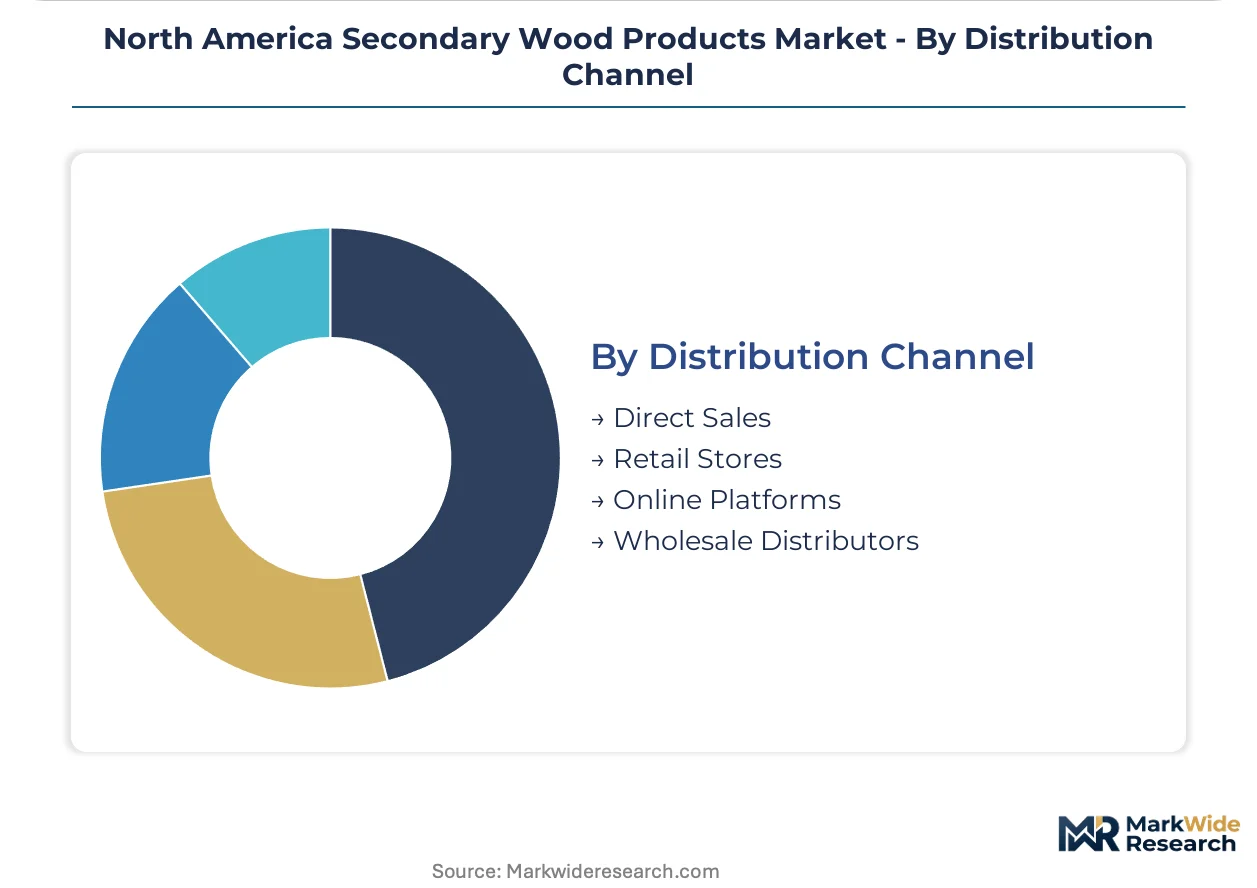
Distribution Channel:
Channel configuration reflects project scale and specification complexity, with large developments bypassing intermediaries while smaller orders retain traditional two-step distribution.
- Direct Sales:Mill-to-developer contracts for 500-plus unit multifamily and commercial projects. Texas and Florida markets exhibit the most pronounced channel compression.
- Wholesale Distributors:Regional lumberyards and building material dealers serving mid-size contractors. Inventory carrying costs are pressuring distributor margins during interest rate cycles.
- Retail Stores:Home center and pro-dealer channels for repair, remodel, and small contractor demand. Big-box retailers are consolidating specification influence through private-label engineered wood programs.
- Online Platforms:Emerging channel for specialty grades and hard-to-source specifications. Fulfillment complexity limits penetration for bulky, weight-intensive panel products.
Wholesale Distributors retain the largest volume placement; Direct Sales channels are gaining share fastest among national homebuilders and institutional developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for secondary wood products concentrates in the southeastern United States, where furniture manufacturing clusters and residential construction absorb engineered panels at rates sustaining regional mill operations above break-even thresholds.
United States
Single-family housing starts across Texas, Florida, and Georgia drive oriented strand board consumption for subflooring and wall sheathing applications. The International Building Code, administered by the International Code Council, now permits mass timber structures up to 18 stories, unlocking institutional verticals for cross-laminated timber specifications. Ashley Furniture Industries anchors procurement networks across North Carolina and Georgia, securing particle board and medium density fibreboard volumes for case goods production.
Canada
British Columbia and Quebec provincial codes are advancing 12-story mass timber permissions ahead of U.S. adoption curves, positioning domestic producers for early-mover specification capture. Health Canada and the Canadian Construction Materials Centre evaluate qualification testing data for structural wood products entering the National Building Code. Weyerhaeuser Company leverages its Pacific Northwest timber base to supply certified structural panels for institutional projects across Vancouver and Toronto metropolitan areas.
Mexico
Export-oriented furniture manufacturing in Jalisco and Nuevo León absorbs medium density fibreboard for ready-to-assemble products destined for U.S. retail channels. The Secretariat of Economy oversees industrial standards alignment with North American Free Trade Agreement successor provisions. Guadalajara-based fabricators are expanding particle board lamination capacity to serve hospitality and residential interior contracts.
North America Secondary Wood Products Market Key Industry Players
Capacity expansion dominates the current landscape as engineered wood producers retool adhesive formulations and certification protocols for structural load-bearing applications. The vendor base separates into three distinct tiers: integrated timberland-to-panel operators controlling raw material sourcing, specialized furniture substrate manufacturers serving regional procurement networks, and mass timber technology specialists pursuing code-permitted vertical construction. M&A activity and geographic expansion represent the two dominant competitive moves, with producers acquiring regional mills to secure veneer supply and establishing direct mill-to-developer sales channels in Texas and Florida markets.
Among U.S.-based operators, Herman Miller occupies a position exemplifying premium office systems specification, sourcing engineered substrates that meet stringent indoor air quality protocols. Steelcase and HNI Corporation represent the scale-driven tier, anchoring corporate and institutional furniture procurement networks across North American metropolitan markets. These three companies illustrate divergent competitive positioning within the same end-use vertical.
| Leading Market Players |
|---|
| Herman Miller |
| IKEA |
| Ashley Furniture Industries |
| La-Z-Boy |
| Masco Corporation |
| Steelcase |
| Weyerhaeuser Company |
| Ethan Allen |
| HNI Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap producers across the southeastern United States anchor supply discipline through generational timberland holdings and captive veneer operations, translating raw material control into pricing power that resists spot-market volatility during housing downturns. Their long-tenured relationships with Carolina furniture clusters and Texas homebuilders enable contract-based offtake structures that buffer against adhesive cost spikes.
Pricing Analysis
Volume placements in oriented strand board compress margins through commodity spot exposure, while thin-board medium density fibreboard grades command certification-linked premiums for indoor air quality compliance. Price differentiation hinges on CARB Phase 2 and EPA TSCA Title VI emission tier attainment plus volume-scale procurement commitments from national homebuilders. Cost compression in structural sheathing intensifies because methanol and phenol input costs track energy benchmarks without full pass-through elasticity. Multifamily developers exhibit acute price sensitivity, whereas institutional projects with LEED mandates absorb premium grades with limited negotiation leverage.
Supply Chain Analysis
ICC-ES and Canadian Construction Materials Centre qualification gating constrains supplier entry, with certification timelines filtering out speculative capacity additions. Douglas fir veneer concentrates in Oregon and Washington, phenol-formaldehyde resins draw from Gulf Coast petrochemical complexes, and MDF fiber feedstocks cluster in Georgia and North Carolina pulp operations. Single-source vulnerability runs through Cascade corridor rail logistics where wildfire disruption and tunnel maintenance create chokepoints. Distribution runs through wholesale lumberyard networks for mid-size contractors, though direct mill-to-developer contracts are compressing intermediary layers in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-laminated timber technology is displacing legacy steel and concrete specifications in mid-rise construction, creating a generational retooling window for engineered wood producers. Stakeholders must position for code-permitted vertical expansion while defending against input cost volatility and substitution threats.
For Market Incumbents: Cement specification control through captive Douglas fir veneer supply in the Pacific Northwest and phenol-formaldehyde resin backward integration to offset methanol price spikes. Defend against cold-formed steel substitution in seismic zones by accelerating ICC-ES fire-rated assembly certifications that satisfy conservative building official requirements. For New Entrants and Emerging Players: Custom cabinet fabrication shops represent an underserved buyer archetype bypassed by volume-focused national distributors. Penetrate this segment through moisture-resistant MDF grades with compressed lead times and direct mill relationships. Target the prefabricated panel integration channel for multifamily offsite construction modules, where precision-manufactured subfloor assemblies face limited qualified supply. For Investors and Strategic Acquirers: British Columbia and Quebec provincial code adoption of 12-story mass timber permissions is the leading indicator that Canadian producers will capture early-mover specification premiums ahead of U.S. jurisdictions. Frame long-term viability around biogenic carbon accounting integration into corporate and educational portfolios, with acquisition focus on CLT technology specialists possessing ICC-ES evaluation reports and established architect specification relationships. Watch for state-level IBC amendment adoption velocity as the signal for demand inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Formulation Reformulation | EPA TSCA Title VI and CARB Phase 2 compliance unlocks LEED-specified institutional projects. |
| Mass Timber Certification Investment | ICC-ES and CCMC evaluation reports enable code-permitted 18-story structural applications. |
| Direct Mill-to-Developer Channel Expansion | Texas and Florida volume contracts compress lead time variability for 500-plus unit developments. |
| Prefabricated Panel Integration | Offsite construction modules penetrate multifamily verticals demanding precision subfloor assemblies. |
| Biogenic Carbon Accounting Positioning | Stored atmospheric carbon credits electrify architect preference in corporate and educational portfolios. |
Research Approach
Independent corroboration across engineered wood producer procurement directors, Carolina furniture manufacturing plant managers, and Texas multifamily developer project executives underwrites the qualitative findings. Secondary validation draws from EPA TSCA Title VI certification databases, ICC-ES evaluation report filings, U.S. Census Bureau housing starts data, and ANSI/HPVA performance standard documentation. Bottom-up demand modeling triangulates against top-down capacity utilization assessments across Pacific Northwest and southeastern mill operations.
Comparable-period anchoring to historical single-family housing cycles and mass timber code adoption trajectories structures the projection methodology across the analysis window. Segmentation dimensions include product type, end-user vertical, application durability requirements, and distribution channel configuration, with CAGRs derived from housing start elasticity coefficients and furniture production reshoring rates. Forecast inputs incorporate adhesive input cost correlation models and state-level IBC amendment adoption schedules.
Revisions become necessary when wildfire disruption severity exceeds historical Cascade corridor baselines or when provincial code adoption curves diverge from modeled trajectories. Forecasts reflect documented assumptions regarding methanol-phenol price pass-through elasticity and mass timber engineering talent pipeline expansion. A model refresh is warranted upon material change in IRC/IBC tall wood building provisions or EPA formaldehyde emission standard amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
US Contract Furniture and Furnishing Market
Furniture
United States Home Furniture Market
Furniture
Europe Outdoor Furniture Market
Furniture
Furniture Laminate Market
Furniture
India Upholstered Furniture Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Spain Furniture Market
Furniture
Kids Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
Europe Bamboo Furniture Market
Furniture
Outdoor Furniture and Grills Market
Furniture
Global Folding Furniture Market
Furniture
Kids Storage Furniture Market
Furniture
France Furniture Market
Furniture
UAE Home Furniture Market
Furniture
Europe Home Furniture Market