
 Home Furnishings Market | 2026-2036
Home Furnishings Market Size, Share, and Industry Trends Forecast 2026-2036
Home Furnishings Market Outlook
Artisan upholstery craftworkers is reorganizing supply chains across the home furnishings sector as hand-finished furniture commands sustained premiums. IKEA leverages flat-pack logistics to dominate mass-market penetration across continents. Wayfair anchors North American e-commerce demand through data-driven curation of third-party catalogs. Ashley Furniture Industries sustains domestic manufacturing scale while competing on delivery velocity against import-heavy rivals.
Home furnishings encompass movable and fixed interior assets—sofas, cabinetry, window treatments, and luminaires—typically specified by dimensional tolerance, fire-resistance rating, and volatile organic compound emission thresholds to ensure habitability and safety in built environments. The furniture segment within product type captures the largest revenue pool due to replacement cycles tied to housing turnover, while textiles is accelerating fastest as consumers prioritize layered, seasonal refresh of living spaces over full-room overhauls. Wood dominates material composition for structural pieces, though metal is gaining share in minimalist and industrial-aesthetic categories where weld precision and powder-coat durability matter.
EPA formaldehyde emission standards and California Air Resources Board Phase 2 compliance constrain panel-product sourcing for US manufacturers, while EU REACH restrictions on azo dyes and flame retardants redirect textile procurement toward certified supply bases. Stakeholders must monitor evolving state-level chemical disclosure laws and building code amendments that will determine which material certifications become table stakes for market access.
Market Dynamics
REACH compliance in Europe and California Air Resources Board Phase 2 standards are forcing material substitutions across upholstery foam, engineered wood, and textile treatments, compressing supplier margins while opening certified supply bases to first movers.
Growth Catalysts
- REACH chemical restrictions:EU azo dye and flame-retardant limits redirect procurement toward certified Turkish and Portuguese textile mills, creating tiered supply access.
- Urban middle-class expansion:Tier-2 and Tier-3 Chinese cities are driving premium furniture consumption as household formation rates outpace developed markets.
- Flat-pack logistics optimization:Container density improvements and last-mile assembly models reduce landed cost per unit for cross-border e-commerce fulfillment.
Market Restraints
- Panel-product sourcing constraints:EPA formaldehyde emission standards limit US manufacturer access to low-cost Southeast Asian composite wood suppliers.
- Artisan labor scarcity:European upholstery craftworker pipelines have contracted, extending lead times for hand-finished furniture by 40-60 days.
- Freight rate volatility:Trans-Pacific container pricing swings compress working capital cycles for import-dependent retailers.
Strategic Opportunities
- Indian organized retail penetration:Furniture and home décor mall formats in Bangalore, Hyderabad, and Pune remain underdeveloped relative to saturated Chinese urban cores.
- Textile-to-furniture bundling:Coordinated seasonal refresh programs linking window treatments, throws, and accent seating capture higher basket values than standalone furniture sales.
- EU Green Deal circularity mandates:Take-back and refurbishment requirements create reverse-logistics revenue streams for durable goods retailers.
Industry Challenges
- Flame-retardant certification timelines:California Bureau of Electronic and Appliance Repair standards evolution requires 12-18 month product recertification cycles.
- Legacy ERP integration:Real-time inventory visibility across flat-pack SKUs demands middleware investment that mid-market distributors struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Furnishings Market |
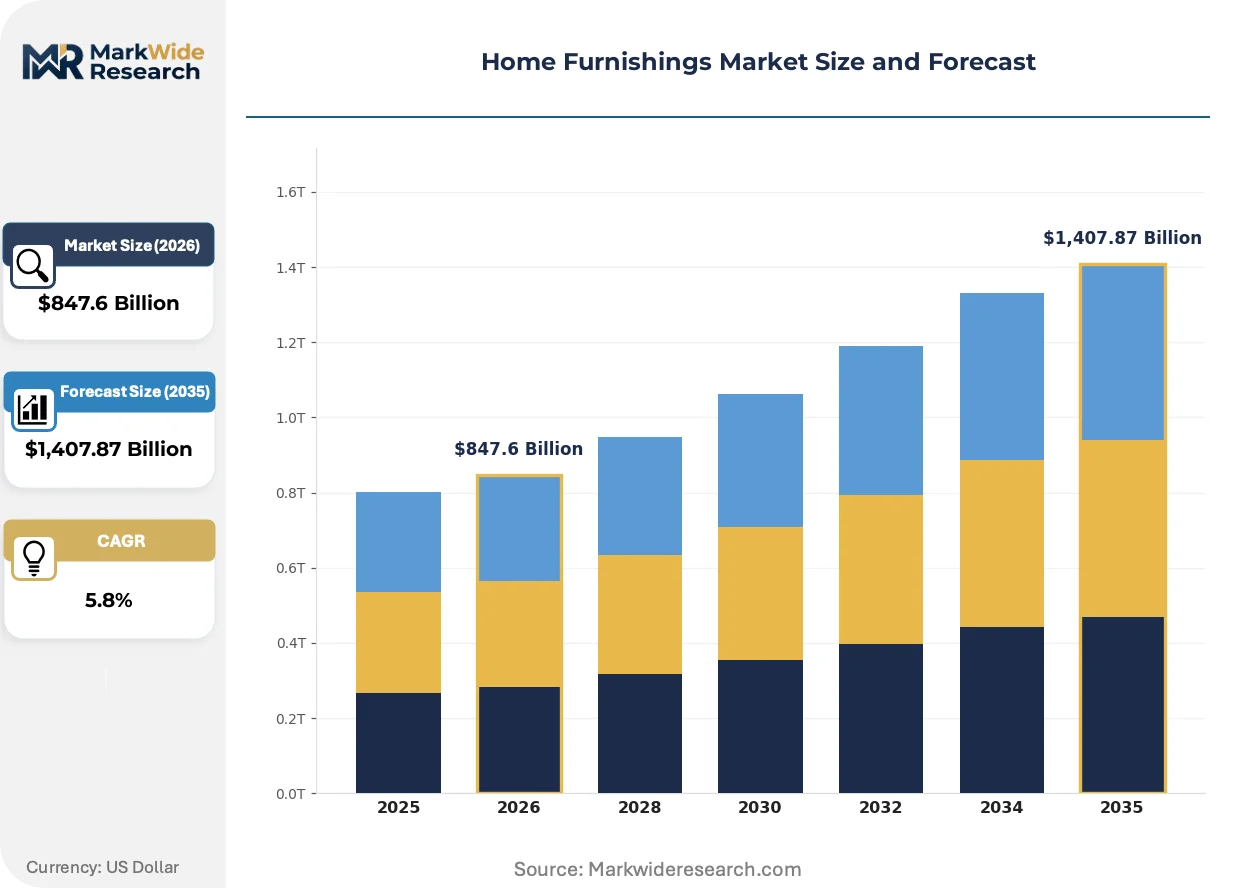
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,407.87 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Textiles, Lighting, Décor Material: Wood, Metal, Glass, Fabric End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online, Retail, Wholesale, Direct |
| Companies Covered | IKEA, Wayfair, Ashley Furniture Industries, Williams-Sonoma, The Home Depot, Lowe's Companies, Mohawk Industries, West Elm, Crate & Barrel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Furnishings Market Strategic Shifts
Three forces are restructuring competitive advantage: digital fabrication compressing prototyping cycles, chemical disclosure mandates fragmenting supplier pools, and rental-subscription models displacing ownership in urban cores.
Generative design software paired with CNC routing is decomposing traditional furniture prototyping from months to weeks. Small-batch manufacturers in North Carolina and Veneto are adopting these tools to serve interior designers with bespoke dimensions at near-mass-market lead times. The technology is decomposing the historical tradeoff between customization velocity and unit economics.
California Air Resources Board Phase 2 compliance and evolving state-level chemical disclosure laws are tightening panel-product sourcing. US manufacturers now face dual tracking of EPA formaldehyde thresholds and emerging PFAS restrictions. Upholstery foam and engineered wood suppliers serving the West Coast market are consolidating around certified domestic mills to reduce audit burden.
Subscription-based furniture access is gaining traction among metropolitan renters in Berlin, Tokyo, and New York. Feather and similar platforms unbundle ownership from use, compressing replacement cycles and shifting residual value risk to operators. This model concentrates demand for durable, modular designs that withstand repeated install cycles.
Home Furnishings Market Segmentation
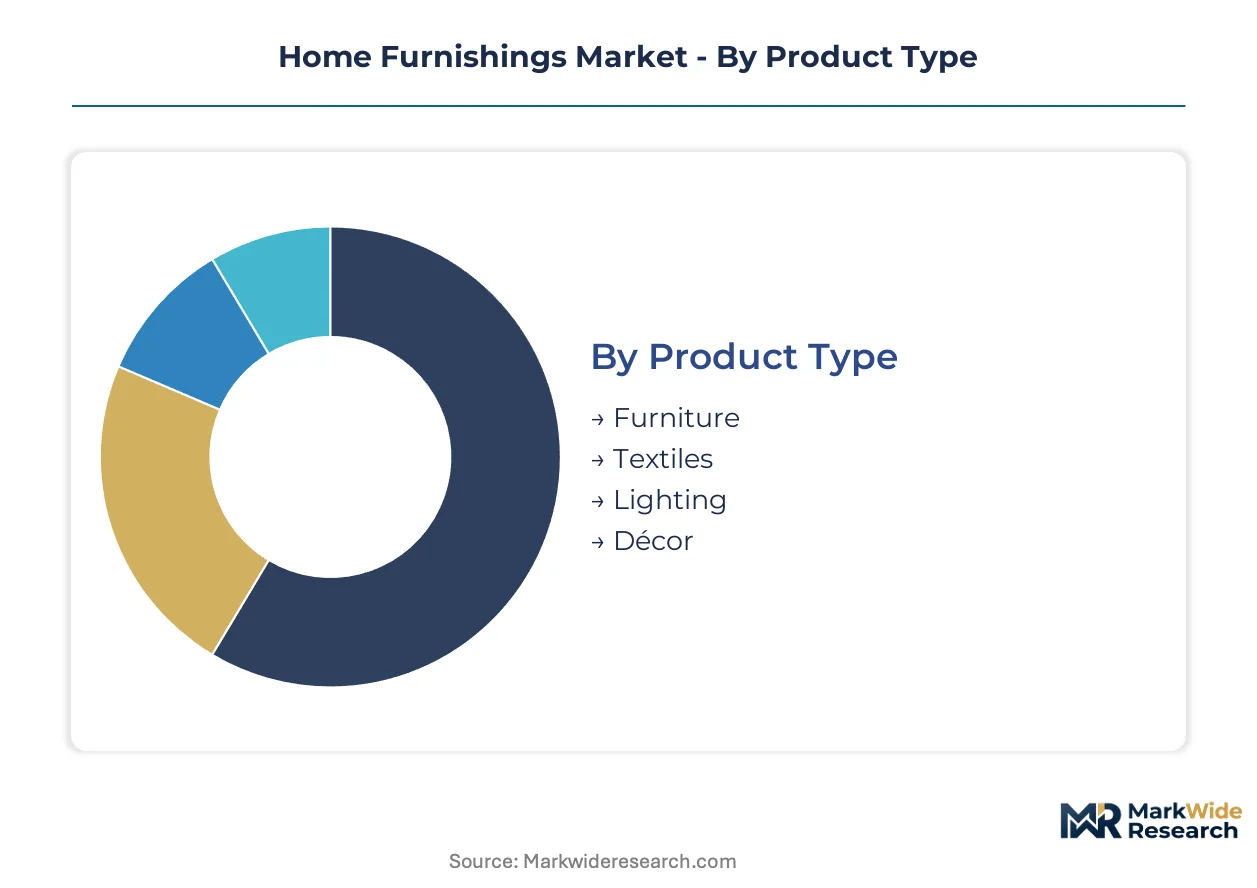
Segmentation in home furnishings reveals how regulatory pressure and logistics economics reshape competitive boundaries. Substitution threats vary sharply across material and channel categories, determining which specifications become mandatory for market access.
Product Type:
Furniture faces intensifying substitution pressure from rental-subscription platforms in urban cores, while textiles compete against fast-fashion home collections with compressed refresh cycles.
- Furniture:Structural pieces specified by dimensional tolerance, fire-resistance rating, and formaldehyde emission thresholds. Demand concentrates in suburban residential markets across the United States and China, where housing turnover drives replacement cycles. EPA and California Air Resources Board Phase 2 compliance constrain panel-product sourcing.
- Textiles:Layered soft goods including window treatments, throws, and upholstery fabrics. European REACH azo dye and flame-retardant restrictions redirect procurement toward certified Turkish and Portuguese mills, compressing supplier margins.
- Lighting:Luminaires and fixtures governed by electrical safety and energy efficiency standards.
- Décor:Accent pieces and ornamental objects with shorter purchase intervals.
Furniture anchors the volume base while textiles gains share at the steepest rate.
Material:
Cost tier differentiation separates structural materials facing certification burdens from aesthetic materials competing on design velocity.
- Wood:Dominates structural composition for cabinetry and seating frames. Demand concentrates in North American and European markets where sustainable forestry certification influences specification. Replacement cycles tie directly to housing transaction volume.
- Metal:Gaining share in minimalist and industrial-aesthetic categories where weld precision and powder-coat durability matter. Chinese and German manufacturers lead production scale.
- Glass:Tabletops and decorative elements requiring tempering standards.
- Fabric:Upholstery and drapery subject to flame-retardant certification timelines.
Wood retains the largest installed base while metal climbs the fastest among material alternatives.
End User:
Application context determines compliance burden intensity, with hospitality and office segments facing stricter fire-safety and durability specifications than residential.
- Residential:Individual households in suburban United States and tier-2 Chinese cities scaling furniture and décor purchases. California Bureau of Electronic and Appliance Repair standards and evolving state-level chemical disclosure laws shape product development.
- Commercial:Retail and public space furnishings with accelerated wear profiles.
- Hospitality:Hotel and restaurant specifications demanding commercial-grade durability certifications.
- Office:Workplace furniture subject to ergonomic and safety standards in corporate procurement.
Residential anchors the volume base while hospitality expands most quickly as global travel recovers.
Distribution Channel:
Customer type fragmentation separates inventory-heavy retail from asset-light digital models, with divergent working capital requirements.
- Online:Data-driven curation and flat-pack logistics optimization reduce landed cost per unit for cross-border fulfillment. North American and European consumers drive demand concentration.
- Retail:Physical showrooms in underdeveloped Indian urban cores remain expansion targets.
- Wholesale:Bulk procurement for commercial and hospitality project specification.
- Direct:Manufacturer-to-consumer models bypassing intermediary margin layers.
Online anchors the volume base while direct channels gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home furnishings consumption patterns diverge sharply by geography: suburban households in the United States prioritize replacement cycles tied to housing turnover, while Chinese buyers concentrate premium spending in tier-2 urban cores, and European procurement teams navigate REACH chemical restrictions that reshape supplier access.
United States
Suburban residential markets in Texas and Florida drive furniture replacement demand as housing transaction volumes recover. EPA formaldehyde emission standards and California Air Resources Board Phase 2 compliance constrain panel-product sourcing from Southeast Asian suppliers. North Carolina's Piedmont Triad anchors domestic upholstery manufacturing, where craftworker scarcity extends hand-finished furniture lead times.
China
Urban middle-class households in Chengdu, Wuhan, and Xi'an scale premium furniture purchases as household formation outpaces developed markets. MIIT industrial standards and dual carbon goals redirect manufacturing investment toward certified sustainable forestry supply chains. The Pearl River Delta cluster around Dongguan and Foshan dominates metal-frame and minimalist-aesthetic production for export and domestic consumption.
Germany
EU Green Deal circularity mandates and ECHA REACH restrictions on azo dyes compress textile supplier margins while opening certified Portuguese and Turkish mills to first movers. The North Rhine-Westphalia corridor around Cologne and Düsseldorf concentrates flat-pack logistics optimization and last-mile assembly infrastructure for cross-border e-commerce fulfillment.
India
Organized retail penetration in Bangalore, Hyderabad, and Pune remains underdeveloped relative to saturated Chinese urban cores, creating expansion targets for furniture and home décor mall formats. BIS certification requirements and DGFT import policies shape material sourcing strategies for domestic manufacturers. The Mumbai-Pune industrial belt anchors engineered wood and metal fabrication capacity serving western India demand.
United Kingdom
London metropolitan renters drive subscription-based furniture access models that compress replacement cycles and shift residual value risk to operators. CSRD sustainability disclosure requirements and evolving building code amendments determine which material certifications become mandatory for commercial project specification. The Midlands manufacturing corridor around Nottingham and Leicester sustains textile upholstery and window treatment production.
Home Furnishings Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with flat-pack logistics optimizers and data-driven curators commanding distinct competitive vectors. The market structure separates inventory-heavy retailers with showroom networks from asset-light digital platforms that reduce working capital intensity through third-party fulfillment. Three archetypes dominate: Scandinavian-origin mass-market penetrators, North American e-commerce aggregators, and domestic manufacturing scale players competing on delivery velocity. Competitive moves concentrate on flat-pack logistics optimization and certified supply base consolidation.
Among mass-market penetrators, IKEA exemplifies the flat-pack logistics archetype through continental-scale distribution density. Wayfair and Ashley Furniture Industries occupy positions on the digital-native and domestic-manufacturing vectors respectively, with the former anchoring data-driven curation of third-party catalogs and the latter sustaining North American production scale against import-heavy rivals.
| Leading Market Players |
|---|
| IKEA |
| Wayfair |
| Ashley Furniture Industries |
| Williams-Sonoma |
| The Home Depot |
| Lowe's Companies |
| Mohawk Industries |
| West Elm |
| Crate & Barrel |
| Others |
Value Chain & Pricing Dynamics
Forty-to-sixty day lead-time extensions for hand-finished upholstery compress working capital cycles and amplify pricing power for certified European craftworkers, while container density improvements in flat-pack logistics create divergent cost structures between mass-market and artisan tiers.
Pricing Analysis
Long-term offtake contracts with certified Turkish and Portuguese textile mills anchor premium-tier pricing stability, while spot-market procurement for Southeast Asian panel products exposes mid-market manufacturers to formaldehyde-compliance cost volatility. Price differentiation hinges on REACH certification grade and California Air Resources Board Phase 2 compliance status, with certified domestic mills commanding sustained premiums over uncertified imports. Pricing pressure intensifies in the mass-market furniture tier as flat-pack logistics optimization erodes landed-cost advantages for traditional container-shipped finished goods. Residential buyers in suburban United States markets exhibit highest price sensitivity, while hospitality procurement teams prioritize durability certifications over unit cost.
Supply Chain Analysis
Trans-Pacific container availability fluctuations and Pearl River Delta port congestion elevate inbound logistics costs for North American retailers sourcing metal-frame and minimalist-aesthetic production. Manufacturing gravity centers on China for metal fabrication, Vietnam for engineered wood components, and Portugal for certified textile upholstery. Raw material dependencies encompass sustainable forestry-certified timber, low-emission resin systems, and azo-dye-compliant fabric treatments. Single-source vulnerability concentrates in Southeast Asian composite wood suppliers facing EPA formaldehyde emission exclusions. Distribution runs through flat-pack logistics hubs in North Rhine-Westphalia for European fulfillment and direct-to-consumer platforms for metropolitan rental-subscription demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home furnishings sector sits in early-cycle expansion as subscription-based furniture access models penetrate metropolitan rental markets and compress traditional replacement cycles.
For Market Incumbents: Secure certified supply base consolidation around REACH-compliant Portuguese and Turkish textile mills before compliance timelines harden into structural bottlenecks. Deepen backward integration into sustainable forestry certification to reduce panel-product sourcing exposure against Southeast Asian supplier exclusions. Prioritize flat-pack logistics density investments in underdeveloped Indian urban cores where organized retail penetration trails Chinese saturation levels. For New Entrants and Emerging Players: Anchor in Bangalore, Hyderabad, and Pune mall-format expansion corridors where furniture and home décor retail infrastructure remains underdeveloped relative to tier-2 Chinese cities. Target textile-to-furniture bundling programs that capture higher basket values through coordinated seasonal refresh offerings. Pursue direct-to-consumer digital-native positioning with data-driven curation models that bypass incumbent showroom capital intensity. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because EU Green Deal take-back and refurbishment mandates will concentrate residual value capture among operators with reverse-logistics capabilities. Acquisition targets should emphasize certified supply base access and modular design IP suited to repeated install cycles. Watch California Bureau of Electronic and Appliance Repair standards evolution as the inflection signal determining which material certifications become mandatory for West Coast market access.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Supply Base Consolidation | REACH and CARB Phase 2 compliance lock in tiered supplier access for first movers. |
| Flat-Pack Logistics Optimization | Container density improvements reduce landed cost per unit for cross-border e-commerce. |
| Textile-to-Furniture Bundling | Coordinated seasonal refresh programs capture higher basket values than standalone sales. |
| Reverse Logistics Infrastructure | EU Green Deal take-back mandates create refurbishment revenue streams for durable goods retailers. |
| Direct-to-Consumer Platform Launch | Data-driven curation bypasses showroom capital intensity while scaling metropolitan penetration. |
Study Parameters
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in documented compliance timelines and material substitution patterns. Conversations with upholstery craftworker guild representatives, flat-pack logistics operators, hospitality procurement directors, and certified textile mill quality managers informed supply-side constraint assessments. Secondary sources encompass EPA formaldehyde emission databases, ECHA REACH restriction updates, California Air Resources Board Phase 2 certification registries, and customs trade data for panel-product flows. Bottom-up SKU-level demand modeling and top-down housing turnover projections triangulate volume estimates.
Sensitivity analysis around freight rate volatility, artisan labor pipeline contraction, and regulatory compliance timeline acceleration tests forecast robustness across the projection horizon. Segmentation dimensions span product type, material composition, end-user application, and distribution channel, with additional modeling of certification-tier splits within textile and engineered wood categories. CAGRs derive from housing formation rate projections, replacement cycle compression in subscription models, and premium-tier penetration in tier-2 Chinese urban cores.
Underlying assumptions cover sustained suburban residential demand in Texas and Florida, REACH enforcement consistency, and container pricing normalization, with deviation risk concentrated in California state-level chemical disclosure law acceleration and European upholstery craftworker pipeline collapse. Recalibration cycles align with material shifts in regulatory compliance deadlines and trans-Pacific logistics cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Mexico Home Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
Vietnam Furniture Market
Furniture
Global Multifunctional Furniture Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Europe School Furniture Market
Furniture
Wood Furniture Market
Furniture
Portering Chair Market
Furniture
Europe Outdoor Furniture Market
Furniture
US School Furniture Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
US Secondary Wood Products Market
Furniture
France Furniture Market
Furniture
Australia Smart Furniture Market
Furniture
Europe Luxury Furniture Market