
 US Sustainable Furniture Market | 2026-2036
US Sustainable Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
US Sustainable Furniture Market Analytics
Direct-to-consumer digital channels is narrowing as legacy manufacturers and digital-native brands converge on the same online audiences. Steelcase Inc. leverages its established commercial dealer network to sustain contract furniture dominance, while Floyd specializes in modular, flat-pack designs that anchor its direct-sales model. IKEA competes through global scale and circular service extensions, including buyback and resale programs that control secondary market flows.
Sustainable furniture comprises seating, surface, and storage products manufactured with certified low-emission materials, reclaimed inputs, or rapidly renewable biomass such as FSC-certified solid wood and bamboo ply, engineered to meet indoor air quality thresholds and end-of-life recyclability protocols. The material dimension shows bamboo and FSC-certified solid wood commanding premium positioning, while recycled plastic gains share in outdoor and hospitality applications where weather resistance outweighs tactile preferences. Sofas and chairs capture the largest current revenue pools, though cabinets are accelerating fastest as kitchen and bath renovation cycles align with LEED and WELL building certifications.
The EPA enforces TSCA Title VI formaldehyde standards for composite wood products, while California's CARB maintains stricter in-state benchmarks that de facto shape national sourcing decisions; OSHA indoor air quality guidelines further influence commercial specification behavior. The USDA BioPreferred program and FTC Green Guides create additional compliance layers around marketing claims and biobased content verification. Stakeholders must monitor how pending revisions to federal procurement standards under the Buy Clean Initiative could redirect specification authority toward embodied-carbon disclosure requirements.
Market Dynamics
Corporate ESG procurement mandates are restructuring buyer-seller relationships across the US sustainable furniture market, with Fortune 500 real estate teams now requiring embodied-carbon disclosure and third-party certifications as table stakes for vendor qualification.
Growth Catalysts
- EPA TSCA Title VI enforcement:Stricter formaldehyde emission testing for composite wood products is eliminating non-compliant imports and expanding domestic certified manufacturing capacity.
- LEED v4.1 and WELL v2 adoption:Commercial building certification systems are embedding furniture selection criteria directly into credit pathways, forcing specification upgrades.
- California municipal purchasing policies:Los Angeles and San Francisco procurement codes now mandate sustainable furniture for public buildings, creating guaranteed demand pools.
Market Restraints
- FSC-certified solid wood supply concentration:Pacific Northwest and Appalachian certified timber supplies face competing demand from mass timber construction, tightening input access.
- Bamboo ply technical limitations:Dimensional instability in humidity-variable climates restricts specification for high-end indoor residential applications.
- USDA BioPreferred verification friction:Biobased content testing timelines and documentation requirements delay product launches by 6-12 months.
Strategic Opportunities
- Texas and Florida commercial corridors:Underpenetrated Sun Belt markets lack established sustainable furniture dealer networks, creating first-mover positioning windows.
- Furniture-as-a-service models:Subscription and leasing structures for corporate fit-outs align circular economy goals with recurring revenue streams.
- Buy Clean Initiative procurement revisions:Pending federal embodied-carbon disclosure requirements would redirect GSA specification authority toward low-carbon domestic suppliers.
Industry Challenges
- CARB Phase 2 to EPA TSCA compliance bridging:Dual-certification complexity strains quality assurance teams and extends product development cycles.
- Secondary material traceability systems:Reclaimed wood and recycled plastic input verification requires blockchain or chain-of-custody investments that mid-tier manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sustainable Furniture Market |
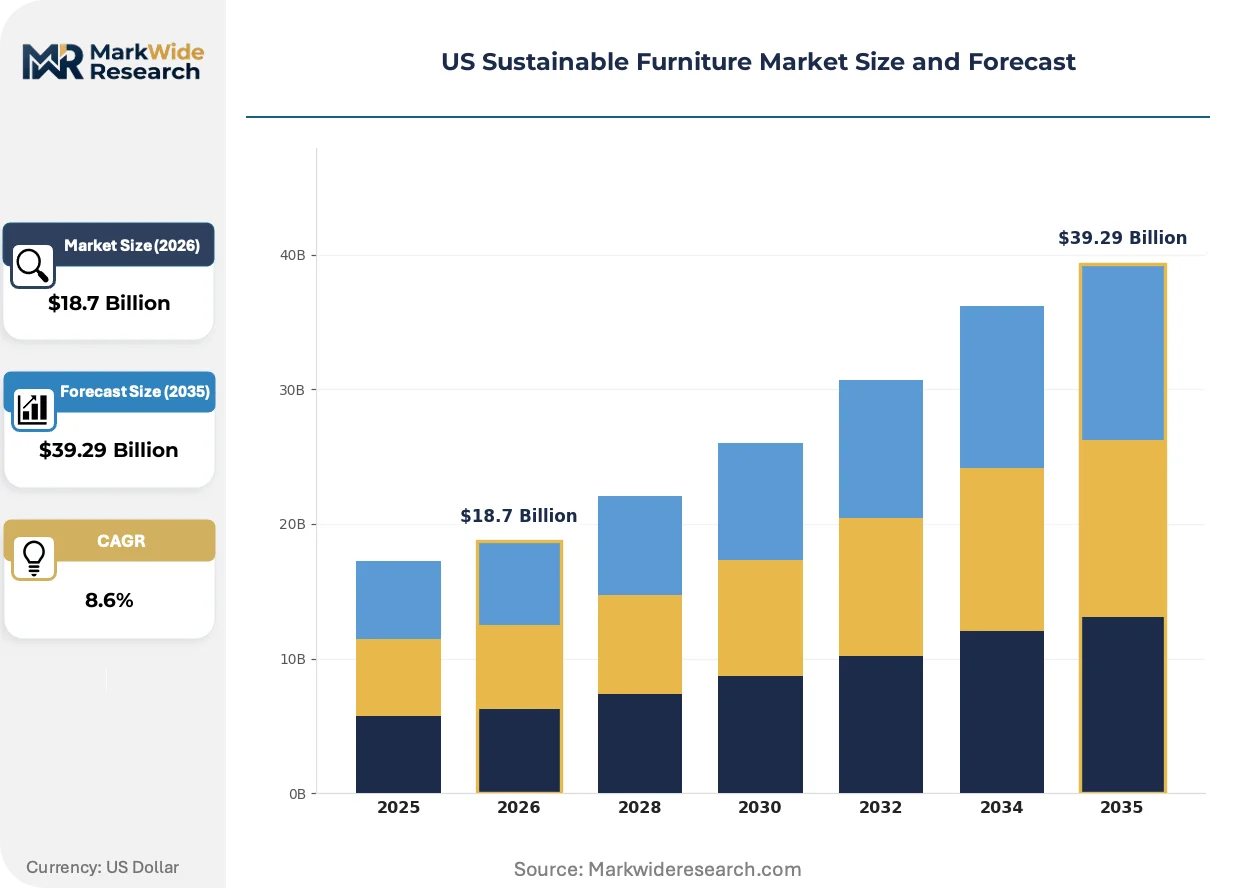
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Cabinets, Sofas Material: Bamboo, Recycled Plastic, Solid Wood, Metal End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online, Showrooms, Retail Stores, Direct Sales |
| Companies Covered | Haworth Inc., Koala, Williams Sonoma Inc., Floyd, Joybird, MillerKnoll Inc., IKEA, Sabai, Steelcase Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sustainable Furniture Market Evolving Landscape
Digital fabrication and bio-based material science are converging to compress production lead times while expanding the performance envelope of certified sustainable products beyond traditional solid wood limitations.
Structural bamboo composite technology is collapsing the performance gap between engineered grass products and hardwood alternatives. Corporate office furniture buyers are specifying bamboo ply for workstation surfaces at accelerating rates. This compression is eroding price premiums previously commanded by FSC-certified temperate hardwoods in commercial applications.
California's CARB Phase 2 certification maintains stricter in-state formaldehyde benchmarks than federal TSCA Title VI standards, de facto nationalizing its testing protocols. Furniture manufacturers serving multi-state accounts default to CARB-compliant sourcing to avoid SKU fragmentation. Upholstered seating and casegoods segments absorb the highest compliance costs, passing through testing fees via specification-grade pricing tiers.
Corporate procurement teams are consolidating vendor rosters around full-service sustainability partners capable of furnishing entire floorplates. Traditional product-category specialists lose access as integrated facility service contracts absorb furniture specification authority. This concentration is most visible in Manhattan and Chicago central business districts where landlord-controlled build-to-suit deliveries dominate new supply.
US Sustainable Furniture Market Segmentation
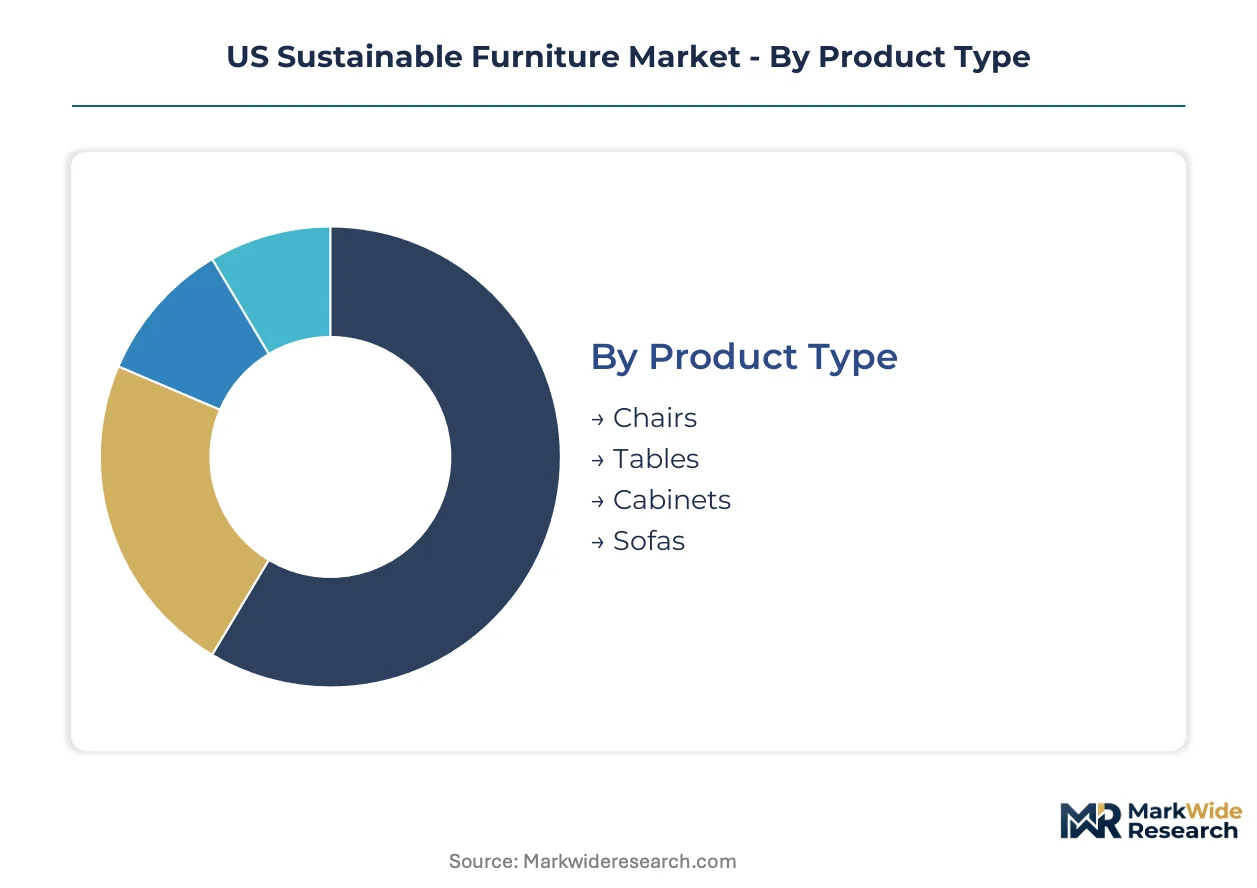
Segmentation in the US sustainable furniture market reveals how certification requirements, procurement mandates, and material performance specifications reshape competitive positioning across distinct buyer contexts and supply configurations.
Product Type:
Application-driven demand patterns separate high-frequency replacement categories from capital-intensive installations governed by building certification cycles.
- Sofas:Upholstered seating systems combine FSC-certified hardwood frames with low-VOC foam and natural fiber textiles. Corporate headquarters in Manhattan and Chicago specify these for WELL-certified lounge areas, though California's CARB Phase 2 compliance adds testing costs that concentrate sourcing among certified domestic manufacturers.
- Cabinets:Kitchen and bath storage units engineered for moisture resistance and formaldehyde emission compliance. LEED v4.1 multi-family residential projects in Los Angeles and San Francisco absorb premium-grade certified cabinetry at accelerating rates as municipal green building codes tighten.
- Chairs:Task seating dominates commercial procurement volumes with ergonomic adjustability and cradle-to-cradle material passports.
- Tables:Surface products span dining, conference, and workstation applications with modular dimension standards.
Sofas hold installed capacity. Cabinets is rotating up the share rankings.
Material:
Cost tier positioning and performance envelope characteristics determine specification authority across climate zones and end-use durability requirements.
- Solid Wood:FSC-certified temperate hardwoods from Pacific Northwest and Appalachian supply basins deliver dimensional stability and repairability. Fortune 500 corporate real estate teams specify these for executive suites and boardrooms where embodied-carbon disclosure requirements favor verified chain-of-custody documentation.
- Bamboo:Engineered grass composites processed through structural lamination achieve hardness ratings comparable to oak. Commercial workstation surface specifications in Texas and Florida commercial corridors adopt bamboo ply as FSC-certified solid wood supply tightens from competing mass timber construction demand.
- Recycled Plastic:Post-consumer HDPE and PET formulations extruded for weather resistance in exterior hospitality applications.
- Metal:Recycled content steel and aluminum framing systems with powder-coat finishes for industrial aesthetic segments.
Solid Wood holds installed capacity. Bamboo is rotating up the share rankings.
End User:
Customer type differentiation reflects procurement sophistication, budget authority, and sustainability mandate enforcement mechanisms.
- Office:Corporate facility managers and landlord-controlled build-to-suit developers consolidate vendor rosters around full-service sustainability partners. ESG procurement mandates from Fortune 500 headquarters in Manhattan and Chicago now require embodied-carbon disclosure and third-party certifications as baseline vendor qualification criteria.
- Commercial:Retail, healthcare, and educational institutions with LEED v4.1 and WELL v2 certification obligations drive specification-grade furniture volumes.
- Residential:Individual consumers purchasing through direct-to-consumer digital channels prioritize modular flat-pack designs and circular service extensions.
- Hospitality:Hotel and restaurant operators balancing aesthetic differentiation with durability requirements in high-traffic environments.
Office holds installed capacity. Commercial is rotating up the share rankings.
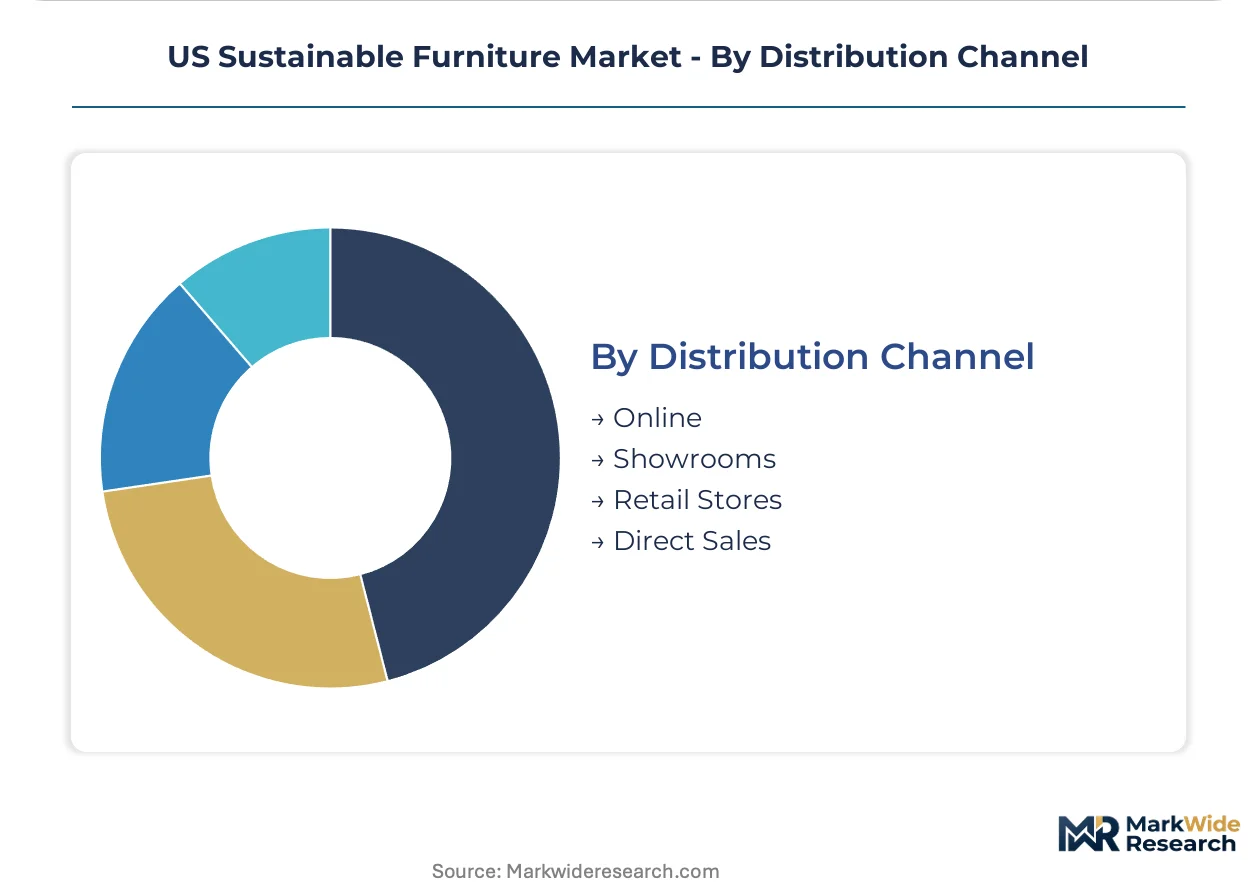
Distribution Channel:
Volume concentration and margin structure vary by channel control over specification authority and customer relationship depth.
- Direct Sales:Manufacturer-owned account executives serve corporate real estate teams with integrated floorplate furnishing and furniture-as-a-service subscription structures. This channel captures recurring revenue streams from circular economy-aligned corporate fit-outs while maintaining specification authority against dealer network intermediation.
- Online:Digital-native brands and legacy manufacturer direct-to-consumer platforms converge on modular, flat-pack product architectures with transparent material sourcing documentation.
- Showrooms:Physical specification environments where commercial buyers evaluate tactile performance and finish quality.
- Retail Stores:Big-box and specialty furniture retailers with buyback and resale program integration for secondary market control.
Direct Sales holds installed capacity. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California commands price premiums that Texas and Florida markets cannot yet replicate, creating a two-tier demand structure that rewards early certification investments in coastal metros while Sun Belt corridors compete on volume absorption.
California
Los Angeles and San Francisco metropolitan areas absorb premium-grade certified furniture through municipal green purchasing mandates and LEED v4.1 building codes. CARB Phase 2 formaldehyde standards exceed federal TSCA Title VI thresholds, de facto nationalizing California's testing protocols for multi-state suppliers. The Bay Area's corporate headquarters cluster drives WELL-certified office fit-outs that require embodied-carbon disclosure documentation.
Texas
Houston and Dallas commercial corridors present underpenetrated demand pools where sustainable furniture dealer networks remain sparse. Municipal procurement in Austin now mandates biobased content verification for public building furnishings, extending USDA BioPreferred program influence. The state's energy sector headquarters generate corporate ESG procurement mandates that redirect specification authority toward certified domestic manufacturers.
New York
Manhattan's landlord-controlled build-to-suit deliveries concentrate vendor consolidation around full-service sustainability partners capable of furnishing entire floorplates. New York City's Local Law 97 carbon emission caps intersect with commercial lease structures to prioritize low-carbon furniture specifications. Brooklyn's design-manufacturing cluster supports regional production of FSC-certified casegoods for East Coast corporate accounts.
Illinois
Chicago's central business district mirrors Manhattan's vendor consolidation patterns as integrated facility service contracts absorb furniture specification authority. The city's commercial real estate recovery drives LEED v4.1 renovation cycles that accelerate cabinet and seating replacement demand. Regional distribution hubs serving Midwest corporate accounts prioritize CARB-compliant sourcing to avoid SKU fragmentation.
Florida
Miami and Orlando hospitality corridors absorb weather-resistant recycled plastic furniture for exterior applications where durability requirements outweigh tactile preferences. State-level procurement guidelines lag California and New York, creating specification authority vacuums that direct-to-consumer brands exploit. Tampa's emerging corporate office market presents first-mover positioning windows for certified manufacturers establishing dealer networks.
US Sustainable Furniture Market Competitive Landscape
Integrated facility service providers and direct-to-consumer digital specialists split the market along specification authority lines, with commercial contract channels consolidating around full-service partners while residential volume fragments across modular flat-pack platforms. Fortune 500 vendor rosters narrow to sustainability-certified manufacturers capable of embodied-carbon disclosure. Dominant competitive moves include geographic expansion into underpenetrated Sun Belt corridors and circular service model development capturing recurring revenue from furniture-as-a-service subscriptions.
Among legacy contract furniture manufacturers, Steelcase Inc. and MillerKnoll Inc. exemplify the integrated service archetype, anchoring specification authority through established dealer networks serving corporate real estate teams. Direct-to-consumer specialists including Floyd occupy the modular flat-pack positioning, converging on online audiences with transparent material sourcing documentation. IKEA represents global scale-driven competition through circular service extensions controlling secondary market flows.
| Leading Market Players |
|---|
| Haworth Inc. |
| Koala |
| Williams Sonoma Inc. |
| Floyd |
| Joybird |
| MillerKnoll Inc. |
| IKEA |
| Sabai |
| Steelcase Inc. |
| Others |
Value Network & Pricing Analysis
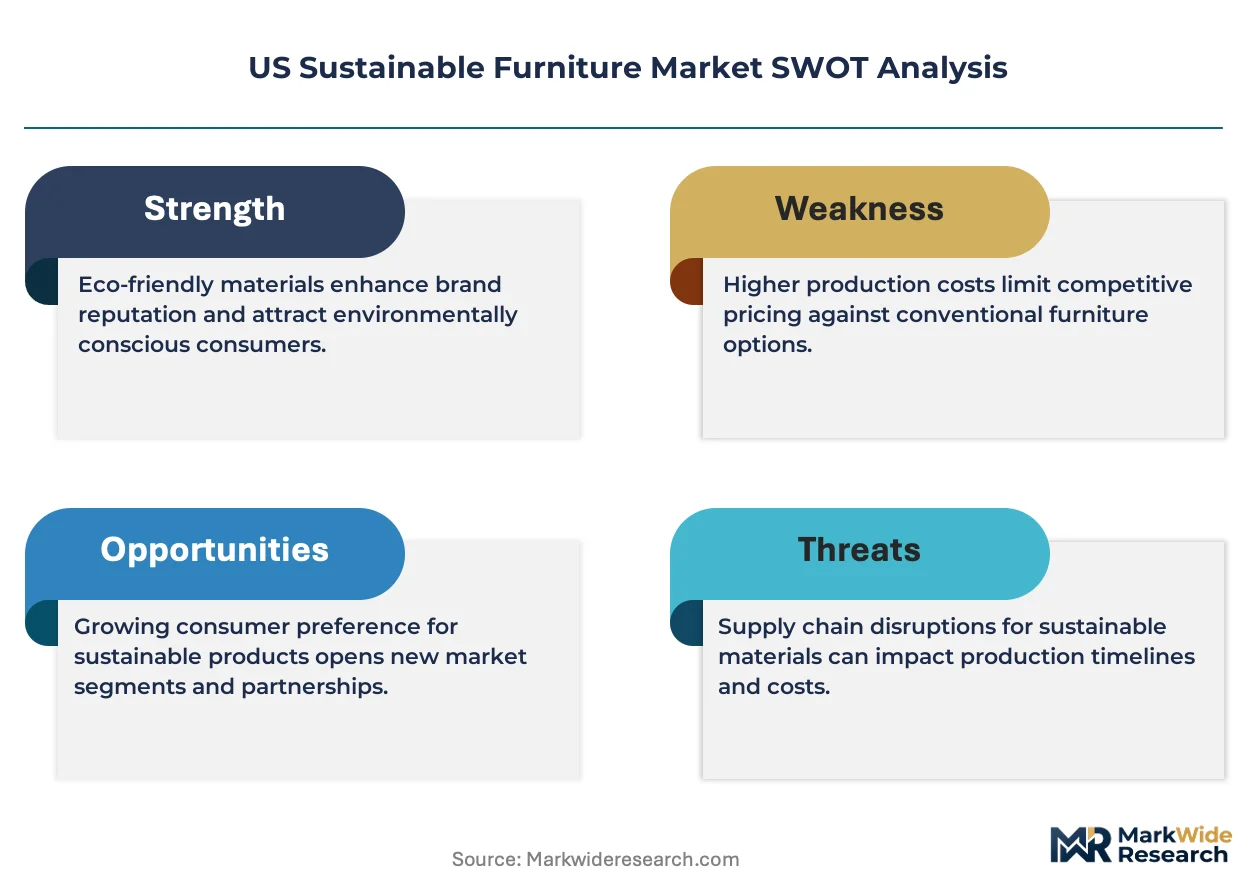
Tariff exposure between Southeast Asian composite wood suppliers and US finished goods manufacturers compresses margin structures across both pricing tier spreads and supply chain configuration. EPA TSCA Title VI compliance costs concentrate among upholstered seating and casegoods segments, forcing domestic manufacturers to absorb testing fees or pass them through specification-grade pricing tiers while reshaping sourcing decisions toward CARB-certified domestic mills.
Pricing Analysis
The customization-premium spread separates configured-to-order corporate workstation systems from standard flat-pack residential offerings by three-to-one multiples. Pricing stratifies across premium, standard, and economy tiers with certification grade and volume scale as primary differentiation drivers. Cost compression in the standard tier intensifies as direct-to-consumer brands converge on modular designs. Corporate real estate teams show lowest price sensitivity due to ESG procurement mandate enforcement, while residential consumers exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between Vietnam and China dominates supply chain risk assessment for US sustainable furniture manufacturers. Pacific Northwest and Appalachian timber basins anchor domestic FSC-certified solid wood supply, while bamboo ply feeds from engineered grass processing facilities in China and Vietnam. Single-source vulnerability concentrates in low-emission adhesive formulations and specialized textile finishing. Distribution runs through commercial dealer networks for contract furniture and direct-to-consumer platforms for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US sustainable furniture market represents early-cycle expansion as corporate ESG procurement mandates penetrate beyond Fortune 500 headquarters into mid-market real estate portfolios. Federal Buy Clean Initiative revisions signal accelerating specification authority shifts toward embodied-carbon disclosure requirements.
For Market Incumbents: Entrench specification authority through furniture-as-a-service subscription structures that capture recurring revenue from circular economy-aligned corporate fit-outs. Deepen backward integration into FSC-certified timber basins as competing mass timber construction tightens input access. Prioritize CARB Phase 2 to EPA TSCA dual-certification investments to defend against import substitution threats from Southeast Asian manufacturers.
For New Entrants and Emerging Players: Build out dealer networks in Houston and Dallas commercial corridors where sustainable furniture distribution remains sparse and first-mover positioning windows persist. Target Austin municipal procurement contracts leveraging USDA BioPreferred program verification as a qualification wedge. Deploy transparent material sourcing documentation through digital channels to capture residential consumers migrating from legacy retail.
For Investors and Strategic Acquirers: Pending Buy Clean Initiative procurement revisions reshape the acquisition landscape toward domestic manufacturers with embodied-carbon disclosure capabilities. Long-term viability favors integrated facility service providers capable of furnishing entire floorplates over product-category specialists. Monitor GSA specification authority shifts as the primary inflection signal for portfolio reallocation toward low-carbon domestic suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Timber | Captive FSC supply from Pacific Northwest basins secures input access against mass timber competition. |
| Furniture-as-a-Service Launch | Subscription structures align circular economy goals with recurring revenue from corporate fit-outs. |
| Dual-Certification Investment | CARB Phase 2 and EPA TSCA compliance eliminates SKU fragmentation for multi-state accounts. |
| Dealer Network Expansion | First-mover positioning in Houston and Dallas corridors captures underpenetrated Sun Belt demand. |
| Embodied-Carbon Disclosure Platform | Third-party verification systems meet Fortune 500 ESG procurement mandate requirements. |
Research Methodology
Cross-validation between primary interviews with corporate real estate directors and secondary validation through EPA enforcement records anchors the qualitative findings. Conversations with facility managers at Fortune 500 headquarters, commercial furniture dealers, FSC-certified mill operators, and municipal procurement officers in Los Angeles and San Francisco combined with CARB certification databases, USGBC LEED project directories, and GSA procurement disclosures. Bottom-up segment sizing and top-down market reconciliation triangulate volume estimates.
Calibration against historical adoption curves for building certification systems and procurement mandate diffusion patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material certification tier, end-user procurement sophistication, and distribution channel control. CAGRs derived from regression analysis of certification penetration rates and replacement cycle timing. Industry-specific inputs encompass formaldehyde testing cost trajectories and mass timber construction demand forecasts.
Stress conditions across tariff rate volatility, FSC supply availability, and federal procurement timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around ESG mandate enforcement velocity and certification cost pass-through elasticity. Material shifts in Buy Clean Initiative implementation scope or CARB Phase 2 federal preemption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Brazil Furniture Market
Furniture
US School Furniture Market
Furniture
Sanded Plywood Market
Furniture
Asia-Pacific Contract Furniture Market
Furniture
North America RTA Furniture Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Fireplace Mantels Market
Furniture
Contract Furniture and Furnishing Market
Furniture
GCC Furniture Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Europe Sustainable Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
Children Furniture Market
Furniture
Europe Luxury Furniture Market
Furniture
Armchair on Casters Market
Furniture
Armchairs with Footrest Market